
 Feed Mycotoxin Binders Market | 2026-2036
Feed Mycotoxin Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Mycotoxin Binders Market Analysis
Market Context
Brazil is reconfiguring feed additive supply chains as domestic grain handling expands and export-oriented protein producers face stricter importer mycotoxin limits. Cargill Incorporated leverages its integrated grain-merchandising and nutrition platforms to anchor binder distribution across South American feed mills. BASF SE sustains technology leadership through precision-modified clay chemistry that targets fumonisin and zearalenone co-contamination. Olmix Group differentiates via marine-sulfated polysaccharide technology that competes with conventional aluminosilicates in ruminant applications.
Technical Definition and Segment Structure
Feed mycotoxin binders are feed-grade adsorbent materials, primarily aluminosilicate clays, yeast cell wall derivatives, or activated carbon formulations, engineered to sequester fungal metabolites in the gastrointestinal tract and prevent systemic absorption in food-producing animals. These additives function through ion exchange, surface adsorption, and hydrogen bonding at pH conditions typical of monogastric and ruminant digestive systems, with binding capacity measured against aflatoxin B1, deoxynivalenol, and T-2 toxin standards. Clay-based products occupy the largest volume share due to cost positioning and established efficacy data, while organic binders derived from Saccharomyces cerevisiae cell walls represent the fastest-expanding category as producers seek selective binding without mineral nutrient interference. Powder formulations dominate manufacturing throughput, though liquid applications are gaining share in automated dosing systems for large-scale poultry and swine operations.
Regulatory Framework and Outlook
EFSA, the EU's F-Gas Regulation indirect pressure on feed storage climate control, and Brazil's Ministry of Agriculture (MAPA) feed inspection protocols collectively shape product registration pathways and residue monitoring obligations across major protein-exporting jurisdictions. FDA guidance on blending contaminated grain and EU feed hygiene regulation (EC) 183/2005 enforce binding agent documentation and efficacy validation, tightening market access for unverified suppliers. Stakeholders must monitor evolving multi-mycotoxin maximum levels and climate-driven contamination geography shifts to align R&D portfolios with emerging regulatory stringency.
Market Dynamics
Climate volatility across major grain belts is forcing feed compounders to rebuild mycotoxin risk management protocols from reactive testing toward preventive binding systems integrated at the mill level.
Growth Catalysts
- EFSA Multi-Mycotoxin Guidance:The EU's tightened maximum levels for aflatoxins in feedstuffs under EFSA guidance are accelerating reformulation toward multi-mycotoxin binding systems across European compound feed operations.
- Brazilian Integrator Expansion:Large-scale swine and broiler integrators across Brazil's southern grain belt face rising feed safety compliance costs and are deepening binder adoption to secure export market access.
- Yeast Cell Wall Technology:Saccharomyces cerevisiae-derived binders are gaining traction as producers seek selective mycotoxin binding without the mineral nutrient interference associated with aluminosilicate clays.
Market Restraints
- Aluminosilicate Cost Volatility:Bentonite and montmorillonite feedstock prices fluctuate with energy-intensive mining and processing costs in concentrated extraction regions.
- Binding Selectivity Limitations:Clay-based products demonstrate variable efficacy against trichothecenes and fumonisins, creating performance gaps that limit universal application.
- Regulatory Documentation Burden:FDA guidance on blending contaminated grain and EU feed hygiene regulation (EC) 183/2005 enforce extensive efficacy validation requirements that raise barriers for unverified suppliers.
Strategic Opportunities
- Automated Liquid Dosing Systems:Large-scale poultry and swine operations are adopting liquid binder applications for precision dosing, opening channel expansion beyond traditional powder distribution.
- Ruminant Segment Penetration:Marine-sulfated polysaccharide technology is competing with conventional aluminosilicates in dairy and beef cattle applications where rumen pH dynamics create distinct binding requirements.
- Climate-Driven Geography Shifts:Mold contamination patterns are extending into northern European and North American grain belts previously considered low-risk, generating first-time binder demand in underpenetrated feed markets.
Industry Challenges
- Multi-Toxin Analytical Capability Gap:Feed mills lack in-house LC-MS/MS capacity for simultaneous detection of regulated mycotoxin classes, creating dependency on third-party testing and delaying binder optimization decisions.
- Species-Specific Formulation Complexity:Differential gastrointestinal pH and transit times across monogastric and ruminant species force manufacturers to maintain parallel product development pipelines rather than universal solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Mycotoxin Binders Market |
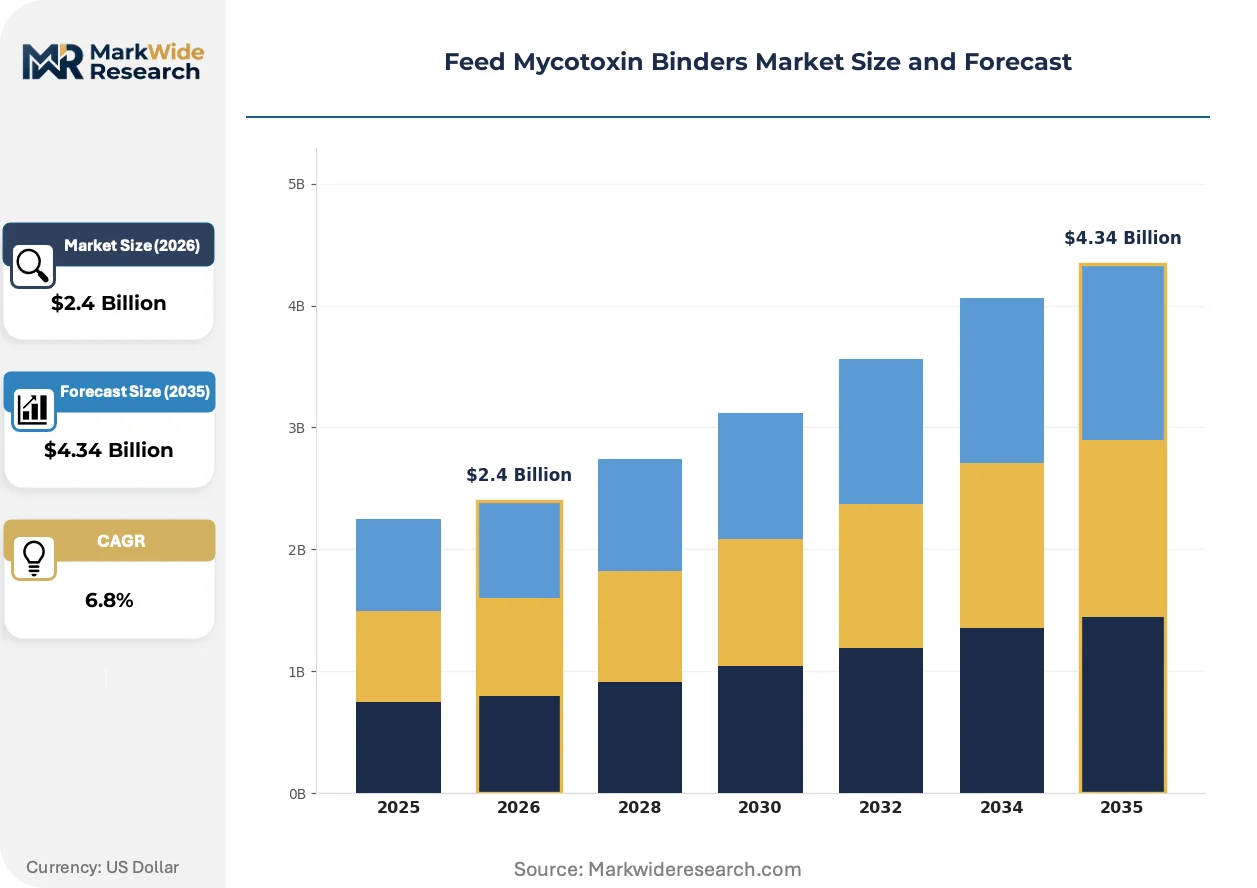
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay-based, Organic, Activated Carbon, Silicate Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granule, Pellet Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Cargill Incorporated, Kemin Industries, Inc, BASF SE, Olmix Group, ADM, Alltech Inc., Novus International Inc., Impextraco N.V., BIOMIN Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Mycotoxin Binders Market Emerging Trajectories
Feed mycotoxin binder technology is converging with precision nutrition platforms as compounders demand real-time contamination response capabilities rather than static additive inclusion rates.
Modified clay chemistry is hybridizing with enzymatic biotransformation approaches to address co-contamination scenarios where adsorption alone proves insufficient. Poultry integrators in Southeast Asia are piloting these dual-mechanism systems at commercial scale. The technology is hybridizing conventional mineral binder supply chains with biotechnology partnerships that reshape competitive capability requirements.
The EU F-Gas Regulation is indirectly pressuring feed storage climate control investments by raising refrigeration and ventilation equipment costs. This accelerates interest in preventive mycotoxin management through binding agents rather than post-harvest storage conditioning. Compound feed manufacturers in Germany and the Netherlands are prioritizing multi-mycotoxin binders that reduce dependency on climate-controlled silo infrastructure.
Buyer concentration among integrated protein producers is compressing supplier negotiation cycles and unbundling technical service from product procurement. Large Brazilian and Thai integrators now separate binder sourcing decisions from on-farm application support, forcing additive manufacturers to compete on validated efficacy data rather than relationship-based distribution. This pattern is most visible in Southeast Asian poultry markets where vertical integration has concentrated purchasing power among fewer than ten dominant integrators.
Feed Mycotoxin Binders Market Segmentation
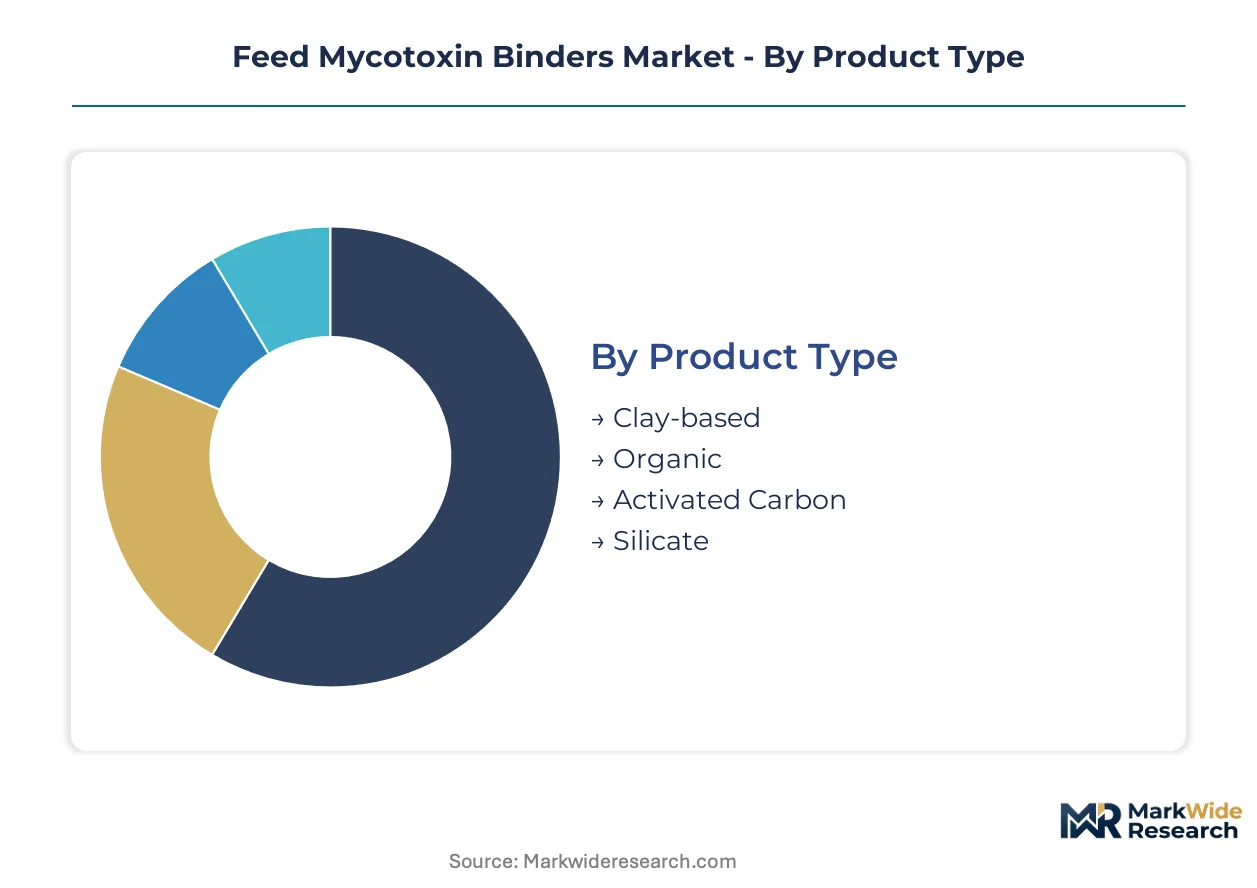
Mycotoxin binder procurement cycles vary dramatically across product categories, with clay-based formulations turning over rapidly due to commodity pricing while organic binders command longer evaluation periods. Understanding these velocity differentials helps suppliers align inventory and technical service investments with actual customer decision timelines.
Product Type:
Clay-based products refresh inventory quarterly at most feed mills, whereas organic binders face 12-18 month validation cycles before specification changes.
- Clay-based:Bentonite and montmorillonite formulations constitute the volume foundation, priced for continuous inclusion in standard compound feeds. Brazilian integrators specify these for baseline aflatoxin control across southern grain belt operations where fumonisin co-contamination pressures binding capacity.
- Organic:Saccharomyces cerevisiae cell wall derivatives command premium positioning through selective adsorption that preserves mineral bioavailability. German and Dutch compounders specify these when EFSA multi-mycotoxin guidance demands simultaneous deoxynivalenol and zearalenone management without nutrient interference.
- Activated Carbon:High-surface-area carbon blacks target acute contamination events and pharmaceutical residue scenarios in specialized feed applications.
- Silicate:Synthetic aluminosilicates offer engineered pore structures for targeted toxin geometries in precision nutrition formulations.
Clay-based products dominate installed base. Organic binders are where expansion concentrates.
Application:
Species-specific gastrointestinal physiology creates distinct performance specifications that fragment manufacturing requirements.
- Poultry:Rapid transit times in avian digestive systems demand high-affinity binding at acidic pH, driving specification of modified clay chemistries in automated dosing systems. Thai and Brazilian broiler integrators prioritize liquid applications for precision inclusion in high-volume operations.
- Swine:Monogastric sensitivity to deoxynivalenol and zearalenone necessitates multi-toxin formulations, with EU compounders reformulating under tightened EFSA maximum levels for breeding herd protection.
- Ruminants:Rumen pH dynamics and microbial fermentation create unique binding requirements where marine-sulfated polysaccharides compete with conventional aluminosilicates in dairy applications.
- Aquaculture:Water stability and palatability constraints in shrimp and fish feeds limit applicable technologies to specialized coated formulations.
Poultry maintains the largest active specification base. Ruminant applications are climbing the fastest as dairy producers face emerging mycotoxin pressure.
Form:
Manufacturing infrastructure investments determine form adoption patterns, with powder handling systems already depreciated at legacy mills.
- Liquid:Automated dosing compatibility drives adoption at greenfield poultry and swine facilities with integrated nutrition platforms, particularly in Southeast Asian operations seeking precision inclusion rates.
- Powder:Established bulk handling infrastructure at conventional feed mills sustains volume leadership despite dust control and homogeneity challenges.
- Granule:Intermediate flow properties suit smaller compounders without liquid dosing capability or pneumatic powder systems.
- Pellet:Pre-formed inclusion in feed pellets addresses specialty premix applications and export logistics where segregation resistance matters.
Powder forms anchor current manufacturing throughput. Liquid applications are gaining share fastest in new facility investments.
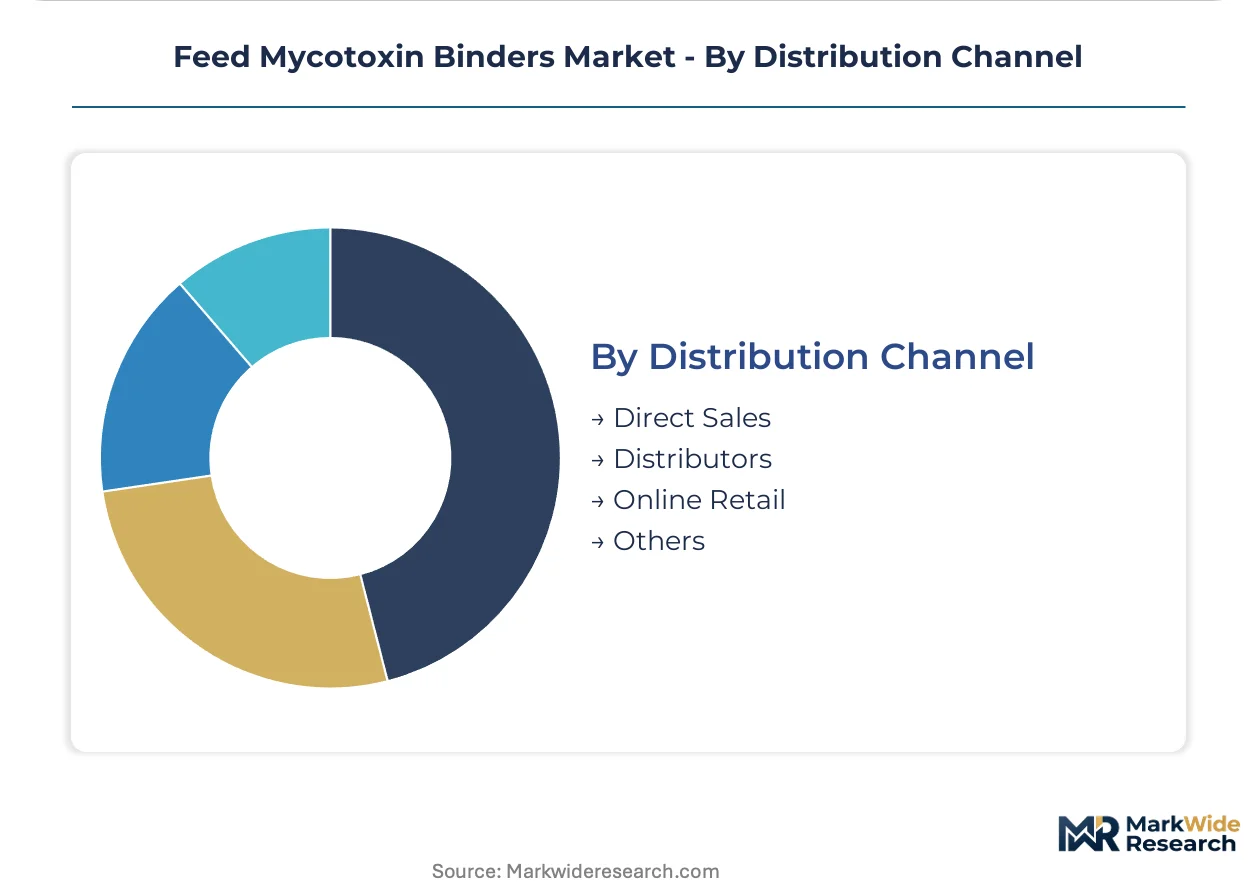
Distribution Channel:
Customer scale and technical service requirements split procurement pathways between direct and intermediated relationships.
- Direct Sales:Integrated protein producers with centralized purchasing consolidate volume through manufacturer relationships, separating product procurement from application support in Brazilian and Thai markets.
- Distributors:Regional feed additive specialists maintain inventory and technical service for mid-tier compounders lacking in-house mycotoxin management expertise.
- Online Retail:Digital platforms serve small livestock operations and specialty feed producers with standardized product grades and rapid fulfillment.
- Others:Cooperative purchasing arrangements and integrated grain-merchandising channels capture residual volume in concentrated agricultural regions.
Distributor relationships dominate transaction volume. Direct sales are where margin expansion concentrates as buyer consolidation progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos grain terminal anchors Brazil's mycotoxin binder distribution infrastructure, channeling South American feed additives into Atlantic shipping lanes serving European and Asian protein markets.
Brazil
Integrated swine and broiler operations across Paraná and Santa Catarina states drive binder procurement as MAPA inspection protocols tighten feed safety documentation. The southern grain belt's humid subtropical climate intensifies aflatoxin and fumonisin pressure in corn and soybean meal. São Paulo-based feed compounders are consolidating purchasing power through cooperative arrangements that bypass traditional distributor markups.
United States
Midwest corn belt ethanol byproducts and DDGS streams concentrate mycotoxin loads in monogastric feed rations. FDA guidance on blending contaminated grain forces compounders toward preventive binding systems rather than post-harvest diversion. Iowa and Illinois feed mills are retrofitting liquid dosing infrastructure to serve large-scale sow operations facing deoxynivalenol pressure from Fusarium-infected harvests.
Germany
EFSA multi-mycotoxin maximum levels and the F-Gas Regulation's climate control cost pressures are accelerating binder adoption in compound feed operations. Lower Saxony's dense dairy corridor generates demand for ruminant-specific formulations that address rumen pH dynamics. Bavarian feed manufacturers are prioritizing yeast cell wall derivatives to meet tightened zearalenone limits for breeding herd protection.
Thailand
Vertical integration among Bangkok-headquartered poultry integrators concentrates purchasing decisions among fewer than ten dominant buyers. The Eastern Economic Corridor's automated feed mills favor liquid binder applications for precision inclusion in high-volume broiler operations. Thai compounders face simultaneous EU and Japanese importer mycotoxin limits that exceed domestic regulatory thresholds.
Netherlands
Randstad logistics hubs distribute multi-mycotoxin binding systems across northwest European compound feed networks. Dutch feed hygiene regulation enforcement under EC 183/2005 mandates documented efficacy validation that raises barriers for unverified suppliers. Gelderland and Overijssel dairy cooperatives are piloting marine-sulfated polysaccharide alternatives to conventional aluminosilicates in precision nutrition formulations.
Feed Mycotoxin Binders Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying differentiated chemistries to integrated nutrition platforms. The market structure consolidates around grain-merchandising conglomerates with captive feed additive distribution and independent technology developers with proprietary binding mechanisms. Three archetypes dominate: integrated agribusiness platforms with multi-regional coverage, precision-modified clay chemistry specialists, and marine-biotechnology innovators with ruminant-focused portfolios. Competitive dynamics center on backward integration into mineral feedstock security and technology licensing partnerships that extend geographic reach without capital-intensive manufacturing replication.
Among integrated agribusiness platforms, Cargill Incorporated and ADM exemplify the grain-merchandising archetype that anchors binder distribution across South American and North American feed mill networks. BASF SE occupies a position within the precision-chemistry tier, representing modified aluminosilicate technology development. Olmix Group sits within the marine-biotechnology specialization vector, anchoring sulfated polysaccharide alternatives to conventional clay binders. These three company types collectively span the competitive spectrum from commodity-scale mineral sourcing to differentiated organic formulations.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kemin Industries, Inc |
| BASF SE |
| Olmix Group |
| ADM |
| Alltech Inc. |
| Novus International Inc. |
| Impextraco N.V. |
| BIOMIN Holding GmbH |
| Others |
Supply Flow & Price Mechanics
Commodity bentonite price volatility in concentrated mining regions determines both the spread between economy clay formulations and premium yeast-cell-wall derivatives and the backward-integration incentives shaping supplier consolidation across Brazilian and German feed additive markets.
Pricing Analysis
Volume-discount tiering structures separate large integrator direct contracts from distributor-mediated small-compounder purchases. Pricing stratifies across premium organic binders certified for EFSA multi-mycotoxin compliance, standard modified-clay formulations for baseline aflatoxin control, and economy bentonite grades for cost-sensitive Brazilian operations. Cost compression in the clay-based tier is intensifying because energy-intensive mining and processing expenses fluctuate with regional fuel costs. Small livestock operations purchasing through online retail channels exhibit highest price sensitivity, while Thai and Brazilian integrators negotiating direct manufacturer relationships prioritize validated efficacy documentation over unit cost.
Supply Chain Analysis
Extended payment terms from integrated protein producers are forcing raw material suppliers to access supply-chain finance facilities, restructuring working capital dynamics across the value chain. Feedstock extraction concentrates in the United States, Brazil, and China for bentonite and montmorillonite clays, while marine-sulfated polysaccharide precursors draw from coastal processing facilities in France and Norway. Single-source vulnerability in specialized yeast cell wall derivatives rests on concentrated fermentation capacity in Germany and the Netherlands. Distribution runs through grain-merchandising conglomerates with captive feed additive platforms, particularly Cargill's integrated South American networks, alongside regional distributor specialists serving mid-tier compounders lacking in-house mycotoxin management expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where technical application support and real-time contamination monitoring subscriptions expand faster than commodity binder volumes, particularly as Brazilian and Thai integrators unbundle product procurement from on-farm advisory.
For Market Incumbents: Pre-empt displacement by marine-biotechnology innovators through captive supply of precision-modified clay feedstocks in the southern United States and Paraná state. Backward integration into bentonite mining secures margin control against commodity volatility, while multi-mycotoxin binding capacity investments defend specification position against yeast-cell-wall substitutes gaining share under tightened EFSA guidance. For New Entrants and Emerging Players: Pursue white-space penetration in automated liquid dosing systems for greenfield Southeast Asian poultry facilities, where precision inclusion capabilities outpace established powder distribution infrastructure. Northern European dairy cooperatives piloting ruminant-specific marine-polysaccharide alternatives represent the most penetrable application segment, accessible through technical partnerships with precision-nutrition platform integrators rather than direct mill sales. For Investors and Strategic Acquirers: EFSA multi-mycotoxin maximum level revisions reshape the acquisition landscape toward yeast-cell-wall technology developers with documented deoxynivalenol and zearalenone binding validation. Long-term viability across the projection horizon favors targets combining organic binder intellectual property with existing distribution relationships in Brazil's southern grain belt. Monitor MAPA feed inspection protocol enforcement intensity as the signal indicating regulatory-driven specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clay Feedstock Mining | Captures margin compression from energy-intensive bentonite processing in concentrated extraction regions. |
| Multi-Mycotoxin Binding Certification Investment | Secures specification priority under tightened EFSA maximum levels for aflatoxin, deoxynivalenol, and zearalenone co-contamination. |
| Automated Liquid Dosing System Partnership | Aligns with Thai and Brazilian integrator infrastructure investments for precision inclusion in high-volume broiler operations. |
| Marine-Polysaccharide Ruminant Formulation Development | Addresses dairy cooperative demand for alternatives to aluminosilicates under rumen pH dynamics in Lower Saxony and Gelderland. |
| Technical Service Unbundling and Digital Platform Launch | Responds to buyer concentration separating binder sourcing from application support among Southeast Asian poultry integrators. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with feed mill procurement directors, technical nutritionists at integrated poultry and swine operations, regulatory affairs specialists navigating EFSA and FDA guidance, and distribution channel managers across Brazilian and European markets. Secondary validation drew from EU feed hygiene regulation documentation, MAPA inspection protocol filings, SEC disclosures by grain-merchandising conglomerates, and customs data tracking bentonite and yeast derivative trade flows. Bottom-up volume estimates from species-specific application rates triangulated against top-down market sizing from compound feed production statistics.
Calibration against historical adoption curves for organic binders and modified clay chemistries anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application species, formulation form, and distribution channel structure, with regional regulatory cluster intensity serving as an additional industry-specific dimension. CAGRs were derived from elasticity-adjusted penetration rate projections, incorporating climate-driven contamination geography shifts and integrator consolidation patterns as feedstock demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by marine-biotechnology specialists or accelerated FDA enforcement of blending guidance would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market