
 Global Agricultural Enzymes Market | 2026-2036
Global Agricultural Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Enzymes Market Foresight
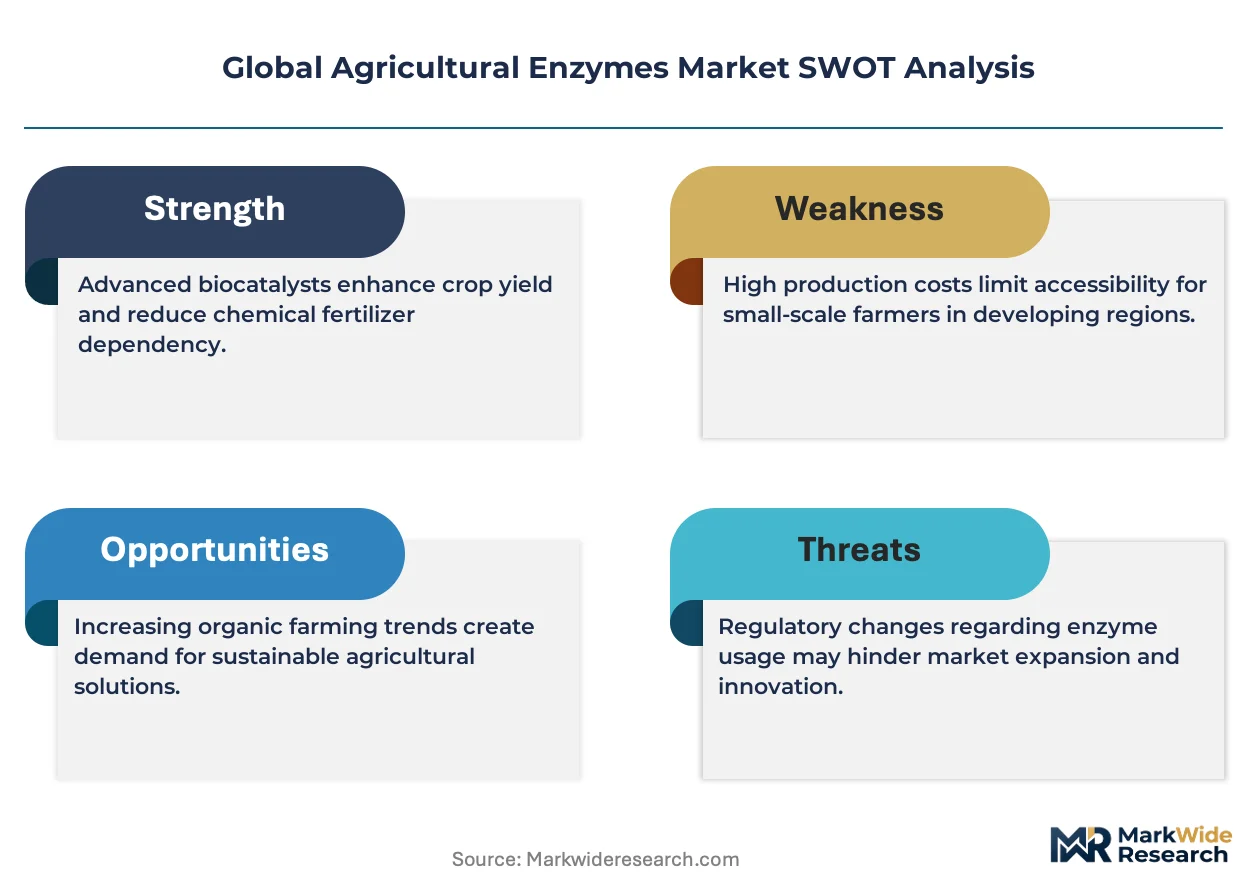
The capital-intensity divergence between precision fermentation specialists and commodity chemical incumbents is unwinding competitive stability across the sector. BASF SE leverages its integrated agrochemical distribution to push enzyme-fertilizer bundled offerings into European cooperatives. Novonesis Group anchors its position through microbial strain libraries optimized for tropical soil conditions. Syngenta AG competes by embedding enzymes within broader biologicals portfolios sold to large-scale greenhouse operators.
Agricultural enzymes are protein-based biocatalysts, typically operating at pH ranges between 4.0 and 8.0 and temperatures of 25°C to 55°C, that accelerate biochemical reactions in soil and plant systems without altering equilibrium constants; manufacturers produce them via submerged fermentation of fungal or bacterial hosts, followed by downstream purification and stabilization in liquid or granule matrices. Cellulase dominates product type volumes due to its role in degrading crop residue for nutrient release, while pectinase commands premium positioning among horticulture firms processing high-value fruit crops. Application demand tilts toward soil treatment and fertilizer supplementation as growers face mounting pressure to reduce synthetic nitrogen runoff.
The EPA regulates agricultural enzyme products under FIFRA as biological pesticides or plant regulators, creating registration pathways that favor companies with multi-year toxicology datasets; REACH compliance in Europe mandates full substance dossiers for enzyme active ingredients, raising barriers for new entrants lacking ECHA-ready toxicological profiles. India's Central Insecticides Board under the Ministry of Agriculture requires biopesticide registration that increasingly covers microbial enzymes, shaping how exporters structure India-market entry. Stakeholders must monitor how divergent national biologicals frameworks reshape product registration timelines and capital allocation across R&D pipelines.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is systematically compressing synthetic chemical allowances, forcing enzyme manufacturers to accelerate biological proof-of-concept timelines for European cooperatives.
Growth Catalysts
- REACH compliance pathways:ECHA's streamlined biopesticide dossier processes reward early-movers with multi-year data libraries, accelerating market access for established enzyme portfolios.
- Contract farming consolidation:India's cooperative belt is standardizing biological input protocols, creating captive demand clusters for residue-free yield enhancement products.
- Tropical soil optimization:Microbial strain libraries engineered for high-temperature, acidic pH conditions unlock enzyme stability in Brazil's specialty crop regions.
Market Restraints
- Fermentation input volatility:Molasses and corn steep liquor prices fluctuate with ethanol policy shifts, compressing margin predictability for submerged production runs.
- Downstream purification bottlenecks:Chromatography resin supply concentrates among three specialty chemical suppliers, creating single-source vulnerability for high-purity enzyme grades.
- Storage stability thresholds:Liquid formulations degrade above 35°C, limiting distribution reach into equatorial zones lacking cold-chain infrastructure.
Strategic Opportunities
- Greenhouse biological integration:Controlled-environment agriculture operators seek enzyme-microbe synergies for closed-loop nutrient cycling, opening premium positioning.
- Carbon credit monetization:Soil carbon sequestration protocols under voluntary offset markets reward enzymatic residue decomposition as measurable CO2 reduction.
- Drone-based foliar application:Ultrasonic atomization nozzles compatible with high-viscosity enzyme suspensions enable precision delivery to orchard canopies.
Industry Challenges
- Strain development timelines:CRISPR-edited microbial hosts face 18-24 month stability validation cycles before commercial fermentation scale-up.
- FIFRA registration synchronization:EPA toxicology requirements diverge from OECD harmonized protocols, forcing redundant mammalian studies for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Enzymes Market |
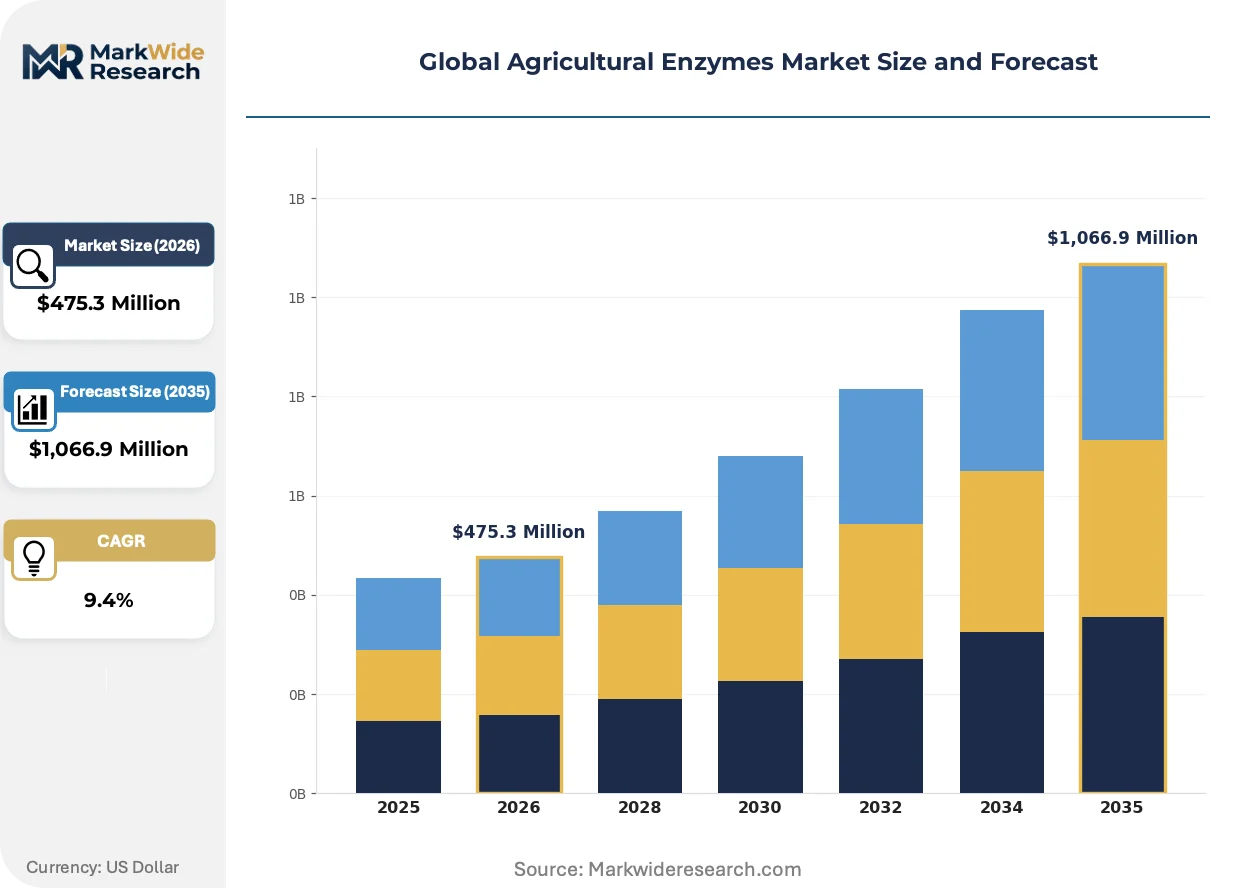
| Market Size in 2026 | $475.3 Million |
| Market Size in 2035 | $1,066.9 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Cellulase, Protease, Pectinase, Xylanase, Lipase Application: Soil Treatment, Crop Conditioning, Pest Management, Fertilizer Supplementation, Seed Germination, Nutrient Recycling End User: Contract Farming, Agricultural Cooperatives, Organic Farms, Horticulture Firms, Agrochemical Companies, Greenhouse Operators Form: Liquid, Powder, Granules, Tablets, Capsules |
| Companies Covered | BioWorks Inc., BASF SE, Novonesis Group, Stoller USA Inc., AB Enzymes, Elemental Enzymes, Syngenta AG, Enzyme Solutions Inc., Infinita Biotech Pvt. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Enzymes Market Shifts & Advancements
Enzyme stabilization chemistry and delivery mechanism engineering are converging to extend field efficacy windows, reshaping how manufacturers compete on performance guarantees rather than unit pricing.
Cellulase-pectinase enzyme cocktails formulated for simultaneous residue breakdown and fruit softening are fragmenting the traditional sequential-application model in Brazilian citrus processing. Mid-scale juice cooperatives are piloting these dual-function blends to compress harvest-to-processing timelines. The consolidation of enzyme functionality is compressing supplier margins on single-activity products while rewarding integrated formulation capabilities.
REACH's 2023 update to substance dossier requirements for protein-based actives is tightening toxicological data standards for enzyme imports into European fertilizer blends. Manufacturers must now submit extended aquatic toxicity profiles for downstream metabolites. Specialty crop formulators in Spain and Italy are restructuring supply contracts to transfer registration liability upstream to strain developers.
Cooperative procurement officers in India's Maharashtra and Gujarat states are consolidating annual enzyme tenders into multi-year framework agreements with fixed-volume escalators. This concentration of buying power is displacing spot-market transactions and favoring suppliers with captive fermentation capacity. The shift is most visible in paddy and sugarcane contract farming clusters where yield-guarantee clauses now specify enzyme-inclusive nutrient protocols.
Global Agricultural Enzymes Market Segmentation
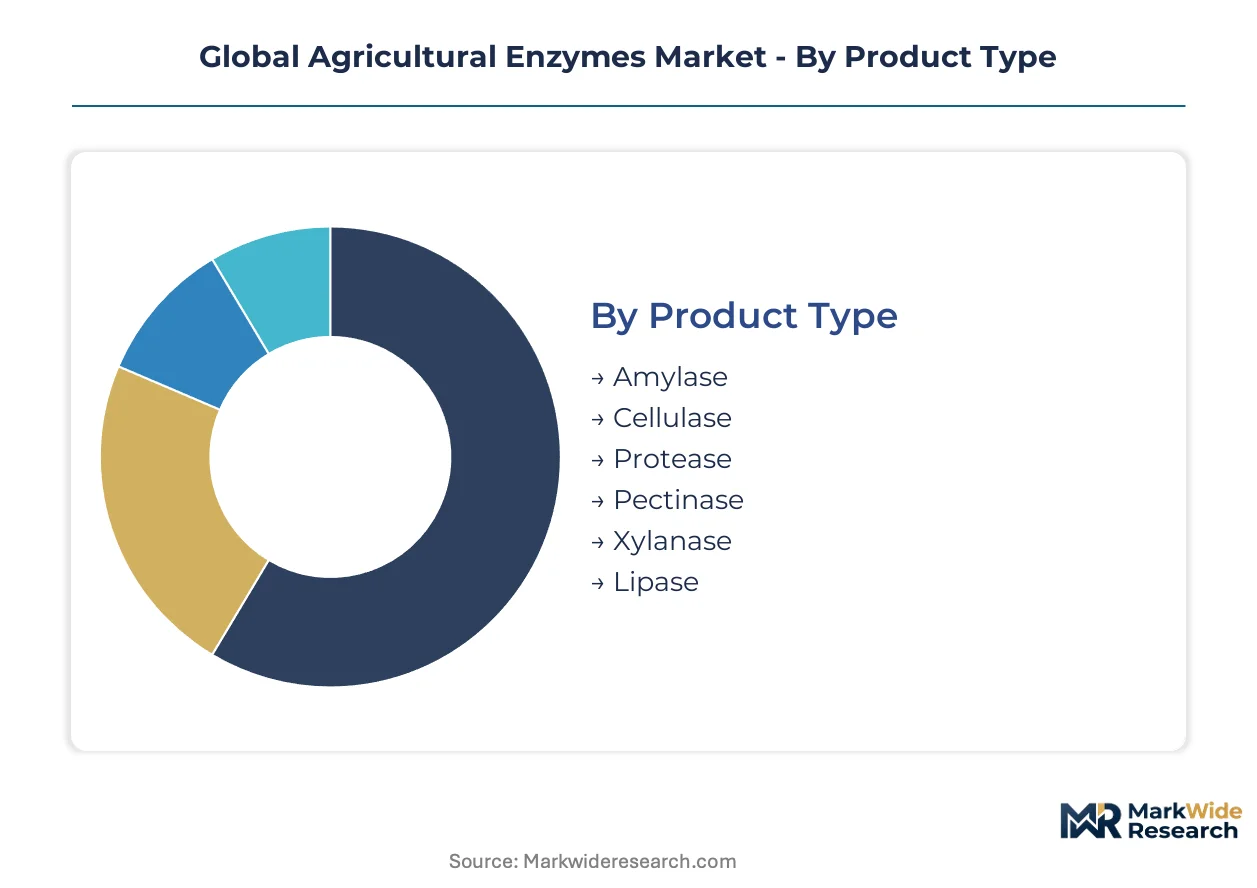
Enzyme manufacturers structure their commercial portfolios around four intersecting dimensions that determine formulation priorities, distribution channel selection, and pricing architecture. Each segmentation axis reveals distinct margin profiles and customer concentration patterns that shape competitive positioning.
Product Type:
Channel mix varies sharply by enzyme class: cellulase and pectinase flow predominantly through horticulture distributors and juice processing cooperatives, while amylase and protease concentrate in bulk fertilizer blending networks serving broad-acre row crops.
- Cellulase:This enzyme hydrolyzes β-1,4-glycosidic bonds in cellulose to release fermentable sugars and soil organic matter. Demand concentrates in Brazil's sugarcane belt and India's paddy regions where residue incorporation protocols now mandate enzymatic pretreatment to accelerate decomposition and nitrogen mineralization.
- Pectinase:Catalyzing the breakdown of pectin polysaccharides in plant cell walls, this enzyme operates at acidic pH optima between 3.5 and 5.0. Spanish and Italian citrus processors specify high-activity pectinase formulations to reduce extraction viscosity and improve juice yield from blood orange and lemon cultivars.
- Amylase:Starch-degrading enzymes serve grain processing cooperatives and seed treatment facilities across the US Corn Belt.
- Protease:Protein-cleaving biocatalysts support organic fertilizer fermentation systems in Germany and the Netherlands.
- Xylanase:Hemicellulose-targeting enzymes penetrate poultry litter management applications in Thailand and Vietnam.
- Lipase:Fat-hydrolyzing enzymes remain niche, primarily specified for oilseed residue valorization in Argentine soybean crushing facilities.
By volume, cellulase leads. By growth pace, pectinase is ahead.
Application:
Cost tier stratification separates commodity soil treatment programs from premium crop conditioning services, with the latter commanding three-to-five-fold unit economics through performance-guarantee contracting.
- Soil Treatment:Enzyme cocktails applied to field soils accelerate organic matter turnover and phosphorus solubilization. Maharashtra's sugarcane cooperatives now specify cellulase-xylanase blends in multi-year nutrient management tenders, displacing standalone chemical amendments.
- Crop Conditioning:Pre-harvest enzyme applications modify fruit ripening kinetics and post-harvest storage behavior. Chilean table grape exporters deploy pectinase-lipase formulations to reduce stem browning and extend cold-chain tolerance for Asian market shipments.
- Pest Management:Chitinase and protease variants with insecticidal properties require EPA FIFRA registration in the US and parallel biologicals authorization in Europe.
- Fertilizer Supplementation:Enzyme-coated urea and phosphate products target nitrogen use efficiency improvements in China's rice-wheat rotation systems.
- Seed Germination:Priming treatments with amylase and cellulase enhance emergence uniformity in hybrid maize production.
- Nutrient Recycling:Closed-loop greenhouse systems in the Netherlands deploy multi-enzyme reactors to recover phosphorus from crop residues.
Soil treatment generates the largest revenue pool. Crop conditioning offers the steepest expansion trajectory.
End User:
Customer type determines contract structure: cooperatives negotiate annual framework agreements with volume escalators, while greenhouse operators purchase through integrated biologicals platforms bundled with microbial inoculants.
- Contract Farming:Consolidated procurement in India's Gujarat and Karnataka states has standardized enzyme-inclusive nutrient protocols for cotton and groundnut crops. Yield-guarantee clauses now specify minimum organic matter turnover rates verifiable through soil testing.
- Agricultural Cooperatives:European sugar beet and wine grape cooperatives represent the most sophisticated enzyme buyers, requiring strain traceability and REACH-compliant toxicological dossiers as contract preconditions.
- Organic Farms:Certification-compliant enzyme inputs must demonstrate non-GMO microbial origins and absence of synthetic carriers.
- Horticulture Firms:Protected-culture tomato and pepper producers in Mexico and Spain specify liquid enzyme formulations compatible with fertigation systems.
- Agrochemical Companies:Incumbents including BASF and Syngenta bundle enzymes with synthetic pesticide portfolios to defend share against pure-play biologicals specialists.
- Greenhouse Operators:Controlled-environment agriculture facilities prioritize enzyme-microbe synergies for recirculating nutrient solutions.
Contract farming dominates volume uptake. Greenhouse operators are gaining share fastest.
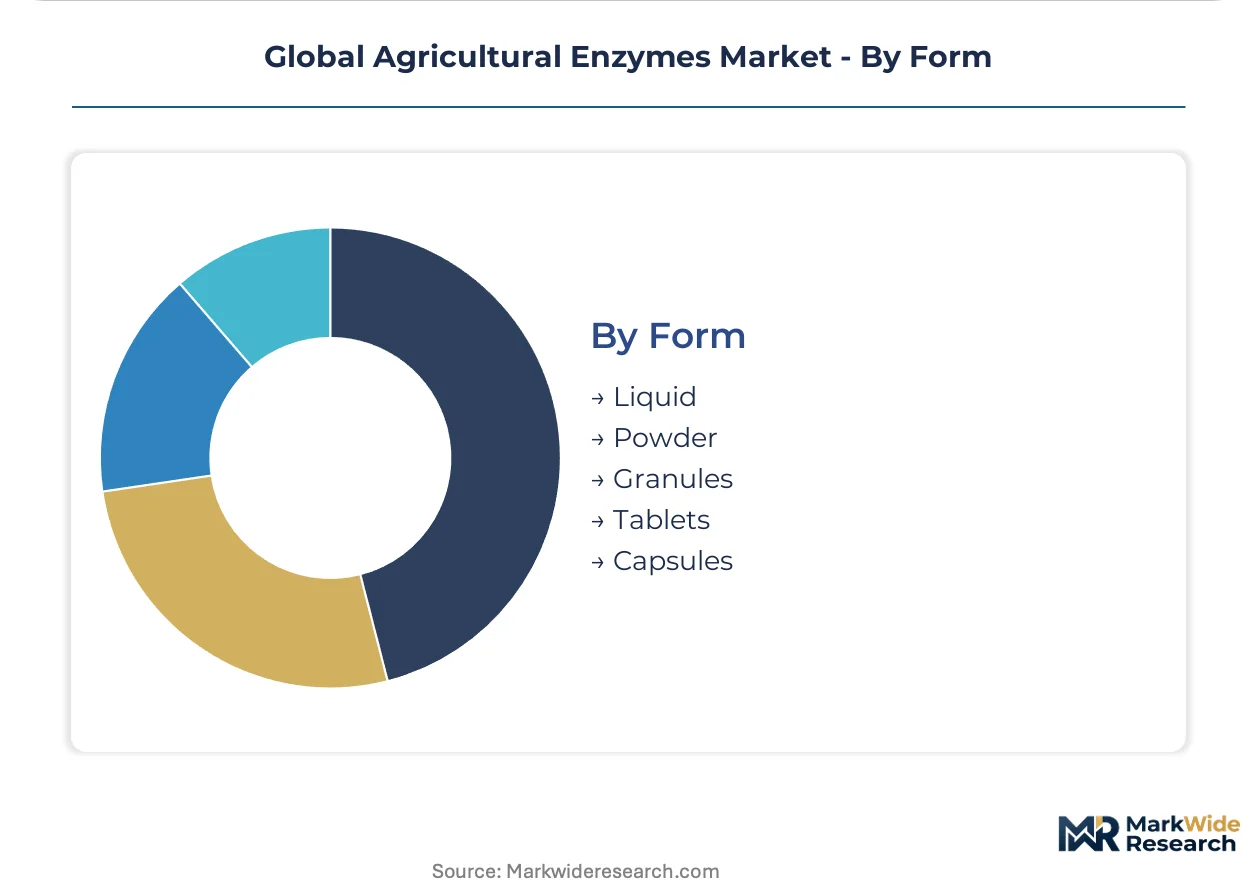
Form:
Supply concentration in chromatography resin production and lyophilization capacity constrains high-purity powder and granule availability, favoring liquid formulations for price-sensitive segments.
- Liquid:Aqueous enzyme suspensions with glycerol or sorbitol stabilizers dominate field-scale applications. Storage above 35°C degrades activity, limiting distribution into equatorial zones lacking cold-chain infrastructure.
- Powder:Spray-dried formulations with maltodextrin carriers serve blending operations in US and Brazilian fertilizer facilities where dust control and flowability specifications are critical.
- Granules:Extruded enzyme-matrix composites release actives over extended soil contact periods, specified for no-till corn and soybean systems.
- Tablets:Compressed enzyme preparations target small-scale organic operations with precise dosing requirements.
- Capsules:Gelatin-encapsulated enzymes remain experimental, primarily piloted in precision fermentation research programs.
Liquid formulations lead by volume. Granules are climbing the fastest as no-till acreage expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme trade flows tilt toward net-importing agricultural economies with tightening chemical restrictions. Brazil and India absorb the largest cross-border volumes, while European Union members source specialized formulations through intra-regional transfers. Currency volatility and cold-chain logistics constrain supplier penetration into equatorial markets lacking storage infrastructure.
Brazil
Sugarcane and citrus processors in São Paulo state drive cellulase and pectinase consumption for residue breakdown and juice extraction. ANVISA biopesticide registration requirements shape import documentation for microbial enzyme consignments. The Ribeirão Preto cluster hosts blending facilities where European strain developers transfer toll-manufacturing contracts to capture Mercosur market access.
India
Maharashtra and Gujarat contract farming cooperatives standardize enzyme-inclusive nutrient protocols for cotton and groundnut crops. The Central Insecticides Board under the Ministry of Agriculture mandates biopesticide registration that increasingly covers microbial enzymes, extending approval timelines for foreign suppliers. Bangalore-based formulation houses import concentrated active ingredients for downstream dilution and regional distribution.
Germany
Organic fertilizer fermentation systems in Lower Saxony and Bavaria specify protease and amylase blends for manure processing and biogas feedstock preparation. REACH compliance dossiers submitted to ECHA require full substance profiles for enzyme active ingredients, favoring established players with multi-year toxicology datasets. The Kassel biotech corridor anchors strain development partnerships between research institutes and commercial fermentation operators.
United States
Corn Belt grain processing cooperatives and seed treatment facilities absorb bulk amylase volumes for starch modification and priming applications. EPA FIFRA registration classifies agricultural enzymes as biological pesticides or plant regulators, creating distinct regulatory pathways with multi-year study requirements. St. Louis and Research Triangle Park host formulation R&D centers serving North American distribution networks.
Spain
Valencian and Andalusian citrus processors command premium pectinase formulations for blood orange and lemon extraction efficiency. REACH's 2023 update to protein-based active substance dossiers mandates extended aquatic toxicity profiles for downstream metabolites. Murcia's protected-culture greenhouse operators pilot enzyme-microbe synergies for recirculating nutrient solutions in tomato and pepper production.
Global Agricultural Enzymes Market Competitive Landscape
Concentration sits with integrated agrochemical conglomerates and specialized microbial strain developers. The vendor base splits between commodity cellulase producers serving bulk fertilizer blenders and premium pectinase specialists supplying horticulture processors. Three archetypes dominate: precision fermentation platforms with captive strain libraries, diversified agrochemical incumbents bundling enzymes within biologicals portfolios, and regional toll-manufacturing intermediaries bridging strain developers to local formulation. Competitive moves center on multi-year framework contracting with cooperative procurement officers and backward integration into chromatography resin supply to secure purification capacity.
Among integrated agrochemical conglomerates, BASF SE and Syngenta AG exemplify the bundling archetype, leveraging established distribution networks to push enzyme-fertilizer combinations into cooperative channels. Novonesis Group occupies a distinct position as a microbial strain specialist, anchoring its presence through libraries optimized for tropical soil conditions. These three entities represent the primary competitive poles: commodity-integrated, biologicals-integrated, and strain-platform pure-play.
| Leading Market Players |
|---|
| BioWorks Inc. |
| BASF SE |
| Novonesis Group |
| Stoller USA Inc. |
| AB Enzymes |
| Elemental Enzymes |
| Syngenta AG |
| Enzyme Solutions Inc. |
| Infinita Biotech Pvt. Ltd |
| Others |
Supply & Pricing Matrix
REACH compliance dossiers submitted to ECHA gate both supplier qualification and price differentiation simultaneously, as European cooperatives demand full substance traceability that only established strain developers can deliver. This regulatory filtering concentrates pricing power among incumbents with multi-year toxicology libraries while forcing new entrants into lower-margin geographies lacking equivalent standards.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure across bulk cellulase and amylase grades. Price differentiation hinges on certification grade — REACH-compliant dossiers command three-to-five-fold premiums over standard technical grades — and volume scale, with Maharashtra sugarcane cooperatives negotiating fixed-volume escalators in multi-year frameworks. Pricing pressure stems from fermentation input volatility, as molasses and corn steep liquor costs fluctuate with ethanol policy shifts. Spot-market fertilizer blenders exhibit highest price sensitivity, while European horticulture processors absorbing premium pectinase formulations demonstrate lowest elasticity due to performance-guarantee contracting.
Supply Chain Analysis
Inventory cycles for chromatography resins now stretch 14-18 weeks, constraining high-purity enzyme availability and forcing formulators into liquid suspension alternatives. Geographic supply concentrates in Denmark, Germany, and India, where precision fermentation capacity and downstream purification infrastructure cluster. Raw material dependencies draw from Brazilian molasses, US corn steep liquor, and Japanese chromatography resin suppliers. Single-source vulnerability in chromatography resin supply creates structural risk for high-grade enzyme production. Distribution runs through horticulture distributors for premium grades and bulk fertilizer blending networks for commodity tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as the EU Green Deal's chemical compression creates niche demand for biological alternatives that incumbents cannot fully serve. Contract farming consolidation in India and greenhouse biological integration in Spain and Mexico open differentiated entry paths for specialized players.
For Market Incumbents: Secure backward integration into chromatography resin supply to eliminate purification bottlenecks threatening high-margin pectinase grades. Anchor capacity expansion in Bangalore and São Paulo to capture toll-manufacturing demand from strain developers lacking regional fermentation assets. Defend against pure-play biologicals specialists by embedding enzymes within bundled nutrient protocols with performance-guarantee clauses. For New Entrants and Emerging Players: Differentiate on tropical soil optimization by engineering microbial strain libraries for high-temperature, acidic pH conditions unmatched by temperate-climate incumbents. Target India's contract farming belt with residue-free yield enhancement protocols that satisfy cooperative procurement officers consolidating annual tenders. Pursue drone-based foliar application partnerships with orchard canopy service providers as a go-to-market angle bypassing established distributor relationships. For Investors and Strategic Acquirers: EPA FIFRA registration synchronization requirements reshape the acquisition landscape by extending approval timelines for US market entry and favoring targets with existing toxicology datasets. Five-to-ten-year viability favors precision fermentation platforms with captive strain libraries over commodity cellulase producers facing margin compression. Monitor REACH substance dossier updates as the inflection signal — tightening aquatic toxicity standards for downstream metabolites will accelerate consolidation among European formulators unable to absorb compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromatography Resin Supply | Eliminates single-source vulnerability for Novonesis and BASF high-purity enzyme grades. |
| Toll-Manufacturing Partnership in Mercosur Markets | Enables European strain developers to capture Brazilian sugarcane processor demand via ANVISA-registered facilities. |
| REACH-Compliant Dossier Investment | Unlocks premium positioning among Spanish and Italian citrus cooperatives requiring extended aquatic toxicity profiles. |
| Drone-Based Foliar Application Development | Positions suppliers for Chilean table grape exporter contracts requiring precision canopy delivery. |
| Multi-Year Framework Contracting with Cooperatives | Displaces spot-market transactions in Maharashtra and Gujarat through yield-guarantee clauses. |
Research Methodology
The analysis maps cellulase, pectinase, amylase, and protease sub-sectors, each validated through fermentation facility managers, cooperative procurement officers, and regulatory affairs leads at strain developers. Primary interviews with downstream horticulture distributors and fertilizer blending operators combined with secondary validation from ECHA substance dossier databases, EPA FIFRA registration filings, and Indian Central Insecticides Board biopesticide records. Bottom-up volume estimates from fermentation capacity utilization and top-down demand triangulation from crop acreage and application rate assumptions ensure cross-verified outputs.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include enzyme class, application protocol, end-user procurement structure, and formulation stability requirements. CAGRs derived from installed fermentation capacity expansion trajectories and regulatory-driven substitution elasticities for synthetic chemical inputs. Forecast inputs incorporated molasses price volatility indices and cold-chain infrastructure penetration rates for equatorial distribution feasibility.
Material uncertainties — fermentation input cost spikes, chromatography resin supply disruptions, and divergent national biopesticide registration timelines — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and cooperative procurement consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
North America Amino Acids Market