
 Africa Feed Enzymes Market | 2026-2036
Africa Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Feed Enzymes Market Analysis
Commercial feed manufacturers is rotating toward specialized enzyme blends as livestock farmers in Kenya and Ethiopia seek premix solutions that lower feed conversion ratios. Novonesis leverages its fermentation technology leadership to supply phytase concentrates across East African milling corridors. BASF SE anchors its position through backward integration into enzyme production, ensuring supply continuity for Nigerian compound feed operations. Alltech Inc. differentiates via yeast-based additive platforms that complement its carbohydrase portfolio for ruminant applications.
Feed enzymes are protein-based biocatalysts—typically produced through submerged fermentation of fungal or bacterial strains—that hydrolyze anti-nutritional factors in cereal-based diets, with phytase operating optimally at pH 2.5-5.5 and temperatures between 40-60°C to liberate phosphorus from phytic acid. Their commercial purpose centers on improving nutrient digestibility, reducing environmental phosphorus excretion, and enabling cost-effective substitution of expensive protein and mineral ingredients in monogastric and ruminant rations. Phytase commands the dominant revenue share among product types due to universal phosphorus cost pressures, while liquid formulations grow fastest as integrated poultry operations automate their dosing systems. Poultry applications generate the largest volume demand, though aquaculture enzymes carry superior margin profiles as Nigerian and Egyptian tilapia producers adopt precision nutrition protocols.
South Africa's Department of Agriculture enforces maximum residue limits and feed safety standards that compel enzyme suppliers to submit stability data under local temperature and humidity conditions. The country's Bureau of Standards (SABS) aligns with Codex Alimentarius guidelines, creating a compliance threshold that filters out uncertified imports from Asian trading houses. Egypt's Ministry of Agriculture and Land Reclamation maintains import licensing for feed additives that requires local efficacy trials, extending registration timelines for new enzyme entrants. Stakeholders must monitor how harmonization between SADC and COMESA trade blocs reshapes cross-border enzyme registration requirements and tariff structures.
Market Dynamics
Commercial poultry integrators across Nigeria and South Africa are driving enzyme adoption as maize-soybean meal prices surge and phosphorus discharge regulations tighten, creating a structural pull for phytase and carbohydrase formulations that lower feed conversion ratios while meeting environmental compliance.
Growth Catalysts
- South Africa's mycotoxin regulations:The Department of Agriculture, Land Reform and Rural Development enforces strict maximum residue limits, compelling feed manufacturers to adopt enzyme-enhanced formulations that improve nutrient safety profiles.
- Precision nutrition protocols:Nigerian and Egyptian tilapia producers are integrating aquaculture-specific enzyme blends to optimize protein digestibility in high-density farming operations near Lagos and the Nile Delta.
- Carbohydrase adoption in East African ruminant sectors:Kenyan and Ethiopian dairy cooperatives are deploying fiber-degrading enzymes to unlock energy from locally sourced roughage, reducing dependence on imported concentrate feeds.
Market Restraints
- Fermentation input cost volatility:Submerged production of fungal and bacterial strains depends on molasses and nitrogen sources whose prices fluctuate with sugar crop yields across Southern Africa.
- Import concentration risk:Technical-grade enzyme concentrates arrive primarily through Durban and Lagos ports, creating vulnerability to shipping delays and customs bottlenecks at these Atlantic and Indian Ocean gateways.
- Thermostability limitations:Standard phytase formulations lose efficacy above 80°C during pelleting, forcing feed mills to choose between enzyme performance and feed manufacturing efficiency.
Strategic Opportunities
- Ethiopia's underpenetrated poultry belt:Addis Ababa's expanding broiler operations near Debre Zeit lack consistent enzyme supply, creating first-mover advantage for distributors establishing local technical service presence.
- Liquid dosing automation:Integrated operations in Egypt's Sharqia Governorate are retrofitting batch plants with inline enzyme injection systems, opening equipment-enzyme bundled service models.
- SADC-COMESA harmonization:Cross-border trade bloc alignment is reducing duplicate registration requirements, enabling regional suppliers to achieve economies of scale across Zimbabwe, Zambia, and Malawi markets.
Industry Challenges
- Formulation chemist scarcity:Feed mills in Ghana and Côte d'Ivoire struggle to recruit technical staff capable of optimizing multi-enzyme matrices for variable local grain quality.
- Egyptian efficacy trial timelines:The Ministry of Agriculture and Land Reclamation mandates local performance studies that extend new product registration by 18-24 months, freezing market entry for novel enzyme variants.
- Cold chain gaps for liquid enzymes:Temperature excursions during last-mile distribution to farms outside major Nigerian cities degrade phytase activity before application.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Feed Enzymes Market |
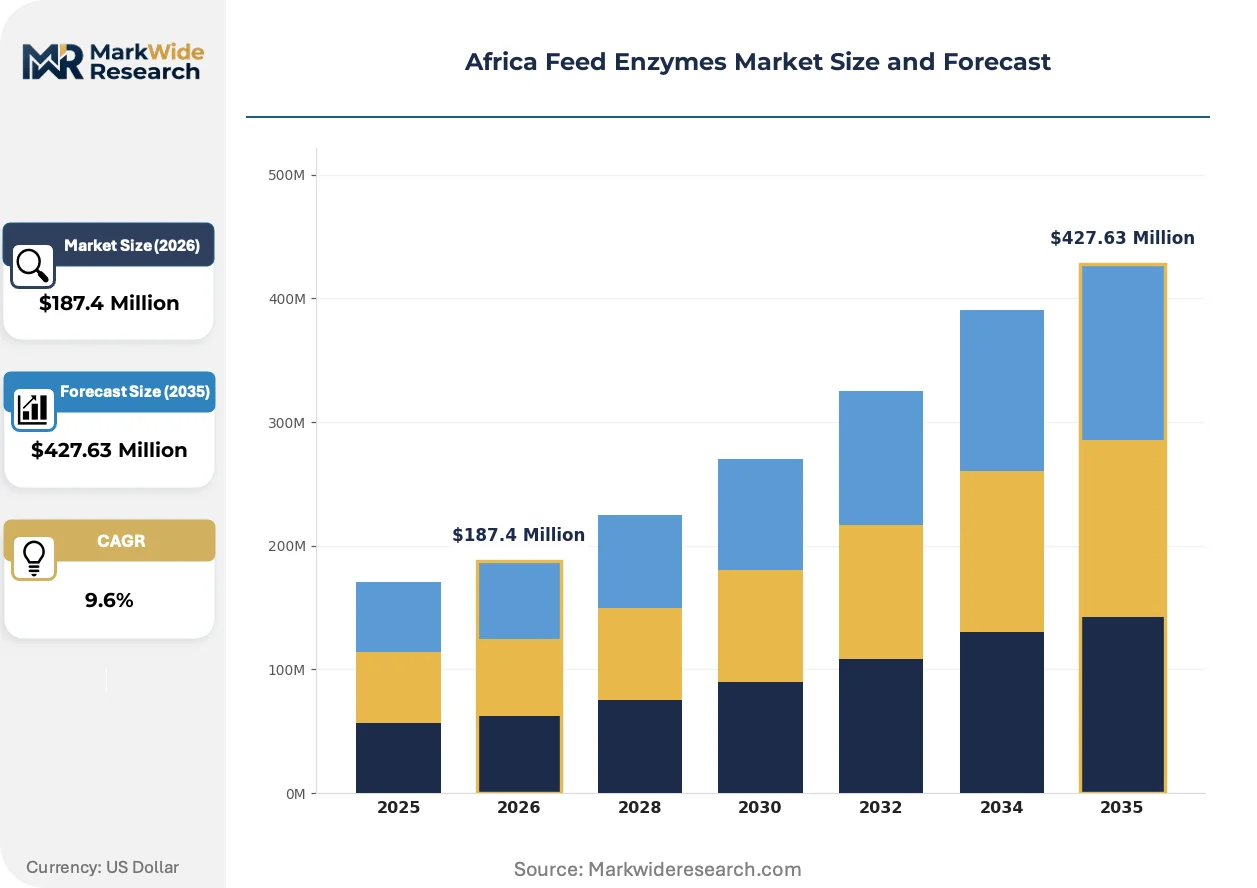
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Cellulase, Phytase Form: Liquid, Powder, Granular, Tablet Application: Poultry, Swine, Aquaculture, Ruminants End User: Feed Manufacturers, Livestock Farmers, Pet Food Industry, Aquaculture Producers |
| Companies Covered | IFF (Danisco Animal Nutrition), BASF SE, Novonesis, Kemin Industries Inc., Alltech Inc., Adisseo, Archer Daniels Midland Co., Rossari Biotech Limited, Elanco Animal Health Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Feed Enzymes Market Emerging Trajectories
Enzyme technology is fragmenting across multiple performance tiers as feed manufacturers demand solutions calibrated to specific raw material matrices rather than universal formulations, while regulatory pressure and procurement sophistication reshape how value flows through African supply chains.
Next-generation thermostable phytase variants produced through protein engineering are fragmenting the traditional enzyme landscape. Nigerian compound feed operations near Ibadan are adopting these heat-resistant formulations to maintain phosphorus liberation rates through high-temperature pelleting processes. The technology is fragmenting competitive positioning between global suppliers with research pipelines and regional blenders dependent on off-the-shelf concentrates.
South Africa's Bureau of Standards alignment with Codex Alimentarius guidelines is tightening stability documentation requirements for imported feed additives. Suppliers must now submit performance data under local temperature and humidity conditions before gaining market access. Poultry integrators in the Western Cape are prioritizing certified enzyme sources over lower-cost uncertified alternatives from Asian trading houses.
Long-term supply agreements are displacing spot purchasing among East African milling corridors. Kenyan commercial feed manufacturers near Nairobi are contracting directly with enzyme suppliers for 12-18 month volumes, securing price predictability amid currency volatility. This contracting behavior concentrates procurement leverage with integrated poultry operations while squeezing smaller compounders dependent on distributor markups.
Africa Feed Enzymes Market Segmentation
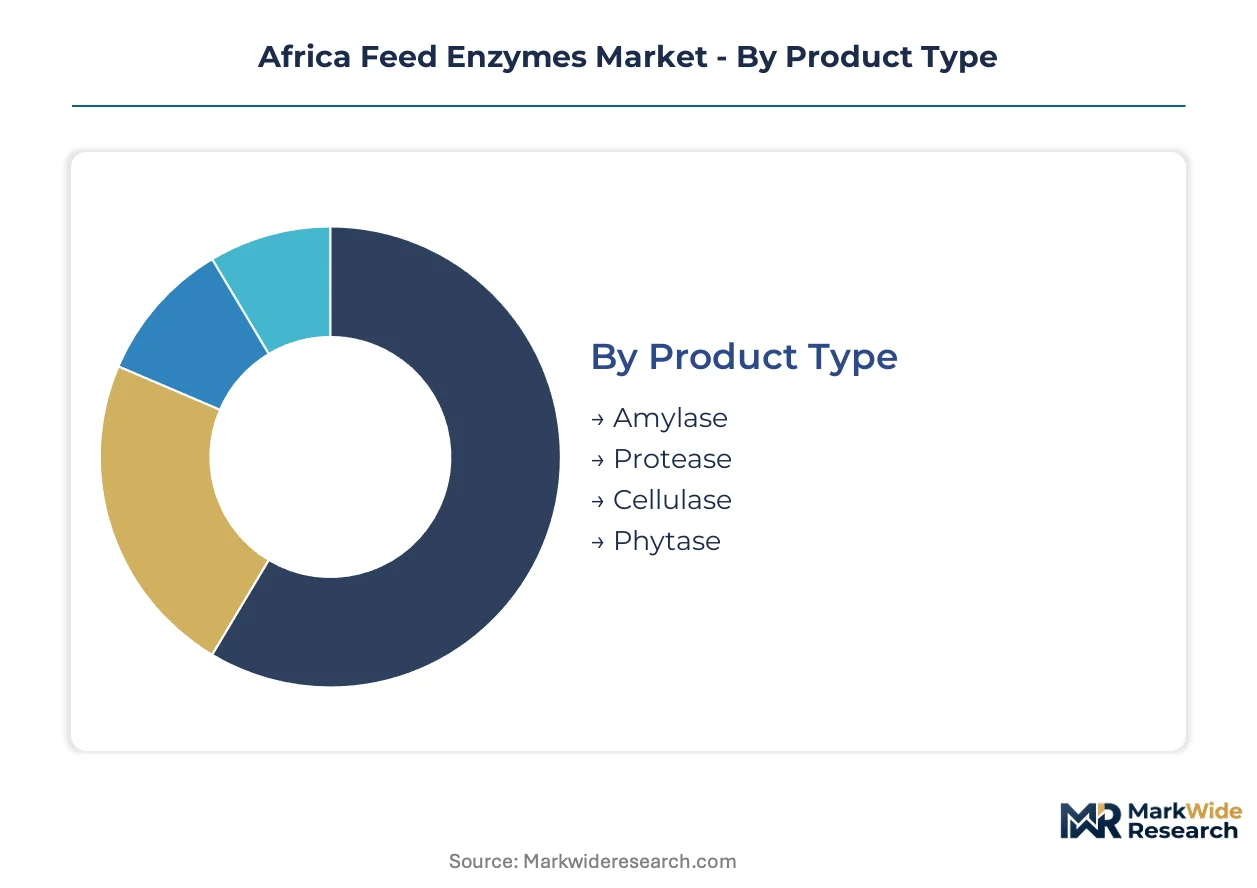
Feed enzyme segmentation across Africa reflects divergent supply chain realities between domestic milling corridors and import-dependent markets. Technical specifications, formulation stability, and dosing infrastructure vary sharply between South Africa's integrated operations and fragmented farming systems in West and East Africa.
Product Type:
Phytase dominates export-led procurement through Durban and Lagos ports, while carbohydrase variants concentrate in domestic East African ruminant applications.
- Phytase:This phosphorus-liberating enzyme operates optimally at pH 2.5-5.5 and temperatures between 40-60°C. Nigerian compound feed operations near Ibadan and Lagos anchor demand as maize-soybean meal prices surge and environmental discharge regulations tighten around phosphorus excretion.
- Cellulase:Fiber-degrading biocatalysts unlock energy from roughage in ruminant diets. Kenyan and Ethiopian dairy cooperatives deploy these enzymes to reduce dependence on imported concentrate feeds, though thermostability limitations during pelleting constrain formulation flexibility.
- Amylase:Starch-hydrolyzing enzymes improve energy digestibility in cereal-based poultry rations across Ghanaian and Ivorian feed mills.
- Protease:Protein-degrading catalysts support amino acid availability in high-density aquaculture operations near Egypt's Nile Delta.
Phytase holds the largest share; momentum sits with cellulase as East African dairy sectors expand.
Form:
Powder formulations dominate cost-sensitive domestic markets, while liquid enzymes concentrate in automated dosing systems at integrated export-oriented operations.
- Liquid:Inline injection systems enable precise dosing at Egyptian poultry integrators in Sharqia Governorate. Cold chain gaps during last-mile distribution to farms outside major Nigerian cities degrade phytase activity, limiting penetration beyond port-proximate milling corridors.
- Powder:Dry formulations dominate Kenyan and Ethiopian commercial feed manufacturing near Nairobi and Addis Ababa. These variants tolerate temperature excursions during regional distribution but require manual blending infrastructure absent at smaller compounders.
- Granular:Coated particles protect enzyme activity through high-temperature pelleting processes at South African integrators facing Bureau of Standards stability requirements.
- Tablet:Compressed dosing units serve smallholder livestock farmers in Ghana and Côte d'Ivoire lacking technical staff for multi-enzyme matrix optimization.
Powder commands volume leadership; liquid formulations are climbing the fastest as automation spreads.
Application:
Poultry applications concentrate procurement leverage among large-scale operations, while aquaculture carries superior margin profiles in precision nutrition protocols.
- Poultry:Broiler and layer operations across Nigeria's belt near Lagos and Ibadan generate the largest enzyme volume demand. Feed conversion ratio pressures and mycotoxin regulations from South Africa's Department of Agriculture, Land Reform and Rural Development drive phytase and carbohydrase adoption at commercial integrators.
- Aquaculture:Tilapia producers in Egypt's Nile Delta and Nigerian operations near Lagos integrate specialized enzyme blends for protein digestibility optimization. High-density farming protocols justify premium pricing for aquaculture-specific formulations.
- Ruminants:Kenyan and Ethiopian dairy cooperatives deploy fiber-degrading enzymes to unlock roughage energy, reducing imported concentrate dependence.
- Swine:Pork production in South Africa's Western Cape and Eastern Cape provinces utilizes phytase-enhanced formulations to meet environmental compliance standards.
Poultry anchors demand volume; aquaculture shows the steepest expansion trajectory on margin strength.
End User:
Feed manufacturers concentrate procurement through long-term supply agreements, while livestock farmers and aquaculture producers fragment across spot purchasing and distributor markups.
- Feed Manufacturers:Commercial compounders near Nairobi, Lagos, and Johannesburg contract directly with enzyme suppliers for 12-18 month volumes. Kenyan operations secure price predictability amid currency volatility, concentrating leverage with integrated poultry operations while squeezing smaller mills dependent on distributor networks.
- Aquaculture Producers:Egyptian tilapia operations and Nigerian catfish farms near Lagos adopt precision nutrition protocols requiring technical service support for enzyme matrix optimization.
- Livestock Farmers:Smallholder dairy and beef operations across Ethiopia's Debre Zeit corridor and Ghana's Ashanti region lack consistent enzyme supply, creating first-mover opportunities for distributors establishing local technical presence.
- Pet Food Industry:Specialty feed producers in South Africa's Western Cape utilize enzyme-enhanced formulations for premium companion animal nutrition products.
Feed manufacturers represent the dominant procurement channel; aquaculture producers are gaining share fastest on precision nutrition adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial feed manufacturers concentrate procurement leverage across four distinct national markets, each shaped by divergent regulatory stringency and livestock sector maturity. Integrators in Nigeria and South Africa anchor volume demand, while Kenya and Egypt represent expansion frontiers with contrasting compliance barriers.
Nigeria
Large-scale broiler operations near Lagos and Ibadan drive phytase and carbohydrase consumption as maize-soybean meal costs surge. The country's national feed safety regulator enforces import documentation requirements that filter uncertified enzyme concentrates. Poultry integrators in Ogun State are retrofitting mills with automated dosing infrastructure to reduce feed conversion ratios.
South Africa
Integrated poultry and swine producers in the Western Cape and Gauteng provinces absorb premium enzyme formulations to meet discharge compliance standards. The Department of Agriculture, Land Reform and Rural Development mandates mycotoxin maximum residue limits that compel stability-tested additives. Feed compounders near Johannesburg are consolidating procurement through 12-18 month supply contracts to hedge currency volatility.
Kenya
Dairy cooperatives in the Rift Valley deploy fiber-degrading enzymes to unlock energy from locally sourced roughage and reduce imported concentrate dependence. The Kenya Bureau of Standards aligns feed additive regulations with Codex Alimentarius guidelines, creating compliance thresholds for imported concentrates. Commercial feed manufacturers near Nairobi are establishing direct supplier relationships to bypass distributor markups.
Egypt
Tilapia producers in the Nile Delta integrate specialized aquaculture enzyme blends for protein digestibility optimization in high-density farming protocols. The Ministry of Agriculture and Land Reclamation requires local efficacy trials that extend new product registration timelines by 18-24 months. Operations in Sharqia Governorate are adopting liquid dosing automation to enable precision nutrition protocols.
Ethiopia
Emerging broiler operations near Debre Zeit lack consistent enzyme supply chains, creating first-mover opportunities for technical service providers. The country's national agricultural regulator maintains import licensing requirements for feed additives that favor established regional suppliers. Poultry integrators around Addis Ababa are seeking premix solutions to lower feed conversion ratios amid expanding domestic protein demand.
Africa Feed Enzymes Market Vendor Landscape
Player mix skews toward multinational biocatalyst suppliers with fermentation technology leadership and regional distribution networks. Market structure concentrates procurement leverage among three to four integrated suppliers capable of delivering technical-grade concentrates through Durban and Lagos port corridors. Strategic archetypes separate global research-intensive players with protein engineering pipelines from regional blenders dependent on licensed concentrate formulations. Competitive moves center on backward integration into enzyme production and long-term supply contracting with East African milling corridors.
Among European-based biocatalyst specialists, BASF SE and Novonesis occupy positions anchored by captive fermentation capacity and regional technical service infrastructure. Novonesis exemplifies the research-intensive archetype through its leadership in submerged fermentation technology deployment across East African markets. BASF SE represents the vertically integrated model with in-house enzyme production ensuring supply continuity for Nigerian compound feed operations. Alltech Inc. sits within the yeast-based additive specialist tier, differentiating through complementary platforms for ruminant applications. These three suppliers collectively illustrate how global biocatalyst leaders are calibrating Africa-specific strategies around regulatory compliance, port-proximate distribution, and precision nutrition service models.
| Leading Market Players |
|---|
| IFF (Danisco Animal Nutrition) |
| BASF SE |
| Novonesis |
| Kemin Industries Inc. |
| Alltech Inc. |
| Adisseo |
| Archer Daniels Midland Co. |
| Rossari Biotech Limited |
| Elanco Animal Health Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Durban and Lagos port corridors shapes both supply concentration and price floors for technical-grade enzyme concentrates. Kenyan and Ethiopian commercial feed manufacturers absorb distributor markups when direct supplier relationships fail, while South African integrators leverage long-term contracting to compress input costs.
Pricing Analysis
Cost-plus contracts with molasses and nitrogen source indexation dominate procurement between global biocatalyst suppliers and East African milling corridors. Three-tier pricing structure across premium thermostable phytase, standard liquid formulations, and economy powder concentrates separates certified suppliers from uncertified Asian trading houses. Cost compression in standard-grade carbohydrase is intensifying because fermentation input volatility squeezes regional blenders. Smallholder livestock farmers in Ghana and Côte d'Ivoire exhibit highest price sensitivity, while Egyptian tilapia producers accept premium positioning for precision nutrition protocols.
Supply Chain Analysis
Inventory lead times for liquid phytase stretch beyond powder alternatives due to cold chain requirements through Nigerian last-mile distribution. Technical-grade concentrates originate primarily from Denmark, Germany, and the Netherlands, with formulation blending anchored in South Africa and Nigeria. Submerged fermentation draws from molasses, nitrogen substrates, and fungal or bacterial strain banks vulnerable to Southern African sugar crop yield fluctuations. Single-source vulnerability concentrates at Durban and Lagos ports, where customs bottlenecks disrupt just-in-time delivery. Distribution runs through regional distributors serving fragmented farming systems and direct-supply agreements with integrated poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs. Egypt's 18-24 month efficacy trial timelines and South Africa's Bureau of Standards stability documentation freeze out uncertified competitors.
For Market Incumbents: Fortify captive fermentation capacity and backward integration into enzyme production to secure supply continuity against emerging regional blenders. BASF SE's model of in-house production ensures Nigerian compound feed operations avoid port-disruption vulnerability. Invest in thermostable phytase R&D to defend margin position as high-temperature pelleting spreads. For New Entrants and Emerging Players: Differentiate on local technical service presence in Ethiopia's underpenetrated Debre Zeit poultry belt, where consistent enzyme supply gaps persist. Target liquid dosing automation bundles for Egyptian integrators retrofitting Sharqia Governorate batch plants. Penetrate through equipment-enzyme service models rather than commodity concentrate sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among yeast-based additive specialists with ruminant application platforms, given Kenyan and Ethiopian dairy cooperative expansion. Long-term viability rests on regulatory navigation capabilities across SADC-COMESA harmonization. Watch SADC-COMESA cross-border registration alignment as inflection signal for regional scale economies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive production insulates Nigerian operations from Durban port congestion and currency volatility. |
| Thermostable Phytase Development | Heat-resistant variants maintain efficacy through high-temperature pelleting at South African integrators. |
| Liquid Dosing Automation Bundles | Equipment-enzyme service models penetrate Egyptian Sharqia Governorate precision nutrition retrofit programs. |
| Local Efficacy Trial Investment | Early registration in Egypt's Ministry of Agriculture pipeline accelerates 18-24 month market access timelines. |
| SADC-COMESA Harmonization Positioning | Regional registration consolidation enables scale economies across Zimbabwe, Zambia, and Malawi distribution. |
Methodological Framework
A spread of perspectives from fermentation technology directors, East African feed mill procurement managers, Nigerian poultry integrator nutritionists, and Egyptian aquaculture operations specialists converged on the working assumptions. Secondary validation drew from South Africa's Bureau of Standards stability documentation, Egypt's Ministry of Agriculture registration filings, SADC trade bloc harmonization protocols, and COMESA cross-border tariff schedules. Bottom-up enzyme volume estimates from port import records triangulated against top-down livestock sector feed conversion ratio benchmarks.
Segmentation dimensions modeled span product type, formulation stability tier, application species, and end-user procurement sophistication across the projection horizon. CAGRs were derived from elasticity-adjusted feed cost pressures and regulatory compliance adoption curves. Industry-specific inputs included South African mycotoxin maximum residue limit enforcement trajectories and Nigerian maize-soybean meal price volatility indices.
Material uncertainties — currency devaluation spikes, shipping route disruptions at Durban and Lagos, and fermentation substrate crop failures — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory harmonization pace and cold chain infrastructure buildout. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Agricultural Microbials Market