
 Air Fryer Paper Liners Market | 2026-2036
Air Fryer Paper Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Air Fryer Paper Liners Market Insights
China is fragmenting as new manufacturing zones add air fryer liner capacity to serve export and domestic kitchenware channels. Reynolds Consumer Products leverages its North American retail shelf presence to sustain volume leadership in pre-cut circular formats. BYKITCHEN specializes in silicone-coated variants that compete on heat-resistance claims across e-commerce platforms. Numola anchors its position through direct-to-consumer subscription models that reduce customer acquisition costs.
Air fryer paper liners are disposable sheets, typically composed of bleached or unbleached cellulose pulp with silicone or quilon treatments, engineered to withstand temperatures between 400°F and 450°F while preventing food adhesion and simplifying cleanup. Their primary commercial purpose centers on extending appliance lifespan by blocking grease migration to heating elements and reducing consumer cleaning time. Parchment paper formulations dominate unit economics due to established supply chains and familiar consumer handling, though compostable paper segments capture premium positioning as municipal organic waste programs expand. The foodservice application channel shows structural momentum as quick-service restaurants adopt air fryers for reduced-oil menu items, while perforated shapes command margin pools through claims of optimized airflow circulation.
The FDA regulates food-contact substances under 21 CFR requirements, while the EPA oversees per- and polyfluoroalkyl substance restrictions that push manufacturers toward PFAS-free barrier coatings. The EU's Framework Regulation EC 1935/2004 and Germany's BfR recommendations on silicone migration limits create compliance thresholds for export-oriented producers. California's Proposition 65 warning requirements and the state's Safer Food Packaging and Cookware Act further constrain additive chemistries in products sold through West Coast distribution channels. Stakeholders must monitor evolving state-level chemical disclosure mandates and third-party compostability certifications to preserve market access across fragmented regulatory territories.
Market Dynamics
EU Single-Use Plastics Directive enforcement and California's Safer Food Packaging and Cookware Act are forcing material substitutions across supply chains, compressing margins for PFAS-dependent coating technologies while opening premium positioning for certified compostable alternatives.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates for reduced plastic content in food-contact materials accelerate demand for cellulose-based barrier coatings in European distribution channels.
- Quick-service restaurant air fryer adoption:Reduced-oil menu development drives commercial liner procurement at volumes exceeding residential replacement cycles.
- Perforated die-cut geometries:Optimized airflow claims command price premiums over standard circular formats through demonstrable cooking performance differentiation.
Market Restraints
- Fluorinated chemistry phase-outs:EPA PFAS restrictions and state-level prohibitions eliminate established quilon coating supply chains before silicone alternatives achieve cost parity.
- Pulp supply concentration:Nordic and Brazilian softwood pulp markets dictate input cost volatility for bleached kraft liner substrates.
- Temperature ceiling limitations:Silicone-coated cellulose formulations degrade above 450°F, excluding high-temperature air fryer applications above this threshold.
Strategic Opportunities
- German municipal organic waste programs:BfR-compliant compostable liners capture household segment premiums through verified biodegradability certification.
- Subscription meal-kit channel integration:Direct-to-consumer bundling of pre-portioned liners with recipe shipments reduces customer acquisition costs versus standalone retail.
- Smart packaging convergence:Temperature-indicating inks and QR-coded disposal instructions merge liner functionality with connected kitchen ecosystems.
Industry Challenges
- Food-grade certification timelines:FDA 21 CFR food-contact notifications and EU Framework Regulation EC 1935/2004 compliance documentation extend new product introduction cycles.
- Coating equipment reconfiguration:Silicone barrier application lines require capital investment distinct from legacy quilon bath systems, stranding mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Fryer Paper Liners Market |
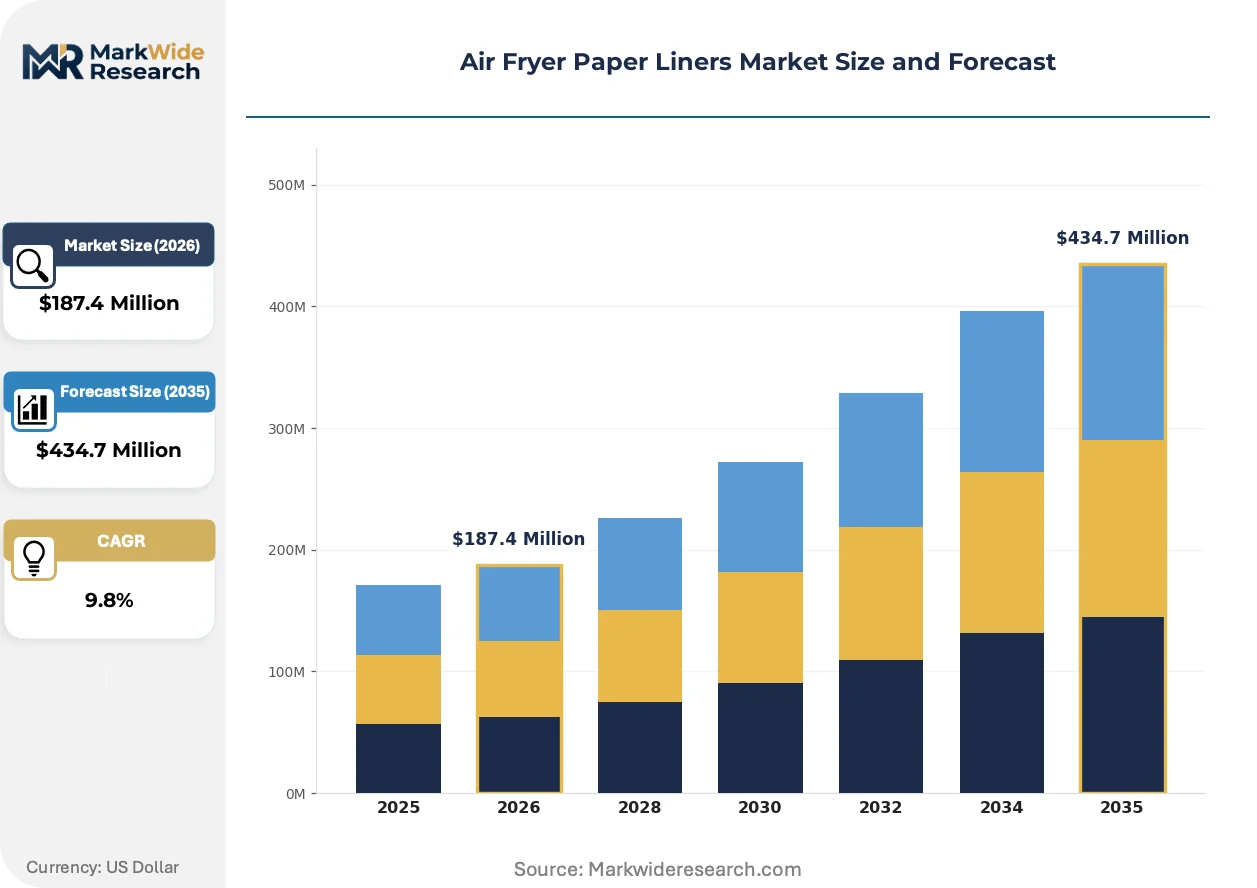
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Parchment Paper, Silicone Coated, Unbleached Paper, Bamboo Fiber, Compostable Paper Application: Household Cooking, Foodservice Industry, Healthy Cooking, Snack Preparation, Catering Services Product Shape: Round, Square, Rectangular, Perforated, Customized Shape Packaging Type: Rolls, Folded Sheets, Pre-cut Circles, Perforated Sheets, Bulk Packaging |
| Companies Covered | Reynolds Consumer Products, BYKITCHEN, Numola, NETANY, AIEVE, SMARTAKE, Acerich, If You Care, PaperChef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Fryer Paper Liners Market Trends and Innovations
Barrier coating chemistry and substrate sourcing are undergoing parallel transformation as regulatory deadlines eliminate incumbent technologies and consumer-facing brands demand supply chain transparency.
Silicone-based heat-resistant formulations are migrating from specialty premium tiers toward mass-market standard specifications. Quick-service restaurant procurement teams now specify silicone-coated liners for high-throughput air fryer operations, compressing the price gap between commodity and performance grades. This migration from quilon to silicone is eliminating the historical two-tier coating market structure.
California's Proposition 65 warning requirements and the state's Safer Food Packaging and Cookware Act now constrain additive chemistries for products entering West Coast distribution. Manufacturers serving US markets must maintain dual formulation inventories or standardize on PFAS-free coatings nationwide. The branded consumer segment bears the heaviest compliance burden, reformulating packaging claims and sourcing documentation to satisfy retailer due diligence protocols.
Subscription replenishment models are displacing episodic retail purchasing for residential air fryer owners. Direct-to-consumer platforms capture liner demand through automated reorder algorithms tied to usage frequency data, bypassing traditional grocery and big-box shelf competition. This pattern concentrates most visibly in United States metropolitan markets where air fryer penetration and e-commerce logistics density align.
Air Fryer Paper Liners Market Segmentation
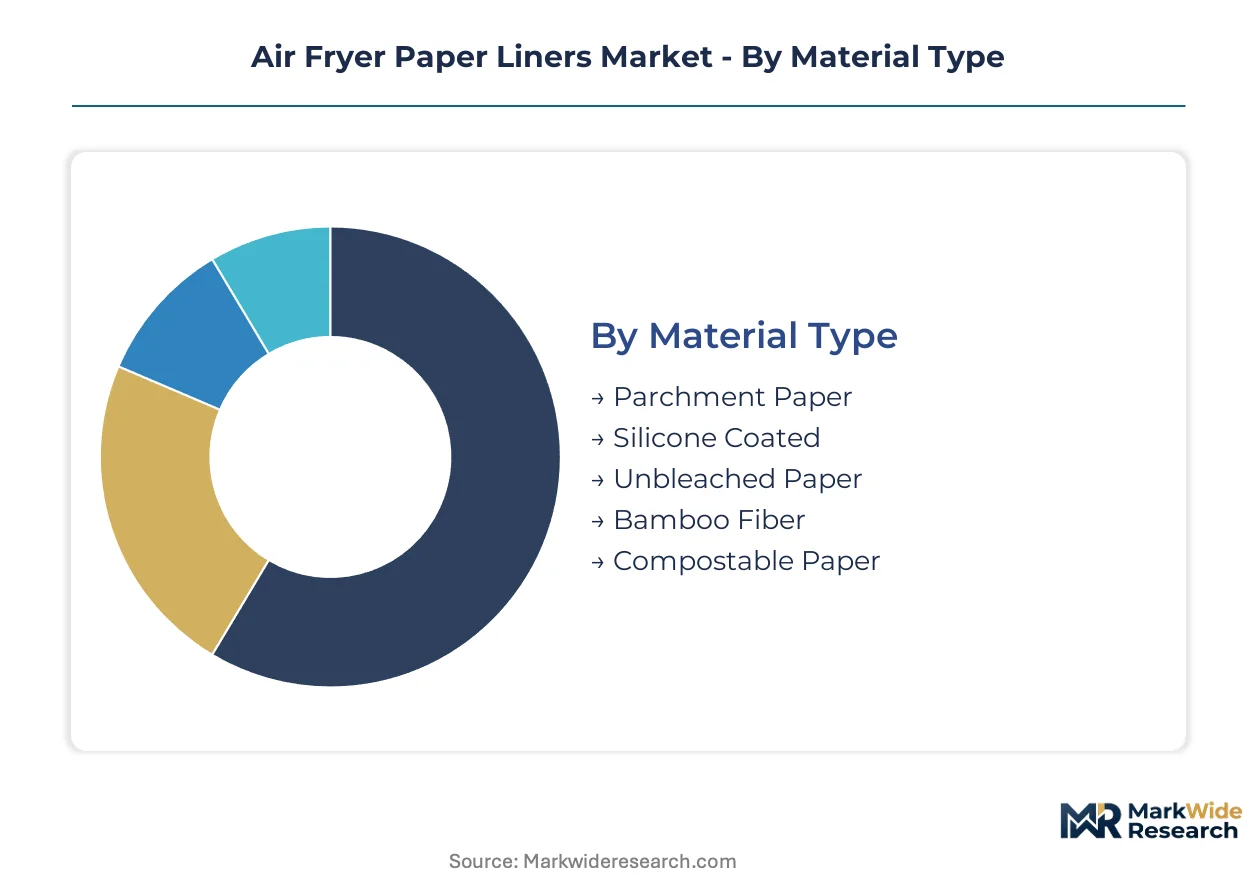
Material chemistry and product geometry dictate margin structures across air fryer liner supply chains. End-use application channels separate residential replenishment cycles from commercial procurement volumes. Packaging formats determine distribution economics and retail shelf placement strategies.
Material Type:
Cost tier positioning separates commodity cellulose substrates from certified premium alternatives, with coating technology driving performance differentiation.
- Parchment Paper:Bleached or unbleached cellulose pulp treated with silicone or quilon barriers dominates unit economics through established supply chains. Quick-service restaurants in the United States specify these liners for high-throughput air fryer operations where familiar handling properties reduce training friction.
- Silicone Coated:Heat-resistant formulations withstand temperatures approaching 450°F, capturing procurement specifications from commercial kitchens running extended cooking cycles. German foodservice distributors now mandate silicone-only coatings to preempt BfR compliance complications.
- Unbleached Paper:Kraft pulp retains natural lignin content, appealing to consumers prioritizing reduced chemical processing over optical brightness.
- Bamboo Fiber:Rapid-renewable grass pulp offers alternative cellulose sourcing for brands emphasizing agricultural diversification.
- Compostable Paper:BPI or TUV-certified biodegradability commands household premiums in municipalities with curbside organic waste collection.
Parchment Paper holds installed capacity. Silicone Coated is rotating up the share rankings.
Application:
Customer type separates episodic residential purchasing from contract-based commercial procurement with divergent price sensitivity profiles.
- Household Cooking:Individual consumers purchase through grocery, big-box, or direct-to-consumer channels with replenishment cycles tied to air fryer usage frequency. Subscription bundling with meal-kit services concentrates demand in United States metropolitan markets.
- Foodservice Industry:Quick-service restaurants and ghost kitchen operators procure liners at volumes exceeding residential replacement by an order of magnitude, with specifications written around labor cost reduction and equipment protection. California's Safer Food Packaging and Cookware Act constrains coating chemistries for chains operating West Coast locations.
- Healthy Cooking:Reduced-oil positioning aligns with wellness-oriented consumer segments willing to pay formulation premiums.
- Snack Preparation:Frozen appetizer and finger-food applications drive seasonal demand spikes around entertaining periods.
- Catering Services:Event-based volume purchasing with storage and transport efficiency requirements.
Foodservice Industry holds installed capacity. Healthy Cooking is rotating up the share rankings.
Product Shape:
Geometry determines airflow optimization claims and die-cutting capital requirements across manufacturing footprints.
- Perforated:Laser- or die-cut apertures engineered for convective circulation command price premiums through demonstrable cooking performance differentiation. German and United States consumer brands now specify perforated geometries as standard for premium tier positioning.
- Round:Pre-cut circular formats match dominant air fryer basket geometries, minimizing consumer trimming labor and reducing material waste.
- Square:Orthogonal cutting suits toaster-oven style air fryer configurations and multi-use baking applications.
- Rectangular:Extended aspect ratios serve dual-basket and commercial-grade equipment formats.
- Customized Shape:OEM-matched die patterns for proprietary appliance footprints, typically contract-manufactured for branded appliance accessories.
Round holds installed capacity. Perforated is rotating up the share rankings.
Packaging Type:
Volume and margin structure separate consumer convenience formats from commercial efficiency configurations.
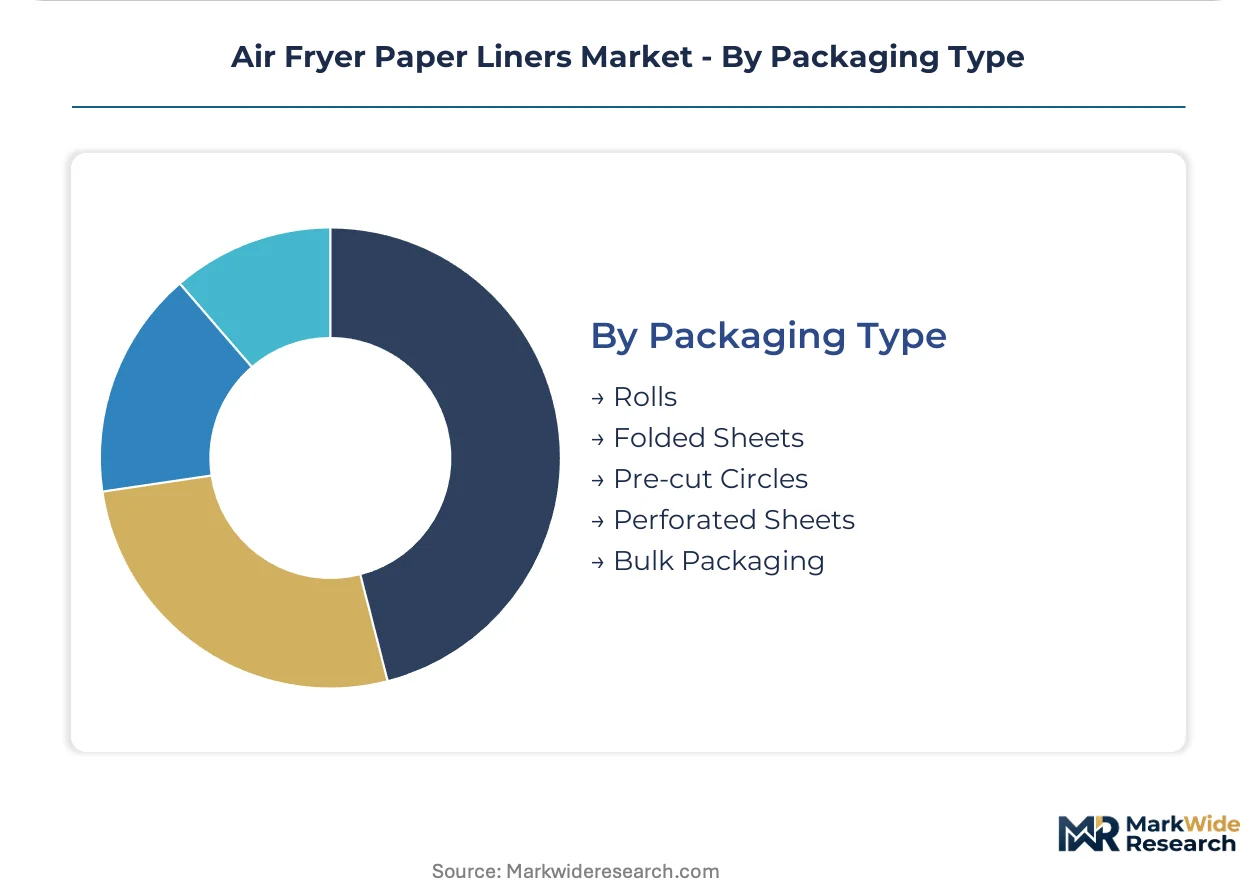
- Pre-cut Circles:Individual sheets packaged in retail-count boxes dominate United States grocery and mass-market channels, with Reynolds Consumer Products leveraging shelf presence for volume leadership.
- Rolls:Continuous sheet formats allow user-determined sizing, concentrating in price-sensitive segments and commercial operations with variable tray dimensions.
- Folded Sheets:Interleaved stacking reduces packaging cube and shipping cost for e-commerce fulfillment.
- Perforated Sheets:Pre-apertured formats combine shape and airflow optimization in single-SKU convenience.
- Bulk Packaging:Case-quantity configurations serve foodservice procurement with cost-per-unit minimization objectives.
Pre-cut Circles holds installed capacity. Bulk Packaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact regulations anchor the United States as the dominant geography, while EU Framework Regulation EC 1935/2004 and Germany's BfR recommendations reshape European material specifications. Municipal organic waste programs and state-level chemical disclosure mandates create divergent compliance territories across major consumption clusters.
United States
Subscription meal-kit services and direct-to-consumer replenishment models concentrate demand in metropolitan markets. California's Proposition 65 warning requirements and the Safer Food Packaging and Cookware Act constrain additive chemistries for West Coast distribution channels. Reynolds Consumer Products leverages established retail shelf presence across the Midwest and Southeast to sustain volume leadership in pre-cut circular formats.
Germany
BfR recommendations on silicone migration limits create compliance thresholds for compostable liner certification. Municipal organic waste collection programs in Berlin and Hamburg drive household premiums for TUV-certified biodegradable variants. Baden-Württemberg manufacturing clusters specialize in silicone-coated barrier application equipment for export-oriented producers.
China
New manufacturing zones in Zhejiang and Guangdong provinces add air fryer liner capacity to serve export and domestic kitchenware channels. The country's national food safety regulator enforces GB standards for food-contact paper products. Yangtze River Delta industrial parks concentrate die-cutting and coating operations for e-commerce platform fulfillment.
United Kingdom
Quick-service restaurant chains operating ghost kitchen networks procure liners at commercial volumes exceeding residential replacement cycles. The Food Standards Agency enforces EU-retained food-contact material regulations post-Brexit. Greater London logistics density supports subscription bundling with recipe shipment services.
Japan
Compact air fryer appliance formats drive demand for precision-cut liner geometries in urban households. METI oversees product safety standards for kitchen accessories and food-contact materials. Osaka-based trading houses coordinate import distribution of silicone-coated variants for premium retail positioning.
Air Fryer Paper Liners Market Competitive Landscape
Consumer-branded incumbents and specialty coating specialists split the market into distinct capability tiers. The vendor base organizes around retail shelf dominance, e-commerce platform optimization, and direct-to-consumer subscription mechanics. Three archetypes prevail: mass-market consumer brands with grocery channel leverage, silicone-coating specialists competing on heat-resistance specifications, and digitally native operators capturing replenishment demand through automated reorder algorithms. Geographic expansion and portfolio diversification represent the dominant competitive moves as participants seek to offset input cost volatility.
Among North American consumer product incumbents, Reynolds Consumer Products occupies a position exemplifying retail shelf-scale leverage, while BYKITCHEN represents the specialty coating archetype competing across digital channels. Numola anchors the direct-to-consumer subscription tier with automated replenishment models that reduce customer acquisition costs versus standalone retail competition.
| Leading Market Players |
|---|
| Reynolds Consumer Products |
| BYKITCHEN |
| Numola |
| NETANY |
| AIEVE |
| SMARTAKE |
| Acerich |
| If You Care |
| PaperChef |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province manufacturing clusters in China absorb coating equipment reconfiguration costs while exporting silicone-coated variants to United States and German distribution channels, compressing margin structures for mid-scale competitors lacking scale economies in barrier application technology.
Pricing Analysis
United States retail pricing for pre-cut circular formats runs 40-60% above German municipal procurement rates for compostable certified alternatives, reflecting divergent certification burden and last-mile fulfillment cost structures. Three-tier pricing structure across premium, standard, and economy levels separates BPI-certified compostable grades from silicone-coated performance tiers and unbleached kraft commodity offerings. Pricing pressure stems from California's Safer Food Packaging and Cookware Act compliance documentation requirements, which force dual-formulation inventory maintenance. Quick-service restaurant procurement teams exhibit lowest price sensitivity due to labor-cost reduction specifications, while household subscribers through meal-kit channels demonstrate highest elasticity.
Supply Chain Analysis
Export-control regimes on fluorinated chemistry precursors under EPA PFAS restrictions constrain quilon coating supply chains before silicone alternatives achieve cost parity, stranding legacy equipment investments across mid-tier manufacturers. Pulp supply concentrates in Nordic softwood markets and Brazilian eucalyptus plantations, with silicone barrier formulations drawing from petroleum-derived polymer feedstocks. Single-source vulnerability in Nordic bleached kraft supply creates input cost volatility during seasonal harvest disruptions. Distribution runs through United States big-box retail shelf presence, German foodservice distributor networks, and Chinese e-commerce platform fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier coating chemistry expertise and food-grade certification navigation capabilities represent the scarcest operational assets in this market, separating viable competitors from margin-compressed commodity suppliers.
For Market Incumbents: Insulate margin structures by securing captive silicone coating capacity in Baden-Württemberg equipment manufacturing clusters before PFAS phase-out deadlines eliminate quilon alternatives. Deepen backward integration into Nordic pulp supply contracts to neutralize input cost volatility from Brazilian harvest cycles. Defend against direct-to-consumer subscription entrants by controlling retail shelf space allocation in Midwest United States grocery channels. For New Entrants and Emerging Players: Establish a beachhead in German municipal organic waste program certification tiers where TUV-verified biodegradability commands household premiums and incumbent brand recognition remains underdeveloped. Target ghost kitchen operators in Greater London logistics corridors with bulk perforated geometries optimized for commercial air fryer throughput. Deploy subscription bundling with recipe shipment services as the primary go-to-market mechanism to bypass established retail shelf competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors silicone-coating specialists with FDA 21 CFR notification expertise and EU Framework Regulation EC 1935/2004 compliance documentation capabilities. Long-term viability hinges on PFAS-free formulation leadership and municipal compostability certification penetration across European organic waste collection programs. Monitor California state-level chemical disclosure mandate expansion as the inflection indicator for nationwide formulation standardization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Coating Capacity Expansion | Baden-Württemberg equipment clusters preempt PFAS phase-out stranding risk for export-oriented producers. |
| BPI/TUV Certification Investment | German municipal organic waste programs create household premium capture for verified biodegradability claims. |
| Direct-to-Consumer Subscription Launch | Automated reorder algorithms tied to air fryer usage frequency reduce customer acquisition costs versus retail. |
| Perforated Geometry Product Line Extension | Laser-cut aperture specifications command price premiums through demonstrable cooking performance differentiation. |
| Nordic Pulp Supply Agreement | Long-term softwood contracts neutralize Brazilian eucalyptus harvest volatility for bleached kraft substrates. |
Research Methodology
Operator-level perspectives from coating equipment engineers, foodservice procurement managers, retail category buyers, and municipal waste program administrators anchored the qualitative base for this study. Primary interview data combined with secondary validation from FDA food-contact substance notifications, EU Framework Regulation EC 1935/2004 compliance databases, BfR silicone migration limit documentation, and California Proposition 65 warning filings. Bottom-up demand modeling across household replenishment cycles and commercial procurement volumes triangulated against top-down market sizing from pulp substrate trade flows and air fryer appliance shipment data.
Scenario-bracketing around regulatory enforcement intensity and silicone coating cost reduction trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tiers, product geometry specifications, end-use application channels, and regional regulatory compliance clusters. CAGRs were derived from appliance ownership penetration curves and replenishment frequency assumptions tied to subscription service adoption patterns. Forecast inputs incorporated pulp futures pricing volatility and coating equipment capital expenditure cycles.
Stress conditions across Nordic pulp supply disruptions, EPA PFAS restriction acceleration timelines, and California chemical disclosure mandate expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding silicone barrier cost parity achievement and municipal compostability program rollout rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Schrenz Paper Market