
 Greaseproof Sheets Market | 2026-2036
Greaseproof Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Greaseproof Sheets Market Foresight
Aftermarket customization revenue is tilting toward value-added coating technologies as buyers specify barrier performance beyond commodity grades. Nordic Paper leverages its integrated pulp-to-paper operations in Scandinavia to sustain cost leadership on unbleached kraft bases. Ahlstrom-Munksjö anchors its position through R&D intensity in fluorochemical-free alternatives, while Mondi Group competes via vertical integration into specialty cellulose sourcing.
Greaseproof sheets are cellulose-based papers engineered with grammages typically ranging from 30 to 60 gsm, treated through mechanical refining or applied coatings to achieve oil and grease resistance coefficients below specified penetration thresholds; their primary purpose is to prevent lipid migration in direct food contact applications while maintaining breathability for moisture control. Silicone-coated paper commands the dominant margin pool due to thermal stability requirements in industrial baking, whereas waxed paper faces structural decline as food safety regulators restrict petroleum-derived contact layers. Plastic-coated paper persists in frozen food segments where moisture vapor transmission rates must stay suppressed, though its growth trajectory flattens against fiber-substitution mandates.
The EU REACH framework and FDA food contact notification requirements govern substance migration limits, while Germany's BfR recommendations and California's Safer Food Packaging and Cookware Act shape permissible chemistry sets across major demand centers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory tightening on forever chemicals will force coating reformulation decisions within the next compliance cycle.
Market Dynamics
Substitution mandates under the EU Single-Use Plastics Directive and California's Safer Food Packaging and Cookware Act are forcing coating chemistry reformulation across the entire supply base, compressing margins for commodity-grade producers while rewarding fluorochemical-free innovators.
Growth Catalysts
- Silicone-coated thermal stability:Industrial bakeries in Germany and France specify these grades for automated high-temperature lines, displacing waxed alternatives that fail above 200°C.
- EU REACH migration limits:Tightened substance restrictions on per- and polyfluoroalkyl substances are accelerating R&D investment in bio-based barrier coatings.
- Premium confectionery demand:Swiss and Belgian chocolate producers command custom-caliber sheets with calibrated breathability for moisture control in luxury packaging.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft prices swing with energy input costs, squeezing integrated producers' margin buffers.
- Scandinavian supply concentration:Nordic Paper and Ahlstrom-Munksjö control critical unbleached kraft capacity, creating bottleneck risk for non-integrated converters.
- Wax coating food safety restrictions:Petroleum-derived contact layers face structural decline as Germany's BfR tightens migration thresholds for mineral oil saturated hydrocarbons.
Strategic Opportunities
- Frozen food segment penetration:Plastic-coated paper retains moisture vapor suppression advantages in ready-meal applications where fiber alternatives underperform.
- EU Green Deal procurement incentives:Public sector food service contracts now mandate compostable packaging, opening institutional volume for certified greaseproof grades.
- Digital print compatibility:Converting equipment upgrades enable short-run customized branding for artisan bakeries, merging functional and marketing value.
Industry Challenges
- Fluorochemical-free coating scale-up:Lab-validated alternatives stumble in continuous coating line trials, delaying commercial rollout timelines.
- Multi-jurisdiction compliance synchronization:FDA food contact notifications, EU REACH registrations, and state-level US restrictions create divergent certification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greaseproof Sheets Market |
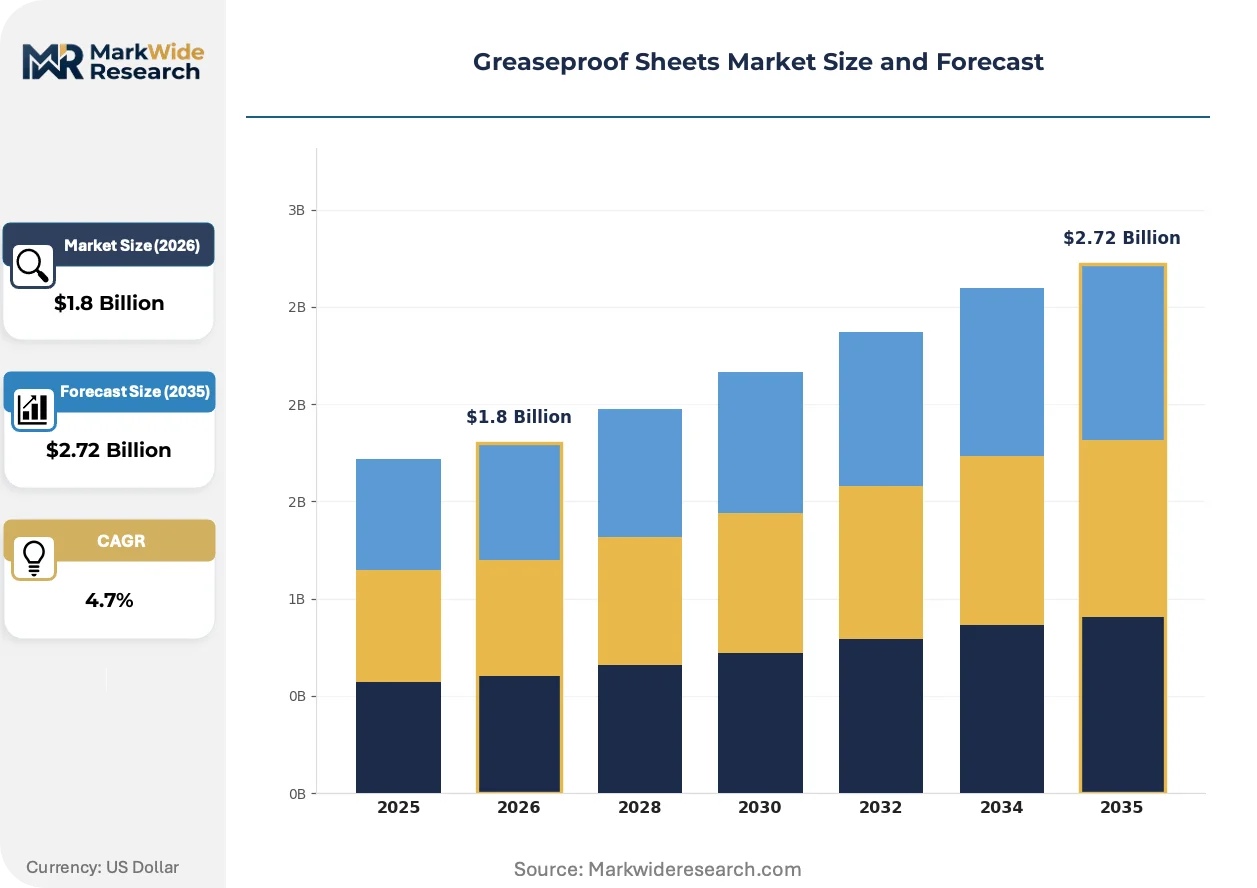
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waxed Paper, Plastic Coated Paper, Silicone Coated Paper, Others End User: Food Industry, Packaging Industry, Bakery, Catering Services Thickness: Lightweight, Medium, Heavyweight, Extra Heavyweight Packaging Type: Rolls, Sheets, Bags, Custom Shapes |
| Companies Covered | Mondi Group, Nordic Paper, Ahlstrom-Munksjö, SCG Packaging, Delfort Group, WestRock, Metsä Tissue, Domtar, Pudumjee Paper Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greaseproof Sheets Market Shifts & Advancements
Barrier coating chemistry is undergoing forced renovation as legacy fluorochemical formulations face coordinated regulatory phase-out across North America and Europe, while demand-side specification tightens around compostability certifications.
Fluorochemical-free greaseproof technology is migrating from laboratory validation to commercial coating lines. Industrial bakeries in Germany and France pilot these alternatives at constrained throughput rates. The shift is compressing margin pools for incumbent coating suppliers locked into per- and polyfluoroalkyl substance chemistries.
California's Safer Food Packaging and Cookware Act prohibits intentionally added per- and polyfluoroalkyl substances in food contact materials starting January 2027. Manufacturers serving the US West Coast market must complete coating reformulation and migration testing cycles. Frozen food packagers face particular pressure given plastic-coated paper's incumbent position in moisture-sensitive applications.
Specification authority is consolidating into centralized procurement functions at bakery chains and food service distributors. Regional paper converters lose direct specification influence as buyers demand pan-European or national contract consistency. This concentration is most visible in Germany, where industrial bakeries negotiate multi-year supply agreements directly with integrated pulp-to-paper producers.
Greaseproof Sheets Market Segmentation
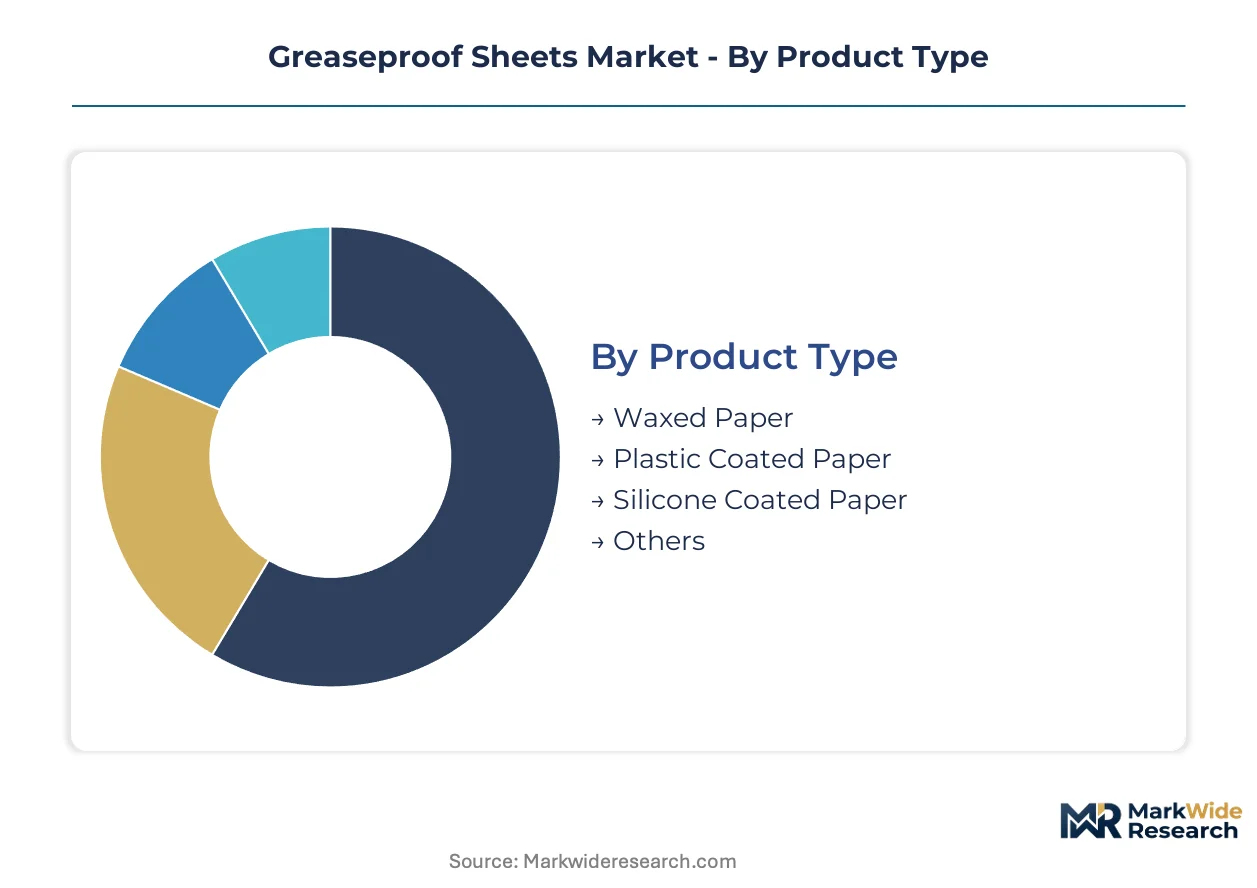
Greaseproof sheet specifications diverge sharply across end-use temperature demands and regulatory exposure, creating distinct margin pools that reward coating chemistry specialization over commodity volume plays.
Product Type:
Silicone-coated grades turn inventory fastest in industrial bakery channels, while waxed alternatives face extended replacement cycles as buyers stretch existing stocks amid regulatory uncertainty.
- Silicone Coated Paper:Engineered with thermal stability exceeding 220°C for automated baking lines. German industrial bakeries specify these grades exclusively for high-throughput production, displacing waxed alternatives that carbonize at elevated temperatures.
- Waxed Paper:Petroleum-derived paraffin coatings face structural decline under Germany's BfR mineral oil saturated hydrocarbon restrictions. Demand concentrates in legacy confectionery wrapping where cost sensitivity outweighs thermal performance requirements.
- Plastic Coated Paper:Polyethylene barriers retain moisture vapor suppression advantages in frozen ready-meal segments where fiber alternatives underperform on water transmission rates.
- Others:Bio-based barrier coatings including polysaccharide and protein-derived formulations remain pre-commercial, with pilot volumes concentrated in Swiss premium chocolate packaging trials.
Silicone-coated paper anchors the volume base while bio-based alternatives gain share at the steepest rate.
End User:
Application economics separate high-specification buyers with centralized procurement functions from fragmented regional converters serving artisan accounts.
- Food Industry:Frozen food packagers drive specification consolidation through national contract structures, demanding plastic-coated moisture barriers for extended shelf-life applications.
- Bakery:Industrial chains in France and Germany negotiate multi-year supply agreements directly with integrated pulp-to-paper producers, bypassing regional converters on silicone-coated thermal grades.
- Packaging Industry:Converters serving artisan bakeries face margin compression as digital print compatibility requirements force equipment upgrade cycles for short-run customization.
- Catering Services:Institutional food service procurement under EU Green Deal mandates specifies compostable greaseproof grades for public sector contracts.
Bakery demand anchors the volume base while catering services gain share at the steepest rate.
Thickness:
Grammage selection maps directly to barrier performance requirements and unit economics, with heavier grades commanding premium positioning in export-sensitive applications.
- Medium:40-50 gsm specifications balance oil resistance with cost efficiency for standard bakery applications across European retail channels.
- Heavyweight:50-60 gsm grades serve premium confectionery in Belgium and Switzerland where calibrated breathability prevents chocolate bloom while blocking grease migration.
- Lightweight:30-40 gsm variants target cost-optimized fast-food wrapping with reduced barrier tolerance for single-use disposal.
- Extra Heavyweight:Above 60 gsm specifications address specialized industrial frying applications requiring extended thermal exposure resistance.
Medium thickness anchors the volume base while heavyweight grades gain share at the steepest rate.
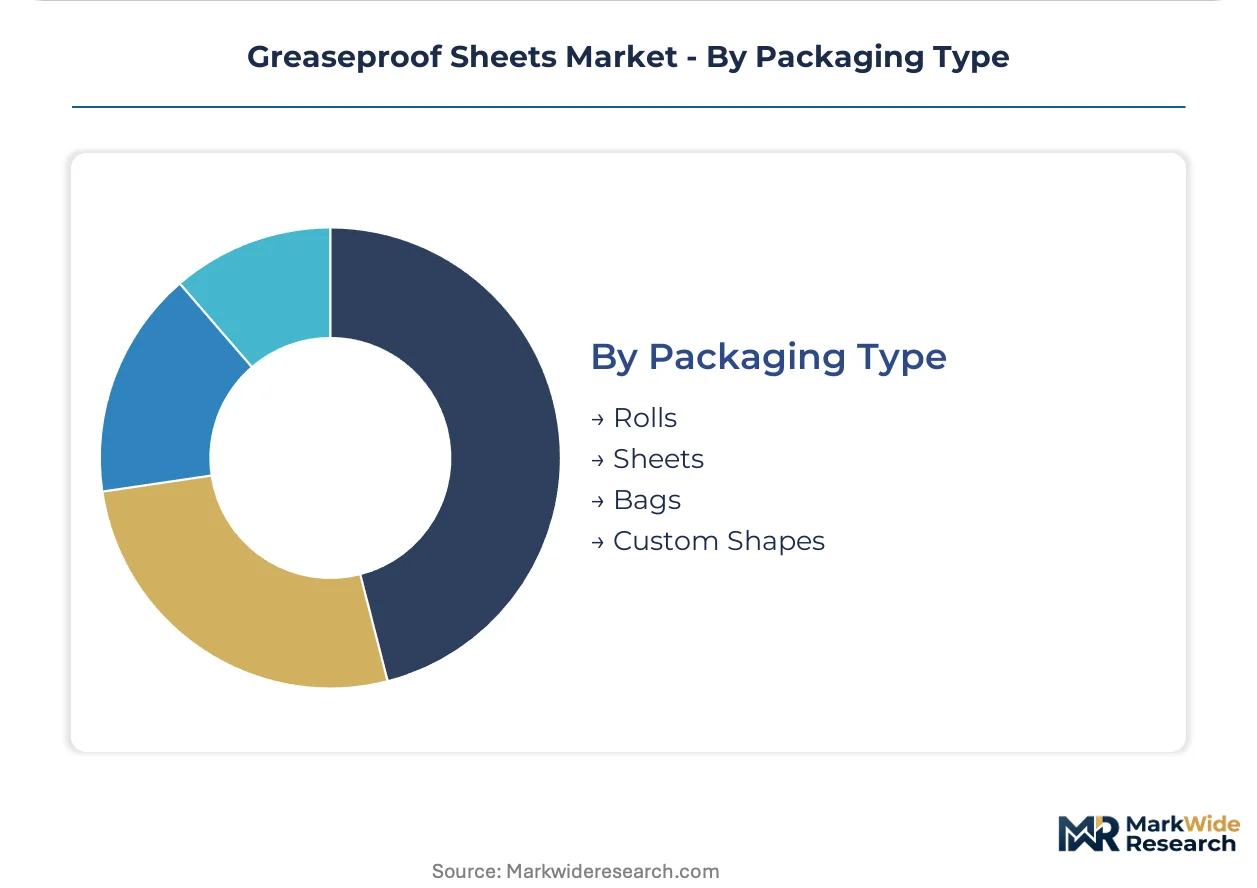
Packaging Type:
Format selection reflects automation compatibility and branding flexibility trade-offs across industrial and artisan production scales.
- Sheets:Pre-cut dimensions dominate industrial bakery automation, with German producers specifying custom calipers for automated line feeding.
- Rolls:Continuous formats serve high-volume converters with in-house cutting capabilities, optimizing material yield for standardized product runs.
- Bags:Pre-formed greaseproof pouches address ready-to-eat snack packaging where consumer convenience commands format premium.
- Custom Shapes:Die-cut configurations enable brand differentiation for artisan bakeries leveraging digital print compatibility for short-run seasonal campaigns.
Rolls anchor the volume base while custom shapes gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes greaseproof sheets differently than other markets, with industrial bakeries demanding thermal-grade silicone coatings while Swiss chocolate houses prioritize breathability-calibrated heavyweight grades for luxury applications.
Germany
Industrial bakery chains in Bavaria and North Rhine-Westphalia specify silicone-coated grades exceeding 220°C thermal stability for automated production lines. The Federal Institute for Risk Assessment tightens mineral oil saturated hydrocarbon thresholds for waxed paper contact layers. Düsseldorf-based procurement consortia negotiate multi-year supply agreements directly with integrated pulp-to-paper producers.
United States
California's frozen food packagers drive plastic-coated paper demand for moisture vapor suppression in ready-meal applications. The Safer Food Packaging and Cookware Act prohibits intentionally added per- and polyfluoroalkyl substances from January 2027. Chicago-area converting facilities pilot fluorochemical-free alternatives for national bakery chain contracts.
Switzerland
Premium confectionery producers in Zurich and Geneva command custom-caliber heavyweight sheets with calibrated breathability to prevent chocolate bloom. Swissmedic maintains alignment with EU REACH migration limits for food contact materials. Basel-area packaging innovators trial bio-based polysaccharide barriers for artisan chocolate exports.
France
Industrial bakeries in Île-de-France and Auvergne-Rhône-Alpes displace waxed alternatives with silicone-coated grades for high-throughput croissant and pastry production. EU Single-Use Plastics Directive implementation accelerates fiber-based substitution mandates. Lyon-based food service distributors consolidate procurement for pan-European contract consistency.
Sweden
Nordic integrated pulp-to-paper operations sustain cost leadership on unbleached kraft bases for export markets. The EU Green Deal procurement incentives mandate compostable packaging for public sector food service contracts. Gothenburg-area producers expand fluorochemical-free coating capacity for German and French industrial bakery supply.
Greaseproof Sheets Market Competitive Landscape
Capability concentration sits with integrated pulp-to-paper specialists; scale advantage sits with diversified packaging conglomerates with global converting networks. The vendor base separates into three strategic archetypes: Scandinavian integrated producers controlling unbleached kraft supply, European specialty paper houses with fluorochemical-free R&D pipelines, and North American diversified packaging groups with continental distribution density. Dominant competitive moves include backward integration into specialty cellulose sourcing and strategic partnerships for bio-based barrier coating commercialization.
Among Scandinavian integrated producers, Nordic Paper and Ahlstrom-Munksjö occupy positions exemplifying captive pulp supply advantages and fluorochemical-free innovation focus respectively. Mondi Group represents the diversified packaging archetype with upstream control over specialty cellulose sourcing. These three entities anchor the competitive structure, with Nordic Paper leveraging geographic concentration in Scandinavian kraft capacity, Ahlstrom-Munksjö sitting within the regulatory-driven innovation tier, and Mondi Group exemplifying scale-driven continental coverage.
| Leading Market Players |
|---|
| Mondi Group |
| Nordic Paper |
| Ahlstrom-Munksjö |
| SCG Packaging |
| Delfort Group |
| WestRock |
| Metsä Tissue |
| Domtar |
| Pudumjee Paper Products |
| Others |
Supply & Pricing Matrix
Scandinavian unbleached kraft pulp clusters around Gothenburg and Kvarnsveden anchor cost structures for integrated producers, translating captive fiber supply into pricing leverage over non-integrated converters dependent on spot market purchases. German industrial bakeries exploit this concentration through multi-year offtake agreements that lock in volume discounts unavailable to fragmented artisan accounts.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated pulp-to-paper producers and German industrial bakery chains, while spot transactions serve fragmented regional converters with volatile exposure to Northern bleached softwood kraft price swings. Pricing stratifies across silicone-coated thermal grades, waxed legacy stocks, and plastic-coated moisture barriers based on certification tier and volume scale. Cost compression in waxed paper intensifies as Germany's BfR tightens mineral oil saturated hydrocarbon thresholds, forcing distressed inventory liquidation. Artisan bakeries exhibit highest price sensitivity due to thin margin buffers, whereas Swiss premium confectionery producers accept substantial premiums for calibrated breathability specifications.
Supply Chain Analysis
EU REACH substance restrictions on per- and polyfluoroalkyl substances limit coating chemistry flows from non-compliant suppliers, reshaping qualified vendor pools across the continent. Production concentrates in Sweden, Finland, and Germany, where integrated operations control unbleached kraft pulp supply, specialty cellulose refining, and fluorochemical-free coating development. Raw material dependencies rest on softwood pulp, silicone emulsions, and bio-based barrier polymers. Single-source vulnerability concentrates in Scandinavian kraft capacity controlled by Nordic Paper and Ahlstrom-Munksjö. Distribution runs through converting facilities in Düsseldorf, Lyon, and Chicago that serve pan-regional bakery chain contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greaseproof sheets sit in early-cycle expansion as EU Single-Use Plastics Directive substitution mandates accelerate fiber-based packaging penetration across frozen food and institutional catering segments previously locked into plastic-coated alternatives.
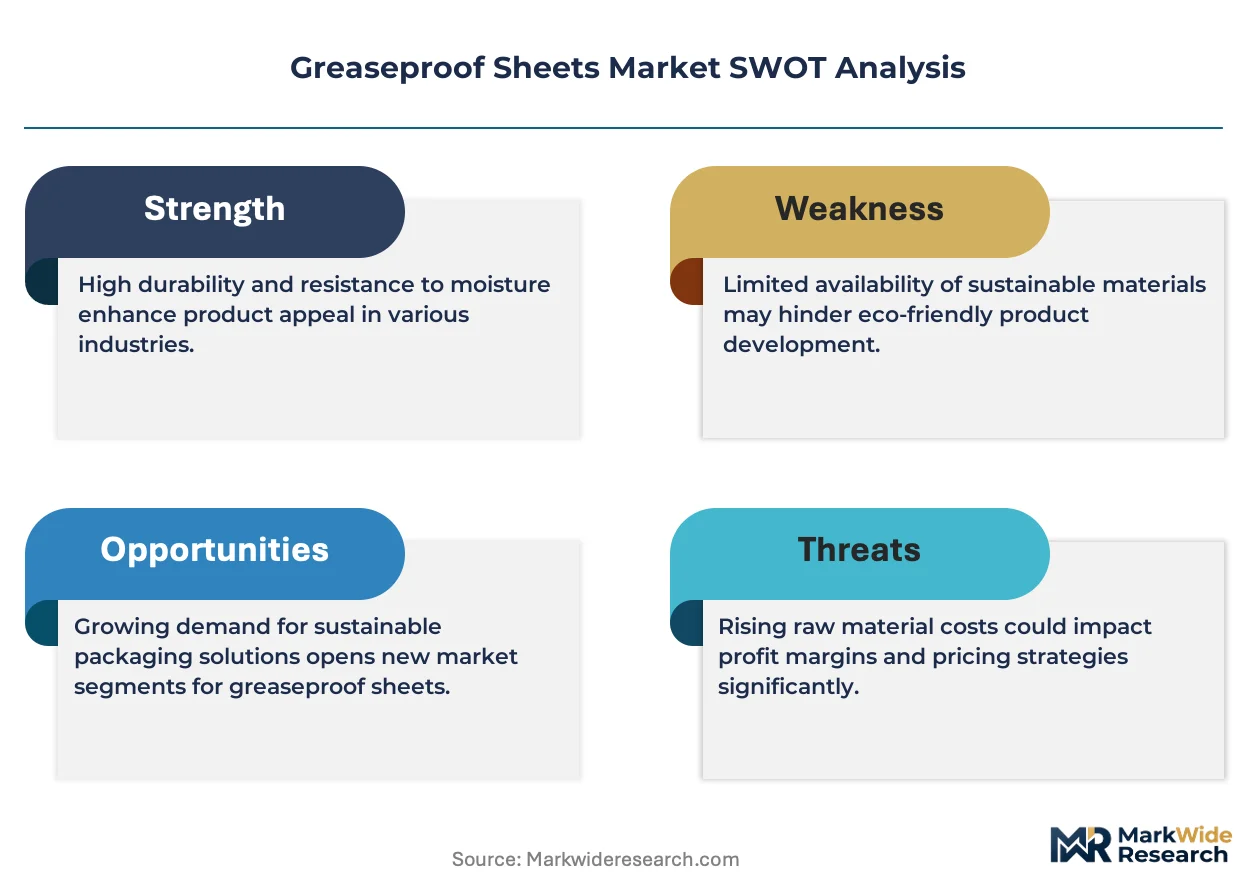
For Market Incumbents: Insulate margin pools by deepening captive pulp supply through backward integration into Scandinavian softwood holdings, while accelerating fluorochemical-free coating scale-up before California's Safer Food Packaging and Cookware Act prohibition takes effect. Priority certification investment in EU Green Deal compostability standards will defend position against emerging bio-based barrier specialists. For New Entrants and Emerging Players: Build out digital print-compatible converting capacity serving artisan bakery short-run customization, where specification authority remains fragmented and equipment upgrade cycles create service gaps. Target Swiss premium chocolate packaging trials for polysaccharide barrier validation, leveraging Basel-area innovation clusters for technical credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated pulp-to-paper specialists with fluorochemical-free R&D pipelines over diversified packaging conglomerates with legacy coating chemistries. Five-to-ten year viability hinges on coating reformulation execution rather than volume scale. The signal to watch is pilot line throughput rates for bio-based barriers at German industrial bakery facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorochemical-Free Coating Scale-Up | EU REACH and California Safer Food Packaging Act compliance separates qualified suppliers from stranded asset risk. |
| Backward Integration into Specialty Cellulose | Mondi Group's upstream control over dissolving pulp secures cost advantage in silicone-coated thermal grades. |
| Digital Print Compatibility Investment | Short-run customization capability merges functional and marketing value for artisan bakery accounts. |
| EU Green Deal Certification Program | Compostable packaging mandates open institutional catering volume in Sweden and Germany. |
| Long-Term Supply Agreement Structuring | Düsseldorf procurement consortia lock in multi-year volume commitments with integrated producers. |
Research Methodology
Desk research of trade association publications, customs records, and regulatory filings preceded structured interviews with plant managers at integrated pulp-to-paper operations, procurement leads at German industrial bakery chains, technical R&D directors at coating suppliers, and category buyers at European food service distributors. Secondary validation drew from EU REACH registration databases, FDA food contact notifications, BfR recommendation updates, and SEC filings from listed packaging conglomerates. Bottom-up volume estimates triangulated against top-down market sizing from pulp consumption and converting capacity data.
Assumptions around EU Single-Use Plastics Directive implementation timelines and per- and polyfluoroalkyl substance regulatory phase-out schedules were held fixed across the analysis window, while pulp cost volatility and coating technology adoption curves were stress-tested through sensitivity scenarios. Segmentation modeling covered product type, end-use application, grammage tier, and packaging format dimensions. CAGRs were derived from trend extrapolation validated against historical substitution elasticities in comparable fiber-based packaging transitions. Forecast inputs included industrial bakery automation rates and frozen food packager specification consolidation patterns.
Stress conditions across pulp price bands, regulatory enforcement intensity, and bio-based barrier commercialization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and boundary conditions. Material shifts in EU per- and polyfluoroalkyl substance restriction scope or California enforcement timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
Finish Foils Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Strip Pack Laminates Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Postal Packaging Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Nigeria Packaging Market
Packaging Materials
Desiccant Market
Packaging Materials
Direct Thermal Printing Films Market