
 Morocco Plastic Bottles Market | 2026-2036
Morocco Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Plastic Bottles Market Insights
Asset-light leasing arrangements for blow-molding equipment is reshaping competitive entry in Morocco's plastic bottles sector, allowing mid-tier converters to scale without heavy capital commitments. Plastipak Holdings Inc. leverages its preform-to-bottle technology platform to serve multinational beverage accounts from Moroccan production nodes. MUTANDIS.com anchors domestic supply through its integrated recycling and conversion footprint near Casablanca. Sumilon Eco PET SARL differentiates on rPET content, positioning its output for brands facing tightening circularity requirements.
Plastic bottles are hollow containers formed through extrusion or injection blow-molding of thermoplastic resins, typically PET or HDPE, with wall thickness calibrated for carbonation retention, drop resistance, or chemical compatibility. These vessels store, transport, and dispense liquids and semi-solids across consumer and industrial supply chains. PET bottles dominate beverage applications due to clarity, barrier performance, and established collection infrastructure, while HDPE bottles capture personal care and pharmaceutical end uses where chemical resistance matters more than optical properties. Small bottles generate the highest unit volumes in cosmetics and pharmaceutical sampling, whereas bulk containers command premium margins in food packaging for institutional buyers.
Morocco's Ministry of Energy Transition and Sustainable Development enforces packaging waste directives aligned with extended producer responsibility principles, compelling converters to document recycled content shares. BIS-equivalent Moroccan standards bodies certify food-contact material safety, while EU REACH compliance remains mandatory for bottles exported to European trading partners. Stakeholders must monitor how domestic recycling capacity expansion and incoming EPR enforcement timelines alter raw material sourcing economics and customer qualification requirements.
Market Dynamics
Extended producer responsibility frameworks from Morocco's Ministry of Energy Transition and Sustainable Development are compelling converters to reconfigure material sourcing and document recycled content shares, while beverage bottlers in Casablanca and Agadir accelerate lightweight PET adoption to meet circularity obligations.
Growth Catalysts
- EPR Compliance Mandates:Morocco's packaging waste directives force brand owners to contract converters with verified rPET supply chains, pulling investment toward recycling infrastructure near Casablanca-Settat.
- Mineral Water Plant Clustering:Soft drink and bottled water producers concentrate in the Casablanca-Settat industrial corridor, creating captive demand for local blow-molding capacity and reducing logistics costs for converters.
- Preform-to-Bottle Technology:Integrated preform injection and blow-molding systems cut cycle times and material waste, allowing mid-tier converters to qualify for multinational beverage accounts previously served by imports.
Market Restraints
- rPET Feedstock Scarcity:Domestic bottle-to-bottle recycling capacity remains insufficient to meet EPR-mandated recycled content thresholds, forcing converters to import flakes at premium prices or risk non-compliance.
- Resin Price Volatility:PET and HDPE pellet costs track MEG and PTA feedstock fluctuations from Asian suppliers, compressing converter margins when crude oil derivatives spike.
- Glass Bottle Resurgence:Premium mineral water brands in Agadir and Marrakech reposition glass as a circular alternative, capturing shelf space in hospitality channels where plastic faces aesthetic and regulatory stigma.
Strategic Opportunities
- Tangier-Tetouan-Al Hoceima Expansion:Underpenetrated northern Morocco lacks local blow-molding capacity despite growing beverage distribution to Spain and EU markets via Tangier Med port.
- Pharmaceutical Blow-Fill-Seal:Sterile liquid packaging for vaccines and biologics remains import-dependent, creating white space for converters achieving ISO 15378 certification and cleanroom standards.
- Green Hydrogen-Driven Recycling:Morocco's renewable energy investments could power pyrolysis-based chemical recycling, enabling food-grade rPET production beyond mechanical recycling limitations.
Industry Challenges
- Blow-Molding Technician Shortage:Skilled operators for multi-cavity PET stretch-blow equipment are scarce in Moroccan technical institutes, forcing converters to train in-house or recruit from Tunisian and Algerian talent pools.
- Food-Contact Certification Timelines:BIS-equivalent Moroccan standards bodies lack parallel review pathways, delaying new resin approvals by 12-18 months and freezing product development cycles.
- Legacy Equipment Integration:Converters leasing second-hand European blow-molding lines face compatibility gaps with modern preform designs and IoT-enabled quality monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Plastic Bottles Market |
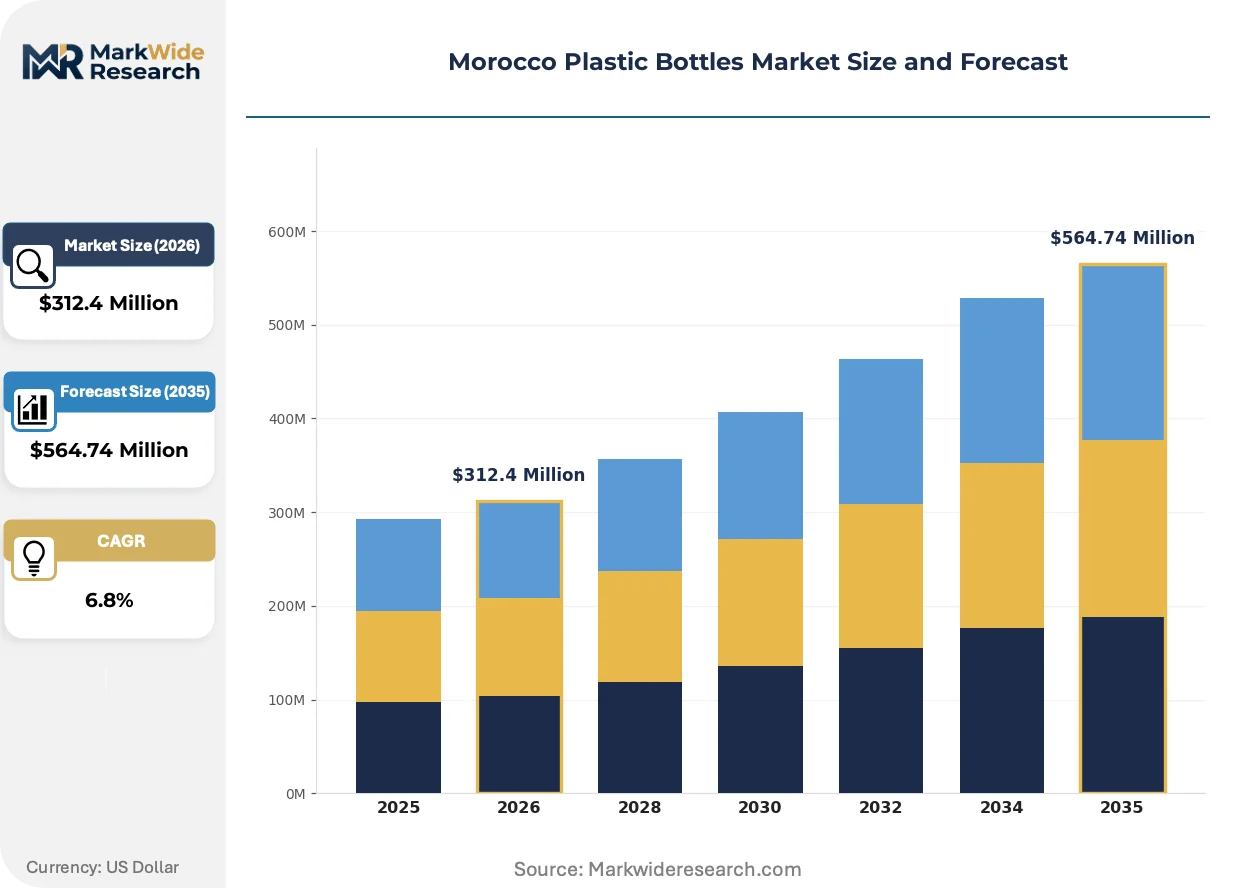
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Bottles, PVC Bottles, LDPE Bottles End User: Beverage Industry, Cosmetics, Pharmaceuticals, Food Packaging Size: Small Bottles, Medium Bottles, Large Bottles, Bulk Containers Design Type: Standard Design, Custom Design, Squeeze Bottles, Trigger Spray Bottles |
| Companies Covered | Alpla Group, Plastipak Holdings Inc., Bericap Holding GmbH, MUTANDIS.com, Blowtec Morocco, Pet Preforms Morocco, Sumilon Eco PET SARL, Intel Plast, Attaghlif, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Plastic Bottles Market Trends and Innovations
Material science advances and regulatory tightening are converging to redefine competitive advantage in Moroccan plastic packaging, with converters racing to deploy lighter structures and verified circular content before EPR enforcement hardens.
Mono-material PET bottle designs incorporating tethered caps and full-body sleeve labels are hybridizing conventional beverage packaging with circular-economy specifications. Multinational soft drink bottlers in Casablanca specify these structures for 2025 production runs. The shift compresses sorting complexity at Moroccan material recovery facilities while enabling higher-purity flake output.
Morocco's Ministry of Energy Transition and Sustainable Development is aligning national packaging waste directives with EU extended producer responsibility principles. Industrial consequence includes mandatory recycled content reporting and eco-modulated fees favoring lighter bottles. Small converters in Agadir face disproportionate compliance costs versus integrated players with captive recycling operations.
Brand owners are consolidating procurement around converters offering certified mass-balance rPET and blockchain-tracked provenance documentation. Hospitality and retail channels in Marrakech and Rabat now require batch-level recycled content certificates. This specification creep disadvantages asset-light leasing models lacking in-house laboratory verification capabilities.
Morocco Plastic Bottles Market Segmentation
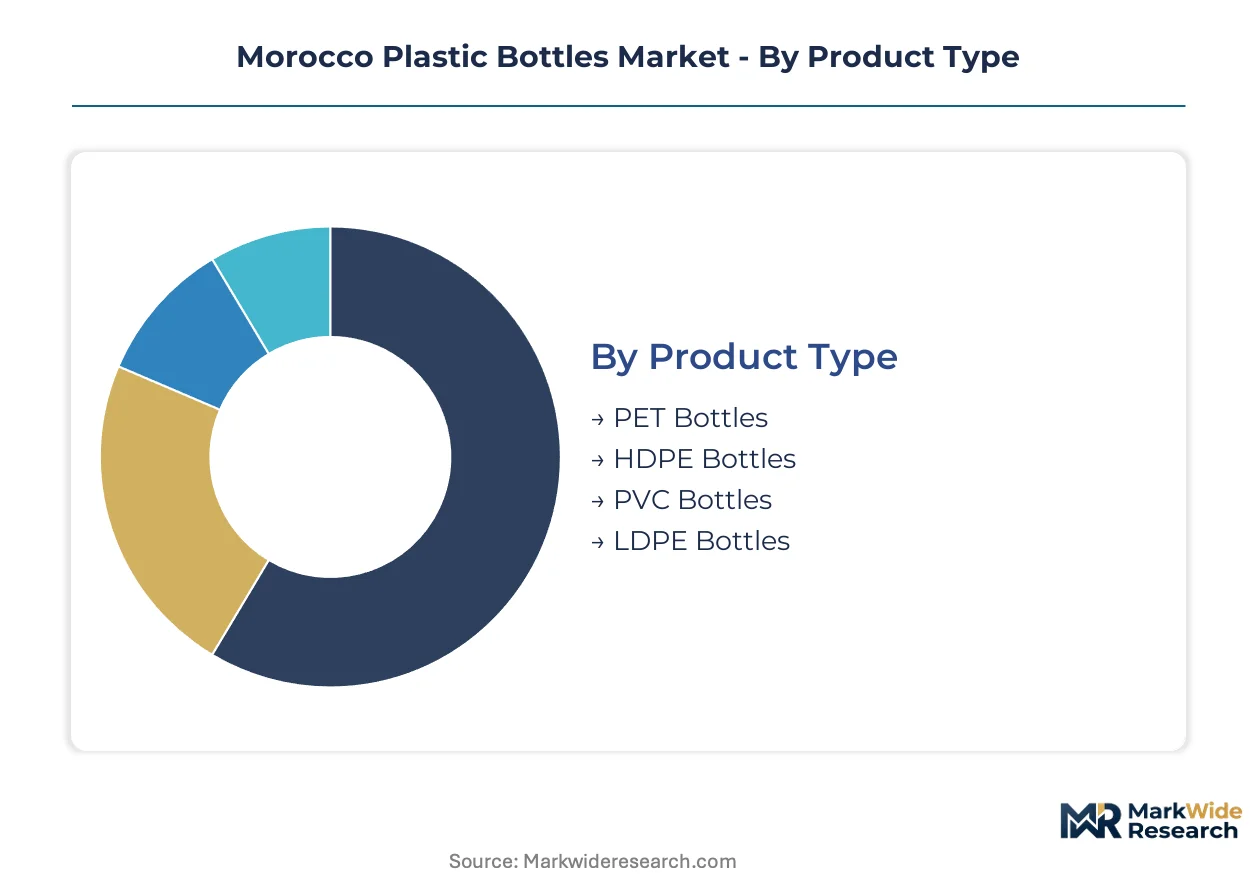
Morocco's plastic bottles market fragments across material chemistry, end-use specifications, and dimensional requirements. Each segmentation axis carries distinct margin profiles and regulatory exposure, shaping converter investment priorities and customer qualification pathways.
Product Type:
Material chemistry determines barrier performance, recyclability credentials, and compliance pathways for Moroccan converters serving EU export markets.
- PET Bottles:Amorphous polyethylene terephthalate delivers clarity and carbonation retention for beverage applications. Casablanca-Settat bottlers specify lightweight PET structures to meet EPR-mandated weight reduction targets while maintaining drop resistance.
- HDPE Bottles:High-density polyethylene offers chemical resistance for personal care and pharmaceutical liquids. Agadir converters favor HDPE for shampoo and disinfectant lines where opacity and stress-crack resistance outweigh optical requirements.
- PVC Bottles:Polyvinyl chloride captures niche industrial chemical packaging despite declining food-contact approvals. Moroccan pharmaceutical formulators specify PVC for certain solvent-based products.
- LDPE Bottles:Low-density polyethylene serves squeeze applications and flexible dispensing formats. Marrakech cosmetic brands specify LDPE for travel-size personal care lines.
PET holds installed capacity. HDPE is rotating up the share rankings.
End User:
Application-specific performance standards and certification requirements segment converter capabilities across Morocco's industrial corridors.
- Beverage Industry:Carbonated soft drink and mineral water bottlers in Casablanca and Agadir drive volume demand. EPR compliance mandates now require verified rPET content documentation from converters serving Coca-Cola and Sidi Ali accounts.
- Cosmetics:Premium skincare and fragrance brands in Marrakech specify custom-molded bottles with decorative finishing. Sumilon Eco PET SARL positions its recycled-content output for hotel amenity channels.
- Pharmaceuticals:Sterile liquid packaging for vaccines and biologics remains import-dependent. ISO 15378 certification gaps constrain domestic blow-fill-seal capacity expansion.
- Food Packaging:Edible oils and condiment producers specify oxygen barrier structures. BIS-equivalent Moroccan standards bodies certify food-contact safety for converters supplying Lesieur and local olive oil cooperatives.
Beverage commands volume concentration. Pharmaceuticals offers the steepest expansion trajectory for certified domestic suppliers.
Size:
Dimensional segmentation aligns with logistics economics, retail channel requirements, and consumption occasion patterns across Moroccan distribution networks.
- Small Bottles:Sub-100ml formats dominate pharmaceutical sampling and cosmetic travel retail. Casablanca converters run dedicated high-cavity molds for airline amenity and hotel vanity channel supply.
- Medium Bottles:250-500ml structures capture standard beverage and personal care applications. Lightweighting initiatives concentrate on this size band for EPR weight-reduction credits.
- Large Bottles:1-2 liter household formats serve cooking oil and cleaning product markets. Agadir packaging lines favor large bottles for institutional food service contracts.
- Bulk Containers:5-20 liter jerrycans and carboys command premium margins in food ingredients and industrial chemicals. Tangier-Tetouan converters target bulk formats for export logistics to Spanish distributors.
Medium bottles anchor production volume. Small bottles are climbing the fastest on unit growth.
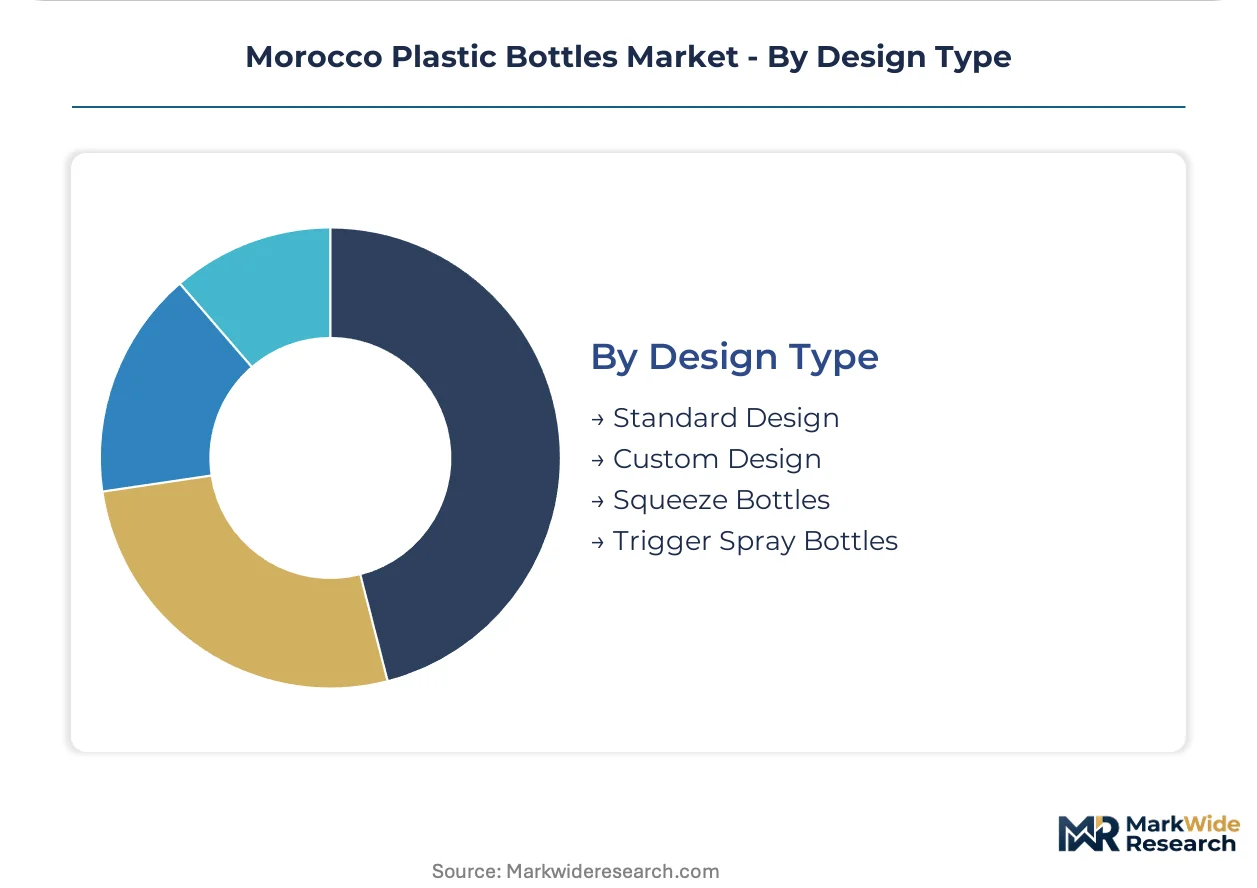
Design Type:
Structural complexity and functional mechanisms differentiate converter tooling investments and customer switching costs.
- Standard Design:Conventional cylindrical or oval profiles with screw-cap closure dominate commodity beverage and personal care. Casablanca-Settat converters amortize standard mold investments across high-volume multinational accounts.
- Custom Design:Proprietary shoulder geometry and embossed branding elements serve premium cosmetic and gift markets. Marrakech fragrance houses commission custom molds with 18-24 month exclusivity terms.
- Squeeze Bottles:Flexible sidewall structures with flip-top or disc-top closures serve condiment and personal care dispensing. LDPE squeeze formats capture honey and argan oil niche applications.
- Trigger Spray Bottles:Integrated dip-tube and trigger mechanism assemblies for cleaning and garden products. Moroccan converters import trigger hardware from Spanish suppliers, constraining margin capture on finished assemblies.
Standard design maintains share leadership. Custom design is gaining share fastest among export-oriented cosmetic brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's plastic bottles trade balance tilts toward import dependency for high-performance resins and specialized blow-molding equipment, while finished bottle exports to West African markets and European Union duty-free zones expand through Tangier Med port infrastructure.
Casablanca-Settat
Soft drink and mineral water bottlers cluster along the Casablanca-Settat industrial corridor, generating captive demand for PET preform and bottle conversion. Morocco's Ministry of Energy Transition and Sustainable Development enforces packaging waste directives that compel local converters to document recycled content shares. Mohammedia and Nouaceur host the densest concentration of blow-molding facilities, where Plastipak Holdings Inc. operates production nodes serving multinational beverage accounts.
Tangier-Tetouan-Al Hoceima
Underpenetrated northern Morocco lacks sufficient local blow-molding capacity despite accelerating beverage distribution to Spain and EU markets. The region benefits from Tangier Med port logistics infrastructure and renewable energy investments that could power future recycling operations. Tetouan converters target bulk container formats for cross-border supply to Spanish distributors, capitalizing on proximity advantages and preferential trade agreements.
Marrakech-Safi
Premium mineral water brands and hospitality channels in Marrakech reposition glass as a circular alternative, capturing shelf space where plastic faces aesthetic stigma. Sumilon Eco PET SARL positions its recycled-content output for hotel amenity and cosmetic sampling applications. Chichaoua and Safi sub-regions show emerging demand for custom-molded cosmetic bottles serving fragrance export markets.
Agadir-Rabat Corridor
Beverage bottlers in Agadir accelerate lightweight PET adoption to meet circularity obligations, while Rabat-based pharmaceutical formulators drive demand for chemical-resistant HDPE packaging. The Agadir industrial zone attracts converters serving both domestic edible oil cooperatives and European organic food exporters. Skilled operator shortages persist across this southern stretch, forcing training investments or cross-border recruitment from Algerian technical institutes.
Morocco Plastic Bottles Market Competitive Landscape
On the supply side, the industry is consolidating around integrated preform-to-bottle technology platforms and captive recycling operations, with mid-tier converters leveraging asset-light equipment leasing to qualify for multinational accounts previously served by imports. Three strategic archetypes dominate: multinational technology licensors with regional production nodes, domestic integrated recyclers with backward material recovery control, and specialized recyclers positioning on certified circular content. Competitive intensity concentrates on preform injection efficiency, rPET verification capabilities, and EPR compliance documentation systems.
Within the multinational technology tier, Plastipak Holdings Inc. and Alpla Group exemplify preform-to-bottle platform operators serving beverage accounts from Moroccan production nodes. MUTANDIS.com anchors domestic supply through its integrated recycling and conversion footprint near Casablanca. Sumilon Eco PET SARL occupies a differentiated position on mass-balance rPET certification, targeting brand owners facing tightening circularity requirements in hospitality and retail channels.
| Leading Market Players |
|---|
| Alpla Group |
| Plastipak Holdings Inc. |
| Bericap Holding GmbH |
| MUTANDIS.com |
| Blowtec Morocco |
| Pet Preforms Morocco |
| Sumilon Eco PET SARL |
| Intel Plast |
| Attaghlif |
| Others |
Pricing and Supply Chain Analysis
Tangier Med port freight corridors govern landed cost dynamics for PET resin imports, concentrating pricing power among Casablanca-Settat converters with backward integration into preform injection while forcing asset-light competitors to absorb volatile MEG and PTA feedstock swings.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on rPET certification grade and volume scale. Cost compression in standard-grade PET bottles is intensifying because beverage bottlers demand documented circularity credentials. Small Agadir converters exhibit highest price sensitivity due to thin margins and import-dependent flake sourcing, while integrated players with captive recycling operations command premium positioning.
Supply Chain Analysis
Tariff exposure between Morocco and EU trading partners dominates supply chain risk calculus, though preferential trade agreements mitigate duty burdens on finished bottle exports. Raw material sourcing draws from Saudi Arabia, Qatar, and Spain for virgin PET resin, with mechanical recycling feedstock resting on domestic collection infrastructure near Casablanca. Single-source vulnerability persists in preform mold tooling from German and Italian suppliers. Distribution runs through Tangier Med port for EU-bound bulk containers and overland trucking networks for domestic beverage corridor supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Morocco plastic bottles market rewards converters possessing in-house rPET verification laboratories and EPR compliance documentation systems, while penalizing asset-light models lacking material recovery control.
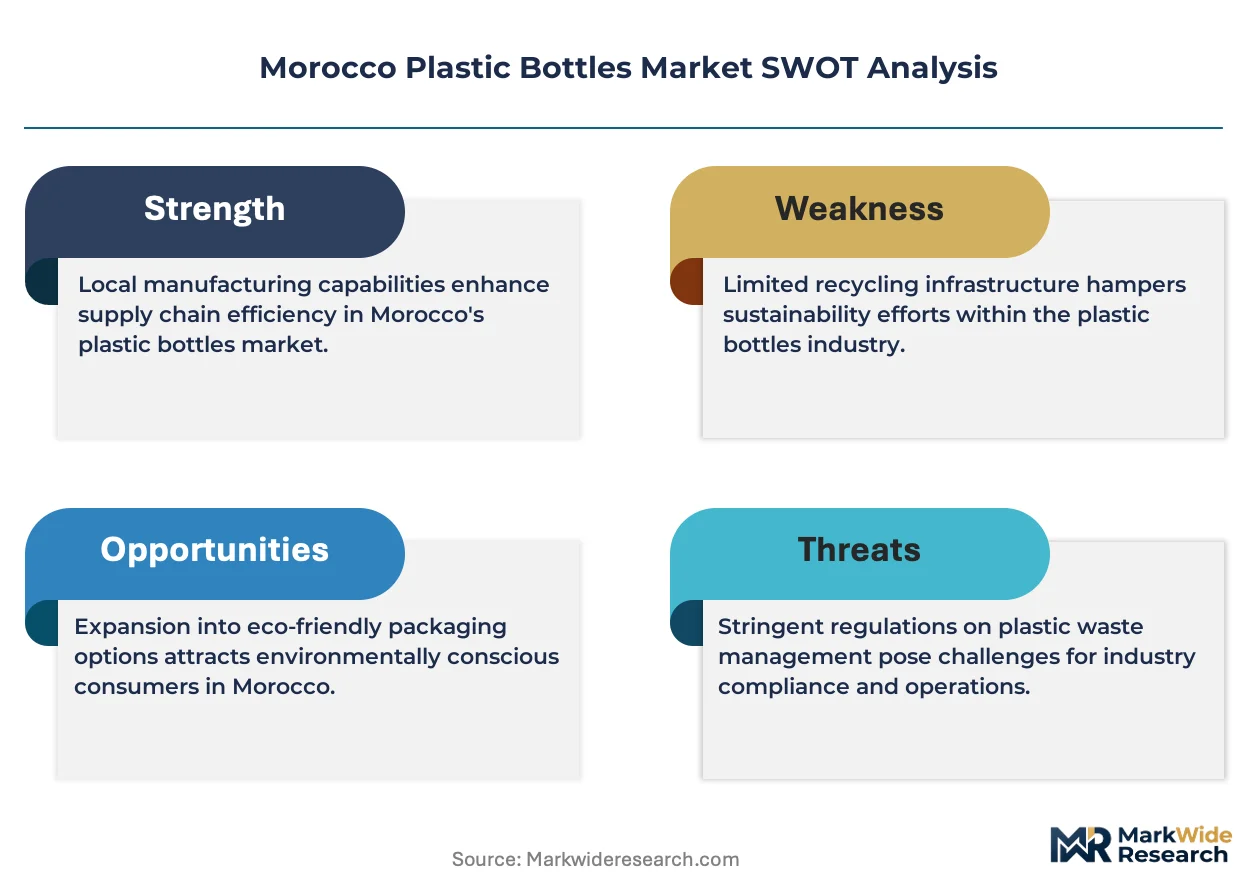
For Market Incumbents: Insulate market position by deepening backward integration into bottle-to-bottle recycling infrastructure near Mohammedia, countering feedstock scarcity threats. Secure ISO 15378 certification pathways for pharmaceutical blow-fill-seal expansion, locking out import-dependent competitors from sterile liquid packaging growth. For New Entrants and Emerging Players: Pursue Tangier-Tetouan-Al Hoceima geographic white space, where underpenetrated northern Morocco lacks local blow-molding capacity despite accelerating EU export demand. Target bulk container formats for cross-border Spanish distributor supply, leveraging proximity advantages and Tangier Med logistics infrastructure as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from European multinational packaging parents seeking to monetize non-core Moroccan production nodes. Five-to-ten year viability hinges on EPR enforcement trajectory and domestic recycling capacity buildout. Monitor Morocco's Ministry of Energy Transition implementation timelines as the critical inflection signal for recycled content mandate stringency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Recycling | Captive feedstock supply secures EPR compliance for Coca-Cola and Sidi Ali accounts. |
| ISO 15378 Certification Investment | Pharmaceutical sterile packaging qualification opens import-dependent vaccine and biologics segments. |
| Tangier-Tetouan Capacity Expansion | Proximity to Tangier Med port captures EU-bound bulk container export growth. |
| Preform-to-Bottle Technology Upgrade | Integrated injection-blow systems cut cycle times for multinational beverage account qualification. |
| Blockchain-Tracked Provenance Documentation | Batch-level recycled content certificates satisfy Marrakech hospitality channel specifications. |
Research Methodology
The analysis maps PET bottle, HDPE container, and pharmaceutical packaging sub-sectors, each validated through blow-molding plant managers, beverage procurement leads at Sidi Ali and Coca-Cola bottlers, recycling facility operators, and Ministry of Energy Transition officials. Primary interview findings triangulate against customs trade records, BIS-equivalent Moroccan standards body filings, EU REACH compliance databases, and SEC disclosures from multinational packaging parents. Bottom-up capacity installations and top-down demand modeling converge through iterative stakeholder verification.
Assumptions held fixed include EPR enforcement timelines, Tangier Med port throughput capacity, and EU preferential trade agreement continuity; variables tested include resin price volatility scenarios and domestic recycling capacity expansion rates. Segmentation dimensions span material chemistry, end-use application, bottle size class, and regional production cluster. CAGRs derive from installed capacity utilization trends and customer qualification pipeline analysis across the projection horizon. Forecast inputs incorporate beverage bottler lightweighting targets and pharmaceutical ISO certification backlog estimates.
Macroeconomic conditions sit as an overlay; deviation in euro-dirham exchange rates, MEG feedstock pricing, or EU packaging waste directive stringency would shift the trajectory. Forecasts reflect documented assumptions without guarantee of realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Fluorinated Bottle Market