
 GCC Paper Bags Market | 2026-2036
GCC Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Paper Bags Market Foresight
Dubai's mandatory charge on single-use plastic bags is pivoting supermarket procurement toward paper alternatives across the emirate. Hotpack Packaging Industries LLC leverages its UAE manufacturing base to supply reinforced kraft bags to regional grocery chains. Mondi sustains competitive positioning through integrated pulp-to-bag operations and European technical standards. Al Zaini Converting Industries anchors volume supply for Saudi retail banners with localized production in Riyadh.
Paper bags are multi-wall containers manufactured from bleached or unbleached kraft pulp, typically ranging from 60 to 150 grams per square meter, designed to carry loads between 5 and 20 kilograms through glued or stitched bottom closures. Their primary commercial purpose is to replace plastic film bags in retail and food service distribution while meeting biodegradability requirements. Kraft paper bags occupy the dominant volume position due to structural strength and printability for branded retail applications. Laminated paper bags command margin premiums in gift packaging and premium apparel where moisture resistance and surface finish differentiate shelf presentation. Food packaging represents the fastest-growing application as quick-service restaurants and bakery chains adopt grease-resistant barrier coatings.
The UAE Ministry of Climate Change and Environment enforces plastic reduction mandates that directly expand paper bag quotas in Dubai and Abu Dhabi retail sectors. Saudi Standards, Metrology and Quality Organization (SASO) specifies paper bag tensile strength and fiber sourcing rules for domestic manufacturers and imports. Stakeholders must monitor how Gulf Cooperation Council harmonization of packaging waste rules reshapes cross-border supply qualifications and local content thresholds.
Market Dynamics
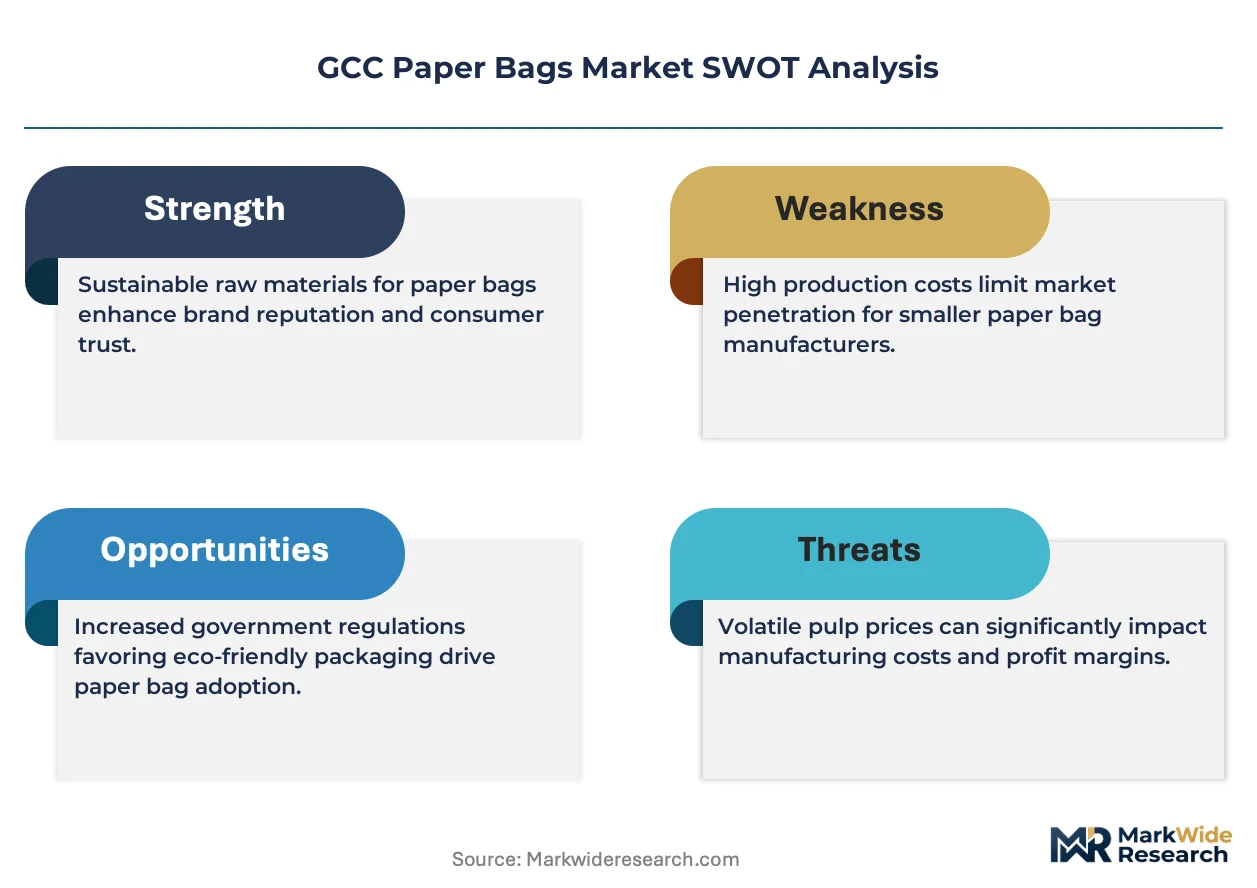
Single-use plastic bans across Gulf Cooperation Council member states are structurally rewiring retail packaging procurement, forcing supermarket chains to convert entire bag supply contracts to kraft paper alternatives within compressed compliance timelines.
Growth Catalysts
- MOHAP enforcement in Dubai:The UAE Ministry of Health and Prevention's plastic reduction mandates compel hypermarket operators to source paper carry bags exclusively from domestic converters.
- Quick-service restaurant expansion:Saudi Arabia's food service sector is absorbing grease-resistant kraft bags at volume as bakery and fried-food chains standardize sustainable packaging.
- Jebel Ali cluster concentration:Dubai's packaging manufacturing zone offers integrated converting capacity that shortens lead times for retail banner replenishment cycles.
Market Restraints
- Pulp cost volatility:Unbleached kraft fiber prices fluctuate with Nordic and South American softwood supply disruptions, compressing converter margins.
- Regional supply concentration:Overreliance on Riyadh and Jebel Ali production nodes creates vulnerability to logistics bottlenecks at Strait of Hormuz transit points.
- Moisture barrier limitations:Uncoated kraft's poor wet-strength performance restricts adoption in fresh seafood and frozen grocery segments.
Strategic Opportunities
- Oman and Bahrain penetration:These smaller GCC markets lack domestic converting capacity, creating import substitution openings for Saudi and UAE producers.
- Gift and luxury retail channel:Laminated paper bags with foil stamping command margin premiums in Dubai Mall and Riyadh Boulevard premium retail zones.
- SASO certification harmonization:Saudi Standards, Metrology and Quality Organization's unified fiber sourcing rules simplify cross-border qualification for regional suppliers.
Industry Challenges
- Twisted handle attachment automation:Semi-automatic cord inserting equipment requires skilled technicians scarce in Saudi Arabia's Eastern Province industrial zones.
- Food-contact compliance timelines:Migratory substance testing under SASO and MOHAP parallel frameworks delays new product launches by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Paper Bags Market |
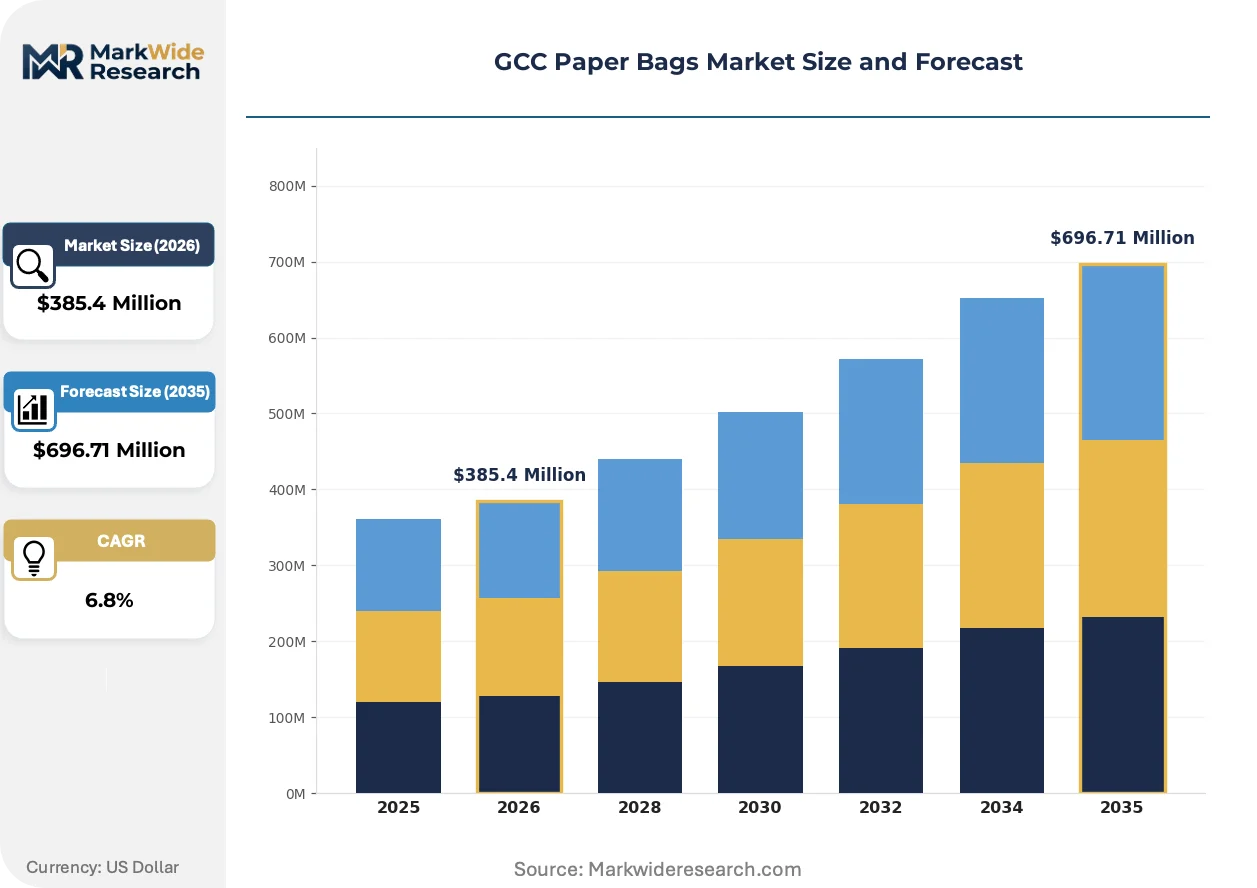
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kraft Paper Bags, Colored Paper Bags, Printed Paper Bags, Laminated Paper Bags Application: Food Packaging, Personal Care Packaging, Apparel Packaging, Gift Packaging End User: Supermarkets, Specialty Stores, E-commerce Vendors, Department Stores Distribution Channel: Direct Sales, Wholesalers, Online Platforms, Distributors |
| Companies Covered | Al Zaini Converting Industries, Mondi, Huhtamaki Flexibles UAE, BreezPack, Smurfit WestRock, Hotpack Packaging Industries LLC, Falcon Pack Industries LLC, Unipack Containers & Carton Products LLC, Gulf East Paper & Plastic Industries LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Paper Bags Market Shifts & Advancements
Converting technology is advancing rapidly across GCC packaging corridors. Automation investments are compressing unit economics while regulatory deadlines accelerate format standardization.
Digital printing systems are automating short-run customization for retail branding campaigns. Saudi supermarket chains are adopting these systems for seasonal promotional bag designs. This capability is automating what previously required month-long plate-change cycles, collapsing production lead times from weeks to days.
SASO's updated paper bag tensile strength specifications entered force in early 2024. Domestic manufacturers must now certify fiber provenance and wet-burst resistance metrics. Saudi food retail banners are responding by consolidating supplier panels to pre-qualified converters with in-house testing laboratories.
Hypermarket procurement teams are consolidating bag specifications across private-label and national-brand requirements. Regional grocery chains are displacing fragmented local supplier networks with single-source national contracts. This concentration is most visible in Abu Dhabi's Lulu and Carrefour operations, where standardized kraft grades now dominate shelf-ready packaging.
GCC Paper Bags Market Segmentation
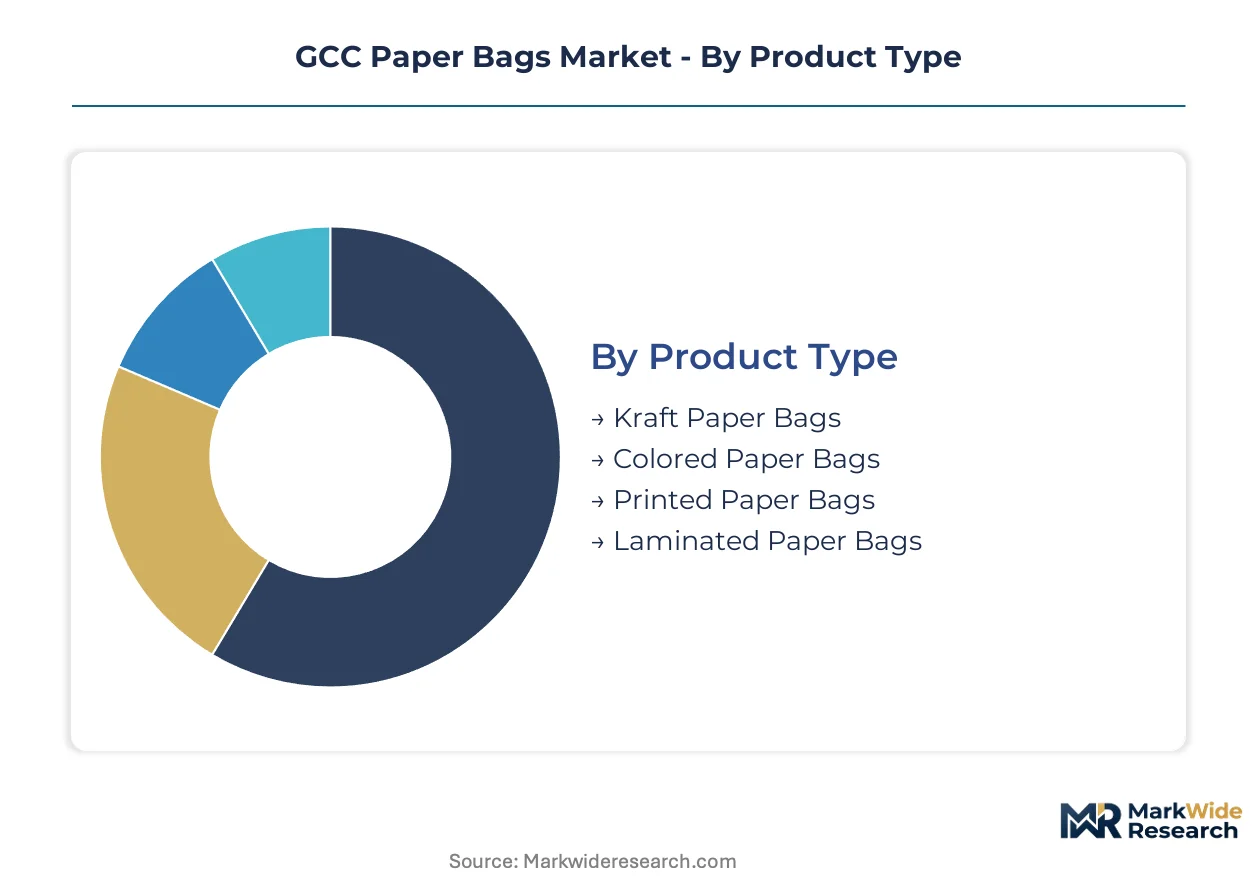
Paper bag procurement across the Gulf Cooperation Council diverges sharply between commodity retail volumes and premium branded formats. Converters must align production assets with distinct technical specifications, lead time requirements, and margin structures that vary by segment.
Product Type:
The customization-to-standardization spectrum runs from plain unbleached kraft for supermarket chains to fully engineered laminated constructions for luxury retail.
- Kraft Paper Bags:Unbleached sulfate pulp construction ranging 80-120 gsm delivers the tensile strength required for 10-20 kilogram grocery loads. Saudi hypermarket operators including Panda and Danube source these exclusively from domestic converters to meet SASO fiber provenance rules. Dubai's Jebel Ali cluster supplies reinforced twisted-handle variants to UAE retail banners under MOHAP plastic reduction mandates.
- Laminated Paper Bags:Extrusion-coated polyethylene or aluminum foil barriers create moisture resistance for frozen food and premium apparel applications. Gift retailers in Riyadh Boulevard and Dubai Mall specify these for branded unboxing experiences. Margin premiums of 40-60 percent above standard kraft attract specialty converters with digital printing capabilities.
- Printed Paper Bags:Flexographic or offset decoration serves seasonal promotional campaigns and private-label retail branding. Short-run digital systems are displacing conventional plate-based workflows.
- Colored Paper Bags:Dyed pulp or surface-coated finishes target party supply and confectionery segments with lower volume, higher color consistency requirements.
Most installed capacity flows through Kraft Paper Bags. Expansion is steepest in Laminated Paper Bags.
Application:
Volume concentration versus margin capture defines strategic positioning across end-use categories.
- Food Packaging:Grease-resistant fluorochemical or bio-based barrier coatings enable hot-food containment for Saudi quick-service restaurant chains. Albaik and Maestro Pizza specify heat-sealed kraft pouches with anti-fog windows. Bakery chains across Dubai and Jeddah are standardizing compostable PLA-lined bags for pastry display.
- Gift Packaging:Rigid laminated constructions with ribbon handles and foil stamping command highest per-unit pricing. Ramadan and Eid seasonal demand concentrates in Dubai's Deira wholesale district.
- Apparel Packaging:Large-format twisted-handle bags with reinforced bottoms serve fashion retail in Riyadh's Roshn Front and Abu Dhabi's Yas Mall.
- Personal Care Packaging:Smaller format flat bags with die-cut handles target pharmacy and cosmetics retail with moderate decoration requirements.
Food Packaging absorbs the greatest absolute volume. Gift Packaging delivers the highest contribution margin per square meter.
End User:
Procurement scale and technical specification intensity separate national retail banners from fragmented specialty trade.
- Supermarkets:Carrefour UAE and Lulu Group operate centralized procurement functions specifying standardized kraft grades across private-label and national-brand requirements. These buyers negotiate annual volume contracts with 30-45 day replenishment cycles.
- E-commerce Vendors:Noon and Amazon.ae specify custom-printed mailer bags with tamper-evident closures and return-ready construction. Demand fluctuates with promotional calendars requiring 7-10 day production turnarounds.
- Specialty Stores:Independent food retailers and boutique chains purchase through wholesale distributors with limited customization.
- Department Stores:Landmark Group and Chalhoub Group balance premium presentation with cost control across multiple retail banners.
Supermarkets consolidate the largest contract values. E-commerce Vendors are gaining share fastest in absolute growth terms.
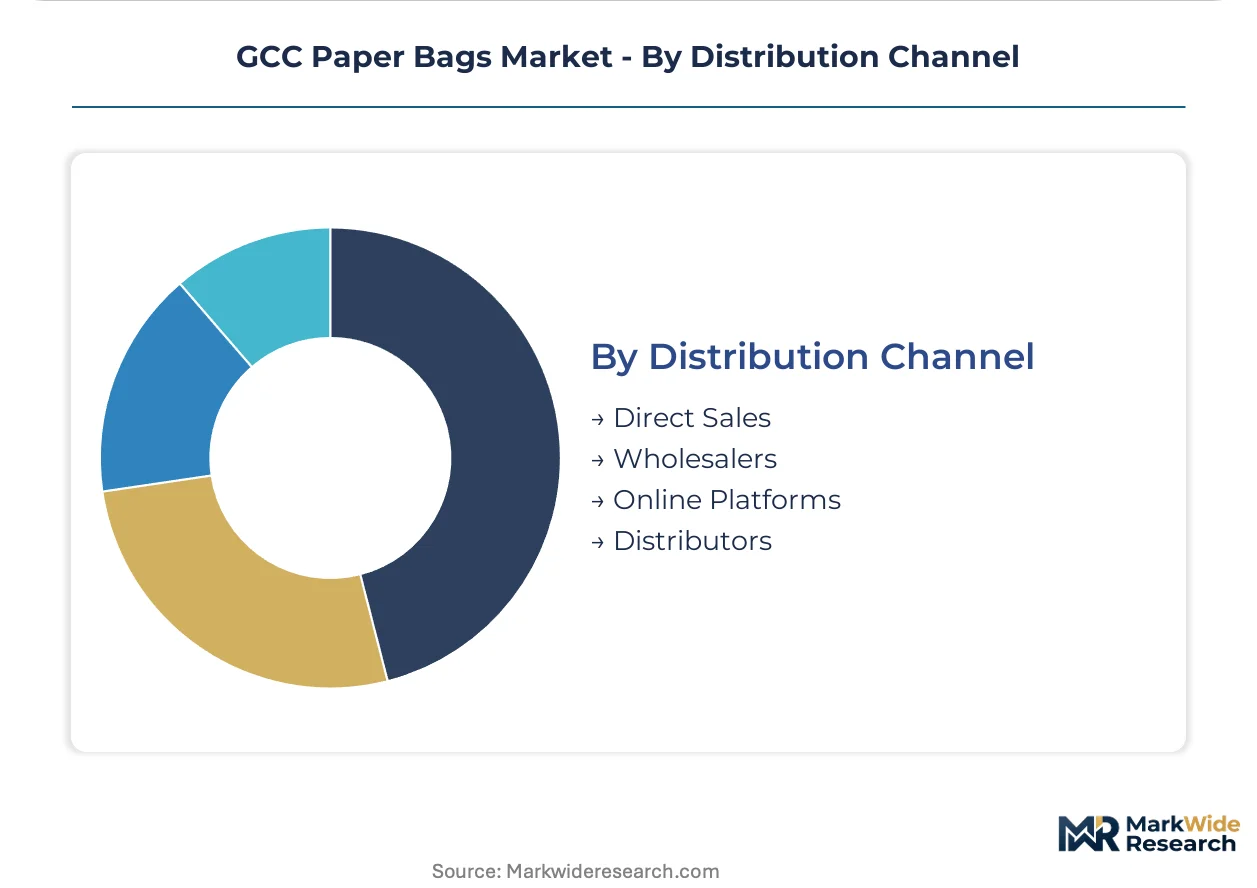
Distribution Channel:
Channel selection determines margin retention versus market reach tradeoffs for converters of varying scale.
- Direct Sales:National retail banners negotiate factory-direct supply agreements with converters maintaining in-house testing laboratories for SASO compliance documentation.
- Distributors:Regional packaging distributors inventory standard kraft grades for smaller retail accounts across Oman, Bahrain, and Kuwait.
- Wholesalers:Deira and Riyadh wholesale markets serve cash-and-carry buyers with undecorated stock bags.
- Online Platforms:Alibaba.com and regional B2B marketplaces connect buyers with Chinese and Indian converters for non-urgent, price-sensitive procurement.
Direct Sales captures the majority of high-volume contract value. Distributors enable geographic expansion into undersupplied smaller GCC markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paper bag manufacturing across the Gulf Cooperation Council traces its commercial scale to Dubai's 1990s free-zone industrialization, when Jebel Ali's packaging cluster first supplied regional retail expansion. Today, national plastic bans are redistributing production capacity across member states.
United Arab Emirates
MOHAP's 2024 plastic reduction mandates compel Dubai hypermarkets to source paper carry bags exclusively from domestic converters. Hotpack Packaging Industries LLC anchors production in Jebel Ali's integrated manufacturing zone, supplying reinforced kraft grades to Carrefour UAE and Lulu Group banners. Abu Dhabi's retail procurement teams are consolidating supplier panels to meet identical compliance timelines.
Saudi Arabia
SASO's fiber provenance and tensile strength specifications entered force in early 2024, forcing domestic manufacturers to certify wet-burst resistance metrics. Al Zaini Converting Industries maintains localized production in Riyadh's industrial corridor, serving Panda and Danube hypermarkets under centralized annual contracts. The Eastern Province's skilled technician shortage complicates twisted-handle automation expansion.
Oman
The Sultanate lacks domestic converting capacity of scale, creating import substitution openings for Saudi and UAE producers. Retail procurement teams in Muscat source standard kraft grades through distributors rather than factory-direct agreements. Salalah's port infrastructure offers alternative Strait of Hormuz transit for regional suppliers seeking redundancy.
Bahrain
Manama's compact retail market concentrates demand in supermarket and food service channels without supporting dedicated bag manufacturing. MOHAP-equivalent regulations are pending, delaying procurement shifts already completed in Dubai. Bahraini distributors inventory Saudi-origin kraft bags for cash-and-carry wholesale trade.
Kuwait
The emirate's retail sector absorbs laminated paper bags for premium apparel and gift applications, with volume kraft requirements met through cross-border supply from Riyadh and Jebel Ali. Kuwait City's procurement teams negotiate 30-45 day replenishment cycles with regional converters maintaining SASO certification. No domestic production capacity of significance operates.
GCC Paper Bags Market Competitive Landscape
Capital-heavy integrated producers compete with asset-light converting specialists across GCC packaging corridors. The vendor base stratifies between pulp-to-bag operators with captive fiber supply and independent converters purchasing kraft rolls on spot markets. Three archetypes dominate: multinational integrated players with European technical standards, regional specialists with localized Riyadh or Jebel Ali manufacturing, and import-dependent distributors serving undersupplied smaller markets. Competitive moves center on SASO certification pre-qualification and automation investments compressing unit economics.
Among UAE-based converters, Hotpack Packaging Industries LLC and Falcon Pack Industries LLC exemplify the regional specialist archetype with Jebel Ali manufacturing footprints. Mondi represents the integrated multinational tier, sustaining positioning through pulp-to-bag operations and technical standard transfer from European facilities. These three anchors illustrate the competitive tension between localized supply chain proximity and global scale efficiencies.
| Leading Market Players |
|---|
| Al Zaini Converting Industries |
| Mondi |
| Huhtamaki Flexibles UAE |
| BreezPack |
| Smurfit WestRock |
| Hotpack Packaging Industries LLC |
| Falcon Pack Industries LLC |
| Unipack Containers & Carton Products LLC |
| Gulf East Paper & Plastic Industries LLC |
| Others |
Supply & Pricing Matrix
Automation of twisted-handle attachment equipment is compressing unit labor costs while simultaneously concentrating production among converters with capital reserves for semi-automatic lines, reshaping competitive economics across Saudi Arabia's Eastern Province and Dubai's Jebel Ali corridor. This technology shift rewards scale operators who can amortize equipment costs across high-volume supermarket contracts while marginalizing manual-assembly workshops.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Saudi hypermarkets and domestic converters, with price differentiation driven by SASO certification tier and volume scale commitments. Pricing pressure stems from Nordic softwood pulp cost volatility transmitted through spot-market kraft roll purchases. National retail banners exhibit lowest price sensitivity due to compliance mandates, while independent wholesalers in Oman and Bahrain face acute cost pressure from freight-inflated import supply.
Supply Chain Analysis
Unbleached kraft fiber supply rests on Nordic and South American softwood pulp producers, with GCC converters drawing from Brazilian eucalyptus and Scandinavian pine sources. Regional bag manufacturing concentrates in Saudi Arabia and the United Arab Emirates, with finished goods distribution running through Jebel Ali port infrastructure and Riyadh industrial corridor logistics nodes. Single-source vulnerability exists at Strait of Hormuz transit chokepoints, where shipping disruptions cascade through replenishment cycles for Omani and Bahraini retail markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium laminated bag segments are expanding contribution margins faster than commodity kraft volumes as Dubai Mall and Riyadh Boulevard luxury retailers upgrade packaging specifications. Automation investments and SASO certification pre-qualification together constitute the primary cost-down and premium-capture pathway.
For Market Incumbents: Anticipate consolidation pressure from multinational integrated producers by securing captive pulp supply agreements or backward integration into kraft roll production. Defensive priority rests on automating twisted-handle attachment lines before skilled technician scarcity in Saudi Arabia's Eastern Province worsens. Pre-qualification under SASO's updated tensile strength specifications locks out smaller competitors from Carrefour UAE and Lulu Group panels. For New Entrants and Emerging Players: Enter via gift packaging and laminated bag segments where digital printing capabilities and foil stamping expertise command 40-60 percent margin premiums above standard kraft. Oman and Bahrain present the most penetrable geographies given absent domestic converting capacity and distributor-dependent procurement. Go-to-market angle should emphasize Salalah port routing to bypass Strait of Hormuz bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale converters lacking SASO-certified testing laboratories but possessing established relationships with Saudi retail banners. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume scale. Acquisition target archetype: Jebel Ali or Riyadh-based operators with underutilized automation capacity. Signal to monitor: MOHAP-equivalent plastic reduction mandates spreading to Bahrain and Kuwait.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Roll Production | Captive pulp supply insulates converters from Nordic softwood price volatility transmitted through spot markets. |
| SASO Certification Pre-Qualification | Certified testing laboratory access unlocks centralized procurement contracts with Panda and Danube hypermarkets. |
| Semi-Automatic Handle Attachment Deployment | Equipment investments compress unit labor costs while concentrating supply among capitalized Jebel Ali and Riyadh producers. |
| Digital Printing Capability Addition | Short-run customization systems capture seasonal promotional campaigns from Saudi supermarket chains. |
| Salalah Port Distribution Redundancy | Alternative routing through Omani port infrastructure mitigates Strait of Hormuz transit risk for regional supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with procurement directors at Saudi hypermarket operators, technical managers at UAE converting facilities, and logistics coordinators at Jebel Ali port operators with secondary validation against SASO regulatory filings, MOHAP enforcement notices, and customs trade records. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across product type, application, and end-user dimensions.
Segment-weighting approaches modeled kraft versus laminated bag splits, food packaging versus gift packaging application shares, and supermarket versus e-commerce vendor end-user concentrations across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement timelines and plastic ban implementation schedules. Forecast inputs incorporated pulp cost index movements and automation adoption curves specific to GCC converting corridors.
Inputs from Saudi and UAE regulatory filings were available through the study window; gaps in real-time Omani and Bahraini procurement data introduce uncertainty bands for smaller GCC market sizing. Forecasts reflect documented assumptions regarding SASO harmonization timelines and MOHAP enforcement consistency. Pulp cost volatility, Strait of Hormuz logistics disruptions, and skilled technician availability in Saudi Arabia's Eastern Province constitute primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market