
 Fresh Produce Trays Market | 2026-2036
Fresh Produce Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Produce Trays Market Foresight
Capital-intensity divergence between automated thermoforming lines and manual assembly operations is reorganizing competitive tiers in fresh produce tray supply. Sealed Air Corporation leverages its barrier film integration to control shelf-life extension in berry applications. Smurfit Kappa dominates corrugated tray supply to European supermarket private-label programs through regional mill networks.
Fresh produce trays are rigid or semi-rigid containers, typically manufactured from PET, PP, molded pulp, or corrugated fiberboard, designed to protect, display, and ventilate perishable fruits and vegetables during distribution and retail presentation. Structural segment dynamics reveal that molded pulp trays are capturing share fastest as foodservice operators and supermarkets face plastic-reduction targets, while clamshell designs for berries retain the strongest margin pools due to precision engineering requirements and brand-owner specification lock-in.
The EU F-Gas Regulation and REACH compliance frameworks shape material selection across European tray converters, while FDA food-contact substance notifications govern resin approvals for US-bound produce packaging. California's SB 54 extended producer responsibility law is forcing domestic suppliers to validate fiber-based alternatives through state-certified recycling pathways. Stakeholders must monitor how fragmentation between composting infrastructure availability and mechanical recycling capacity determines which material platforms achieve viable end-of-life economics.
Market Dynamics
The EU Single-Use Plastics Directive is decomposing incumbent PET tray architectures across European fresh produce supply chains, forcing converters to requalify entire material platforms through accelerated certification timelines while supermarket private-label programs demand simultaneous cost parity and carbon footprint reductions.
Growth Catalysts
- California SB 54 mandates:Extended producer responsibility laws are compelling US retailers to validate fiber-based tray alternatives through state-certified recycling pathways, creating certified demand pools for molded pulp suppliers.
- Berry segment engineering specifications:Clamshell designs for soft fruits require precision venting and barrier integration that locks in technical relationships between converters and brand owners.
- German retail consolidation:Discounter and supermarket chain concentration favors standardized tray formats with uniform recyclability credentials, streamlining procurement at scale.
Market Restraints
- Pulp fiber input volatility:Recycled paperboard and agricultural residue feedstock prices fluctuate with energy costs and harvest yields, compressing molded pulp tray margins unpredictably.
- Thermoforming equipment concentration:Automated high-speed lines for APET and PP trays concentrate supply among German and Italian machinery builders, creating capex bottlenecks for new entrants.
- Composting infrastructure asymmetry:Industrial composting facility availability varies dramatically between Netherlands dense networks and Eastern European gaps, fragmenting end-of-life economics for biodegradable trays.
Strategic Opportunities
- Pre-cut vegetable foodservice channels:Ghost kitchen operators and meal-kit assemblers in France and UK are specifying custom tray formats for portion-controlled produce with extended cold-chain performance.
- Barrier film integration convergence:Oxygen-scavenging and anti-fog coating technologies are merging with fiber-based substrates to create hybrid trays that satisfy both shelf-life and sustainability specifications.
- Deposit-return scheme expansion:Nordic extended producer responsibility frameworks are piloting reusable tray pooling systems for closed-loop supermarket distribution, creating service-based revenue models.
Industry Challenges
- Migration testing expertise scarcity:Food-contact substance notification pathways under FDA and EFSA frameworks require specialized toxicology and analytical chemistry capabilities that smaller converters struggle to staff.
- Legacy thermoforming asset stranding:Existing PET and PP production lines face accelerated obsolescence risk as retailer plastic-reduction targets compress payback periods for recent equipment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Produce Trays Market |
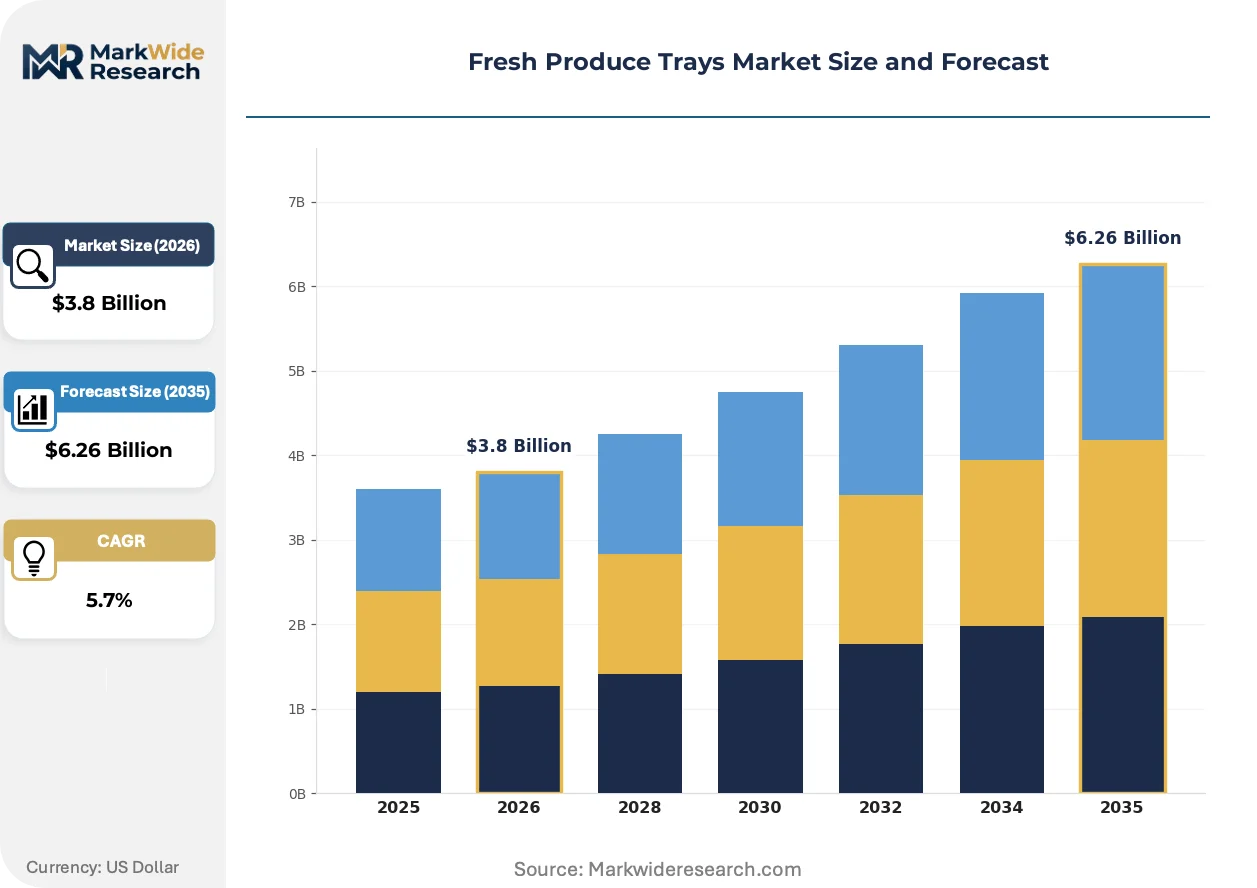
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Cardboard, Molded Pulp, Aluminum, Bamboo Tray Design: Clamshell, Compartmentalized, Flat, Raised Edge, Perforated Application: Fruits, Vegetables, Herbs, Berries, Exotic Produce End User: Supermarkets, Wholesalers, Foodservice Operators, Agro Processors, Specialty Stores |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Berry Global Inc., Amcor Plc, Smurfit Kappa, WestRock, Mondi Group, DS Smith, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Produce Trays Market Shifts & Advancements
Active material science breakthroughs are collapsing the performance gap between fiber-based and plastic trays, while regulatory fragmentation across jurisdictions forces simultaneous multi-pathway compliance strategies.
Barrier-coated molded pulp technology is decomposing the historical shelf-life advantage of petroleum-based trays. Berry packers in Spain and Netherlands are qualifying fiber clamshells with integrated oxygen barriers at commercial scale. The structural consequence is compressing premium pricing power that incumbents previously extracted from extended shelf-life guarantees.
REACH authorization requirements for persistent organic pollutants are tightening residual contamination thresholds in recycled PET feedstocks. Tray converters serving EU markets must now document supply chain segregation and advanced sorting investments. Small-to-mid converters in Poland and Romania are most affected, consolidating toward toll-manufacturing relationships with resin compounders.
Centralized procurement desks at supermarket chains are compressing supplier rosters and demanding carbon accounting transparency. Category managers in Germany and France now require third-party verified lifecycle assessments as table stakes for tender participation. This behavior is most visible in organic produce segments where consumer-facing sustainability claims carry price premiums.
Fresh Produce Trays Market Segmentation
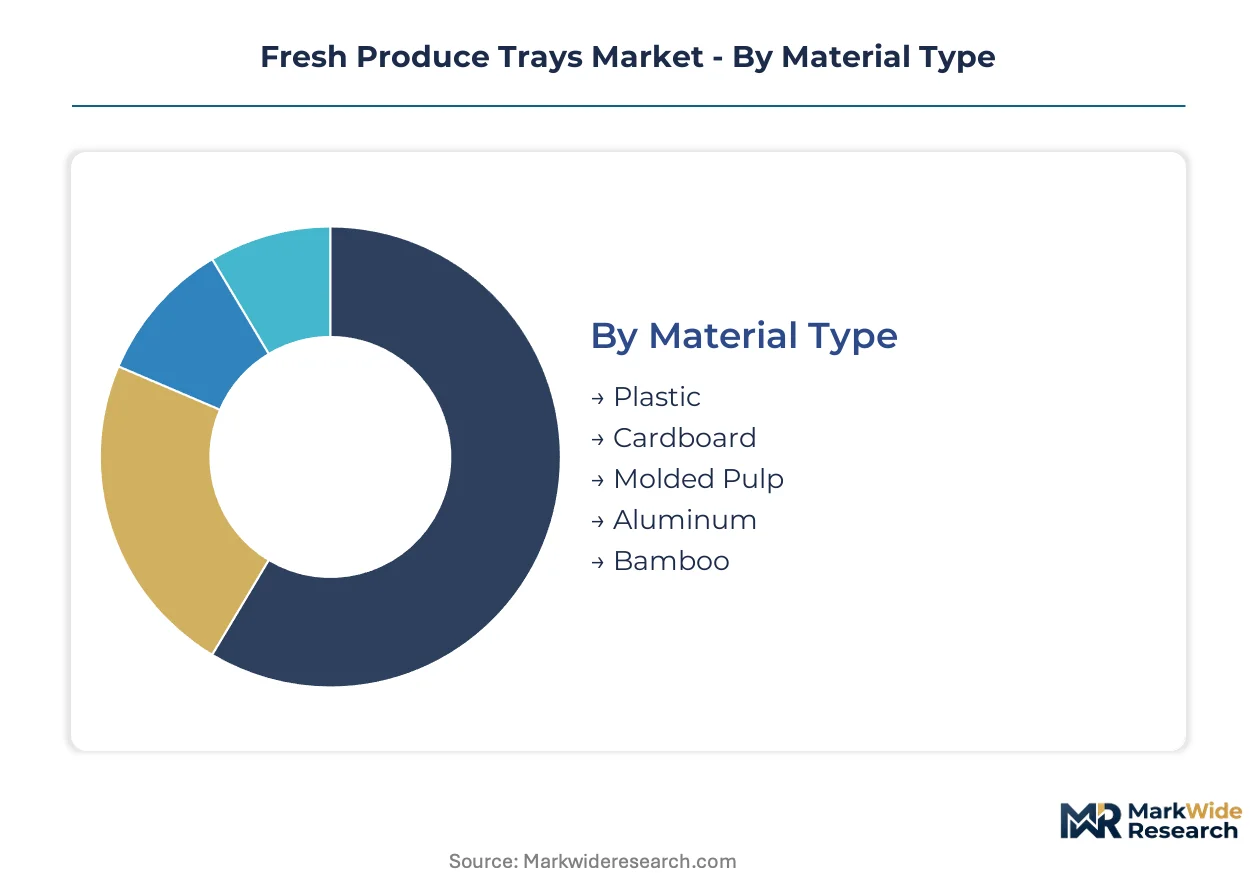
Fresh produce tray procurement diverges sharply by channel. Supermarket chains demand standardized, recyclable formats for high-velocity SKUs. Foodservice operators prioritize portion control and cold-chain performance over shelf presentation.
Material Type:
Channel-mix dynamics concentrate premium materials in branded retail while cost-sensitive foodservice channels absorb fiber-based alternatives. Supermarket private-label programs in Germany and France are accelerating material shifts through centralized tender specifications.
- Plastic:PET and PP thermoformed trays dominate berry clamshell applications through precision venting and optical clarity. German retailers are phasing out virgin petroleum-based formats under EPR mandates, forcing converters toward recycled content validation.
- Molded Pulp:Agricultural residue and recycled paperboard substrates are displacing plastic in pre-cut vegetable trays. Spanish and Dutch berry packers are qualifying barrier-coated fiber clamshells at commercial scale, collapsing the historical shelf-life advantage of petroleum-based alternatives.
- Cardboard:Corrugated fiberboard serves bulk distribution to wholesalers and agro processors with lower unit-value produce.
- Aluminum:Premium exotic produce and gift formats exploit metallic barrier properties for extended air-freight shelf life.
- Bamboo:Niche organic and specialty retail channels in France and UK specify bamboo for consumer-facing sustainability claims.
By volume, plastic leads. By growth pace, molded pulp is expanding most quickly.
Tray Design:
Cost-tier stratification separates precision-engineered formats from commodity distribution trays. Berry applications command engineering premiums while bulk vegetable movement absorbs standardized designs.
- Clamshell:Hinged-lid configurations with integrated latches and micro-perforations protect soft fruits through distribution vibration and retail handling. Brand-owner specification lock-in creates durable technical relationships between converters and packers.
- Compartmentalized:Multi-cell designs for meal-kit assemblers and ghost kitchen operators enable portion-controlled produce presentation with extended cold-chain performance.
- Flat:Minimal-cost formats serve wholesale bulk movement of root vegetables and hard produce with limited spoilage risk.
- Raised Edge:Stacking stability for warehouse club and discounter channels handling high-cube produce volumes.
- Perforated:Ventilation-optimized designs for respiring vegetables in extended distribution loops.
By margin capture, clamshell dominates. By volume throughput, flat trays lead.
Application:
Geographic production clusters determine tray specification intensity. Mediterranean berry cultivation and Benelux greenhouse vegetable operations generate concentrated demand for high-performance formats.
- Berries:Soft-fruit fragility demands precision-engineered clamshells with anti-fog barriers and crush-resistant geometries. Spanish raspberry and Dutch strawberry packers drive specification innovation through integrated oxygen-scavenging technologies.
- Vegetables:Pre-cut and ready-to-cook segments in UK and French foodservice channels specify custom tray formats with moisture management and extended cold-chain credentials.
- Fruits:Pome and stone fruit distribution relies on ventilated corrugated or perforated plastic for respiration management.
- Herbs:Live-plant and cut-herb formats require high-humidity retention with condensation control.
- Exotic Produce:Air-freight tropical fruits exploit aluminum and high-barrier plastic for ethylene and moisture management.
By revenue concentration, berries lead. By volume expansion, vegetables are gaining share fastest.
End User:
Customer-type procurement power reshapes supply relationships. Centralized supermarket buying desks compress supplier rosters while fragmented foodservice channels sustain regional converter diversity.
- Supermarkets:German discounter and supermarket chain concentration favors standardized tray formats with uniform recyclability credentials and third-party verified lifecycle assessments as tender prerequisites.
- Foodservice Operators:Ghost kitchen and meal-kit channels in France and UK specify custom formats for portion-controlled produce with cold-chain performance guarantees.
- Wholesalers:Bulk distribution networks prioritize cost-minimization through corrugated and flat plastic formats with minimal specification overhead.
- Agro Processors:Industrial-scale washing, cutting, and packing operations demand durable, stackable trays for high-throughput lines.
- Specialty Stores:Organic and premium retail channels in urban France and UK absorb bamboo and molded pulp formats for consumer-facing sustainability differentiation.
By procurement scale, supermarkets dominate. By specification dynamism, foodservice operators show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in fresh produce trays varies sharply by channel. German supermarket buyers enforce strict cost discipline through centralized tenders, while UK foodservice operators absorb premium pricing for custom formats with extended cold-chain credentials.
Germany
Discounter concentration and EPR mandates drive demand for standardized recyclable formats. The country's packaging waste regulations under the VerpackG framework require verified recyclability credentials. The Rhine-Ruhr industrial corridor hosts thermoforming equipment clusters serving pan-European supermarket private-label programs.
United States
California SB 54 and state-level EPR laws compel retailers to validate fiber-based alternatives through certified recycling pathways. FDA food-contact substance notifications govern resin approvals for produce packaging. The Central Valley agricultural belt generates concentrated demand for berry clamshells with precision venting specifications.
Netherlands
Greenhouse vegetable operations and advanced composting infrastructure support rapid molded pulp adoption. The EU Single-Use Plastics Directive accelerates shifts away from virgin petroleum-based formats. The Westland region's high-density horticulture clusters specify barrier-coated fiber trays for pre-cut vegetable distribution.
Spain
Mediterranean berry cultivation drives specification intensity for soft-fruit protection formats. REACH compliance frameworks shape material selection across domestic converters. The Huelva and Almería growing regions anchor demand for clamshell designs with integrated oxygen-scavenging technologies.
United Kingdom
Meal-kit assemblers and ghost kitchen operators specify custom tray formats for portion-controlled produce. Extended producer responsibility schemes under the UK Packaging Waste Regulations favor fiber-based alternatives. The London-Southeast corridor concentrates foodservice procurement desks demanding carbon accounting transparency.
Fresh Produce Trays Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in fresh produce tray supply. Tier-one players combine barrier film integration with regional mill networks to control shelf-life performance and raw material access. Strategic archetypes include film-integrated packaging conglomerates, corrugated fiberboard specialists with supermarket private-label lock-in, and molded pulp converters capturing plastic-reduction demand. Dominant competitive moves center on backward integration into agricultural residue feedstocks and technology licensing for barrier-coated fiber platforms.
Within the integrated packaging tier, Sealed Air Corporation and Amcor Plc exemplify film-barrier integration strategies, while Smurfit Kappa anchors corrugated supply to European retail programs. These three occupy positions spanning the plastic-to-fiber transition, with each representing distinct approaches to material platform diversification and customer relationship depth in supermarket and foodservice channels.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Berry Global Inc. |
| Amcor Plc |
| Smurfit Kappa |
| WestRock |
| Mondi Group |
| DS Smith |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German supermarket chains and molded pulp converters lock in both agricultural residue feedstock access and three-year price visibility, insulating procurement desks from pulp fiber input volatility while compressing spot-market opportunities for smaller suppliers.
Pricing Analysis
After-sales service contracts for barrier film integration and shelf-life performance guarantees drive lifetime value for berry clamshell converters. Three-tier pricing structure across premium, standard, and economy levels separates precision-engineered clamshells with oxygen-scavenging technology from commodity flat trays. Cost compression in standard-tier thermoformed PET runs through recycled content validation requirements under California SB 54. Supermarket private-label buyers show highest price sensitivity, while foodservice operators absorbing custom formats for ghost kitchens demonstrate lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of recycled paperboard and agricultural residues characterizes converter procurement in Germany and the Netherlands, contrasting with just-in-timed virgin resin purchasing by legacy PET thermoformers. Raw material sourcing draws from Swedish forestry residues, Spanish wheat straw, and Italian recycled fiber streams. Single-source vulnerability concentrates in German and Italian thermoforming equipment builders, creating capex bottlenecks. Distribution runs through regional mill networks serving pan-European supermarket private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh produce tray demand follows cyclical patterns tied to supermarket capital expenditure cycles for packaging format refreshes, with current EPR mandate acceleration compressing replacement timelines across European retail networks.
For Market Incumbents: Compound technical relationships with berry brand owners through integrated barrier film R&D partnerships, locking out fiber-based alternatives from precision clamshell specifications. Pursue backward integration into agricultural residue preprocessing in Spain and Poland to secure feedstock cost advantage against emerging molded pulp specialists. Defensive consolidation toward toll-manufacturing relationships with resin compounders addresses REACH authorization tightening for recycled PET.
For New Entrants and Emerging Players: Certification fast-track through EU compostability standard EN 13432 and US BPI validation opens foodservice channels in France and UK where procurement desks prioritize sustainability credentials over incumbent relationships. Target ghost kitchen and meal-kit assemblers specifying custom compartmentalized formats with extended cold-chain guarantees. Go-to-market through direct technical sales to fragmented regional foodservice operators bypasses supermarket centralized procurement lock-in.
For Investors and Strategic Acquirers: Regional molded pulp converters with validated barrier-coating technology and established supermarket private-label relationships represent the most defensible acquisition profile for five-to-ten year holding periods. Watch Nordic deposit-return scheme pilot expansion as inflection indicator for reusable tray pooling service models displacing single-use formats.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coated Fiber Platform Development | Spanish and Dutch berry packers are qualifying oxygen-scavenging fiber clamshells at commercial scale. |
| Agricultural Residue Backward Integration | Wheat straw preprocessing in Almería and Huelva secures feedstock cost advantage for EU converters. |
| Reusable Tray Pooling Pilot | Nordic extended producer responsibility frameworks test closed-loop supermarket distribution service models. |
| REACH Compliance Consolidation | Polish and Romanian converters face toll-manufacturing pressure from resin compounders over persistent organic pollutant thresholds. |
| California SB 54 Certification Pathway | State-certified recycling validation creates demand pools for molded pulp suppliers serving US retailers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU packaging waste directive filings, FDA food-contact substance notifications, and supermarket tender documentation across Germany, France, and the Netherlands. Primary interviews engaged thermoforming equipment operators, agricultural residue brokers, supermarket category managers, and barrier film chemists. Secondary sources incorporated customs data for recycled paperboard flows, ECHA REACH authorization registers, and California SB 54 implementation guidance. Bottom-up volume modeling triangulated against top-down expenditure estimates from retail packaging procurement disclosures.
Segmentation dimensions modeled include material platform, tray design complexity, produce application fragility, and end-user channel concentration across the analysis window. CAGRs derived from weighted regression of historical substitution patterns between plastic and fiber formats, calibrated to regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated composting infrastructure density indices and thermoforming equipment capacity utilization rates.
Decision-makers should treat outputs as directional under base assumptions of sustained EPR mandate enforcement and barrier-coating technology maturation; material deviation would warrant model refresh. Revision becomes warranted when industrial composting facility commissioning crosses thresholds in Eastern European markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Disposable Food Containers Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Cake Box Market