
 Fluorinated Bottle Market | 2026-2036
Fluorinated Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorinated Bottle Market Foresight
Fluorination process control is fragmenting as plasma-enhanced surface treatments displace conventional batch fluorine gas methods. Thermo Fisher Scientific leverages its laboratory-grade certification protocols to dominate life science packaging. Plastipak Holdings sustains high-volume production lines across North American chemical corridors. Berry Global differentiates through multi-layer co-injection platforms that integrate fluorinated barriers with recycled content streams.
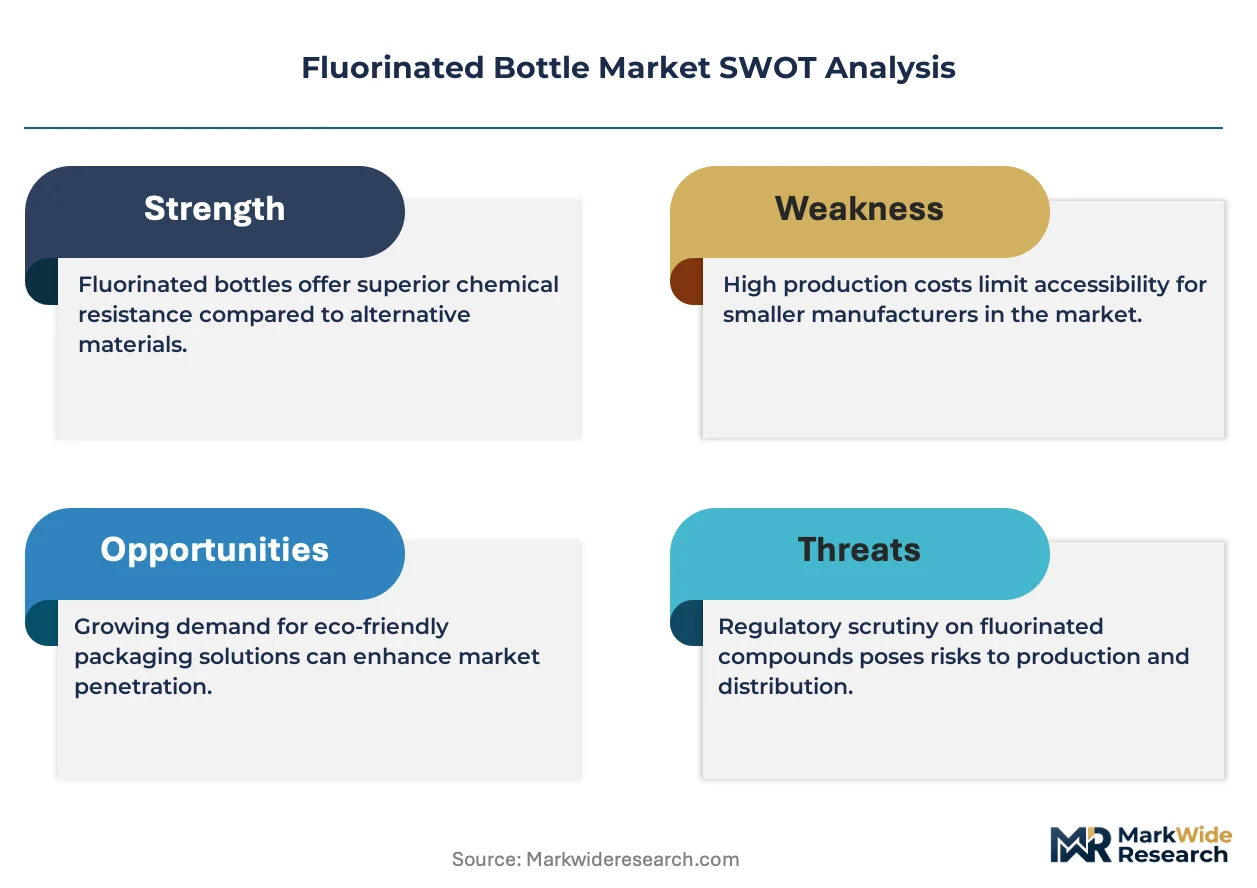
Fluorinated bottles are polymer containers treated with fluorine gas or plasma to create a dense, low-permeability surface layer, typically achieving oxygen transmission rates below 0.1 cc per bottle per day. This barrier architecture prevents solvent loss, oxidative degradation, and volatile organic compound migration in pharmaceutical and agrochemical storage. HDPE bottles lead volume due to established blow-molding infrastructure and cost-efficient fluorination compatibility. Spray bottles within the packaging type dimension capture premium margin pools as fine-mist pharmaceutical and cosmetic applications require precise dose control with zero leakage. Pharmaceutical applications anchor value concentration because regulatory compliance costs favor suppliers with validated manufacturing records.
The FDA enforces strict extractables and leachables testing under container closure guidance, compelling fluorinated bottle makers to document batch-level permeation consistency. The EPA regulates fluorinated greenhouse gas emissions under the American Innovation and Manufacturing Act, pushing converters toward closed-loop fluorination recovery systems. REACH compliance in Europe restricts certain fluorinated compound classifications, reshaping material qualification pathways for exporters. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across jurisdictions to avoid stranded inventory positions.
Market Dynamics
Plasma-enhanced fluorination is fragmenting process control across the value chain, displacing conventional batch fluorine gas methods and forcing capital retooling at conversion facilities serving pharmaceutical and agrochemical end-uses.
Growth Catalysts
- Container closure integrity mandates:FDA extractables and leachables testing requirements compel drug manufacturers to specify barrier-validated fluorinated bottles for parenteral and oral liquid formulations.
- Specialty chemical cluster expansion:Germany's Rhine-Neckar and Antwerp-Rotterdam chemical corridors generate concentrated demand for high-purity fluorinated storage in active pharmaceutical ingredient handling.
- Closed-loop fluorination recovery:EPA American Innovation and Manufacturing Act enforcement drives adoption of emission-capture systems that simultaneously reduce compliance costs and permit availability.
Market Restraints
- Elemental fluorine supply concentration:Five integrated chemical producers control global fluorine gas supply, creating input cost volatility when maintenance outages coincide with seasonal agricultural chemical demand.
- Perfluorinated compound restrictions:REACH classifications in Europe and state-level PFAS legislation in Minnesota and Maine threaten material qualification for exporters serving multiple jurisdictions.
- Glass and metal substitution:Borosilicate vials and aluminum bottles retain preference in ultra-high-purity biologics where any polymer permeation risk is unacceptable.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO alignment with ICH Q3D guidelines creates certified supplier gaps that fluorinated bottle converters with validated manufacturing records can fill.
- Recycled content integration:Multi-layer co-injection platforms enable post-consumer HDPE incorporation while maintaining fluorinated barrier performance against oxygen transmission.
- Fine-mist spray applications:Cosmetic and over-the-counter pharmaceutical dose-control requirements expand addressable market beyond traditional screw-cap pharmaceutical bottles.
Industry Challenges
- Plasma process engineering talent scarcity:Electrochemical surface treatment expertise concentrates at semiconductor equipment suppliers, creating recruitment competition for fluorination equipment operators.
- Batch-level permeation documentation:Pharmaceutical customers require oxygen transmission rate certificates for every production lot, forcing quality system investments that mid-scale converters struggle to amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorinated Bottle Market |
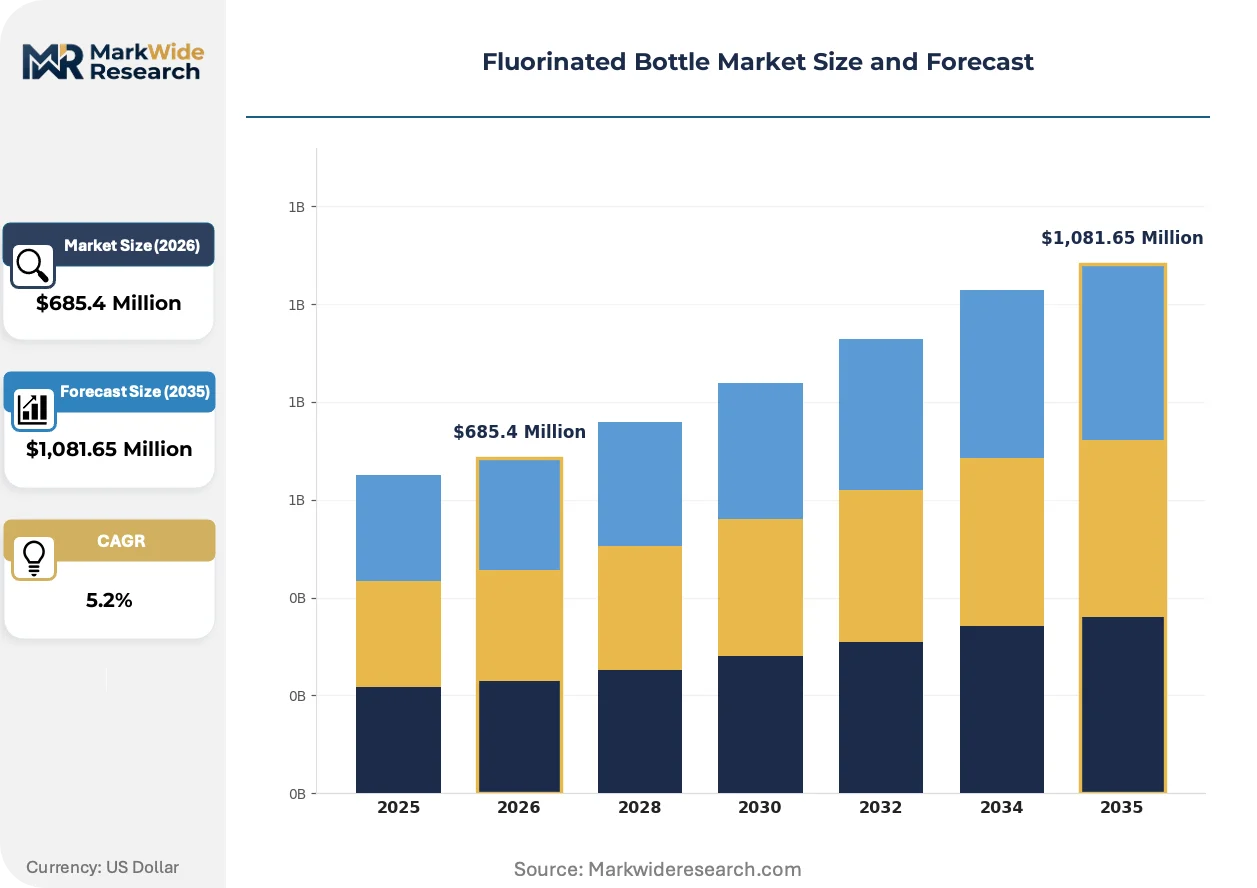
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE Bottles, PET Bottles, Glass Bottles, Aluminum Bottles, PP Bottles Application: Pharmaceuticals, Chemical Storage, Food & Beverage, Personal Care, Agriculture End User: Contract Manufacturers, Packaging Providers, Industrial Suppliers, Retail Distributors Packaging Type: Spray Bottles, Dropper Bottles, Wide Mouth Bottles, Amber Bottles, Cylinder Bottles |
| Companies Covered | Thermo Fisher Scientific, Plastipak Holdings Inc., Berry Global Inc., Greiner Packaging, Graham Packaging Company, Solvay S.A., Corning Inc., Alpha Packaging, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorinated Bottle Market Shifts & Advancements
Barrier architecture innovation is compressing the performance gap between commodity HDPE and engineered multi-layer structures while regulatory chemistry restrictions force material scientists toward novel surface activation pathways.
Plasma-enhanced fluorination is hybridizing gas-phase and liquid-phase surface treatment approaches to achieve nanometer-scale barrier uniformity without bulk polymer property degradation. Contract manufacturers serving generic pharmaceutical firms are adopting this hybrid equipment fastest, drawn by reduced fluorine consumption and shorter batch cycle times. The technology is hybridizing competitive positioning between high-volume commodity converters and precision barrier specialists previously separated by capital intensity thresholds.
REACH restrictions on per- and polyfluoroalkyl substance classifications are forcing European fluorinated bottle exporters to requalify material streams for non-EU destinations. The industrial consequence is bifurcated production lines where EU-facing output requires distinct resin sourcing and process documentation compared to Americas or Asia-Pacific shipments. Agrochemical distributors in France and Benelux face the tightest compliance timelines as ECHA substance evaluation deadlines approach.
Pharmaceutical procurement teams are consolidating supplier panels around converters with dual FDA-EMA manufacturing site certifications. This concentration displaces regional packaging distributors who previously intermediated between local bottle converters and drug formulation facilities. The shift is most visible in North American generic drug manufacturing corridors where CVS Caremark and Walgreens Boots Alliance purchasing power forces direct manufacturer relationships.
Fluorinated Bottle Market Segmentation
Fluorinated bottle segmentation reflects divergent barrier requirements across pharmaceutical purity tiers and chemical resistance specifications. Material selection and packaging geometry determine compliance pathways against FDA extractables standards and EPA emission controls.
Product Type:
Mature blow-molding infrastructure dominates commodity polymer segments while engineered alternatives carve niche positions in oxygen-sensitive applications.
- HDPE Bottles:High-density polyethylene provides the dominant substrate for fluorination treatment due to established extrusion-blow molding lines and favorable fluorine gas diffusion kinetics during surface modification. German specialty chemical clusters and North American agrochemical corridors drive concentrated demand for HDPE-based barrier packaging in solvent storage applications. HDPE bottles retain volume leadership; PET bottles hold the steepest expansion curve.
- PET Bottles:Polyethylene terephthalate offers superior clarity and mechanical strength for pharmaceutical visibility requirements, though fluorination compatibility demands modified process parameters to prevent chain scission during surface treatment. Cosmetic and over-the-counter pharmaceutical brands in France and Benelux specify PET for premium positioning where bottle aesthetics support brand differentiation.
- Glass Bottles:Borosilicate and soda-lime glass containers serve ultra-high-purity biologics where zero permeation tolerance overrides cost considerations, particularly in parenteral drug storage.
- Aluminum Bottles:Metal containers provide absolute barrier performance for volatile organic compound storage in industrial chemical distribution.
- PP Bottles:Polypropylene offers elevated temperature resistance for autoclave-sterilized pharmaceutical applications, though fluorination uniformity challenges limit adoption relative to HDPE.
Cost tier stratification separates commodity HDPE from premium glass and metal alternatives, with PET occupying the mid-tier clarity-performance position.
Application:
Regulatory compliance intensity varies sharply across end-use sectors, with pharmaceutical validation requirements creating the highest barrier to supplier entry.
- Pharmaceuticals:Oral liquid and parenteral drug packaging demands batch-level oxygen transmission rate documentation under FDA container closure integrity guidance, favoring converters with validated manufacturing records and dual FDA-EMA site certifications. CDSCO alignment with ICH Q3D guidelines in India creates certified supplier gaps that documented manufacturers can exploit.
- Chemical Storage:Active pharmaceutical ingredient handling and specialty solvent storage in Germany's Rhine-Neckar corridor require high-purity fluorinated barriers to prevent oxidative degradation and VOC migration.
- Food & Beverage:Flavor and aroma preservation applications specify fluorinated barriers for sensitive edible oil and concentrate packaging, though food-contact regulatory pathways lag pharmaceutical validation maturity.
- Personal Care:Cosmetic fine-mist applications demand precise dose control with zero leakage, expanding addressable market beyond traditional screw-cap formats.
- Agriculture:Pesticide and herbicide storage concentrates seasonal demand patterns tied to planting cycles, with EPA emission capture requirements influencing converter equipment investments.
Pharmaceutical applications anchor value concentration; personal care represents the fastest-climbing demand trajectory.
End User:
Procurement consolidation around direct manufacturer relationships is displacing traditional distributor intermediation, particularly in North American generic drug manufacturing corridors.
- Contract Manufacturers:Generic pharmaceutical firms drive specification standardization as CVS Caremark and Walgreens Boots Alliance purchasing power forces validated supplier panels with dual-certification manufacturing sites.
- Packaging Providers:Integrated converters with multi-layer co-injection capabilities capture margin pools from recycled content integration while maintaining fluorinated barrier performance.
- Industrial Suppliers:Chemical distribution channels serve agrochemical and specialty solvent markets with volume-driven procurement emphasizing emission-compliant production.
- Retail Distributors:Regional packaging intermediaries face margin compression as pharmaceutical procurement teams consolidate around direct converter relationships.
Contract manufacturers command specification authority; packaging providers control technology differentiation.
Packaging Type:
Geometry determines functional performance in dose precision and barrier surface area optimization, with fine-mist formats commanding premium positioning.
- Spray Bottles:Fine-mist pharmaceutical and cosmetic applications require precise dose control with zero leakage, capturing premium margin pools through specialized actuator and fluorinated barrier integration.
- Dropper Bottles:Oral liquid pharmaceuticals and essential oil packaging specify controlled dispensing with minimal headspace oxygen exposure, favoring narrow-neck fluorinated designs.
- Wide Mouth Bottles:Powder and tablet handling in pharmaceutical manufacturing facilities prioritizes access convenience over barrier minimization.
- Amber Bottles:Light-sensitive API storage combines fluorinated oxygen barriers with UV-opaque coloration for dual protection.
- Cylinder Bottles:Standard industrial chemical storage formats optimize palletization efficiency in warehouse distribution.
Spray bottles capture premium pricing; dropper bottles expand most quickly in pharmaceutical oral liquid segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers in Germany, the United States, and India drive specification authority for fluorinated barrier packaging. Specialty chemical clusters in Belgium and Japan generate concentrated demand for high-purity storage solutions. Regulatory divergence across FDA, EMA, and CDSCO jurisdictions shapes converter qualification requirements.
United States
Generic pharmaceutical manufacturing corridors in New Jersey and North Carolina consolidate procurement around direct converter relationships. The FDA enforces container closure integrity guidance with batch-level oxygen transmission rate documentation. CVS Caremark and Walgreens Boots Alliance purchasing power forces validated supplier panels with dual-certification manufacturing sites.
Germany
The Rhine-Neckar and Antwerp-Rotterdam chemical corridors generate concentrated demand for high-purity fluorinated storage in active pharmaceutical ingredient handling. REACH restrictions on per- and polyfluoroalkyl substance classifications force exporters to requalify material streams for non-EU destinations. BASF and Merck KGaA manufacturing facilities in Ludwigshafen drive specification standards for barrier-validated packaging.
India
CDSCO alignment with ICH Q3D guidelines creates certified supplier gaps that documented manufacturers can exploit. Maharashtra and Gujarat pharmaceutical export zones drive demand for FDA-validated fluorinated bottles in oral liquid and parenteral formulations. Cipla and Sun Pharmaceutical contract manufacturing facilities in Mumbai and Ahmedabad prioritize converters with established regulatory documentation.
Belgium
Antwerp-Rotterdam port chemistry clusters require high-purity fluorinated barriers for specialty solvent storage and active pharmaceutical ingredient handling. ECHA substance evaluation deadlines approaching in 2025-2026 compress compliance timelines for agrochemical distributors. Solvay S.A. operations in Brussels anchor regional demand for emission-compliant fluorination equipment.
Japan
PMDA manufacturing site certification requirements favor converters with established quality systems for pharmaceutical packaging. Osaka and Tokyo metropolitan areas concentrate demand for fine-mist spray applications in cosmetic and over-the-counter pharmaceutical segments. Shiseido and Kao formulation facilities drive premium positioning for PET-based fluorinated bottles with aesthetic differentiation.
Fluorinated Bottle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. Thermo Fisher Scientific leverages laboratory-grade certification protocols to dominate life science packaging, while Plastipak Holdings sustains high-volume production lines across North American chemical corridors. The market structures around three archetypes: integrated laboratory suppliers with regulatory documentation depth, high-volume commodity converters with blow-molding scale, and precision barrier specialists with plasma-enhanced equipment. Competitive moves concentrate on dual FDA-EMA site certification acquisition and multi-layer co-injection platform deployment for recycled content integration.
Within the integrated laboratory supplier tier, Thermo Fisher Scientific exemplifies regulatory documentation depth. Among high-volume commodity converters, Plastipak Holdings Inc. and Berry Global Inc. occupy positions defined by blow-molding infrastructure scale and multi-layer co-injection capabilities respectively. These three companies represent the dominant competitive archetypes: certification-anchored laboratory suppliers, scale-driven North American converters, and technology-differentiated barrier specialists.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Plastipak Holdings Inc. |
| Berry Global Inc. |
| Greiner Packaging |
| Graham Packaging Company |
| Solvay S.A. |
| Corning Inc. |
| Alpha Packaging |
| Arkema Group |
| Others |
Supply & Pricing Matrix
Elemental fluorine supply concentration in five integrated chemical producers anchors margin capture upstream, while downstream converters face cost pass-through rigidities in pharmaceutical contract manufacturing. The pricing power asymmetry between fluorine gas suppliers and blow-molding converters intensifies during seasonal agricultural chemical demand spikes.
Pricing Analysis
Cost-plus contracts with elemental fluorine indexation dominate procurement between gas suppliers and conversion facilities. Three-tier pricing structure across plasma-enhanced barrier specialists, dual-certified pharmaceutical converters, and commodity HDPE blow-molders separates oxygen transmission rate performance tiers. Cost compression in standard HDPE bottles runs through recycled content integration mandates. Generic pharmaceutical contract manufacturers exhibit highest price sensitivity; biologics formulators show lowest sensitivity due to zero-permeation requirements.
Supply Chain Analysis
Tariff exposure between Germany and non-EU pharmaceutical export destinations dominates supply chain risk planning for REACH-compliant converters. Manufacturing concentration rests on Germany, the United States, and China for fluorination equipment and barrier resin supply. Raw material dependencies draw from elemental fluorine, HDPE resin, and plasma treatment gases. Single-source vulnerability concentrates in fluorine gas production. Distribution runs through direct converter relationships with pharmaceutical procurement teams, displacing regional packaging intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass and metal substitution in ultra-high-purity biologics threatens polymer barrier incumbents with volume erosion at the premium tier. Incumbents must navigate this substitution defense while consolidating regulatory documentation advantages.
For Market Incumbents: Pre-empt plasma-enhanced fluorination equipment shortages by securing electrochemical surface treatment talent from semiconductor equipment suppliers. Backward integration into closed-loop fluorine recovery systems reduces EPA compliance exposure while locking in emission permit availability. Dual FDA-EMA site certification investments defend against procurement panel consolidation by CVS Caremark and Walgreens Boots Alliance.
For New Entrants and Emerging Players: Indian pharmaceutical export zones offer certified supplier gaps under CDSCO-ICH Q3D alignment that documented manufacturers can exploit. Fine-mist spray applications in cosmetic and over-the-counter segments present white-space expansion beyond traditional screw-cap formats. Partnership with Maharashtra and Gujarat contract manufacturers provides fastest go-to-market validation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision barrier specialists holding plasma-enhanced equipment but lacking dual-certification manufacturing sites. Long-term viability hinges on regulatory documentation depth rather than blow-molding scale alone. Watch for ECHA substance evaluation deadline compliance failures as inflection indicators for stranded inventory risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual FDA-EMA Site Certification | Pharmaceutical procurement consolidation by CVS Caremark and Walgreens Boots Alliance demands validated manufacturing records. |
| Plasma-Enhanced Fluorination Equipment Deployment | Hybrid gas-liquid surface treatment reduces fluorine consumption and shortens batch cycle times for generic drug contractors. |
| Closed-Loop Fluorine Recovery Systems | EPA American Innovation and Manufacturing Act enforcement drives emission-capture adoption for permit availability. |
| Multi-Layer Co-Injection Platform Investment | Post-consumer HDPE incorporation maintains barrier performance against oxygen transmission requirements. |
| Electrochemical Surface Treatment Talent Acquisition | Semiconductor equipment suppliers concentrate plasma process engineering expertise, creating recruitment competition. |
Research Methodology
Desk research of FDA container closure guidance documents, EPA emission compliance filings, and REACH substance classification databases preceded structured interviews with pharmaceutical packaging procurement managers, fluorination equipment operators, and regulatory affairs specialists. Primary fieldwork with contract manufacturing executives and secondary validation against ECHA evaluation timelines and customs trade data enabled bottom-up volume triangulation with top-down market sizing.
Fixed assumptions held regulatory enforcement intensity and fluorine gas supply concentration constant across the projection horizon, while plasma equipment adoption rates and recycled content integration thresholds varied. Segmentation modeling spanned material substrate, barrier performance tier, end-use application, and regional regulatory cluster. CAGRs derived from weighted average of historical volume trajectories and equipment installation pipeline analysis.
Practitioners should monitor ECHA substance evaluation outcomes and state-level PFAS legislation amendments for early signals of material qualification disruption. Forecasts reflect assumptions about regulatory stability and elemental fluorine supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market