
 Italy Food Safety Testing Market | 2026-2036
Italy Food Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Safety Testing Market Foresight
Food service providers is rotating toward third-party laboratory partnerships as restaurant chains and institutional caterers face tightened liability exposure. Bureau Veritas leverages its pan-European accreditation network to anchor multi-site contract wins across northern Italy. Eurofins Scientific competes through specialized mycotoxin and allergen panels tailored to Mediterranean grain and olive oil supply chains. SGS AG extends its footprint in organic certification, a segment where Italian exporters require dual EU and private-standard validation.
Italy food safety testing encompasses analytical protocols that detect microbiological pathogens, chemical residues, nutritional composition, and physical contaminants in food matrices, employing methods with detection thresholds measured in parts per billion to verify compliance with maximum residue limits and hygiene criteria. Microbiological testing dominates routine volume as Salmonella, Listeria, and E. coli screening remains mandatory across dairy, meat, and ready-to-eat categories under EC 2073/2005. PCR testing captures premium pricing through same-day pathogen confirmation, displacing slower culture-based methods in high-velocity supply chains. Chromatography anchors chemical and contaminant workflows, particularly for pesticide and veterinary drug residue quantification where regulatory thresholds tighten periodically.
EU Regulation 2073/2005 on microbiological criteria for foodstuffs and EU Regulation 396/2005 on pesticide residues structure mandatory testing frequencies and method performance requirements, directly shaping laboratory capacity planning and capital equipment procurement across Italian testing facilities. Italy's National Reference Laboratory system under ISS coordinates method harmonization and proficiency testing, reinforcing technical barriers for non-accredited entrants. Stakeholders must monitor the EU Green Deal's Farm to Fork strategy for emerging contaminant categories and digital traceability mandates that will redefine data infrastructure investments.
Market Dynamics
PCR-based pathogen diagnostics is compressing turnaround times from days to hours across Italian dairy and meat processing corridors, forcing laboratories to retire culture-based workflows and retrain technicians.
Growth Catalysts
- EU Regulation 2073/2005:Mandatory Salmonella, Listeria, and E. coli screening across ready-to-eat categories sustains baseline testing volumes for Italian laboratories serving dairy and meat processors.
- Processed meat clusters in Lombardy and Emilia-Romagna:Geographic concentration of high-velocity supply chains creates concentrated demand for same-day pathogen confirmation services.
- Digital traceability mandates under Farm to Fork:The EU Green Deal strategy requires upgraded data infrastructure investments, expanding laboratory information management system procurement.
Market Restraints
- Capital equipment intensity:Real-time PCR platforms and chromatography systems require substantial upfront investment, squeezing smaller regional laboratories.
- Proficiency testing barriers:Italy's National Reference Laboratory system under ISS coordinates method harmonization, creating technical entry barriers for non-accredited facilities.
- Skilled technician scarcity:Molecular biology expertise for PCR diagnostics concentrates in northern industrial regions, limiting service expansion into southern provinces.
Strategic Opportunities
- Organic certification dual validation:Italian exporters require both EU and private-standard validation, creating specialized service demand that SGS AG and Bureau Veritas currently capture.
- Mycotoxin panels for Mediterranean grains:Climate-induced fungal contamination in wheat and maize supply chains drives specialized testing demand outside traditional pathogen screening.
- Third-party laboratory partnerships:Restaurant chains and institutional caterers facing tightened liability exposure rotate toward external testing relationships rather than in-house capabilities.
Industry Challenges
- Legacy culture-based workflow retirement:Technicians require retraining for molecular diagnostics, creating operational friction during platform transitions.
- Accreditation timeline compression:ISO 17025 certification and pan-European accreditation network integration demand extended compliance preparation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Safety Testing Market |
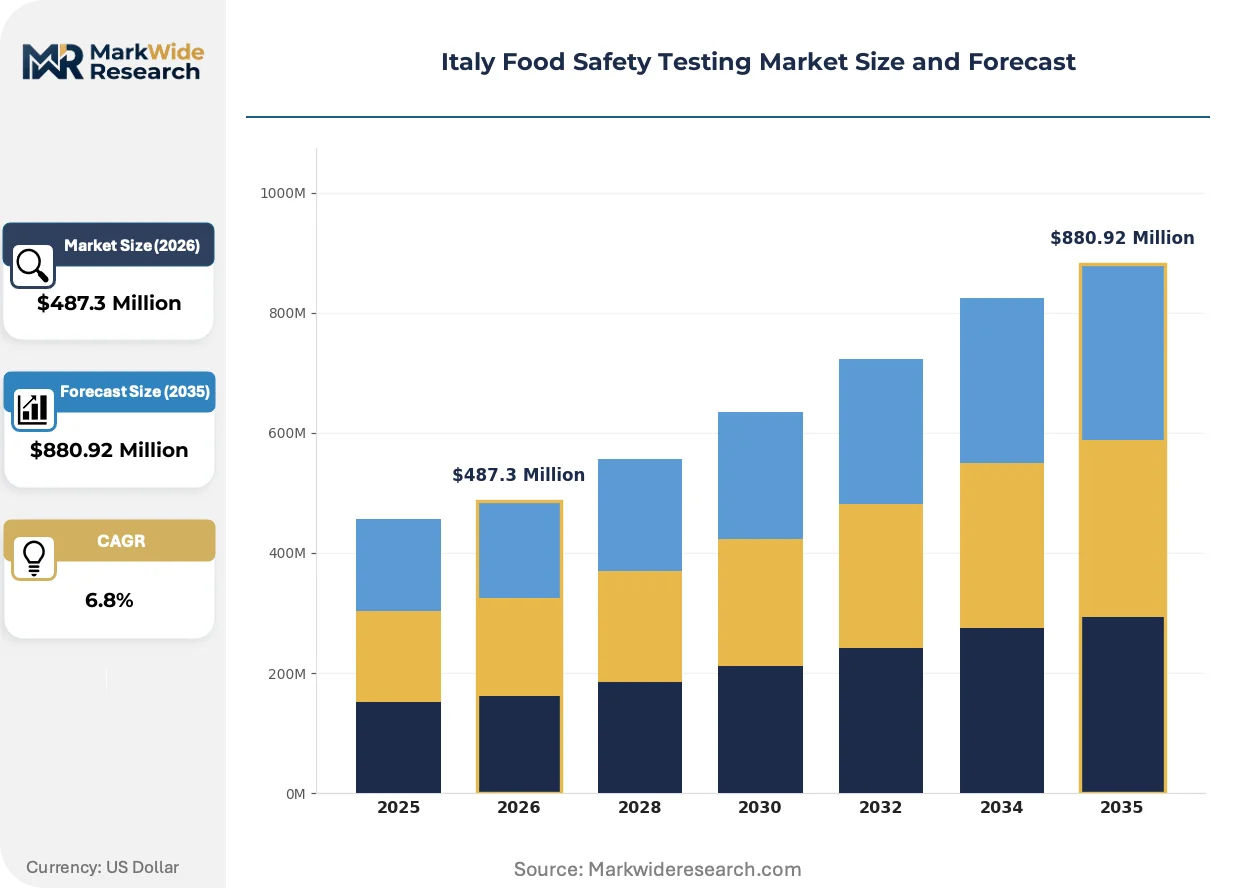
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbiological Testing, Chemical Testing, Nutritional Testing, Contaminant Testing End User: Food Manufacturers, Retailers, Food Service Providers, Regulatory Agencies Technology: PCR Testing, Rapid Testing, ELISA, Chromatography Application: Meat Safety, Dairy Safety, Seafood Safety, Produce Safety |
| Companies Covered | Merieux NutriSciences, Bureau Veritas, Eurofins Scientific, Intertek Group PLC, ALS Limited, Chemiservice S.r.l, NSF International, NEOTRON Societa per Azioni, SGS AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Safety Testing Market Shifts & Advancements
Italian food safety testing is pivoting from reactive compliance verification toward predictive contamination monitoring, with digital integration and accelerated molecular methods redefining laboratory competitive positioning.
Real-time PCR platforms is displacing traditional culture-based methods in high-throughput meat and dairy facilities. Large processors in Emilia-Romagna adopt same-day pathogen confirmation to maintain cold chain velocity. This compression of diagnostic timelines is displacing smaller laboratories lacking capital for platform upgrades.
EU Green Deal's Farm to Fork strategy mandates expanded contaminant surveillance and digital traceability infrastructure. Italian facilities must retrofit data management systems to capture batch-level testing records for export compliance. Organic certification and dual-standard validation requirements most heavily affect exporters targeting German and Swiss retail channels.
Food service procurement now favors outcome-based laboratory partnerships over transactional testing arrangements. Northern Italian restaurant chains and institutional caterers consolidate vendor relationships to reduce liability exposure. This vendor consolidation pattern appears most pronounced in Lombardy, where multi-site contract structures displace single-facility testing agreements.
Italy Food Safety Testing Market Segmentation
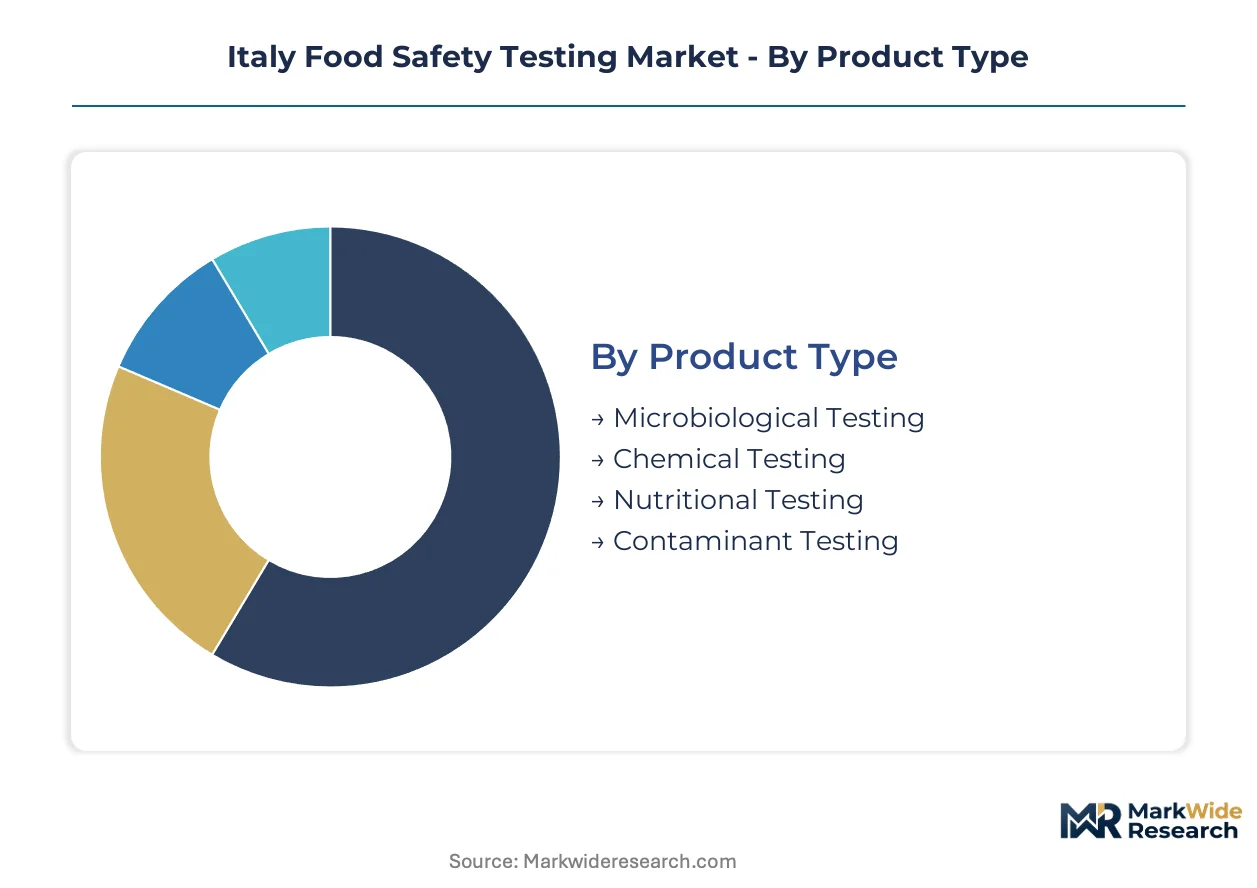
Italy's food safety testing market fragments across four analytical dimensions that reflect distinct margin structures, procurement patterns, and regulatory touchpoints. Each segmentation axis reveals where laboratories capture premium pricing versus commodity volume.
Product Type:
Margin pools concentrate in specialized contaminant detection where regulatory thresholds tighten fastest and method complexity sustains pricing power.
- Microbiological Testing:Pathogen screening for Salmonella, Listeria, and E. coli under EC 2073/2005 mandates dominates routine laboratory volume across Lombardy and Emilia-Romagna meat clusters. Same-day PCR confirmation commands premium pricing in high-velocity supply chains where cold chain integrity depends on rapid turnaround.
- Chemical Testing:Pesticide and veterinary drug residue quantification employs chromatography platforms with detection thresholds measured in parts per billion. Tightening EU Regulation 396/2005 maximum residue limits drives method investment in facilities serving export-oriented olive oil and wine producers.
- Nutritional Testing:Label verification and composition analysis supports packaged food compliance with EU food information regulations.
- Contaminant Testing:Mycotoxin and heavy metal detection addresses climate-induced fungal contamination in Mediterranean grain supply chains.
The dominant share belongs to microbiological testing, while chemical testing is closing the gap fastest as residue thresholds compress.
End User:
Procurement patterns diverge sharply between integrated manufacturers seeking captive capacity and externalizing food service operators.
- Food Manufacturers:Dairy and meat processors in northern Italy maintain in-house laboratories for high-frequency pathogen screening while outsourcing specialized contaminant panels. Capital intensity of real-time PCR platforms favors large facilities with throughput scale.
- Food Service Providers:Restaurant chains and institutional caterers rotate toward third-party laboratory partnerships as tightened liability exposure drives external risk transfer. Multi-site contract structures consolidate vendor relationships in Lombardy.
- Retailers:Private-label programs and import verification sustain baseline testing demand for shelf-stable and fresh categories.
- Regulatory Agencies:ISS-coordinated proficiency testing and National Reference Laboratory functions anchor method harmonization across accredited facilities.
Food manufacturers retain the largest procurement volume, though food service providers are expanding their share fastest through vendor consolidation.
Technology:
Platform selection directly determines turnaround economics and technician skill requirements.
- PCR Testing:Real-time pathogen confirmation compresses diagnostic timelines from days to hours. Large Emilia-Romagna processors adopt same-day workflows to maintain supply chain velocity, displacing smaller laboratories lacking capital for platform upgrades.
- Chromatography:LC-MS and GC-MS systems anchor chemical residue quantification where regulatory thresholds demand parts-per-billion sensitivity. Equipment intensity creates barriers for regional laboratories.
- Rapid Testing:Lateral flow and immunoassay formats serve point-of-need screening with lower capital requirements but reduced sensitivity.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective allergen and mycotoxin detection for mid-scale processors.
PCR testing commands the highest revenue per test, while rapid testing formats are gaining adoption fastest among smaller southern Italian facilities.
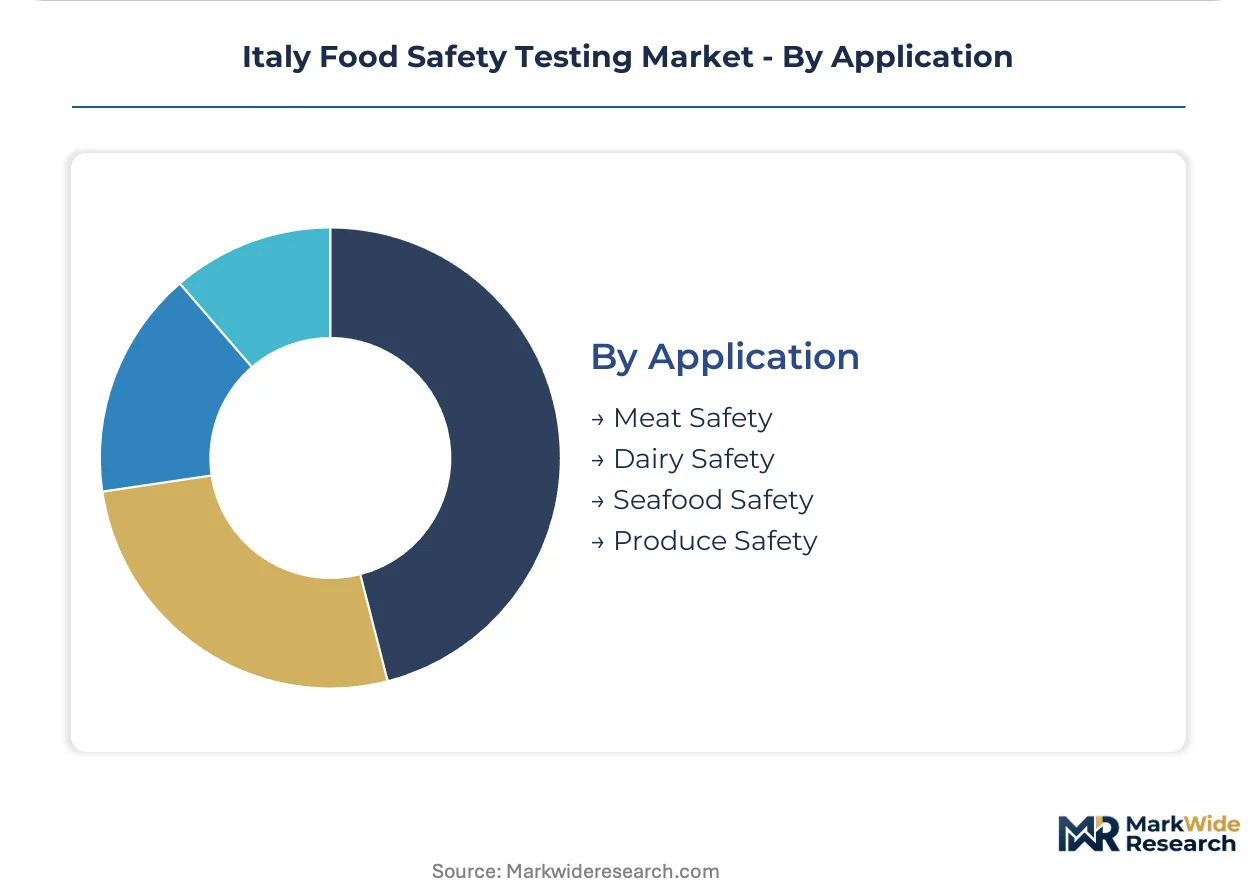
Application:
Category-specific hazard profiles shape method selection and testing frequency.
- Meat Safety:Salmonella and Listeria screening dominates high-throughput pork and poultry processing in Lombardy. Cold chain velocity demands same-day pathogen confirmation unavailable through culture-based methods.
- Dairy Safety:E. coli and Staphylococcus aureus monitoring sustains baseline volume across Parmigiano-Reggiano and mozzarella production corridors in Emilia-Romagna and Campania.
- Seafood Safety:Histamine and biotoxin detection serves Adriatic and Tyrrhenian fishing fleets with seasonal demand concentration.
- Produce Safety:Pesticide residue panels address export requirements for Sicilian citrus and Puglia vegetables targeting German and Swiss retail channels.
Meat safety captures the dominant application share, while produce safety is climbing the fastest as export compliance requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Genoa anchors Italy's food export infrastructure, connecting Emilia-Romagna processing clusters to German and Swiss retail channels through refrigerated container corridors.
Lombardy
Milan's financial and logistics hub concentrates third-party laboratory demand from restaurant chains and institutional caterers. EC 2073/2005 mandates sustain high-frequency Salmonella and Listeria screening across pork and poultry processing facilities in the Po Valley corridor. Cold chain velocity requirements favor PCR-based same-day confirmation services over traditional culture methods.
Emilia-Romagna
Parma's cured meat and cheese production anchors the densest pathogen testing cluster in southern Europe. The region's National Reference Laboratory coordination under ISS reinforces technical barriers for non-accredited entrants. Large processors in Modena and Bologna adopt real-time PCR platforms to maintain supply chain throughput.
Veneto
Verona's wine and grain trading hub drives specialized mycotoxin panel demand for export-bound Mediterranean wheat. EU Regulation 396/2005 tightening of pesticide residue thresholds accelerates chromatography investment among regional laboratories. Padua's agricultural research institutes anchor method development partnerships with commercial testing facilities.
Campania
Naples' mozzarella and tomato processing corridors sustain baseline microbiological testing volume despite infrastructure constraints. The region's technician scarcity for molecular diagnostics limits PCR service expansion compared to northern counterparts. Southern exporters rely on accredited northern laboratories for dual-standard organic certification validation.
Piedmont
Turin's chocolate and confectionery manufacturers anchor allergen and nutritional testing demand for EU food information regulation compliance. The region's proximity to Swiss retail channels intensifies private-standard validation requirements beyond baseline EU mandates. Alba's hazelnut processing cluster drives specialized contaminant surveillance for aflatoxin detection.
Italy Food Safety Testing Market Competitive Landscape
Listed leaders compete with private specialists across accreditation depth and geographic coverage. The market structure consolidates around pan-European networks with ISO 17025 certification, while regional laboratories survive through specialized contaminant panels. Three archetypes dominate: pan-European accreditation networks, Mediterranean supply chain specialists, and organic certification dual-validators. M&A activity concentrates on acquiring regional accreditation assets, while strategic partnerships target digital traceability platform integration.
Within the pan-European network tier, Bureau Veritas and SGS AG occupy positions defined by multi-site contract structures across northern Italy. Eurofins Scientific exemplifies the Mediterranean specialist archetype through its positioning in grain and olive oil supply chains. These three entities represent the dominant competitive anchors, with Bureau Veritas leveraging its accreditation breadth, SGS AG capturing organic certification demand, and Eurofins Scientific concentrating method expertise in climate-induced contamination categories.
| Leading Market Players |
|---|
| Merieux NutriSciences |
| Bureau Veritas |
| Eurofins Scientific |
| Intertek Group PLC |
| ALS Limited |
| Chemiservice S.r.l |
| NSF International |
| NEOTRON Societa per Azioni |
| SGS AG |
| Others |
Supply & Pricing Matrix
Same-day PCR confirmation lead times of 4-6 hours concentrate pricing power among accredited laboratories in Lombardy and Emilia-Romagna, while southern facilities face margin compression from extended logistics cycles and technician scarcity. This lead-time differential reinforces a two-tier supply structure where northern clusters capture premium pathogen screening contracts.
Pricing Analysis
Volume-discount tiering structures separate large Emilia-Romagna meat processors receiving contracted per-batch rates from small southern olive oil producers paying spot prices for mycotoxin panels. Price differentiation hinges on ISO 17025 accreditation status and pan-European network coverage. Pricing pressure intensifies in routine microbiological screening as real-time PCR platform saturation in northern Italy compresses margins for culture-based competitors. Small regional laboratories exhibit highest price sensitivity, while export-oriented organic certification clients demonstrate lowest sensitivity due to dual-standard validation requirements.
Supply Chain Analysis
Reagent inventory cycles of 30-45 days tether Italian laboratories to German chromatography consumable suppliers and American PCR platform manufacturers. The supply chain draws from precision instrumentation clusters in Germany, the Netherlands, and Switzerland for chromatography systems, plus specialized reagent production in the United States and United Kingdom. Single-source vulnerability concentrates in real-time PCR thermal cycler components where replacement part lead times extend operational risk. Distribution runs through pan-European logistics networks anchored at Milan's pharmaceutical hub and Genoa's port infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy food safety testing operates within a cyclical recovery phase as EU Green Deal implementation accelerates laboratory infrastructure replacement cycles deferred during prior compliance periods.
For Market Incumbents: Secure accreditation breadth expansion into Farm to Fork digital traceability certification before regulatory mandates harden technical barriers. Consolidate multi-site contract structures across Lombardy restaurant chains to preempt competitor entry. Counter technician scarcity through automated PCR workflow investment that reduces molecular biology headcount dependence. For New Entrants and Emerging Players: Differentiate on mycotoxin specialization for climate-stressed Mediterranean grain supply chains where incumbent coverage remains thin. Target Campania and Puglia processing corridors for third-party laboratory partnerships, exploiting the technician scarcity that limits incumbent PCR service expansion. Pursue outcome-based vendor relationships with institutional caterers seeking liability transfer rather than transactional testing. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned regional laboratories holding ISO 17025 accreditation but lacking capital for real-time PCR platform migration. Long-term viability favors facilities with dual EU-private standard organic certification capabilities and established relationships with German retail channel exporters. Monitor EU Green Deal digital traceability mandate implementation timelines as the inflection signal for laboratory information management system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Network Expansion | Bureau Veritas leverages pan-European ISO 17025 coverage to capture multi-site contracts across northern Italy. |
| Specialized Contaminant Panel Development | Eurofins Scientific targets climate-induced mycotoxin surveillance in Mediterranean grain supply chains. |
| Digital Traceability Platform Integration | SGS AG positions for Farm to Fork batch-level data infrastructure mandates affecting export compliance. |
| Third-Party Laboratory Partnership Consolidation | Restaurant chains in Lombardy externalize pathogen screening liability through vendor consolidation. |
| Technician Training Program Investment | Regional laboratories address molecular biology skill scarcity limiting PCR service expansion southward. |
Research Methodology
The analysis maps microbiological, chemical, nutritional, and contaminant testing sub-sectors, each validated through laboratory operations directors, regulatory compliance officers at food manufacturers, third-party certification auditors, and procurement managers at restaurant chains. Primary interview insights triangulate against ISS proficiency testing records, EU Regulation 2073/2005 implementation guidance, EFSA scientific opinions, and Italian customs export certification data. Bottom-up facility capacity modeling reconciles with top-down market value estimation across segmentation dimensions.
Consistency checks validated volume and value outputs against external benchmarks including pan-European laboratory accreditation databases and food processing industry production statistics. The analytical framework segments by product type, end user, technology platform, and application category across the projection horizon. CAGRs derive from facility-level throughput assumptions, equipment replacement cycles, and regulatory mandate implementation schedules. Forecast inputs incorporate PCR platform adoption curves and Farm to Fork digital infrastructure investment timelines.
Material uncertainties — regulatory timeline delays, technician training program effectiveness, and reagent supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about EU Green Deal implementation pace and accreditation harmonization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Bottled Water Testing Equipment Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Shelf-Life Testing Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Salt Meter Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Rapid Microbiology Testing Market