
 Mercury Testing Service Market | 2026-2036
Mercury Testing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Mercury Testing Service Market Intelligence
The Minamata Convention on Mercury is repositioning the compliance landscape for industries from power generation to cement production. This international treaty creates a baseline for mercury emission controls, driving consistent testing demand. SGS SA leverages its expansive global laboratory network to serve multinational clients across diverse regulatory environments. Eurofins Scientific specializes in high-sensitivity analysis for food safety and pharmaceutical applications, while Intertek Group sustains its market presence through integrated on-site and laboratory services for industrial facilities.
Mercury testing service involves the quantification of mercury in various matrices, including water, soil, air, and biological samples. These services utilize analytical techniques capable of detecting mercury concentrations down to parts-per-trillion levels to ensure regulatory compliance and public safety. The environmental monitoring application constitutes the largest segment, driven by government mandates for air and water quality. Within technology, Cold Vapor Atomic Fluorescence and Atomic Absorption Spectrometry remain standard methods, though Inductively Coupled Plasma Mass Spectrometry is gaining share for complex sample analysis.
Regulatory frameworks established by the US Environmental Protection Agency (EPA), Europe's ECHA, and China's Ministry of Ecology and Environment (MEE) set stringent mercury emission limits. These regulations mandate specific testing protocols and frequencies, creating a non-discretionary demand for accredited laboratory services. Service providers must continually invest in technology to meet ever-lower detection thresholds and adapt to new substance-of-concern listings.
Market Dynamics
The market's structure is defined by the Minamata Convention on Mercury, which converts environmental policy into non-discretionary, recurring demand for accredited testing across industrial sectors like power generation and manufacturing.
Growth Catalysts
- Minamata Convention Implementation:The ongoing national-level ratification and enforcement of this treaty compels signatory countries to establish monitoring programs for mercury emissions, directly stimulating demand for testing services in industrial and environmental sectors.
- Industrial Activity in Asia:The concentration of coal-fired power generation, cement manufacturing, and chemical production in China and India creates significant, localized demand for mercury emissions testing to comply with national standards like those from the MEE.
- Analytical Technology Advancement:The increasing sensitivity of instruments like Cold Vapor Atomic Fluorescence Spectrometry enables detection at lower concentrations, aligning with progressively stricter regulatory limits set by agencies such as the US EPA.
Market Restraints
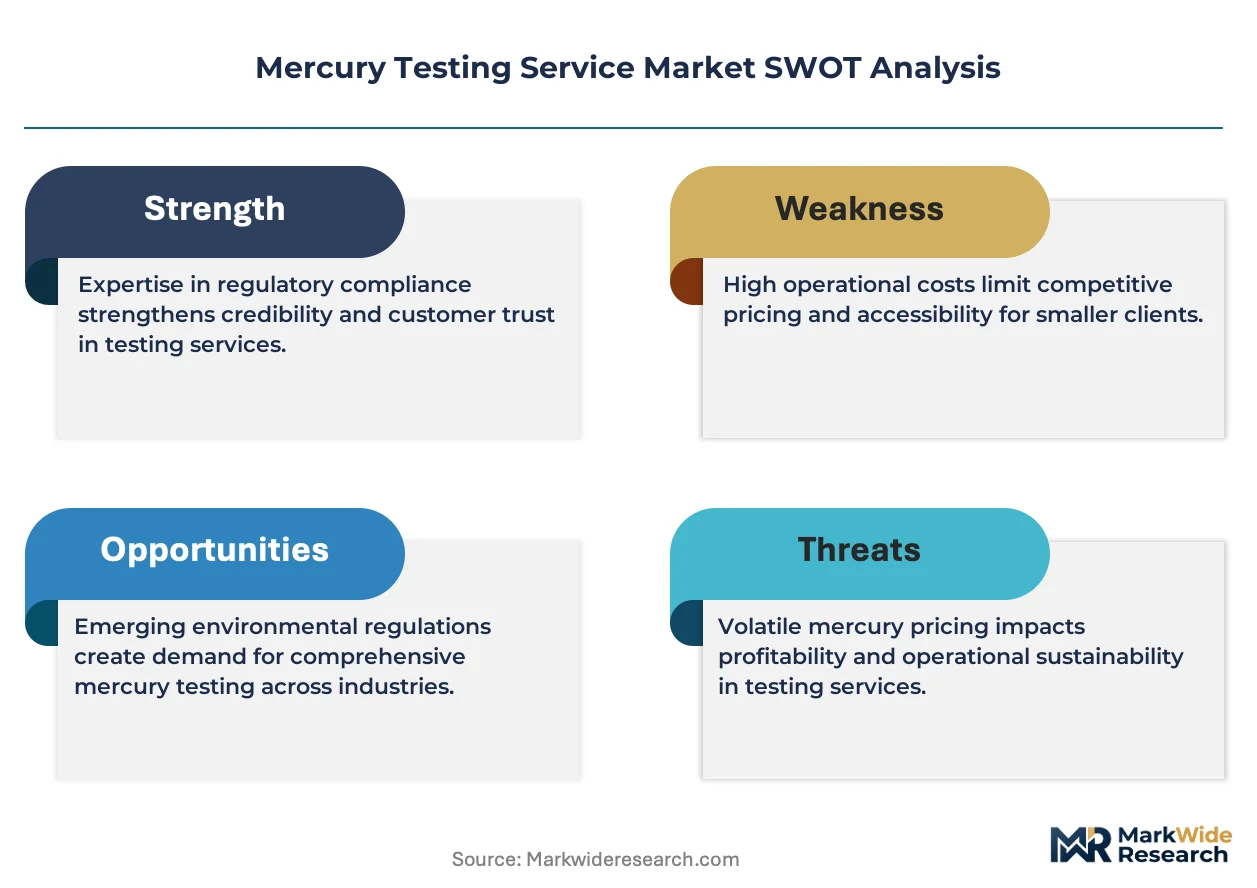
- High Capital Investment:The significant cost of acquiring and maintaining advanced analytical instruments, such as Inductively Coupled Plasma Mass Spectrometry (ICP-MS) systems, presents a substantial barrier to entry for smaller, independent laboratories.
- Sample Matrix Complexity:The presence of interfering substances in complex environmental samples like industrial sludge, soil, or wastewater can compromise analytical accuracy, requiring extensive and costly sample preparation protocols.
- Energy Transition Dynamics:A structural shift away from coal-fired power generation toward natural gas and renewable energy sources in regions like Europe incrementally reduces the volume of flue gas testing required from that specific sector.
Strategic Opportunities
- Geographic Expansion:Under-regulated industrializing economies in Southeast Asia, such as Vietnam and Indonesia, represent significant long-term growth potential as they begin to implement more stringent environmental laws aligned with global standards.
- Emerging Applications:The testing of consumer products, including cosmetics, traditional medicines, and seafood for mercury contamination, provides a new service avenue outside of traditional industrial emissions monitoring.
- On-Site Screening Technologies:Developing portable, rapid-screening instruments allows for preliminary field analysis, creating a new service tier that complements definitive, high-complexity testing performed in a central laboratory.
Industry Challenges
- Skilled Personnel Shortage:A scarcity of qualified analytical chemists and technicians with expertise in operating and troubleshooting sophisticated spectrometry equipment constrains laboratory throughput and expansion capabilities.
- Lack of Method Harmonization:Discrepancies in mandated sampling techniques and analytical protocols between different regulatory jurisdictions, such as between US EPA and ECHA methods, create operational complexities for global service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercury Testing Service Market |
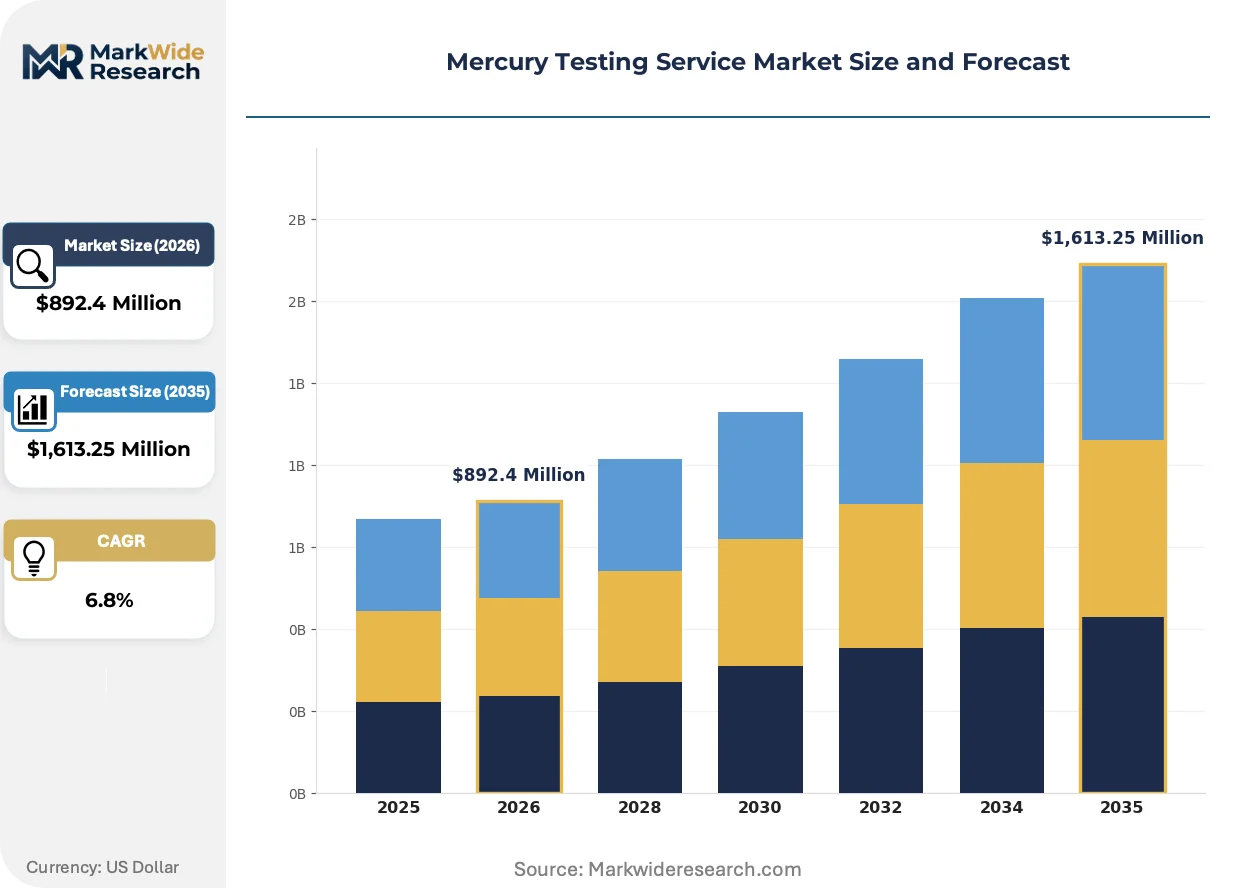
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laboratory Analysis, On-site Testing, Portable Analyzers, Sensor Calibration, Quality Assurance Application: Environmental Monitoring, Industrial Emission Control, Food Safety, Pharmaceutical Testing, Water Quality Assessment End User: Manufacturing Plants, Research Institutes, Government Agencies, Environmental Consultancies, Food Processing Units Technology: Atomic Absorption Spectrometry, Cold Vapor Atomic Fluorescence, Inductively Coupled Plasma, Gas Chromatography, Mass Spectrometry |
| Companies Covered | SGS SA, Bureau Veritas, Eurofins Scientific, Intertek Group, ALS Limited, SOCOTEC Group, Pace Analytical Services, Advanced Environmental Laboratory, TestAmerica Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercury Testing Service Market Strategic Shifts & Innovations
Technological advancements and tightening regulatory oversight are transforming mercury testing from a compliance task into a component of proactive environmental risk management. This evolution prioritizes analytical precision and data integration over simple pass-fail results.
Inductively Coupled Plasma Mass Spectrometry provides ultra-sensitive detection of mercury and other trace elements. Environmental and food safety laboratories adopt ICP-MS for its efficiency in handling high sample volumes. This technology is expanding into the analysis of complex biological matrices, previously the domain of dedicated, single-element analyzers.
Europe's ECHA enforces stringent mercury limits under the REACH regulation, restricting its use in products and processes. This creates a continuous need for verification testing in supply chains for electronics and chemicals. The manufacturing sector is most impacted, integrating compliance testing into its quality management systems.
Clients are bundling services into broader environmental monitoring contracts rather than procuring them on a per-sample basis. This shift displaces transactional purchasing with long-term service agreements managed by integrated laboratory networks. The trend is most visible within multinational mining and petrochemical industries seeking standardized global compliance.
Mercury Testing Service Market Segmentation
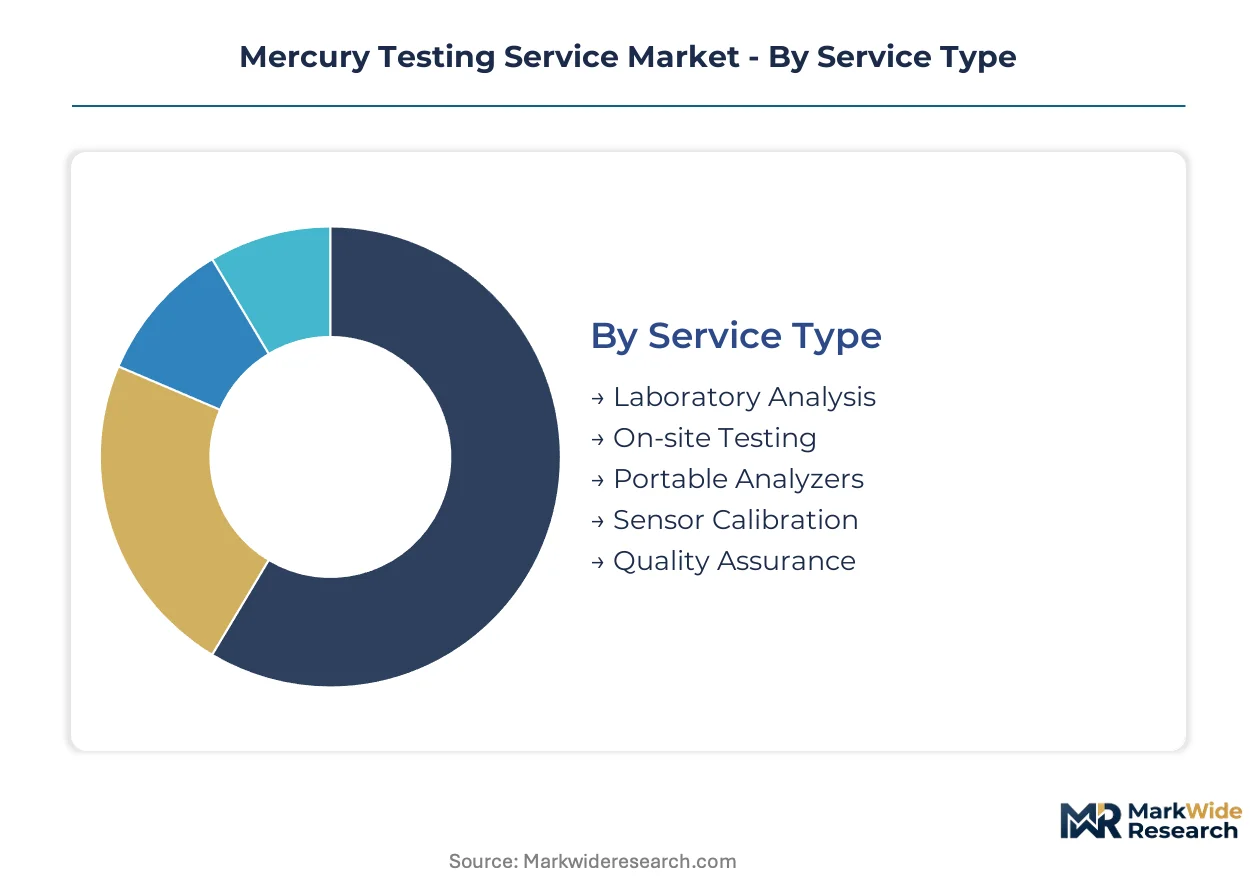
The Mercury Testing Service Market segments across diverse operational and technological dimensions, reflecting the varied requirements of industrial clients and regulatory bodies. Understanding these segmentations helps service providers tailor their offerings to specific compliance needs and analytical challenges.
Service Type:
Buyers of mercury testing services prioritize the delivery mechanism and depth of analysis for their specific operational needs.
- Laboratory Analysis:This service involves sending samples to a central facility for definitive, high-precision quantification of mercury using advanced instrumentation. Demand concentrates from multinational corporations requiring certified results for regulatory reporting to the US EPA and Europe's ECHA.
- On-site Testing:Technicians perform rapid preliminary mercury assessments directly at industrial facilities or environmental sites using portable equipment. This service is critical for immediate compliance checks and initial screening in manufacturing plants and power generation sites in China.
- Portable Analyzers:These are compact, handheld devices enabling quick, qualitative or semi-quantitative mercury detection in the field, often used for preliminary screening.
- Sensor Calibration:This involves regularly adjusting and verifying the accuracy of mercury detection sensors deployed for continuous monitoring applications.
- Quality Assurance:Services ensuring the reliability, accuracy, and comparability of mercury testing results through method validation and inter-laboratory comparisons.
Laboratory Analysis leads on scale; On-site Testing leads on momentum.
Application:
The specific application dictates the required analytical precision and regulatory compliance standards for mercury detection.
- Environmental Monitoring:This application involves the systematic measurement of mercury levels in air, water, and soil to assess ecosystem health and human exposure risks. Government mandates from the US EPA and China's MEE drive consistent demand for this segment.
- Industrial Emission Control:Services focused on monitoring mercury releases from industrial sources, such as coal-fired power plants and cement factories, to ensure compliance with emission limits set by the Minamata Convention. This segment experiences high demand in industrial zones across India.
- Food Safety:Testing of food products, particularly seafood, for mercury contamination to protect public health and ensure compliance with food safety regulations.
- Pharmaceutical Testing:Analysis of pharmaceutical ingredients and finished products for trace mercury content, adhering to strict pharmacopoeial standards.
- Water Quality Assessment:Quantification of mercury in drinking water, wastewater, and surface water bodies to ensure public safety and ecological protection.
Environmental Monitoring remains critical for broad public safety; Industrial Emission Control drives consistent, mandated demand.
End User:
End-users often select mercury testing services based on their operational scale and the stringency of their compliance obligations.
- Manufacturing Plants:Industrial facilities requiring mercury testing for emission compliance, wastewater discharge permits, and occupational safety. Demand is particularly high from chemical and electronics manufacturers in Germany and Japan.
- Government Agencies:Public sector entities responsible for environmental regulation, public health, and large-scale monitoring programs. Agencies like the US EPA and Europe's ECHA frequently procure these services for policy enforcement.
- Research Institutes:Academic and private research organizations conducting studies on mercury's environmental fate, transport, and toxicological effects.
- Environmental Consultancies:Firms providing specialized expertise in environmental impact assessments, permitting, and compliance strategies for various industries.
- Food Processing Units:Facilities involved in the production of food and beverages that require testing for mercury contamination in their raw materials or finished products.
Manufacturing Plants bear a heavy compliance burden; Food Processing Units represent an emerging area of public health concern.
Technology:
The choice of analytical technology depends on the required detection limits and the complexity of the sample matrix.
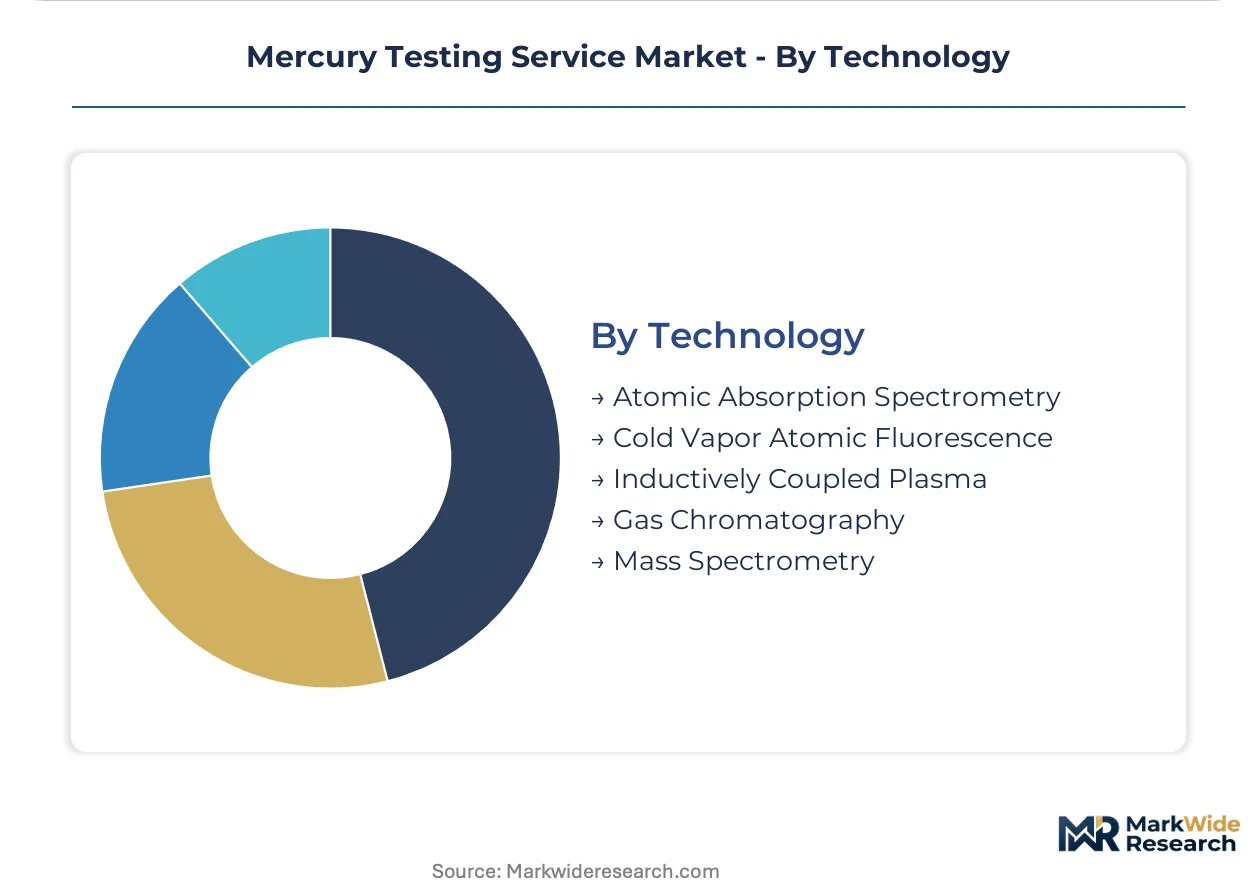
- Cold Vapor Atomic Fluorescence:This technique offers high sensitivity for mercury detection, capable of reaching parts-per-trillion levels, making it a standard method for environmental samples. This technology is widely adopted by laboratories serving regulatory bodies like the US EPA.
- Inductively Coupled Plasma:ICP-based techniques, particularly ICP-MS, provide ultra-sensitive, multi-element detection capabilities for complex matrices, gaining share in food safety and pharmaceutical analysis. Laboratories in Europe are increasingly adopting ICP-MS for its versatility.
- Atomic Absorption Spectrometry:A widely used and cost-effective method for mercury analysis, providing good sensitivity for many routine applications.
- Gas Chromatography:Primarily used for the speciation of mercury compounds, allowing for differentiation between various forms of mercury in samples.
- Mass Spectrometry:Often coupled with other techniques, mass spectrometry provides highly specific and sensitive detection and identification of mercury and its compounds.
Cold Vapor Atomic Fluorescence offers reliable precision; Inductively Coupled Plasma provides versatility for complex matrices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mercury testing service market's foundational demand emerged from industrialized nations addressing public health and environmental concerns. Early regulatory frameworks in Europe and North America established initial requirements for quantifying mercury in various matrices. This historical context shaped the initial development of specialized analytical services and technologies.
China
Chinese industries generate substantial demand for mercury testing due to extensive coal-fired power generation and manufacturing. The Ministry of Ecology and Environment (MEE) enforces strict emission limits, driving compliance. Industrial zones like the Yangtze River Delta require continuous monitoring of air and water discharges.
India
India's rapidly expanding industrial base, particularly in power generation and cement production, creates significant mercury testing demand. National standards from the Central Pollution Control Board (CPCB) mandate regular environmental assessments. Major industrial clusters in Gujarat and Maharashtra utilize these services for regulatory adherence.
United States
Demand in the United States stems from rigorous environmental protection laws targeting mercury emissions from various sectors. The US Environmental Protection Agency (EPA) sets comprehensive standards for air, water, and waste, ensuring public safety. Laboratories in states like California and Texas serve diverse industries from petrochemicals to manufacturing.
Germany
German manufacturing and chemical industries require precise mercury testing to comply with stringent European Union regulations. Europe's ECHA, under REACH, imposes strict limits on mercury in products and processes. Industrial hubs in North Rhine-Westphalia and Bavaria integrate testing into their quality management systems.
Vietnam
Vietnam's industrial growth, particularly in textile manufacturing and energy, is steadily increasing demand for mercury testing services. The country is aligning its environmental laws with international standards, influenced by the Minamata Convention. Emerging industrial parks near Ho Chi Minh City and Hanoi are investing in compliance infrastructure.
Mercury Testing Service Market Key Industry Players
Premium-margin players sit above commodity-margin players across service complexity and global reach. The market structure exhibits a tiered consolidation, with large multinational laboratories dominating the high-end, while regional specialists cater to localized needs. Strategic archetypes include global integrators, specialized analytical providers, and regional compliance partners. Dominant competitive moves involve geographic expansion into emerging markets and continuous investment in advanced analytical technologies.
On the premium-tier vector, SGS SA, Eurofins Scientific, and Intertek Group exemplify global reach and comprehensive service portfolios. These entities represent the multinational laboratory networks that provide certified mercury testing across diverse regulatory environments. They anchor the market for complex, high-sensitivity analysis and integrated environmental monitoring solutions.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas |
| Eurofins Scientific |
| Intertek Group |
| ALS Limited |
| SOCOTEC Group |
| Pace Analytical Services |
| Advanced Environmental Laboratory |
| TestAmerica Laboratories |
| Others |
Cost & Logistics Intelligence
Minamata Convention enforcement compels industries to adopt consistent mercury monitoring, which in turn drives demand for certified testing services. This regulatory mandate creates a stable pricing floor for accredited laboratories globally.
Pricing Analysis
Contract-based long-term agreements define the dominant pricing model for mercury testing services, especially for multinational industrial clients. Price differentiation stems from the required detection sensitivity and the level of regulatory certification needed, such as US EPA or ECHA compliance. Pricing pressure stems from increasing competition among accredited laboratories, particularly in high-volume industrial zones. Manufacturing plants purchasing routine compliance tests exhibit higher price sensitivity compared to pharmaceutical clients requiring ultra-trace analysis.
Supply Chain Analysis
Logistics costs for sample transport significantly influence the supply chain structure, favoring regional laboratory networks. Analytical instrument manufacturing concentrates in Germany, the United States, and Japan, which are critical for advanced ICP-MS and CV-AFS systems. The supply chain relies on specialized reagents and certified reference materials, often sourced from a limited number of global suppliers. Single-source vulnerability for high-purity standards presents a structural risk for laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mercury testing service market functions as a stable compounder, driven by the Minamata Convention's ongoing enforcement. This regulatory framework ensures consistent, non-discretionary demand across industrial sectors.
For Market Incumbents:Anchor global market share by expanding laboratory capacity in high-growth industrial zones like India and China. Pursue strategic acquisitions of smaller, regional specialists to consolidate market presence and mitigate margin pressure from new entrants. The skilled personnel shortage represents a significant threat to expansion capabilities. Investment in advanced analytical technology, particularly ICP-MS systems, remains a critical lever for maintaining service differentiation.
For New Entrants and Emerging Players:Begin with developing portable, rapid-screening technologies for on-site preliminary analysis. Target under-regulated industrializing economies in Southeast Asia, such as Vietnam, for initial market penetration. The emerging applications in consumer product testing, including cosmetics and seafood, represent a penetrable segment with growing demand. Offer bundled service packages to manufacturing plants, integrating basic compliance checks with rapid field assessments.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized analytical providers offering high-sensitivity testing solutions. The market exhibits long-term viability, driven by persistent regulatory tightening and expanding application scope. Acquisition targets should include mid-sized laboratories with strong regional footprints and advanced ICP-MS capabilities. The increasing adoption of Inductively Coupled Plasma Mass Spectrometry across diverse matrices serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion into Southeast Asia | This initiative captures demand from industrializing economies like Vietnam aligning with global environmental standards. |
| Investment in Portable Screening Technologies | Developing rapid on-site tools provides preliminary data for manufacturing plants, complementing definitive laboratory analysis. |
| Acquisition of Regional Laboratory Networks | Consolidating smaller labs enhances global service coverage and operational efficiencies for multinational clients. |
| Specialization in Ultra-Trace Mercury Analysis | Focusing on high-sensitivity techniques like ICP-MS addresses stringent limits for pharmaceutical and food safety applications. |
| Development of Standardized Global Testing Protocols | Harmonizing analytical methods reduces operational complexities for service providers operating across diverse regulatory jurisdictions. |
Research Approach
Direct dialogue with environmental compliance managers, laboratory directors, instrument manufacturers, and regulatory affairs specialists formed the qualitative grounding. This primary research was rigorously validated against extensive secondary data sources. These included US EPA publications, ECHA reports, China's MEE directives, and academic journals focusing on analytical chemistry. A comprehensive bottom-up and top-down triangulation approach ensured data consistency and accuracy.
A hybrid analytical framework, combining both bottom-up and top-down methodologies, structured the market sizing and forecasting across the analysis window. Segmentation dimensions modeled included service type, application, end-user, technology, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical market trends and projected regulatory impacts. Key forecast inputs included industrial production indices for China and India.
Caveats apply where unforeseen geopolitical events or rapid energy transition dynamics could materially shift the outlook. Forecasts reflect a specific set of macroeconomic and regulatory assumptions. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
North America Consumer Product Safety Testing Market