
 US Consumer Product Safety Testing Market | 2026-2036
US Consumer Product Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Consumer Product Safety Testing Market Insights
A capital-intensity divergence between full-service laboratories and specialized boutiques is rotating competitive dynamics across the US Consumer Product Safety Testing Market. UL leverages its captive NRTL status and in-house fire-safety infrastructure to dominate electrical testing for appliances and electronics. Intertek Group sustains geographic coverage through distributed laboratory networks in California, Texas, and North Carolina. Bureau Veritas differentiates through chemical testing leadership, particularly phthalate and heavy-metals analysis for toys and children's products.
Consumer product safety testing encompasses the systematic evaluation of physical, chemical, and electrical hazards in finished goods intended for household use, employing protocols such as ASTM F963 for toys, UL 60335 for appliances, and 16 CFR Part 1303 for lead content. The primary purpose is to verify compliance with CPSC mandatory standards and voluntary consensus standards before products enter US commerce. Chemical testing captures expanding margin pools as state-level regulations like California Proposition 65 multiply substance restrictions beyond federal baselines. Third-party testing services are accelerating fastest among service models, driven by retailer liability-shifting and Amazon's mandatory safety documentation requirements for marketplace sellers. In-house testing remains mature among large manufacturers with sufficient volume to amortize capital equipment, though many maintain dual-track validation through external laboratories.
The CPSC enforces mandatory standards and recall authority, while OSHA governs laboratory workplace safety during testing operations, and the EPA regulates chemical waste disposal from destructive test procedures. ASTM International and UL Standards develop the technical protocols that laboratories apply, creating a layered compliance architecture where multiple standards can apply to single products. Stakeholders must monitor how state-level chemical disclosure laws proliferate beyond federal harmonization, as this fragmentation multiplies testing burdens and opens service opportunities for laboratories with multi-jurisdiction expertise.
Market Dynamics
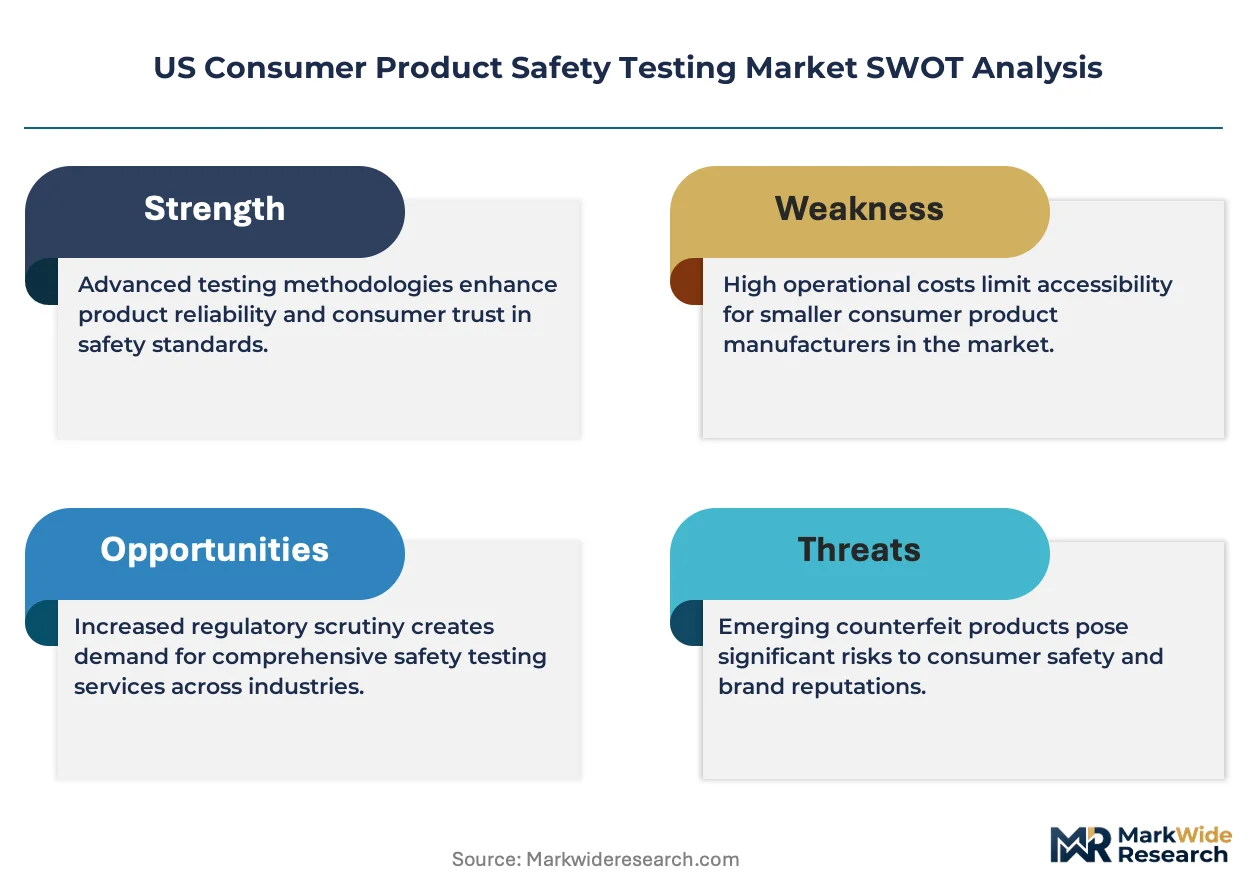
California Proposition 65 enforcement actions are forcing laboratories to expand chemical testing capacity beyond federal CPSC baselines, creating a two-tier compliance burden that favors multi-jurisdiction specialists over single-standard providers.
Growth Catalysts
- ASTM F963 Protocol Revisions:Updated mechanical and chemical testing requirements for toys are compelling manufacturers in California and Texas to expand validation budgets.
- Lithium-Ion Battery Certification:Electronics manufacturers now require comprehensive thermal runaway and abuse testing for portable power systems under UN 38.3 transport rules.
- Amazon Marketplace Mandates:Third-party sellers must submit CPSC-accepted test reports before listing children's products, converting voluntary testing into a channel-entry requirement.
Market Restraints
- Mass Spectrometer Supply Concentration:German and Japanese OEMs dominate high-resolution chemical analysis equipment, exposing US laboratories to 12-18 month delivery timelines.
- Phthalate Testing Cost Escalation:California's expanding Proposition 65 chemical list requires laboratories to maintain 200+ substance reference standards.
- Destructive Test Material Waste:EPA hazardous waste disposal rules for chemically treated product samples add 15-20% to total test cycle costs.
Strategic Opportunities
- North Carolina Laboratory Expansion:Furniture and textile manufacturers in the Piedmont Triad lack proximate CPSC-accredited facilities for flammability testing.
- IoT Device Cyber-Physical Convergence:Connected appliances require combined electrical safety and RF emissions certification, creating bundled service demand.
- State-Level Chemical Disclosure Laws:Washington's Safer Products Act and Maine's reporting requirements multiply substance restriction matrices beyond federal harmonization.
Industry Challenges
- ISO/IEC 17025 Auditor Shortage:CPSC-recognized accreditation bodies face 6-9 month backlogs for laboratory certification renewals.
- Legacy Equipment Obsolescence:Mechanical impact testers calibrated to 2011 ASTM F963 editions require firmware and fixture upgrades to meet 2023 protocol revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Consumer Product Safety Testing Market |
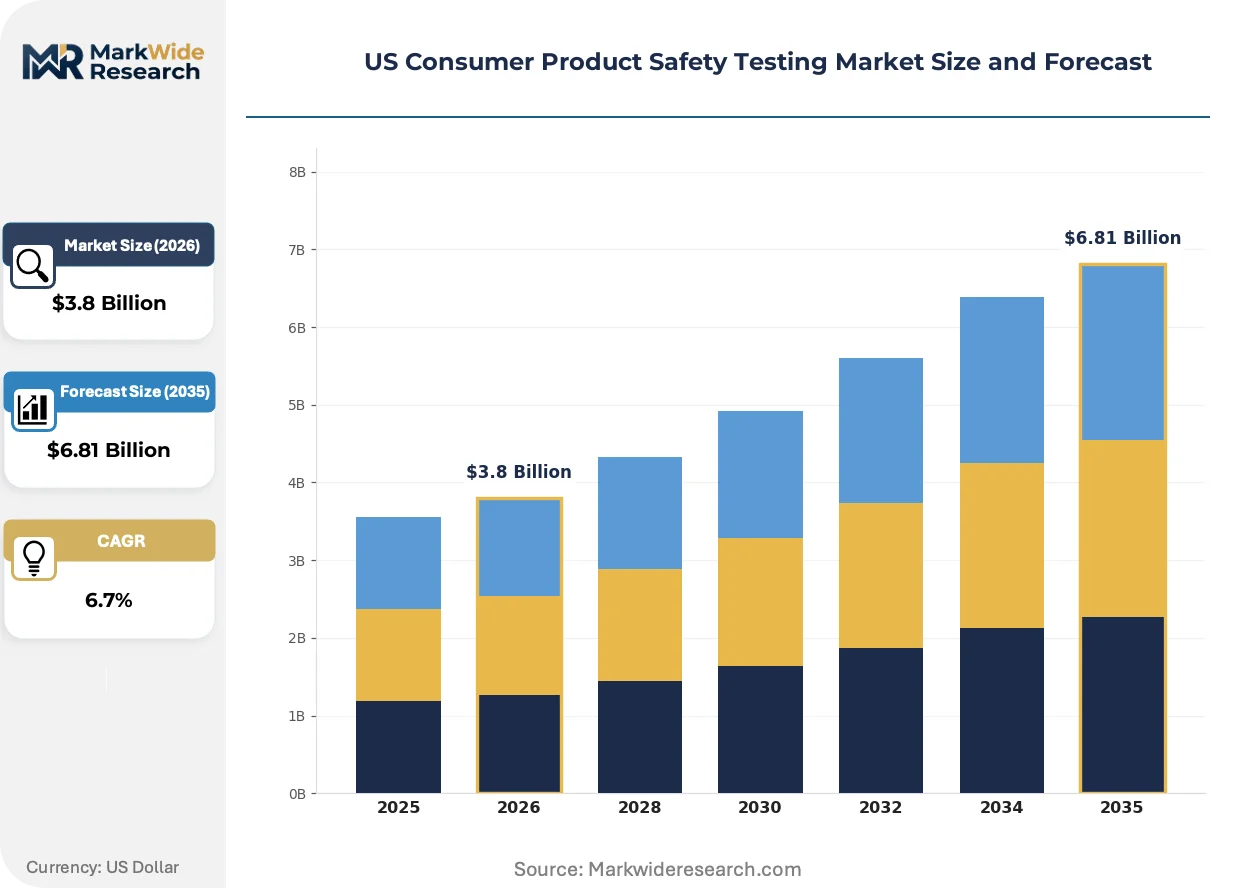
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Electrical Testing, Mechanical Testing, Chemical Testing, Thermal Testing End User: Manufacturers, Retailers, Distributors, Importers Product Category: Toys, Electronics, Furniture, Appliances Service Model: In-House Testing, Third-Party Testing, Consulting, Certification |
| Companies Covered | UL, Intertek Group, SGS, Bureau Veritas, Eurofins Scientific, DEKRA, Element Materials Technology, ALS Limited, BSI Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Consumer Product Safety Testing Market Trends and Innovations
Digital documentation platforms and automated sample tracking are compressing test cycle timelines while regulatory fragmentation multiplies the standard sets laboratories must maintain. Three developments are restructuring competitive positioning.
High-throughput screening systems equipped with robotic sample handling and AI-assisted spectral interpretation are supplanting manual chromatography workflows in chemical analysis laboratories. Mid-sized testing providers in Texas and Ohio are deploying these platforms to reduce phthalate and heavy metals turnaround from 14 days to 72 hours. The capital efficiency of automated batch processing is compressing pricing premiums that full-service incumbents historically commanded for expedited testing.
OSHA laboratory workplace safety inspections are intensifying scrutiny of fume hood ventilation and chemical storage protocols during destructive test procedures. Facilities handling lead paint chip analysis under 16 CFR Part 1303 face elevated citation risk for respiratory protection program gaps. Laboratories in Illinois and New Jersey are preemptively upgrading engineering controls and documentation systems to avoid enforcement actions that suspend testing operations.
Retailer liability-shifting is consolidating testing procurement among manufacturers supplying Walmart, Target, and Amazon marketplace channels. Brand owners now mandate third-party validation from CPSC-accepted laboratories before purchase order execution, displacing post-production spot-checking. Children's product suppliers in Los Angeles and Dallas metropolitan areas report 40% increases in pre-shipment inspection volumes as channel compliance deadlines tighten.
US Consumer Product Safety Testing Market Segmentation
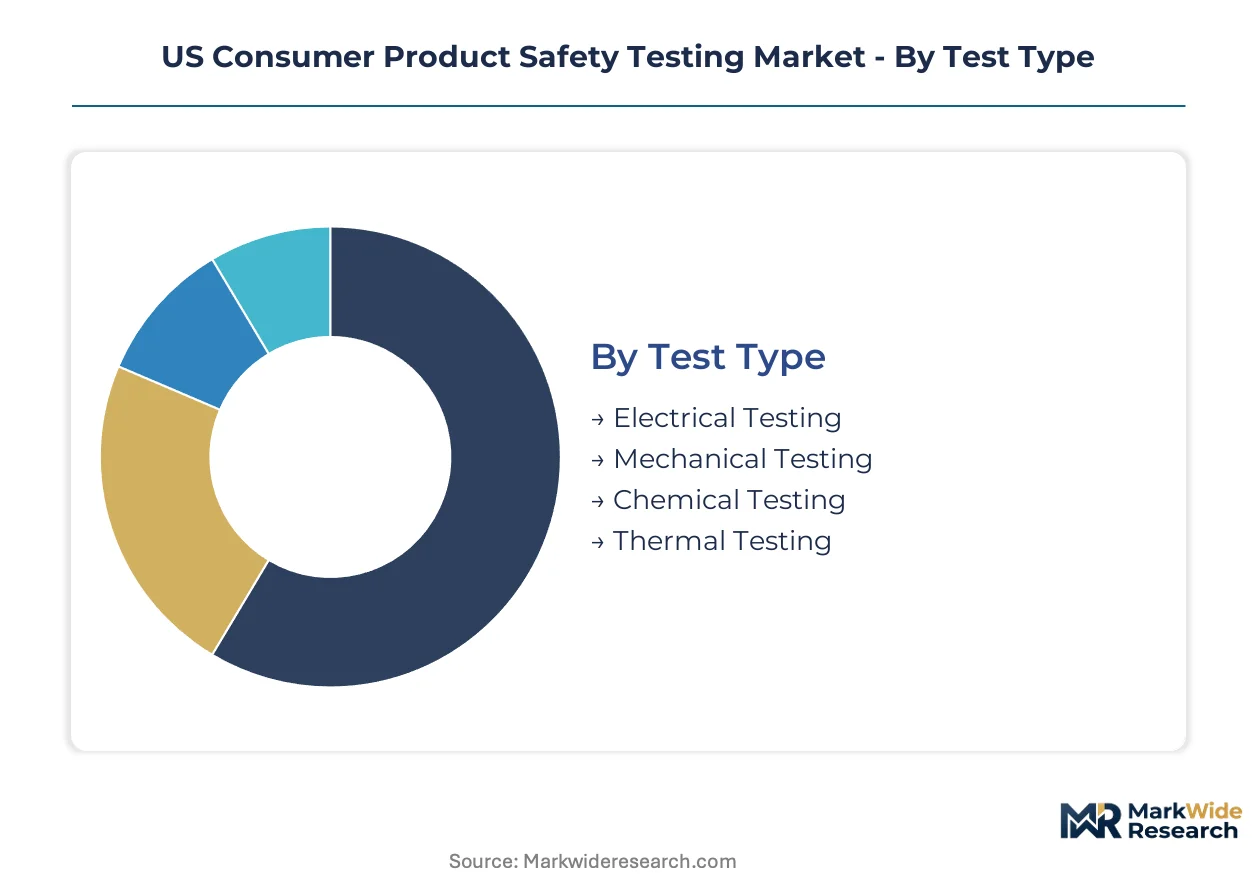
US Consumer Product Safety Testing Market segmentation reflects how regulatory complexity fragments service procurement. Laboratories must align capabilities across multiple standard sets while manufacturers choose between captive capacity and external validation based on volume and risk exposure.
Test Type:
CPSC mandatory standards and state-level chemical disclosure laws create divergent equipment requirements across test disciplines.
- Chemical Testing:Chromatography and spectrometry protocols detect phthalates, heavy metals, and lead content under 16 CFR Part 1303 and California Proposition 65. Laboratories in California and Texas are expanding reference standard libraries to cover 200+ substances as state lists multiply beyond federal baselines.
- Electrical Testing:Thermal runaway and abuse testing for lithium-ion battery systems under UN 38.3 transport rules now dominates service requests from electronics manufacturers. UL 60335 appliance certification and FCC emissions validation require NRTL-accredited facilities with in-house fire-safety infrastructure.
- Mechanical Testing:ASTM F963 protocol revisions for toys mandate updated impact testers and firmware upgrades.
- Thermal Testing:Flammability validation for furniture and textiles under 16 CFR Part 1632 and 1633 standards.
Chemical testing handles the majority of throughput; electrical testing is the fastest mover on share.
End User:
Procurement authority is shifting downstream as retailers impose validation requirements before purchase order execution.
- Manufacturers:Large toy and electronics producers in California and Texas maintain dual-track validation, combining in-house laboratories for routine screening with external certification for NRTL-mandated electrical work. Capital equipment amortization favors this model above 50,000 annual test units.
- Retailers:Walmart, Target, and Amazon marketplace channels now mandate third-party validation from CPSC-accepted laboratories, converting voluntary testing into channel-entry requirements. Children's product suppliers report 40% increases in pre-shipment inspection volumes.
- Distributors:Import consolidation points require rapid turnaround documentation to clear customs and meet retailer deadlines.
- Importers:Foreign manufacturers selling through US channels bear compliance burden under CPSIA Section 102.
Manufacturers retain the largest absolute volume; retailers are expanding their share fastest as liability-shifting accelerates.
Product Category:
Category-specific hazard profiles determine which laboratories capture service demand.
- Electronics:Lithium-ion battery certification under UN 38.3 and IEEE 1725 standards requires combined electrical safety and thermal abuse testing. Portable power system manufacturers in Texas and North Carolina drive the steepest expansion trajectory as consumer device proliferation continues.
- Toys:ASTM F963 mechanical and chemical testing serves California and Texas manufacturing clusters. Small parts choking hazard validation and phthalate screening remain high-frequency protocols.
- Furniture:Upholstered product flammability testing under 16 CFR Part 1633 concentrates demand in North Carolina's Piedmont Triad textile cluster.
- Appliances:UL 60335 household electrical safety certification requires NRTL-accredited facilities.
Electronics commands the highest revenue per test; furniture testing is gaining share fastest as regional capacity shortages persist.
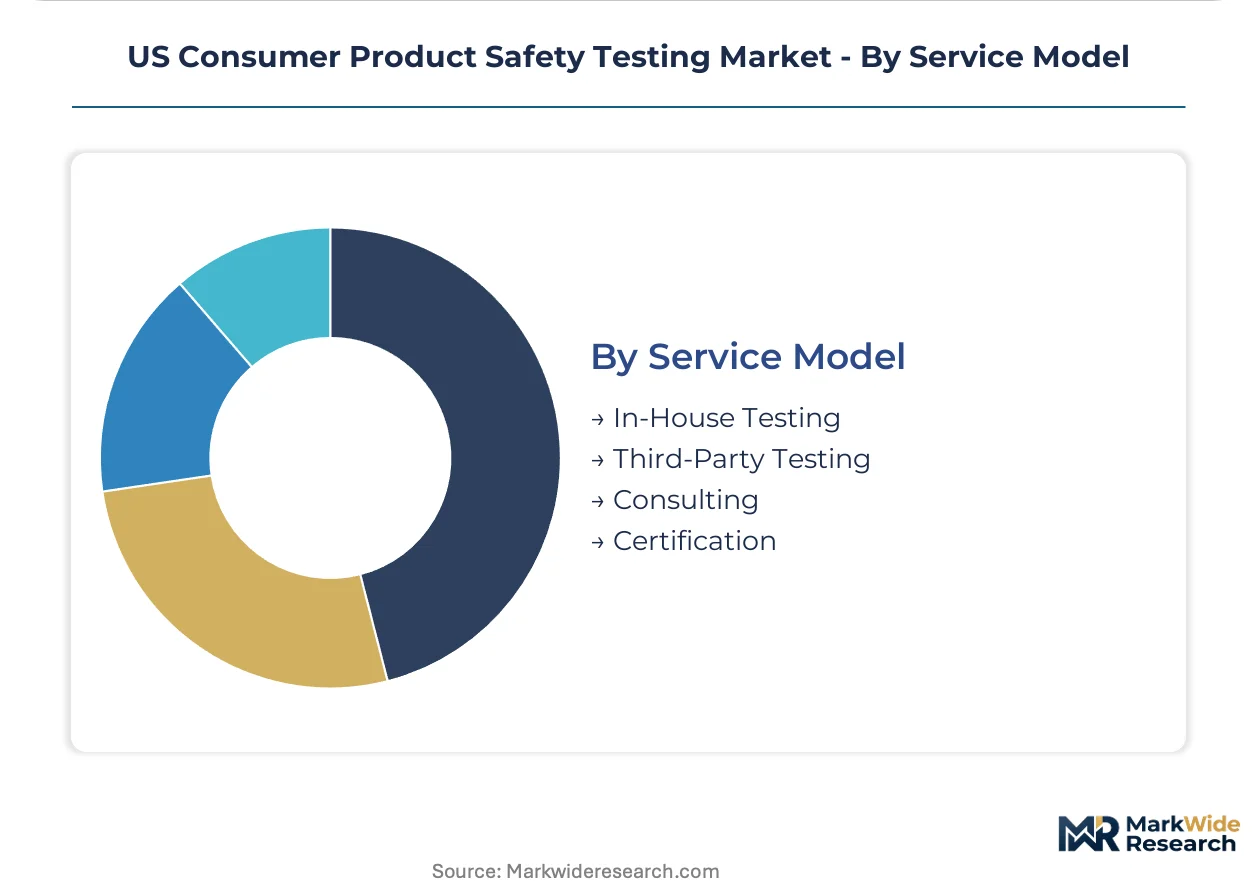
Service Model:
Capital intensity and accreditation requirements stratify competitive positioning across delivery modes.
- Third-Party Testing:External laboratories with CPSC-accepted status and ISO/IEC 17025 accreditation capture accelerating demand from mid-sized manufacturers and marketplace sellers. Amazon's mandatory safety documentation requirements have converted this from discretionary spend to operational necessity.
- In-House Testing:Captive laboratories at large manufacturers amortize equipment across high volumes but maintain external validation for NRTL-mandated electrical work. OSHA workplace safety inspections intensify scrutiny of fume hood ventilation and chemical storage protocols.
- Consulting:Regulatory interpretation and multi-jurisdiction compliance strategy for state-level chemical disclosure laws.
- Certification:NRTL listing and CPSC-accepted laboratory status for product marking.
Third-party testing carries the dominant share; consulting is climbing the fastest as regulatory fragmentation multiplies compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Southeast exhibit the highest price sensitivity, squeezing margins on routine mechanical testing, while California and Texas manufacturers absorb premium pricing for expedited chemical analysis and NRTL electrical certification.
California
Toy manufacturers in Los Angeles and Orange County counties are expanding validation budgets to meet ASTM F963 protocol revisions. Proposition 65 enforcement actions from the California Attorney General's office multiply substance restrictions beyond federal CPSC baselines. The San Francisco Bay Area electronics cluster drives demand for lithium-ion battery thermal runaway testing under UN 38.3 transport rules.
Texas
Electronics manufacturers in Austin and Dallas-Fort Worth require combined electrical safety and RF emissions certification for IoT devices. The Texas Commission on Environmental Quality regulates hazardous waste disposal from destructive chemical test procedures. Houston-area import consolidation points demand rapid turnaround documentation to clear customs and meet retailer deadlines.
North Carolina
Furniture and textile manufacturers in the Piedmont Triad lack proximate CPSC-accredited facilities for 16 CFR Part 1632 and 1633 flammability testing. The North Carolina Department of Labor enforces OSHA laboratory workplace safety standards during destructive test operations. Greensboro-High Point upholstery producers currently ship samples to out-of-state laboratories, creating regional capacity shortage premiums.
Illinois
Midwest appliance manufacturers seek UL 60335 household electrical safety certification from NRTL-accredited facilities. The Illinois Environmental Protection Agency inspects fume hood ventilation and chemical storage protocols at laboratories handling lead paint chip analysis. Chicago metropolitan testing providers face elevated citation risk for respiratory protection program gaps.
New Jersey
Pharmaceutical and consumer goods importers in the Port Newark-Elizabeth complex require CPSC-accepted test reports for customs clearance. The New Jersey Department of Environmental Protection regulates EPA hazardous waste disposal from chemically treated product samples. Laboratories in the New York metropolitan fringe are preemptively upgrading engineering controls to avoid OSHA enforcement suspensions.
US Consumer Product Safety Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US Consumer Product Safety Testing Market. Full-service incumbents with captive NRTL status and in-house fire-safety infrastructure command premium pricing for electrical certification, while mid-sized regional laboratories compete on turnaround speed and specialized chemical analysis. The competitive terrain stratifies into three strategic archetypes: vertically integrated global testing conglomerates, geography-focused mid-cap specialists, and niche boutiques concentrated on single-standard protocols. Dominant competitive moves include geographic expansion through distributed laboratory networks and portfolio diversification into adjacent regulatory consulting services.
Within the full-service tier, UL exemplifies the NRTL-accredited incumbent archetype with captive electrical safety infrastructure. Intertek Group and Bureau Veritas occupy positions as geographically distributed testing providers with multi-jurisdiction chemical analysis capabilities. These three entities represent contrasting approaches to capital intensity—UL's in-house fire-safety investment, Intertek's distributed laboratory network spanning California, Texas, and North Carolina, and Bureau Veritas's chemical testing leadership in phthalate and heavy-metals analysis.
| Leading Market Players |
|---|
| UL |
| Intertek Group |
| SGS |
| Bureau Veritas |
| Eurofins Scientific |
| DEKRA |
| Element Materials Technology |
| ALS Limited |
| BSI Group |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with German and Japanese mass spectrometer OEMs lock in both equipment access and price visibility for US laboratories facing 12-18 month delivery timelines. These long-term contracts insulate full-service incumbents from spot-market volatility while exposing mid-sized regional players to capital equipment inflation.
Pricing Analysis
After-sales revenue from expedited turnaround service and regulatory consulting drives lifetime value beyond the base test fee. Three-tier pricing structure across premium, standard, and economy levels separates NRTL-accredited electrical certification from routine mechanical screening and basic chemical analysis. Price differentiation stems from certification grade (CPSC-accepted laboratory status) and volume scale (annual test unit thresholds above 50,000). Cost compression in routine mechanical testing intensifies because mid-sized laboratories deploy high-throughput screening platforms. Southeast furniture manufacturers exhibit highest price sensitivity, while California electronics producers absorb premium pricing for UN 38.3 battery certification.
Supply Chain Analysis
Inventory lead times for high-resolution chemical analysis equipment extend 12-18 months, constraining laboratory expansion plans. Equipment supply concentrates in Germany and Japan for mass spectrometry systems, with US domestic production limited to lower-resolution instruments. Raw material dependencies include lithium-ion battery reference cells, phthalate and heavy metals certified reference standards, and ASTM F963 mechanical test fixtures. Single-source vulnerability from German OEM concentration exposes laboratories to production delays. Distribution runs through direct OEM sales channels and specialized scientific equipment distributors serving the California and Texas laboratory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from regulatory consulting and retainer-based compliance monitoring expands faster than hardware-centric test execution, framing this market as a service-attach opportunity. Laboratories bundling advisory services with validation protocols capture margin expansion unavailable to transactional competitors.
For Market Incumbents: Shield market position by deepening captive NRTL infrastructure investments and expanding chemical reference standard libraries beyond 200 substances to match California Proposition 65 proliferation. Acquire mid-sized regional specialists in North Carolina and Illinois to preempt capacity shortages in furniture flammability and appliance electrical testing. Vertical integration into AI-assisted spectral interpretation software reduces dependence on manual chromatography workflows.
For New Entrants and Emerging Players: Anchor in the Piedmont Triad furniture and textile cluster, where proximate CPSC-accredited flammability testing facilities remain scarce and regional manufacturers currently ship samples out-of-state. Target mid-sized electronics importers in the Port Newark-Elizabeth complex requiring rapid customs clearance documentation. Lead with 72-hour turnaround guarantees on phthalate and heavy metals screening to differentiate from 14-day incumbent timelines.
For Investors and Strategic Acquirers: Regional mid-cap laboratories with ISO/IEC 17025 accreditation and established retailer relationships represent the most defensible acquisition archetype. Long-term viability hinges on multi-jurisdiction chemical testing capabilities as state-level disclosure laws fragment beyond federal harmonization. Watch for CPSC enforcement action intensity against marketplace sellers as the inflection indicator for third-party testing demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| North Carolina Laboratory Expansion | Captures regional furniture flammability testing demand currently served by out-of-state facilities. |
| AI-Assisted Spectral Interpretation Investment | Compresses phthalate and heavy metals turnaround from 14 days to 72 hours for competitive differentiation. |
| Multi-Jurisdiction Chemical Consulting Bundle | Addresses California Proposition 65, Washington Safer Products Act, and Maine reporting requirement complexity. |
| NRTL Electrical Certification Infrastructure | Secures premium pricing for UL 60335 appliance and UN 38.3 battery thermal runaway testing. |
| Retailer Channel Compliance Partnership | Locks in pre-shipment inspection volumes from Walmart, Target, and Amazon marketplace suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from laboratory operations directors, CPSC regulatory affairs specialists, toy manufacturer quality assurance heads, and electronics supply chain compliance officers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of CPSC recall databases, ASTM International protocol revision records, EPA hazardous waste disposal filings, and OSHA laboratory inspection citations. Bottom-up test volume estimates from state-level manufacturing clusters were triangulated against top-down market sizing from service provider revenue disclosures.
Variance decomposition across test type, end user, product category, and service model dimensions structured the analytical framework. CAGRs were derived from segment-level growth rate assumptions calibrated to regulatory enforcement intensity and equipment capacity expansion timelines. Industry-specific forecast inputs included lithium-ion battery certification demand from portable electronics proliferation and ASTM F963 revision implementation schedules.
Material uncertainties — CPSC enforcement priority shifts, mass spectrometer OEM delivery timeline extensions, and state-level chemical disclosure law proliferation — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Food Testing Services Market