
 North America Feed Yeast Market | 2026-2036
North America Feed Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Yeast Market Analytics
Precision fermentation and strain optimization is rewriting how feed yeast producers engineer product consistency at commercial scale. Alltech Inc. leverages its Kentucky-based research campus to sustain proprietary Saccharomyces cerevisiae strains for ruminant applications. Cargill Incorporated anchors its North American supply chain through captive corn-derived substrate sourcing and integrated distribution. Lallemand Inc. differentiates by occupying specialized yeast culture niches for dairy and pet food channels.
Feed yeast comprises viable or inactivated Saccharomyces cultures, typically supplied at concentrations between 10^9 and 10^10 CFU per gram for active forms, formulated to improve rumen pH stability, nutrient absorption, and immune modulation in monogastric and ruminant species. Inactive yeast fractions rich in mannan-oligosaccharides and beta-glucans serve as prebiotic cell wall components in pet food and aquaculture diets. Active yeast dominates dairy farm applications where live cultures enhance fiber digestibility in high-producing Holstein herds. Inactive yeast shows faster growth in pet food manufacturing as brands replace synthetic additives with clean-label fermentate ingredients. Dried yeast formats command logistics advantages across the Plains states where bulk handling infrastructure supports tonnage deliveries to integrated poultry operations.
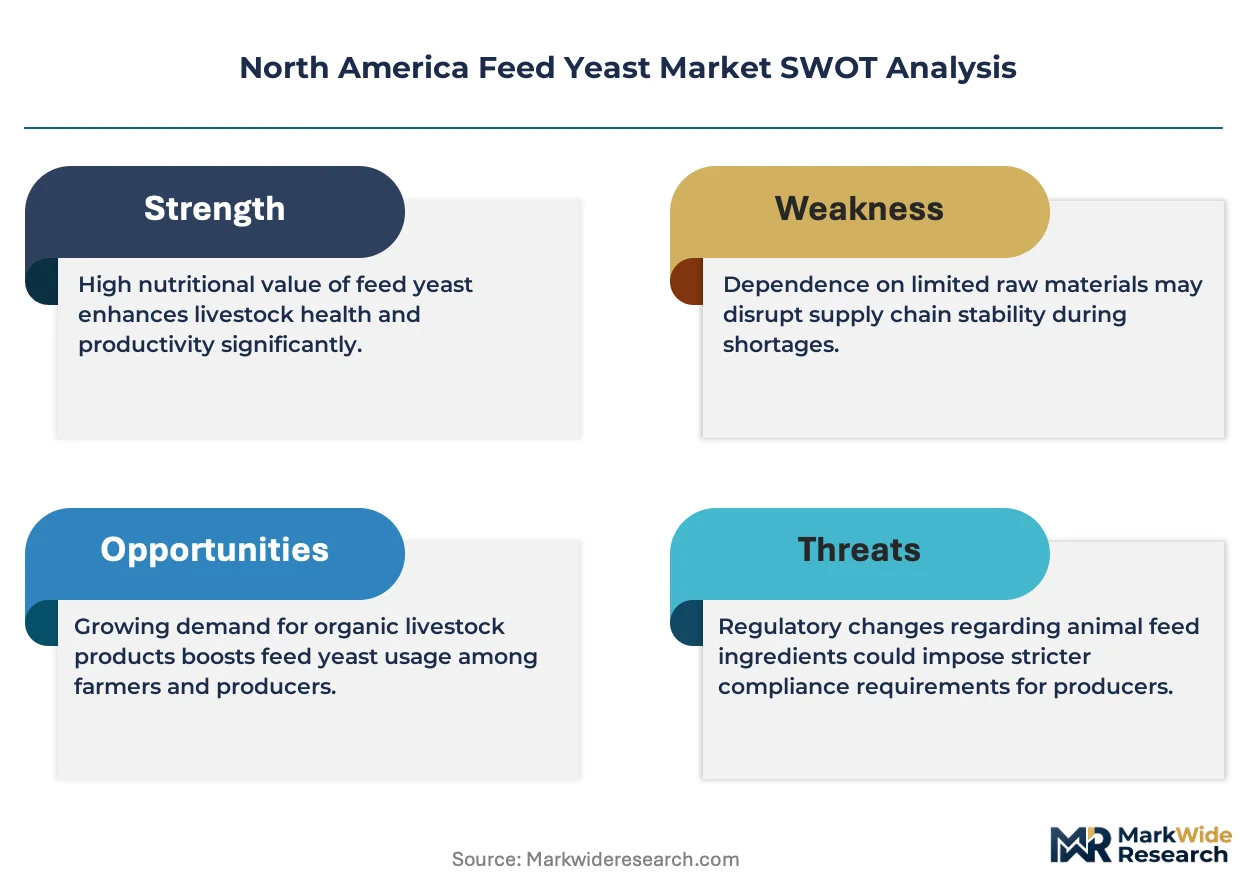
The FDA enforces Current Good Manufacturing Practice requirements for animal food under FSMA, while the USDA monitors label claims for antibiotic-free and natural positioning that yeast ingredients support. CFIA standards in Canada mandate species-specific approval pathways for novel feed additives, creating dual-compliance obligations for cross-border suppliers. State-level Department of Agriculture feed control officials in Iowa, California, and Texas administer registration and sampling protocols that determine market access speed. Stakeholders must monitor evolving FSMA enforcement priorities and CFIA harmonization talks to anticipate compliance cost trajectories and formulation investment timing.
Market Dynamics
Precision fermentation infrastructure is concentrating production capability among operators with captive substrate access and integrated strain libraries, compressing margins for toll-dependent suppliers across the Upper Midwest dairy belt.
Growth Catalysts
- FSMA traceability mandates:The FDA's Current Good Manufacturing Practice rules under the Food Safety Modernization Act are forcing feed compounders to document ingredient provenance, advantaging yeast suppliers with certified supply chains over commodity alternatives.
- Holstein herd productivity targets:High-producing dairy operations in Wisconsin and Minnesota are expanding live yeast supplementation to stabilize rumen pH during high-starch feeding regimens, creating pull-through for active culture formats.
- Mannan-oligosaccharide demand:Pet food manufacturers seeking clean-label positioning are substituting synthetic additives with yeast-derived prebiotic cell wall fractions, opening volume in premium kibble and treat formulations.
Market Restraints
- Corn substrate volatility:Dried distillers grains availability fluctuates with ethanol plant operating rates, creating margin pressure for yeast producers without captive corn processing or long-term offtake agreements.
- CFIA approval timelines:Health Canada's species-specific novel feed additive pathways impose 18-24 month registration delays for cross-border suppliers, fragmenting product portfolios between US and Canadian formulations.
- Enzyme substitution threat:Direct-fed microbial and exogenous enzyme products targeting fiber digestibility compete for the same rumen modification budget in dairy nutrition programs.
Strategic Opportunities
- Texas poultry integration:Consolidated broiler operations in the Texas Panhandle lack localized yeast production capacity, creating white space for bulk dried yeast terminals with rail-served distribution.
- California aquaculture expansion:State-funded recirculating aquaculture system development is generating demand for beta-glucan immunomodulators in salmonid and shrimp diets, a channel with limited incumbent supply.
- USDA Process Verified Program alignment:Antibiotic-free and natural label claims supported by yeast ingredients qualify for premium positioning in retail meat cases, opening branded ingredient partnerships with protein packers.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with GMP-compliant bioprocess experience command premium compensation, constraining capacity expansion timelines for mid-tier producers.
- State feed control registration fragmentation:Iowa, California, and Texas administer non-harmonized sampling and label approval protocols, forcing redundant compliance investments for national distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Yeast Market |
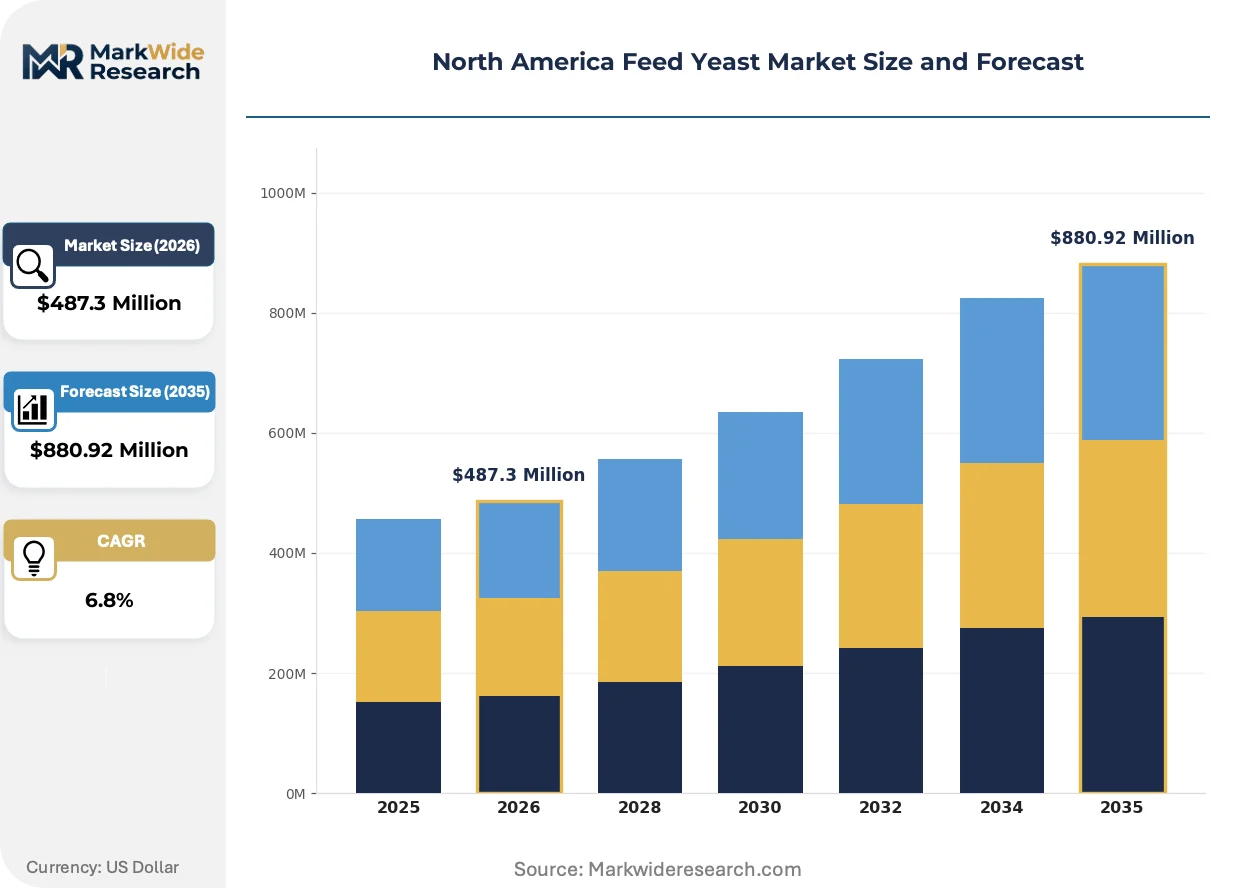
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Yeast, Inactive Yeast, Dried Yeast, Liquid Yeast Application: Livestock Nutrition, Pet Food, Aquaculture, Ruminant Feeding End User: Dairy Farms, Poultry Farms, Aquaculture Producers, Pet Food Manufacturers Distribution Channel: Online Sales, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Alltech Inc., Angel Yeast Co., Ltd., Lesaffre Group, Leiber GmbH, Nutreco, Archer Daniels Midland Company, Cargill Incorporated, Associated British Foods plc, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Yeast Market Evolving Landscape
Bioprocess control systems and substrate engineering are converging to compress batch-to-batch variability, while regulatory alignment between US and Canadian authorities is reshaping cross-border product development priorities.
Automated bioreactor sensor arrays paired with machine learning process control is digitizing fermentation parameter optimization at commercial yeast production facilities. Dairy nutrition consultants in the Upper Midwest are specifying digitized production lots with certificate-of-analysis consistency for high-value herd clients. This capability is compressing quality deviation allowances and forcing toll manufacturers to license control technology or exit premium supply tiers.
The FDA's enforcement discretion letters for animal food ingredients are clarifying GRAS self-determination pathways for yeast derivatives, reducing pre-market notification burdens for established Saccharomyces strains. CFIA is harmonizing with FDA safety assessments through bilateral mutual recognition talks, streamlining dual-market registrations for active dry yeast products. Canadian dairy cooperatives are accelerating adoption in anticipation of synchronized US-Canada label claims.
Integrated poultry operations are consolidating ingredient procurement through direct manufacturer contracts, displacing distributor intermediaries that historically stocked speculative inventory. Bulk handling infrastructure investments across the Plains states are enabling 20-tonne direct deliveries, compressing working capital requirements for large buyers. This concentration is most visible in Arkansas and Mississippi broiler complexes, where three-processor buying groups now negotiate strain-specific supply agreements.
North America Feed Yeast Market Segmentation
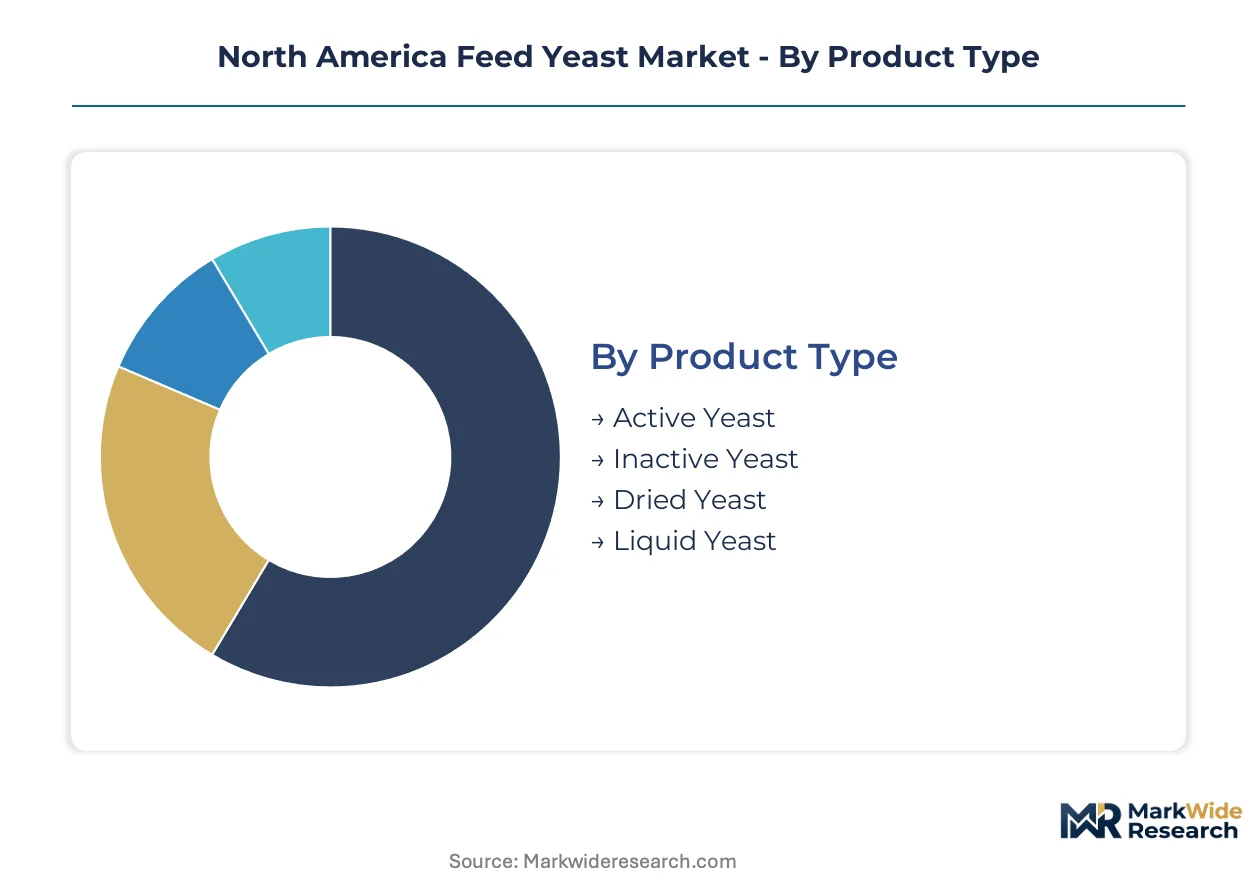
Feed yeast segmentation reveals how formulation chemistry, species-specific nutrition science, and procurement channel economics intersect to create distinct value pools across North American animal agriculture. Product format decisions cascade through application requirements, end-user scale considerations, and fulfillment infrastructure constraints.
Product Type:
Live versus inert formats span a functional spectrum from rumen microbiome modulation to clean-label prebiotic delivery.
- Active Yeast:Viable Saccharomyces cerevisiae cultures supplied at 10^9 to 10^10 CFU per gram stabilize rumen pH during high-starch feeding regimens. Demand concentrates in Wisconsin and Minnesota Holstein operations where fiber digestibility directly correlates with milk yield metrics.
- Inactive Yeast:Heat-inactivated whole cells and autolyzed fractions rich in mannan-oligosaccharides and beta-glucans serve as prebiotic cell wall ingredients. Pet food manufacturers in California and New York are substituting synthetic additives with these clean-label fermentates, opening premium positioning in kibble and treat formulations.
- Dried Yeast:Low-moisture formats enable bulk handling across Plains states rail infrastructure and extended shelf stability for integrated poultry procurement.
- Liquid Yeast:Pumpable suspensions suit automated feed mill inclusion systems with immediate-use requirements and minimal storage footprint.
The dominant share belongs to Active Yeast, while Inactive Yeast is closing the gap fastest.
Application:
Species physiology and regulatory claim pathways determine formulation investment priorities across animal production sectors.
- Livestock Nutrition:Encompasses monogastric and ruminant species with strain-specific efficacy documentation for weight gain and feed conversion metrics.
- Pet Food:Humanization trends drive yeast-derived palatability enhancers and immune-support fractions in premium positioning, with fastest expansion in freeze-dried and raw-coating applications.
- Aquaculture:Beta-glucan immunomodulators address disease pressure in recirculating systems, with California salmonid operations and Gulf shrimp hatcheries generating concentrated demand.
- Ruminant Feeding:Live culture stabilization of rumen pH supports high-producing dairy herds under metabolic stress from energy-dense rations.
Livestock Nutrition commands the largest volume position, though Pet Food exhibits the steepest expansion trajectory.
End User:
Scale economies and technical service requirements segment buyers by integration level and geographic clustering.
- Dairy Farms:Upper Midwest operations with 500+ head counts specify digitized production lots with certificate-of-analysis consistency, prioritizing active culture formats for rumen health protocols.
- Poultry Farms:Consolidated broiler integrators in Arkansas, Mississippi, and Texas Panhandle negotiate direct manufacturer contracts, displacing distributor intermediaries through 20-tonne bulk deliveries.
- Aquaculture Producers:Recirculating system operators in California and emerging Atlantic salmon net-pen operations in Maine seek immunomodulatory beta-glucan fractions with documented pathogen resistance outcomes.
- Pet Food Manufacturers:Premium and super-premium brands in Kansas and Pennsylvania manufacturing corridors specify inactive yeast for clean-label positioning and synthetic additive replacement.
Dairy Farms retain the foundational demand base, while Pet Food Manufacturers are gaining share fastest.
Distribution Channel:
Procurement modality reflects buyer scale, technical support requirements, and working capital optimization strategies.
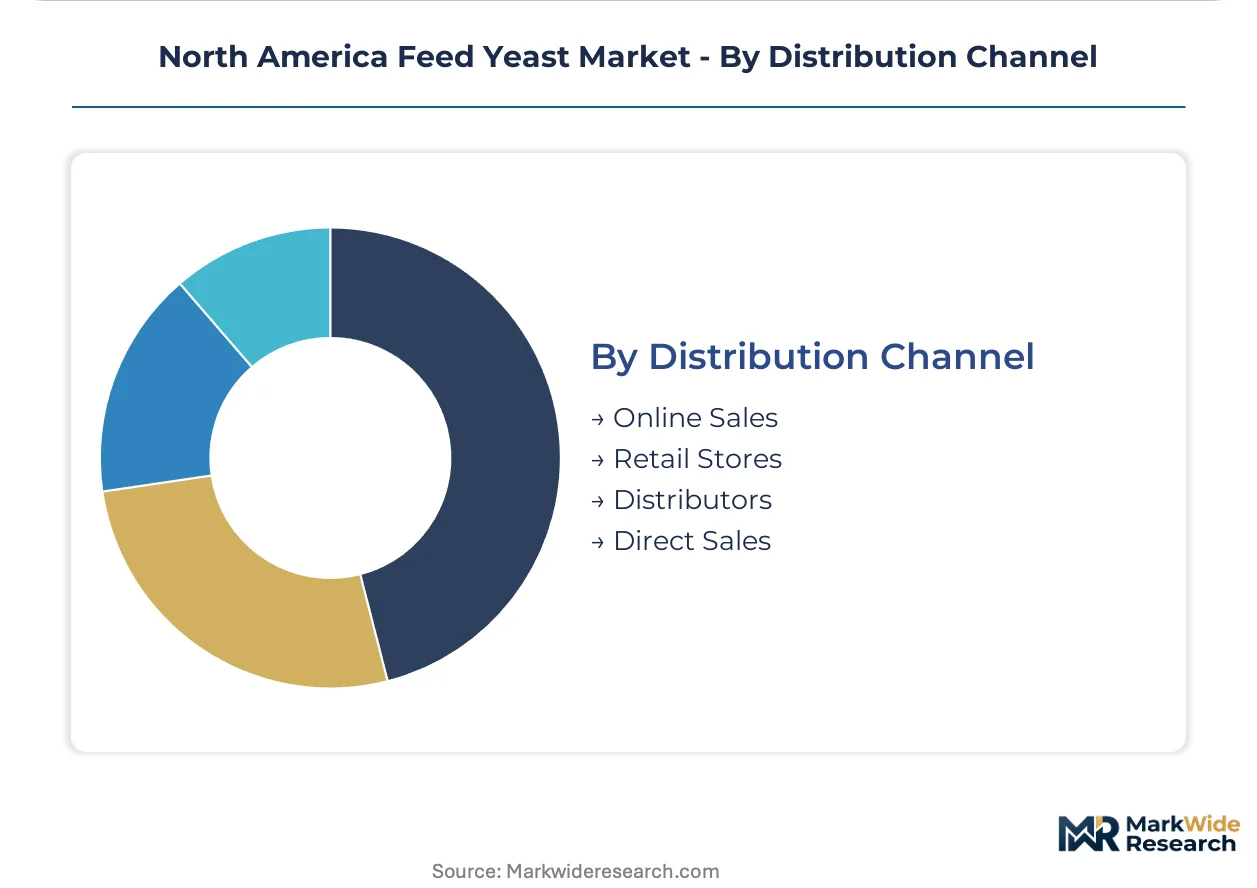
- Direct Sales:Strain-specific supply agreements with integrated poultry processors and large dairy cooperatives eliminate intermediary margins, enabled by captive logistics infrastructure across Plains states.
- Distributors:Regional feed ingredient wholesalers maintain speculative inventory for mid-tier compounders lacking volume certainty or storage capacity.
- Online Sales:E-commerce platforms serve small-scale livestock operators and specialty pet food formulators with sample quantities and rapid fulfillment requirements.
- Retail Stores:Farm supply cooperatives and veterinary clinics stock consumer-packaged yeast supplements for hobby farmers and companion animal owners.
Direct Sales holds the dominant position, though Online Sales is expanding most quickly among non-integrated buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border feed ingredient trade between the United States and Canada generates net yeast product exports northward, while Mexico imports specialized active cultures for its expanding poultry integration sector. Regional supply chains concentrate around corn belt substrate access and dairy belt consumption clusters.
United States
Wisconsin and Minnesota Holstein operations drive active yeast demand for rumen pH stabilization during high-starch feeding regimens. FDA FSMA enforcement mandates ingredient traceability documentation that favors suppliers with certified supply chains over commodity alternatives. Kentucky hosts proprietary strain research campuses serving ruminant nutrition programs across the Upper Midwest dairy belt.
Canada
CFIA species-specific novel feed additive approval pathways impose 18-24 month registration delays that fragment product portfolios between US and Canadian formulations. Health Canada bilateral mutual recognition talks with FDA are streamlining dual-market registrations for active dry yeast products. Ontario and Quebec dairy cooperatives are accelerating adoption in anticipation of synchronized cross-border label claims.
Mexico
Poultry integration growth in Guanajuato and Jalisco generates demand for bulk dried yeast formats suited to automated feed mill systems. Mexican federal agricultural regulators enforce feed safety standards aligned with USMCA trade agreement sanitary provisions. Sonora and Sinaloa broiler complexes negotiate direct manufacturer contracts displacing traditional distributor intermediaries.
North America Feed Yeast Market Competitive Landscape
On the supply side, the industry is consolidating around operators with captive substrate access and integrated strain libraries, compressing margins for toll-dependent suppliers. Three strategic archetypes dominate: diversified agribusiness conglomerates with backward integration into corn processing, specialized yeast culture specialists with proprietary fermentation IP, and regional toll manufacturers serving mid-tier compounders. Capacity expansion and strain licensing represent the dominant competitive moves, with players securing long-term offtake agreements for dried distillers grains to stabilize input costs.
Within the diversified agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positions anchored by captive corn-derived substrate sourcing and integrated North American distribution networks. Lallemand Inc. occupies a specialist position concentrated on yeast culture niches for dairy and pet food channels, representing the proprietary fermentation archetype. Alltech Inc. anchors the research-intensive segment through Kentucky-based strain development capabilities serving ruminant applications.
| Leading Market Players |
|---|
| Alltech Inc. |
| Angel Yeast Co., Ltd. |
| Lesaffre Group |
| Leiber GmbH |
| Nutreco |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Associated British Foods plc |
| Lallemand Inc. |
| Others |
Value Network & Pricing Analysis
Captive corn processing concentration across the US Corn Belt funnels margin pools toward yeast producers with backward-integrated substrate access, leaving toll-dependent suppliers exposed to dried distillers grains spot volatility. Pricing power accrues to operators controlling fermentation capacity proximal to dairy belt demand clusters.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled tiering. Pricing stratifies across certified-organic, FSMA-compliant, and commodity grades, with organic certification commanding sustained premiums. Cost compression in standard-grade active yeast is intensifying because ethanol plant operating rate fluctuations destabilize substrate costs. Mid-tier compounders lacking storage infrastructure exhibit highest price sensitivity, while integrated poultry processors leverage direct negotiation leverage.
Supply Chain Analysis
Export-control regimes limiting precision fermentation technology flows constrain strain optimization capability transfers to non-allied jurisdictions. Supply concentrates in the United States, Canada, and select EU member states with established GMP-compliant bioprocess infrastructure. Raw material dependencies center on corn-derived substrates, nitrogen sources, and specialized bioreactor components. Single-source vulnerability runs through proprietary Saccharomyces strain libraries held by dominant incumbents. Distribution runs through direct manufacturer contracts with integrated protein processors, displacing regional feed ingredient wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated dairy cooperatives and poultry integrators, as three-processor buying groups now negotiate strain-specific supply agreements displacing distributor intermediaries.
For Market Incumbents: Insulate margin position through captive corn processing investments in Iowa and Minnesota, securing substrate cost stability against ethanol market volatility. Deepen strain library IP protection against emerging precision fermentation specialists. Prioritize FSMA-compliant certification infrastructure to maintain traceability advantages over commodity alternatives. For New Entrants and Emerging Players: Pursue California aquaculture beta-glucan supply white space, where state-funded recirculating system expansion outpaces incumbent yeast culture capacity. Target Texas Panhandle poultry integration bulk terminals lacking localized production. Lead with immunomodulatory efficacy documentation as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier toll manufacturers with GMP-compliant fermentation assets and established dairy belt customer relationships, positioned for incumbent acquisition. Long-term viability favors operators bridging precision fermentation scale-up talent scarcity through automated bioprocess control licensing. Watch CFIA-FDA mutual recognition implementation pace as cross-border harmonization inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | Proprietary Saccharomyces cerevisiae development at Kentucky research campuses secures ruminant application differentiation against generic alternatives. |
| Captive Substrate Integration | Backward integration into corn processing stabilizes dried distillers grains supply costs for Upper Midwest fermentation capacity. |
| FSMA Compliance Certification | FDA Current Good Manufacturing Practice documentation enables premium positioning over commodity yeast suppliers in dairy nutrition programs. |
| Bulk Terminal Deployment | Rail-served distribution infrastructure in Texas Panhandle addresses consolidated broiler procurement consolidation displacing intermediaries. |
| Cross-Border Registration Harmonization | CFIA bilateral mutual recognition alignment streamlines dual-market product portfolios reducing 18-24 month approval fragmentation costs. |
Research Methodology
Initial hypotheses were tested against primary input from dairy nutrition consultants, feed mill procurement managers, fermentation process engineers, and state feed control officials, then refined through secondary validation. Dairy cooperative technical directors, poultry integration nutritionists, and pet food formulators provided operational perspective. Secondary sources included FDA FSMA guidance documents, USDA Process Verified Program standards, CFIA novel feed additive registration databases, and state-level feed control sampling protocols. Bottom-up strain-specific volume estimates were triangulated against top-down corn substrate consumption models.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product format, application species, end-user scale tier, and distribution channel. Active yeast, inactive yeast, dried yeast, and liquid yeast categories were separately projected. Ruminant, monogastric, pet food, and aquaculture demand drivers were calibrated against herd productivity targets and clean-label substitution rates. CAGRs were derived from log-linear regression of segment-specific growth trajectories, with cross-elasticities to corn price volatility and ethanol plant capacity utilization incorporated.
Macroeconomic conditions sit as an overlay; deviation in corn commodity price cycles, ethanol policy support levels, or dairy margin compression would shift the trajectory. Forecasts reflect assumptions regarding CFIA-FDA harmonization pace, precision fermentation scale-up talent availability, and state feed control registration fragmentation persistence. Material shifts in USMCA feed safety standard alignment or novel direct-fed microbial substitution efficacy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Stock Cubes Market
Ingredients
Interesterified Fats Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Carob Powder Market
Ingredients
South America Clean Ingredients Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Microparticulated Egg White Protein Market
Ingredients
Egg Free Premix Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Avocado Oil Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Textured Wheat Protein Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Karaya Gum Market