
 South America Vegetable Oil Market | 2026-2036
South America Vegetable Oil Market Size, Share, and Industry Trends Forecast 2026-2036
South America Vegetable Oil Market Analytics
Biofuel producers is restructuring procurement priorities across South America, tilting volume toward soybean oil and palm oil fractions suited for renewable diesel and FAME production. Cargill Incorporated leverages its crushing footprint along the Paraná River to anchor supply contracts with Brazilian biodiesel refiners. Bunge Limited competes through backward integration into Argentine soybean origination, while Louis Dreyfus Company specializes in bulk logistics for export-oriented refined oil cargoes.
South America vegetable oil comprises triglyceride mixtures extracted from oilseeds and palm fruits through mechanical pressing or solvent extraction, with free fatty acid content and iodine value determining suitability for food or fuel applications. Soybean oil dominates volume across the region due to crushing co-location with protein meal demand, though palm oil from Agropalma S/A's Amazonian estates is capturing industrial applications requiring higher oxidative stability. The food industry end-user segment remains the largest value pool, while biofuel producers represent the fastest-expanding demand channel under national blending mandates.
ANVISA in Brazil and Argentina's national food safety authority enforce maximum contaminant limits and labeling standards that shape product formulations for domestic sale. Brazil's RenovaBio carbon intensity scoring and Argentina's biodiesel tax differential structure create compliance thresholds that filter market access for uncertified imports. Stakeholders must track how evolving biofuel quota negotiations between Mercosur members and the EU deforestation regulation reshape acceptable feedstock sourcing geographies.
Market Dynamics
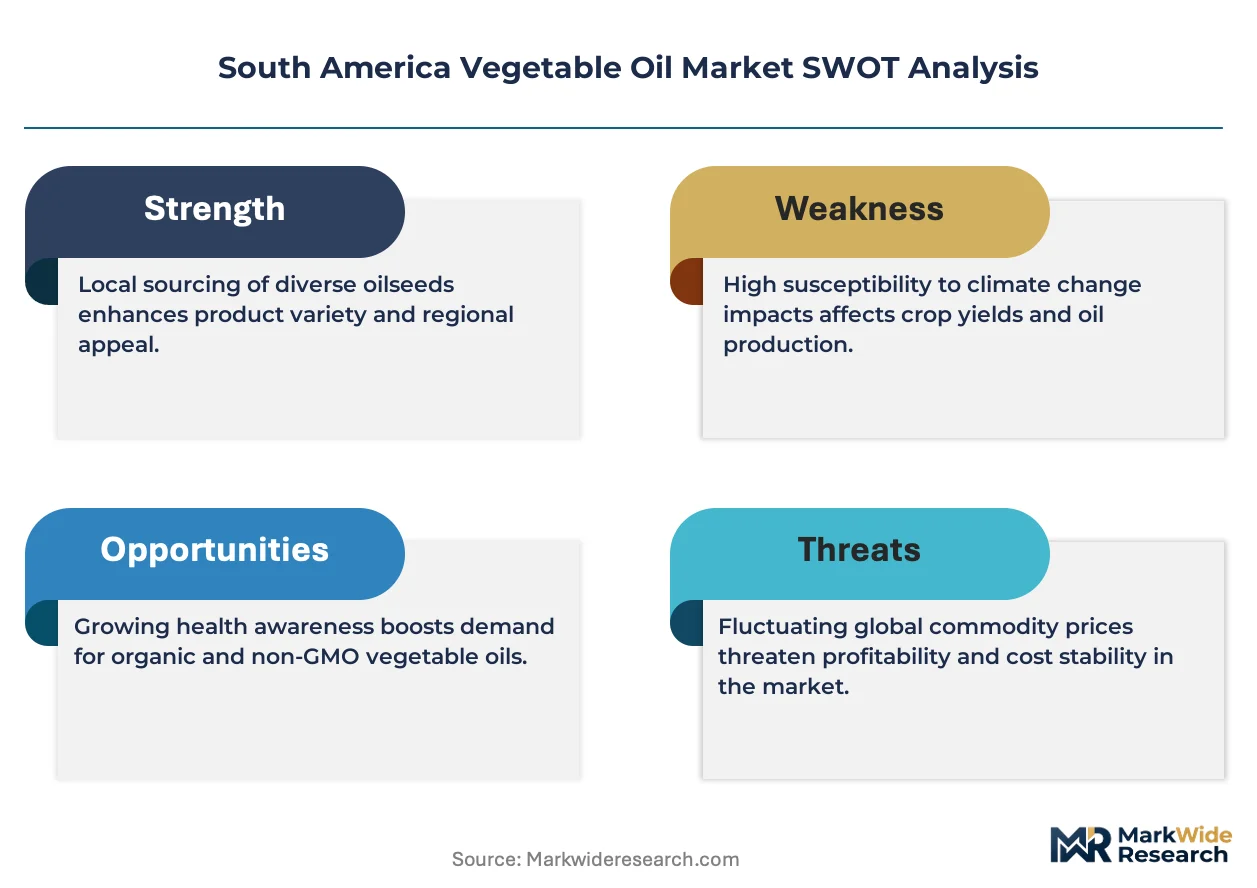
Brazil's RenovaBio carbon intensity scoring and Argentina's biodiesel tax differentials are compressing supply chains toward certified low-carbon feedstocks, forcing crushers to reconfigure procurement around traceability systems and third-party sustainability verification.
Growth Catalysts
- RenovaBio carbon intensity thresholds:Brazilian biodiesel refiners must source soybean oil with verified lifecycle emissions below 60g CO2e/MJ to maximize compliance credits, tightening specifications across the Paraná River processing corridor.
- Rosario-Victoria crushing cluster expansion:Argentine processors are adding enzymatic degumming capacity to produce non-GMO refined oil for EU-bound biodiesel cargoes under deforestation regulation requirements.
- Hydrotreated vegetable oil demand:Renewable diesel producers in Brazil's southeastern industrial belt are contracting long-term offtake for high-oleic soybean oil fractions suited to drop-in fuel specifications.
Market Restraints
- Soybean input cost volatility:Crush margins swing with Chicago Board of Trade futures and Argentine peso devaluation, squeezing independent processors without captive origination.
- Paraná River logistics concentration:Bulk oil movements depend on shallow-draft barge fleets through the Santa Fe-Confluencia corridor, creating weather-dependent bottlenecks during drought cycles.
- Palm oil oxidative stability advantage:Agropalma S/A's Amazonian estates supply industrial fryer markets with longer shelf-life product, displacing soybean oil in high-temperature food applications.
Strategic Opportunities
- Colombia's underdeveloped crushing base:The Llanos Orientales soybean belt lacks solvent extraction capacity, creating white space for integrated protein meal and refined oil operations serving Andean food manufacturers.
- EU deforestation regulation traceability premiums:Certified deforestation-free soybean oil commands price differentials in Rotterdam biodiesel markets, rewarding South American crushers with geolocation-verified supply chains.
- Enzymatic interesterification convergence:Food processors are blending high-oleic soybean oil with palm stearin to achieve tailored melting profiles for confectionery coatings without hydrogenation.
Industry Challenges
- ISCC-EU certification timeline compression:Crushers must complete mass-balance audits and satellite monitoring integration within 18-month windows to maintain EU biodiesel market access.
- Skilled technician scarcity:Solvent extraction plants in Brazil's Mato Grosso expansion zones face competition for process engineers from mining and ethanol sectors.
- Legacy refinery reconfiguration:Older Argentine deodorization units require capex upgrades to meet tightening ANVISA and national food safety authority contaminant limits for 3-MCPD esters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Vegetable Oil Market |
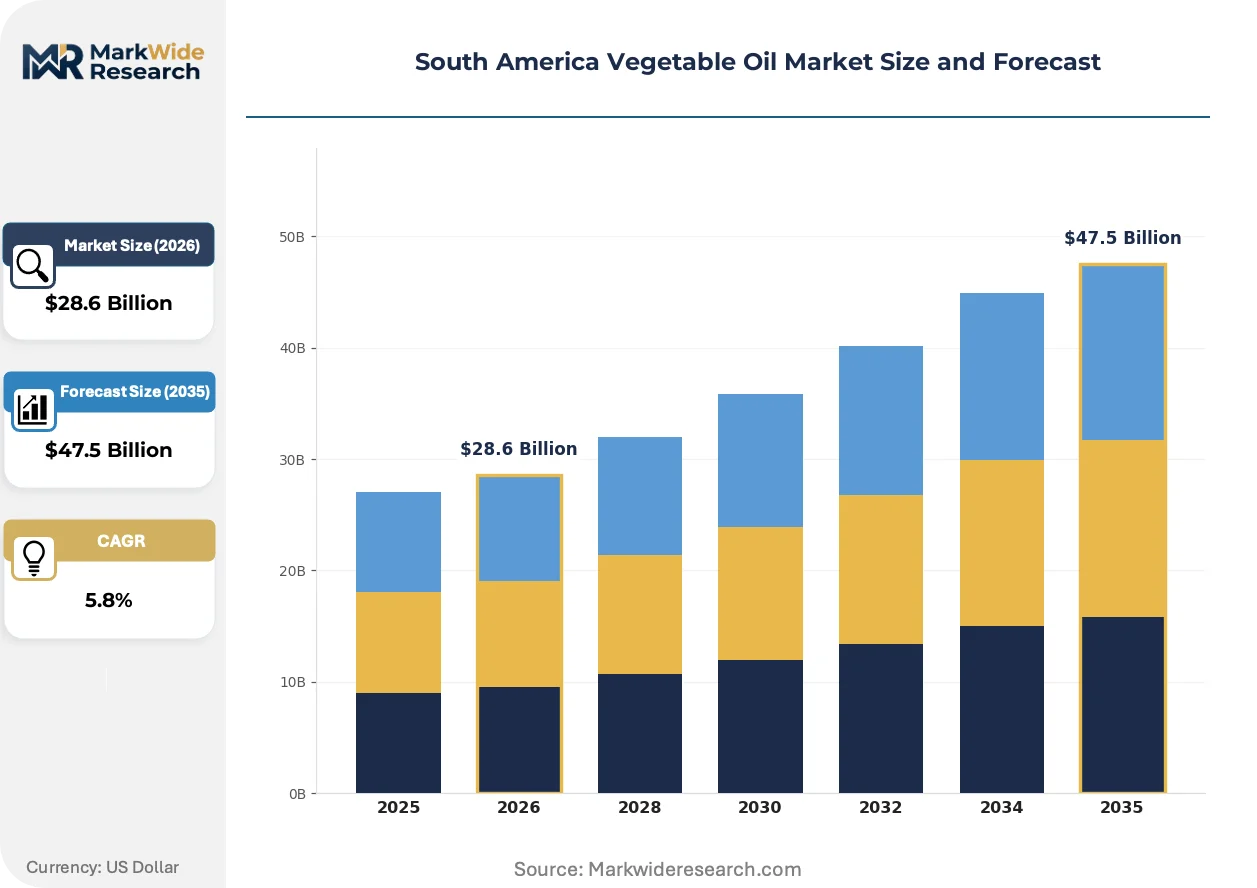
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunflower Oil, Soybean Oil, Palm Oil, Canola Oil End User: Food Industry, Biofuel Producers, Cosmetic Manufacturers, Animal Feed Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Direct Sales Application: Cooking, Industrial Use, Salad Dressing, Food Processing |
| Companies Covered | Aceitera General Deheza S.A., Wilmar International Limited, Cargill Incorporated, Agropalma S/A, Sime Darby Plantation Berhad, Bunge Limited, Molinos Río de la Plata, Louis Dreyfus Company, Archer Daniels Midland Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Vegetable Oil Market Evolving Landscape
Mechanical pressing and enzymatic processing technologies are displacing hexane extraction across South American vegetable oil production, driven by carbon accounting requirements and food safety authority contaminant limits.
Enzymatic degumming systems using phospholipase C enzymes are expanding into Brazilian soybean crushing operations, enabling simultaneous oil yield recovery and phosphorus reduction for biodiesel feedstock quality. RenovaBio-compliant refiners in São Paulo state are retrofitting existing plants at 18-month payback periods. This enzymatic transition is expanding into premium food-grade refined oil segments previously dominated by chemical refining.
Argentina's biodiesel tax differential structure now mandates sulfur content below 10ppm and cold filter plugging point specifications aligned with European EN 14214 standards, forcing crushers to invest in winterization capacity. The national food safety authority has synchronized contaminant maximum residue limits with Mercosur technical regulations, creating dual-compliance pressure on exporters. Rosario-based processors are responding with integrated laboratory certification hubs serving multiple crushing lines.
Long-term offtake contracting is displacing spot market purchases among Brazilian biodiesel distributors, compressing price discovery windows and locking crush margins ahead of harvest cycles. RenovaBio carbon credit banking allows fuel distributors to hedge three-year compliance obligations through forward soybean oil supply agreements. This contractual shift concentrates procurement power with vertically integrated crushers in Mato Grosso and Rio Grande do Sul.
South America Vegetable Oil Market Segmentation
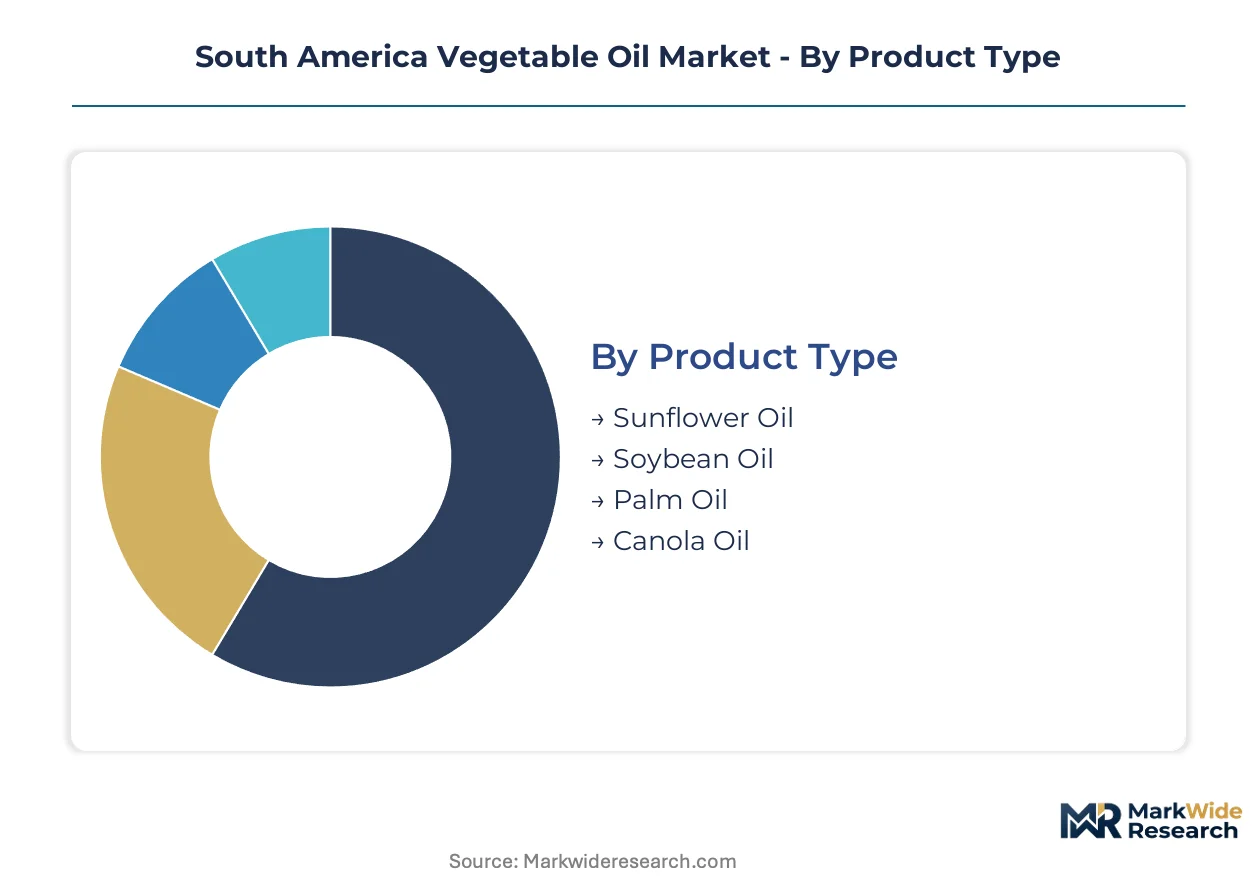
South America's vegetable oil market fragments along product specifications that determine eligibility for biofuel carbon credits versus food safety certifications. End-use differentiation separates buyers by compliance burden, from ANVISA-labeled retail products to RenovaBio-scored biodiesel feedstock.
Product Type:
Buyers in this category separate by oxidative stability requirements and fatty acid profile specifications for fuel versus food applications.
- Soybean Oil:Triglyceride mixture with iodine values of 120-140 and linoleic acid content near 55%, making it the dominant feedstock for Brazilian biodiesel refiners seeking RenovaBio compliance credits. Crushing co-location with protein meal demand in Mato Grosso and Rio Grande do Sul locks in supply concentration for fuel distributors.
- Palm Oil:Saturated fat content near 50% delivers superior oxidative stability for high-temperature industrial frying, with Agropalma S/A's Amazonian estates capturing food manufacturers requiring extended shelf-life performance. The fractionation capability into palm olein and stearin enables tailored melting profiles for confectionery applications.
- Sunflower Oil:High-oleic varieties with linoleic acid below 10% serve premium food processors demanding extended fryer life without hydrogenation.
- Canola Oil:Low erucic acid content and favorable omega-3 profile positions this segment for health-conscious retail bottlers in urban Brazilian markets.
Volume sits with soybean oil; growth tilts toward palm oil fractions for industrial stability requirements.
End User:
Compliance architecture distinguishes these buyers, from carbon intensity scoring mandates to contaminant maximum residue limits.
- Biofuel Producers:Brazilian refiners under RenovaBio must source soybean oil with verified lifecycle emissions below 60g CO2e/MJ to maximize decarbonization credits, forcing procurement through crushers with ISCC-EU certification and satellite-verified geolocation data. Argentine biodiesel blenders face sulfur content caps of 10ppm and cold filter plugging point alignment with EN 14214 standards.
- Food Industry:ANVISA enforces 3-MCPD ester limits and labeling standards that shape formulations for domestic retail, with processors in São Paulo state retrofitting deodorization units to meet tightening contaminant thresholds. This segment commands the largest value pool through branded retail and institutional foodservice contracts.
- Cosmetic Manufacturers:Refined grades with low free fatty acid content serve personal care formulators requiring cosmetic-grade oleochemical feedstock.
- Animal Feed:Acid oil and soapstock byproducts from refining operations concentrate in compound feed mills seeking cost-effective energy sources.
Value concentrates in food industry procurement; expansion accelerates most quickly among biofuel producers under national blending mandates.
Distribution Channel:
Logistics infrastructure and buyer scale determine channel selection across the region's processing corridors.
- Wholesale Distributors:Bulk movements through Paraná River barge fleets and coastal tanker terminals serve biodiesel refiners and industrial food processors with multi-thousand-ton offtake requirements, concentrating procurement power with crushers in the Rosario-Victoria cluster.
- Direct Sales:Long-term offtake contracts between vertically integrated crushers and Brazilian fuel distributors are displacing spot market purchases, locking crush margins ahead of harvest cycles through three-year carbon credit banking arrangements.
- Retail Stores:Supermarket and hypermarket channels in São Paulo and Buenos Aires metropolitan areas handle branded bottled oils for household consumption.
- Online Platforms:E-commerce penetration remains limited to specialty and organic oil segments targeting health-conscious urban consumers.
Tonnage flows through wholesale distributors; contractual innovation is reshaping direct sales most dramatically.
Application:
Temperature performance and regulatory classification split demand between fuel combustion and food preparation.
- Industrial Use:Hydrotreated vegetable oil production in Brazil's southeastern industrial belt requires high-oleic soybean oil fractions for drop-in renewable diesel specifications, with producers contracting dedicated supply streams outside commodity crush economics.
- Cooking:Household and foodservice frying applications dominate volume consumption, with palm olein displacing soybean oil in high-temperature operations requiring extended fryer life.
- Food Processing:Enzymatic interesterification blends of high-oleic soybean oil with palm stearin achieve tailored melting profiles for confectionery coatings without hydrogenation.
- Salad Dressing:Cold-pressed and virgin grades serve premium retail positioning for raw consumption applications.
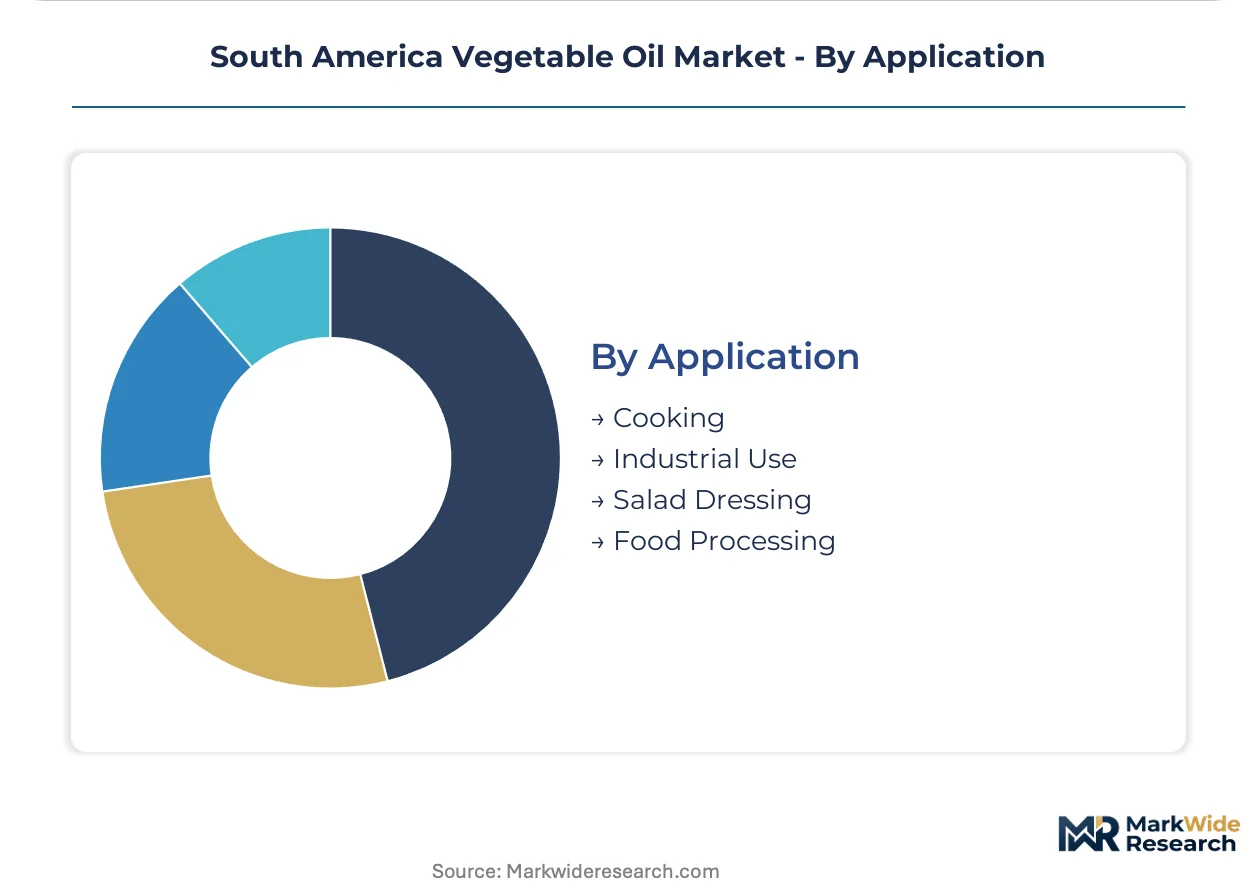
Cooking claims the largest volume base; industrial use is climbing the fastest on renewable diesel capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil produces surplus soybean oil for export while Argentina's crushing capacity exceeds domestic biofuel absorption, creating divergent trade dynamics across the southern cone.
Brazil
Mato Grosso's soybean belt feeds RenovaBio-compliant biodiesel refiners seeking carbon intensity scores below 60g CO2e/MJ. ANVISA enforces 3-MCPD ester limits on food-grade output. The São Paulo-Rio de Janeiro southeastern corridor hosts hydrotreated vegetable oil producers contracting dedicated high-oleic supply streams.
Argentina
Rosario-Victoria crushing clusters export refined oil to EU biodiesel markets under deforestation regulation traceability requirements. The national food safety authority mandates sulfur content below 10ppm for biodiesel blenders. Enzymatic degumming capacity expansion targets non-GMO certification for Rotterdam-bound cargoes.
Colombia
The Llanos Orientales soybean belt lacks solvent extraction infrastructure, forcing Andean food manufacturers to import refined oil from Ecuador. The country's national agricultural regulator promotes oilseed diversification programs. Bogotá-based distributors handle bulk imports through Caribbean port terminals.
Chile
Food processors in Santiago's metropolitan region source high-oleic sunflower oil for premium retail bottling. The national food safety authority synchronizes contaminant limits with Mercosur technical regulations. Valparaíso's coastal refineries blend imported palm olein with domestic crush output for institutional foodservice.
Paraguay
Smallholder soybean cooperatives supply crush plants along the Paraná River without captive biodiesel offtake. The national biofuels regulator maintains blending mandates below regional neighbors. Ciudad del Este processing corridors depend on Brazilian cross-border logistics for refined oil export.
South America Vegetable Oil Market Competitive Landscape
Top-tier vendors anchor integrated crushing and refining operations, while mid-scale processors compete on geographic origination and sustainability certification. The market structure concentrates procurement power with crushers possessing captive soybean supply and ISCC-EU mass-balance verification. Strategic archetypes include river-logistics specialists, enzymatic technology adopters, and deforestation-free supply chain operators. Competitive moves center on backward integration into origination and long-term offtake contracting with fuel distributors.
Among the integrated agribusiness tier, Cargill Incorporated and Bunge Limited represent archetypes of crushing footprint dominance along the Paraná River processing corridor. Louis Dreyfus Company occupies a position exemplifying bulk logistics specialization for export-oriented refined oil movements. These entities anchor competitive positioning through scale-advantaged procurement and RenovaBio compliance infrastructure.
| Leading Market Players |
|---|
| Aceitera General Deheza S.A. |
| Wilmar International Limited |
| Cargill Incorporated |
| Agropalma S/A |
| Sime Darby Plantation Berhad |
| Bunge Limited |
| Molinos Río de la Plata |
| Louis Dreyfus Company |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Chicago Board of Trade soybean futures transmit volatility through Argentine crush margins into Rotterdam biodiesel premiums, with certified low-carbon feedstocks commanding tiered price separation from uncertified commodity flows.
Pricing Analysis
Margin tightening in standard-grade soybean oil reflects Chicago futures volatility and Argentine peso devaluation squeezing processors without captive origination. Three-tier pricing structure across ISCC-EU certified, non-GMO refined, and commodity crush grades separates buyers by compliance burden. Cost-down pressure on economy-tier product accelerates because biodiesel blenders under RenovaBio must bank carbon credits through long-term offtake contracts. Fuel distributors exhibit lowest price sensitivity due to regulatory compliance mandates, while Andean food manufacturers importing from Ecuador show highest sensitivity to freight-adjusted delivered costs.
Supply Chain Analysis
Regional distribution centers along the Paraná River Santa Fe-Confluencia corridor anchor hub-and-spoke patterns for bulk oil movements to Brazilian southeastern refiners. Supply concentrates in Brazil, Argentina, and Paraguay, with raw material dependencies on Mato Grosso soybean origination, Amazonian palm fruit clusters, and imported phospholipase enzymes for enzymatic degumming. Single-source vulnerability runs through shallow-draft barge fleets exposed to drought-cycle navigation restrictions. Distribution feeds from river-logistics specialists into coastal tanker terminals serving EU-bound Rotterdam cargoes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where crushers without captive origination face margin compression against those controlling Mato Grosso soybean supply.
For Market Incumbents: Deepen backward integration into Llanos Orientales origination to preempt Colombian capacity builds, while retrofitting Rosario-Victoria deodorization units to meet tightening ANVISA 3-MCPD ester limits. RenovaBio carbon credit banking requirements threaten spot-market processors unable to lock three-year offtake contracts with fuel distributors. For New Entrants and Emerging Players: The mid-tier price gap between ISCC-EU certified and commodity soybean oil creates entry space for crushers with geolocation-verified supply chains targeting EU deforestation regulation compliance. Colombia's solvent extraction deficit offers the most penetrable geography, with enzymatic degumming technology as the go-to-market angle for Andean food manufacturers seeking non-GMO refined supply. For Investors and Strategic Acquirers: ISCC-EU certification timeline compression among Argentine exporters is the leading indicator that mass-balance audit capacity will consolidate toward integrated laboratory hubs serving multiple crushing lines. Long-term viability across a 5-10 year window favors acquirers of crushers with satellite-verified supply chains and RenovaBio compliance infrastructure, with satellite monitoring integration completion rates as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | Cargill's Paraná River crushing footprint secures captive soybean supply against Argentine peso volatility. |
| Enzymatic Degumming Capacity Expansion | Rosario-based processors capture non-GMO certification premiums for EU-bound biodiesel cargoes under deforestation regulation. |
| ISCC-EU Mass-Balance Certification | Crushers with verified geolocation data access Rotterdam price differentials for deforestation-free soybean oil. |
| Long-Term Offtake Contracting | Brazilian fuel distributors lock crush margins ahead of harvest cycles through RenovaBio carbon credit banking. |
| Winterization Capacity Investment | Argentine biodiesel blenders meet EN 14214 cold filter plugging point specifications for tax differential eligibility. |
Research Methodology
Document review covered ANVISA regulatory filings, Argentine national food safety authority contaminant standards, RenovaBio carbon intensity scoring protocols, and EU deforestation regulation traceability requirements, complemented by interviews with crushing plant managers, biodiesel refinery procurement leads, and Rotterdam commodity traders. Secondary validation drew from Mercosur technical regulation databases, ISCC-EU certification registries, and Paraná River barge fleet capacity reports. Bottom-up volume builds from crusher capacity utilization rates triangulated against top-down demand estimates from national blending mandate schedules.
Segment-level outputs across product type, end user, distribution channel, and application dimensions were generated through the projection horizon, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion pipelines. RenovaBio compliance credit pricing and EU deforestation regulation enforcement timelines served as scenario-weighting inputs for the analytical framework.
Inputs from ANVISA, the Argentine national food safety authority, and ISCC-EU certification bodies were available through the study window; gaps in real-time satellite monitoring coverage for geolocation verification introduce uncertainty bands around deforestation-free supply chain estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Cocoa Products Market
Ingredients
Agar Agar Flakes Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Cocoa Maker Market
Ingredients
Yeast Derivatives Market
Ingredients
Lime Seed Oils Market
Ingredients
Thinned Starch Market
Ingredients
China Corn Glucose Market
Ingredients
Banana Flour Market
Ingredients
Amylase Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Marine Ingredients Market
Ingredients
Clean Label Starch Market
Ingredients
Egg White Powder Market