
 Food Traceability Solutions Market | 2026-2036
Food Traceability Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Food Traceability Solutions Market Insights
Platform licensing revenue is tilting toward subscription-based traceability networks as buyers prioritize continuous compliance monitoring over one-time software deployments. SAP SE leverages its ERP-installed base to embed traceability modules within existing procurement workflows. Zebra Technologies anchors its position through ruggedized RFID hardware purpose-built for cold-chain environments. IBM Corporation competes via Hyperledger Fabric deployments that link multiple tiers of agricultural suppliers.
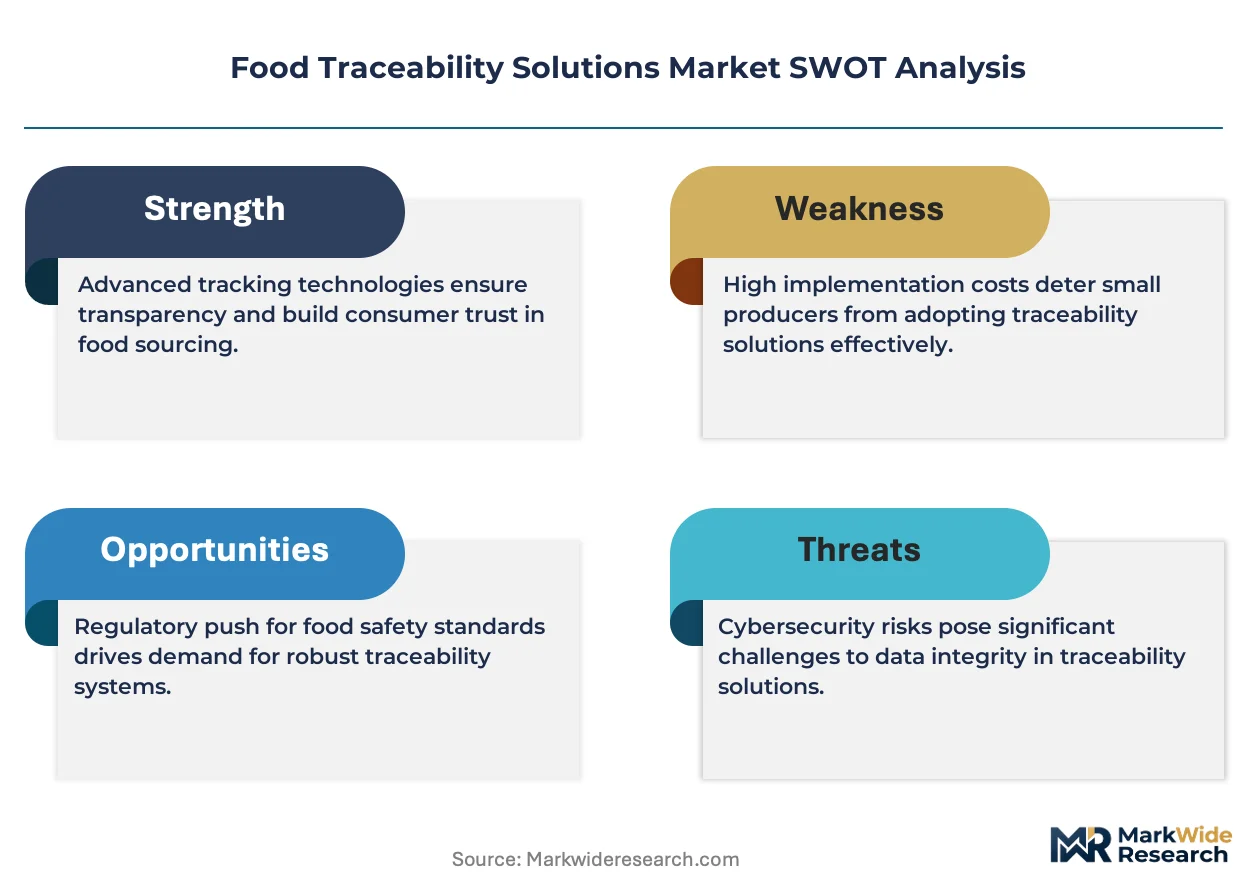
Food traceability solutions encompass hardware, software, and service architectures that capture, store, and transmit product origin, handling, and destination data across supply chain nodes, typically employing GS1-standardized identifiers and distributed ledger or cloud database architectures to maintain immutable records. These systems serve the commercial purpose of reducing recall scope, verifying label claims, and satisfying downstream buyer liability requirements. The blockchain technology segment attracts premium pricing due to cryptographic immutability demands from institutional foodservice buyers, while RFID dominates physical volume through pallet-level tagging at processing facilities. The maintenance service type generates recurring margin pools as regulated facilities require continuous system validation and calibration.
The FDA Food Safety Modernization Act and EU General Food Law impose lot-level tracking mandates that directly shape system design specifications and procurement timelines. REACH chemical documentation requirements and EFSA allergen labeling standards further complicate data field requirements for European operators. Stakeholders must monitor evolving interoperability standards between competing blockchain protocols before committing to multi-year platform contracts.
Market Dynamics
Blockchain-linked compliance mandates from the EU Green Deal's Farm to Fork strategy are forcing fresh produce distributors to abandon paper-based provenance records in favor of interoperable digital networks that satisfy downstream buyer audit requirements.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory origin documentation rules across member states compel processors to deploy GS1-standardized tracking systems, creating baseline demand for integrated hardware-software architectures.
- Institutional Foodservice Buyers:Large-scale catering operators and contract foodservice companies now require cryptographic immutability for liability protection, pulling blockchain-anchored solutions into procurement specifications.
- Cold-Chain Expansion:Temperature-sensitive pharmaceutical and biologics logistics operators are repurposing ruggedized RFID infrastructure for food applications, extending provenance tracking into previously untagged product categories.
Market Restraints
- Silicon Supply Concentration:RFID chip fabrication depends on concentrated Asian foundry capacity, exposing hardware vendors to input cost volatility and extended lead times for pallet-level tagging equipment.
- Protocol Interoperability Friction:Competing blockchain architectures lack standardized data exchange formats, forcing buyers to accept vendor lock-in or bear expensive middleware development for multi-platform environments.
- Legacy ERP Integration Burden:Existing enterprise resource planning systems require custom API development to ingest traceability data streams, inflating total cost of ownership for mid-tier processors with limited IT budgets.
Strategic Opportunities
- India FSSAI Modernization:The Food Safety and Standards Authority of India's phased implementation of digital traceability mandates for packaged foods creates first-mover advantage for platforms pre-certified to Indian data localization requirements.
- Sensor-Blockchain Convergence:Integration of IoT environmental sensors with distributed ledger verification enables real-time quality attestation, opening premium pricing tiers for perishables with continuous condition monitoring.
- Direct-to-Retailer Channel Bypass:Producer-owned traceability platforms that transmit provenance data straight to grocery chain procurement systems disintermediate traditional distributor data aggregation roles.
Industry Challenges
- GS1 Standard Implementation Skill Gap:Facilities lack personnel trained in global trade item number serialization and EPCIS event repository management, delaying system commissioning and requiring vendor-dependent operational support.
- Multi-Tier Supplier Onboarding Complexity:Agricultural cooperatives and smallholder farms resist data sharing protocols, fragmenting chain-of-custody records and forcing processors to subsidize upstream digitization investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Traceability Solutions Market |
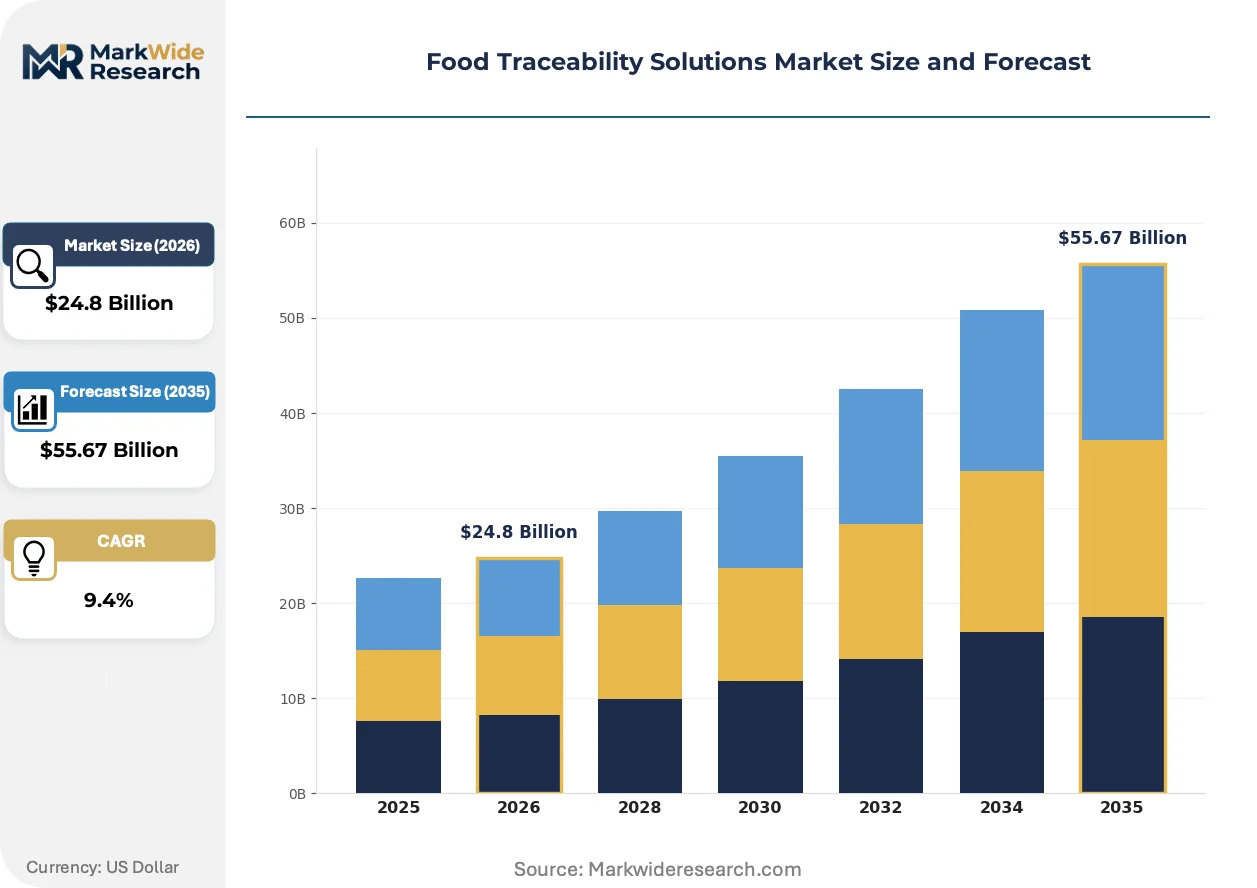
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $55.67 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, RFID, IoT, QR Code End User: Manufacturers, Distributors, Retailers, Consumers Application: Supply Chain Management, Quality Control, Compliance, Inventory Management Service Type: Consulting, Implementation, Maintenance, Training |
| Companies Covered | SGS SA, Honeywell International Inc., Zebra Technologies, C.H. Robinson, Trustwell, Cognex Corporation, FoodLogiQ, SAP SE, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Traceability Solutions Market Trends and Innovations
Traceability infrastructure is converging with adjacent supply chain technologies, producing hybrid architectures that embed compliance verification directly into operational workflows rather than treating it as a post-hoc documentation exercise.
Edge computing nodes with embedded RFID readers and environmental sensors are hybridizing traditional passive tagging with real-time data processing. Cold-storage operators in Germany and the Netherlands are deploying these units at warehouse chokepoints to validate pallet integrity before release. This compression of sensing and verification into single hardware layers is reducing the latency between physical handling events and blockchain-anchored record creation.
REACH chemical documentation requirements are expanding data field specifications for European food processors handling pesticide-treated agricultural inputs. ECHA's substance database integration demands now flow through to finished product labels, compelling traceability platforms to incorporate hazardous substance tracking modules previously isolated from food safety systems. Specialty ingredient suppliers serving EU export markets are absorbing the largest compliance burden, reconfiguring supplier qualification questionnaires to capture chemical origin attestations.
Buyer audit cycles are compressing from annual certification reviews to continuous compliance monitoring through subscription-based platform access. Large retail chains in France and the United Kingdom now require live dashboard visibility into supplier handling events rather than static quarterly reports. This behavioral shift favors network-based traceability providers over perpetual-license software vendors, restructuring vendor revenue models toward recurring service fees tied to transaction volumes rather than upfront deployment charges.
Food Traceability Solutions Market Segmentation
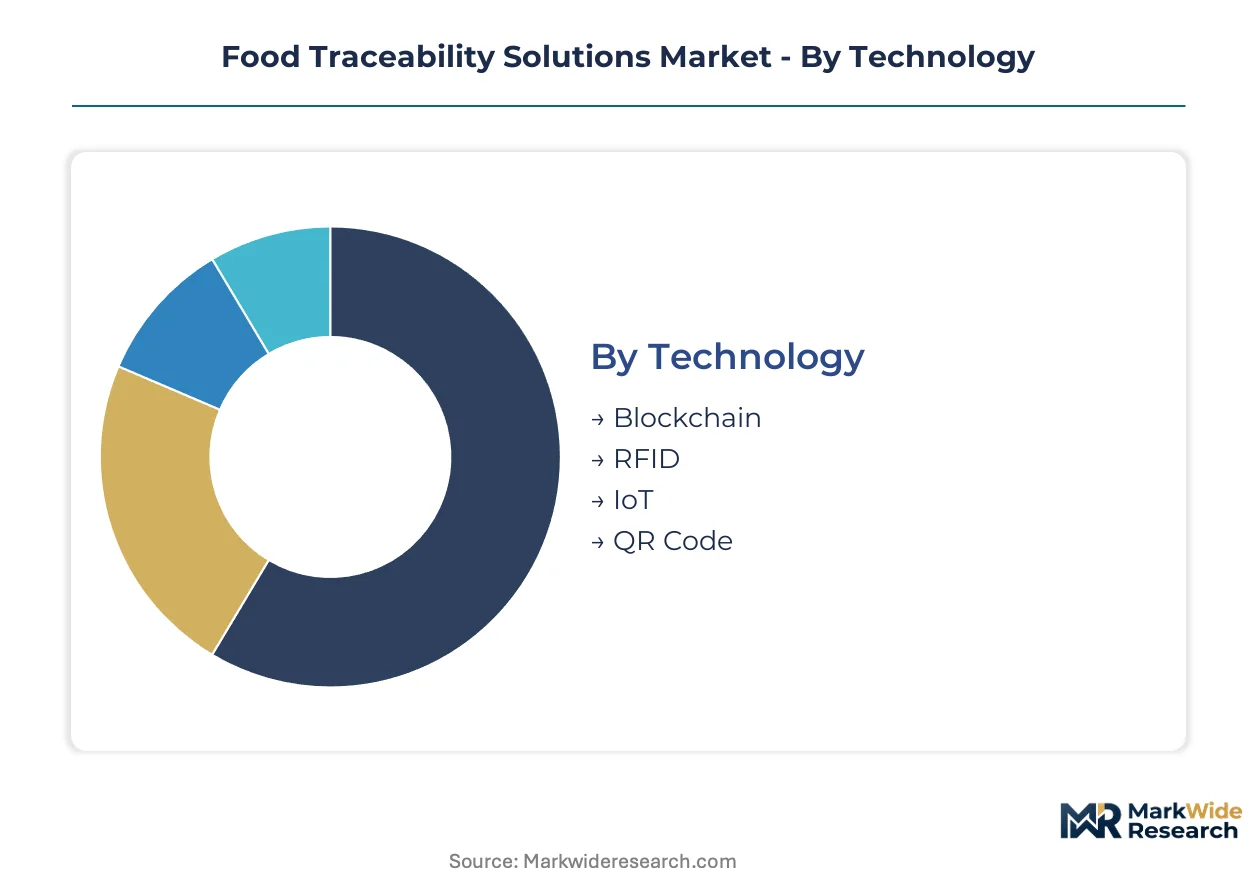
Segmentation in food traceability solutions reveals how technology choices, buyer types, and service requirements create distinct commercial rhythms. Hardware-heavy deployments cycle differently from software-centric platforms, while regulatory pressure varies sharply across end-user categories.
Technology:
Replacement cycles stretch from months for simple tagging to multi-year infrastructure commitments for distributed ledger systems, creating divergent vendor cash flow patterns.
- Blockchain:Cryptographic ledgers anchor immutable provenance records through consensus mechanisms. Institutional foodservice buyers in Germany mandate Hyperledger Fabric deployments for liability protection, pulling premium pricing tiers. Cold-chain operators absorb extended implementation timelines for cryptographic verification.
- RFID:Passive and active radio-frequency tags capture pallet-level movement data through GS1-standardized identifiers. Ruggedized hardware dominates processing facilities in the Netherlands where cold-storage operators validate integrity at warehouse chokepoints. Silicon supply concentration exposes hardware vendors to Asian foundry lead time volatility.
- IoT:Environmental sensors transmit temperature, humidity, and location telemetry through cellular or mesh networks.
- QR Code:Two-dimensional barcodes encode batch identifiers accessible through standard smartphone cameras.
RFID dominates installed base through pallet-level ubiquity. Blockchain is where expansion concentrates as EU Green Deal mandates harden cryptographic requirements.
End User:
Procurement authority and technical sophistication separate buyers who specify systems from those who merely comply with upstream demands.
- Manufacturers:Processors and packagers deploy traceability infrastructure to satisfy downstream audit requirements and reduce recall scope. German meatpacking facilities face mandatory blockchain-linked compliance systems under Farm to Fork implementation timelines. Legacy ERP integration burdens inflate total cost of ownership for mid-tier operators.
- Distributors:Fresh produce distributors expand digital provenance tracking to meet buyer audit requirements, abandoning paper-based records for interoperable networks. French retail chains now demand live dashboard visibility rather than static quarterly reports. Subscription-based platform access is displacing perpetual-license software procurement.
- Retailers:Grocery chains and foodservice operators specify traceability requirements for supplier qualification.
- Consumers:End purchasers scan product labels for origin verification through mobile applications.
Distributors command current deployment volume. Manufacturers represent the steepest expansion trajectory as mandatory origin documentation rules tighten across EU member states.
Application:
Functional priorities shift from reactive compliance documentation toward proactive quality attestation embedded in operational workflows.
- Supply Chain Management:End-to-end visibility platforms track product movement from agricultural input through retail shelf. Edge computing nodes with embedded RFID readers hybridize passive tagging with real-time processing at Netherlands cold-storage facilities. This compression reduces latency between physical handling and blockchain-anchored record creation.
- Quality Control:Continuous condition monitoring enables real-time quality attestation for perishables. Sensor-blockchain convergence opens premium pricing tiers as environmental data flows directly to distributed ledgers. Temperature-sensitive pharmaceutical logistics operators repurpose infrastructure for food applications.
- Compliance:Regulatory adherence systems satisfy FDA Food Safety Modernization Act and EU General Food Law mandates.
- Inventory Management:Lot-level tracking optimizes stock rotation and reduces waste through first-expiry-first-out protocols.
Supply Chain Management anchors current platform deployments. Quality Control is gaining share fastest as sensor-blockchain integration matures.
Service Type:
Revenue model evolution favors recurring service relationships over one-time deployment fees, restructuring vendor economics toward continuous engagement.
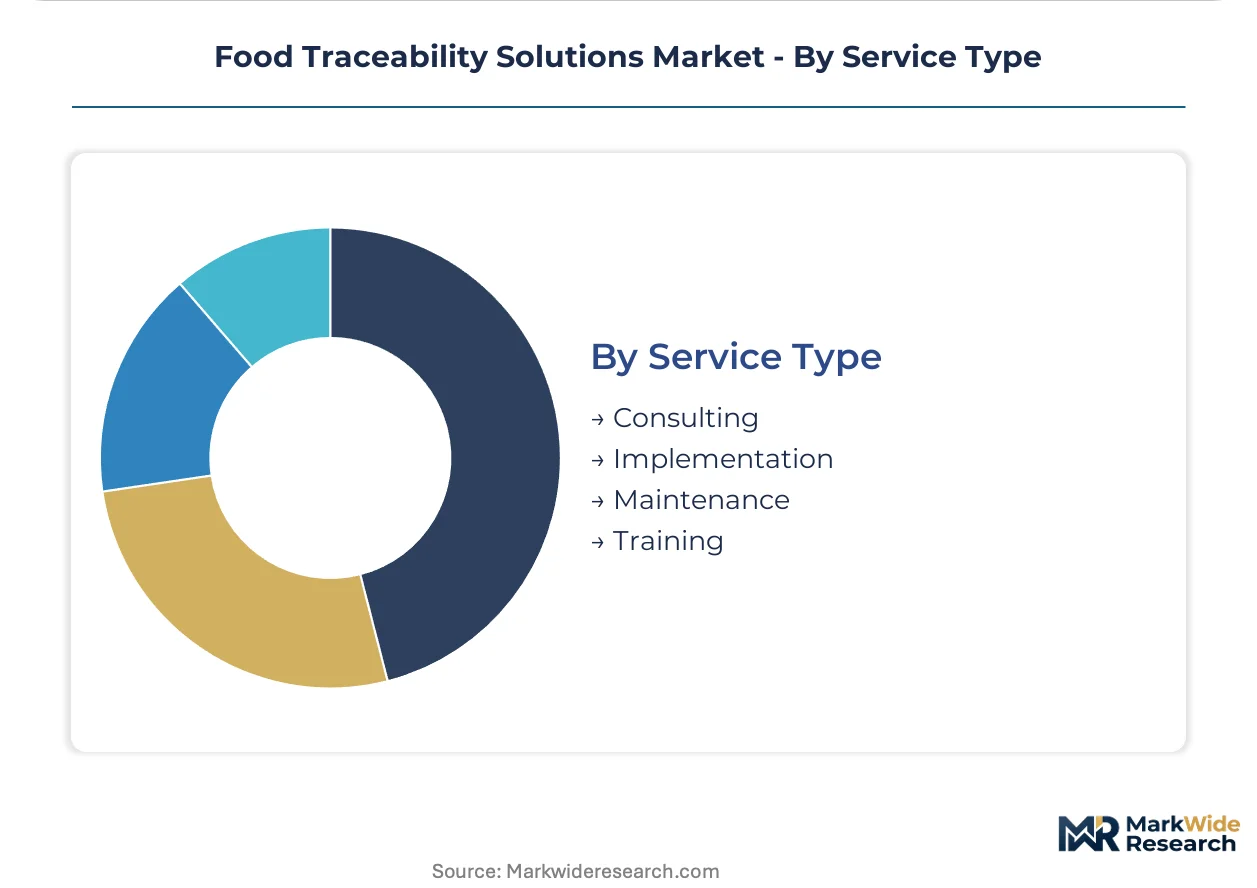
- Consulting:Advisory services guide technology selection, vendor evaluation, and regulatory alignment strategy. GS1 standard implementation skill gaps delay system commissioning, forcing facilities into vendor-dependent operational support relationships. Personnel shortages in global trade item number serialization persist across European processing facilities.
- Implementation:System deployment encompasses hardware installation, software configuration, and ERP integration. Custom API development requirements inflate total cost of ownership for mid-tier processors with constrained IT budgets. Multi-tier supplier onboarding complexity fragments chain-of-custody records.
- Maintenance:Continuous system validation and calibration generate recurring margin pools as regulated facilities require ongoing compliance verification. Subscription-based traceability networks prioritize continuous monitoring over one-time software deployments. Buyer audit cycle compression from annual to continuous monitoring reinforces service revenue durability.
- Training:Knowledge transfer programs build internal capability for system operation and data interpretation.
Maintenance commands the most predictable revenue streams. Implementation absorbs the largest absolute spending as first-time deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys blockchain-anchored compliance systems for mandatory Farm to Fork documentation, while the United States prioritizes FDA Food Safety Modernization Act lot-level tracking and India accelerates FSSAI-mandated digitization for packaged foods. These divergent regulatory architectures create distinct technology procurement patterns across major demand centers.
Germany
Meatpacking facilities and cold-storage operators drive demand for Hyperledger Fabric deployments under EU Green Deal implementation timelines. The Farm to Fork strategy mandates GS1-standardized origin documentation across all member states. Bavarian processing clusters absorb the highest compliance burden as downstream buyers require cryptographic immutability for liability protection.
United States
Institutional foodservice buyers and fresh produce distributors expand digital provenance tracking to satisfy downstream audit requirements. FDA Food Safety Modernization Act lot-level tracking mandates directly shape system design specifications and procurement timelines. California's Central Valley agricultural cooperatives face multi-tier supplier onboarding complexity as smallholder farms resist data sharing protocols.
India
FSSAI's phased digital traceability mandates for packaged foods create first-mover advantage for platforms pre-certified to Indian data localization requirements. The Food Safety and Standards Authority of India modernizes enforcement infrastructure across state jurisdictions. Maharashtra and Gujarat processing hubs absorb implementation spending as mid-tier operators confront legacy ERP integration burdens.
Netherlands
Cold-chain operators deploy edge computing nodes with embedded RFID readers at warehouse chokepoints to validate pallet integrity before release. REACH chemical documentation requirements expand data field specifications for pesticide-treated agricultural inputs. Rotterdam logistics corridors compress sensing and verification into single hardware layers, reducing latency between physical handling and record creation.
France
Large retail chains now require live dashboard visibility into supplier handling events rather than static quarterly reports. EFSA allergen labeling standards complicate data field requirements for European operators. Paris-based foodservice procurement networks favor subscription-based platform access over perpetual-license software, restructuring vendor revenue models toward recurring service fees.
Food Traceability Solutions Market Competitive Landscape
Capability concentration sits with specialized hardware-software integrators; scale advantage sits with enterprise software incumbents leveraging installed base penetration. The vendor landscape organizes around three archetypes: ERP-embedded traceability modules, ruggedized RFID infrastructure specialists, and distributed ledger platform providers. Dominant competitive moves include strategic partnerships between sensor manufacturers and blockchain protocol developers, plus vertical integration into cloud-based subscription networks.
Within the ERP-embedded tier, SAP SE leverages procurement workflow integration to anchor traceability modules within existing enterprise installations. Zebra Technologies occupies a position among ruggedized hardware specialists, with cold-chain RFID readers purpose-built for processing facility environments. IBM Corporation exemplifies the distributed ledger archetype through Hyperledger Fabric deployments that link multiple supplier tiers. These three anchors represent contrasting strategic postures: workflow embedding, physical infrastructure capture, and cryptographic verification networks.
| Leading Market Players |
|---|
| SGS SA |
| Honeywell International Inc. |
| Zebra Technologies |
| C.H. Robinson |
| Trustwell |
| Cognex Corporation |
| FoodLogiQ |
| SAP SE |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp logistics corridors absorb elevated freight costs from EU Green Deal compliance documentation requirements, concentrating pricing power among hardware-software integrators who control both RFID fabrication and blockchain platform deployment while forcing mid-tier processors toward subscription-based service models.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement as German meatpacking facilities lock in multi-year Hyperledger Fabric deployments under Farm to Fork mandates. Three-tier pricing structure across premium, standard, and economy levels separates cryptographic-ledger solutions from cloud-database architectures and basic GS1-compliant tagging systems. Cost compression in mid-tier hardware is intensifying because silicon supply volatility from concentrated Asian foundry capacity is feeding into extended equipment lead times. Smallholder agricultural cooperatives exhibit the highest price sensitivity, while institutional foodservice buyers absorbing liability protection requirements show minimal elasticity for blockchain-anchored premiums.
Supply Chain Analysis
Tariff exposure between China and EU member states dominates supply chain risk planning for RFID chip procurement, with hardware vendors absorbing margin pressure from concentrated foundry capacity. Taiwan, South Korea, and Malaysia anchor semiconductor fabrication for traceability hardware, while Germany and the Netherlands concentrate cold-chain infrastructure deployment. Component dependencies rest on silicon wafers, cryptographic security modules, and ruggedized environmental sensors. Distribution runs through processor-distributor-retailer hierarchies, though direct-to-retailer channel bypass is disintermediating traditional data aggregation roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of GS1-standardized serialization expertise and EPCIS event repository management capability are constraining deployment velocity, creating asymmetric returns for vendors who internalize training and certification functions.
For Market Incumbents: Harden blockchain platform interoperability through middleware development investments that neutralize protocol fragmentation risks threatening customer retention. SAP SE and IBM Corporation should deepen backward integration into sensor hardware to capture margin pools migrating from software licenses to integrated service contracts. Certification pre-positioning for India's FSSAI data localization requirements offers defensive positioning against emerging platform competitors. For New Entrants and Emerging Players: Build out sensor-blockchain convergence offerings targeting quality control applications in temperature-sensitive perishables, where real-time environmental attestation commands premium positioning. India's phased FSSAI modernization represents the most penetrable regulatory window for platforms achieving pre-certification. Direct-to-retailer channel strategies disintermediate established distributor relationships and accelerate procurement system integration. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive food processing traceability units lacking standalone platform scale. Long-term viability hinges on recurring service revenue durability rather than perpetual-license dependence. Watch for EU member state implementation timeline acceleration as inflection signal for hardware-software integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Protocol Interoperability Investment | Hyperledger Fabric deployments require middleware layers to satisfy multi-platform buyer environments. |
| Sensor-Blockchain Convergence Development | IoT environmental sensors feeding distributed ledgers enable real-time quality attestation premiums. |
| FSSAI Pre-Certification Positioning | Indian data localization compliance creates first-mover advantage for packaged food traceability. |
| Direct-to-Retailer Channel Bypass | Producer-owned platforms transmit provenance data straight to grocery chain procurement systems. |
| GS1 Standard Training Program Buildout | Personnel shortages in EPCIS event repository management delay system commissioning timelines. |
Research Methodology
A standing panel of cold-chain operations directors, food safety compliance officers, ERP integration specialists, and agricultural cooperative managers provided ongoing calibration against operating reality. Primary interview findings combined with secondary validation from FDA Food Safety Modernization Act filings, EU Green Deal implementation timelines, FSSAI regulatory notices, and customs trade data for RFID hardware imports. Bottom-up deployment estimates triangulated against top-down market sizing across technology, end user, application, and service type dimensions.
Scenario-bracketing framed projections across the analysis window, modeling baseline, accelerated regulatory, and delayed compliance pathways. Segmentation dimensions included technology architecture, buyer procurement authority tier, functional application priority, and revenue model structure. CAGRs derived from deployment trajectory analysis incorporating hardware replacement cycles, software subscription renewal patterns, and service contract duration distributions. Forecast inputs captured silicon supply lead time volatility and EU member state implementation schedule dispersion.
Stress conditions across Asian foundry capacity constraints, blockchain protocol interoperability friction, and multi-tier supplier onboarding resistance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption curve steepness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Water Activity Instrumentation Market