
 Personal Care Specialty Ingredients Market | 2026-2036
Personal Care Specialty Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care Specialty Ingredients Market Analytics
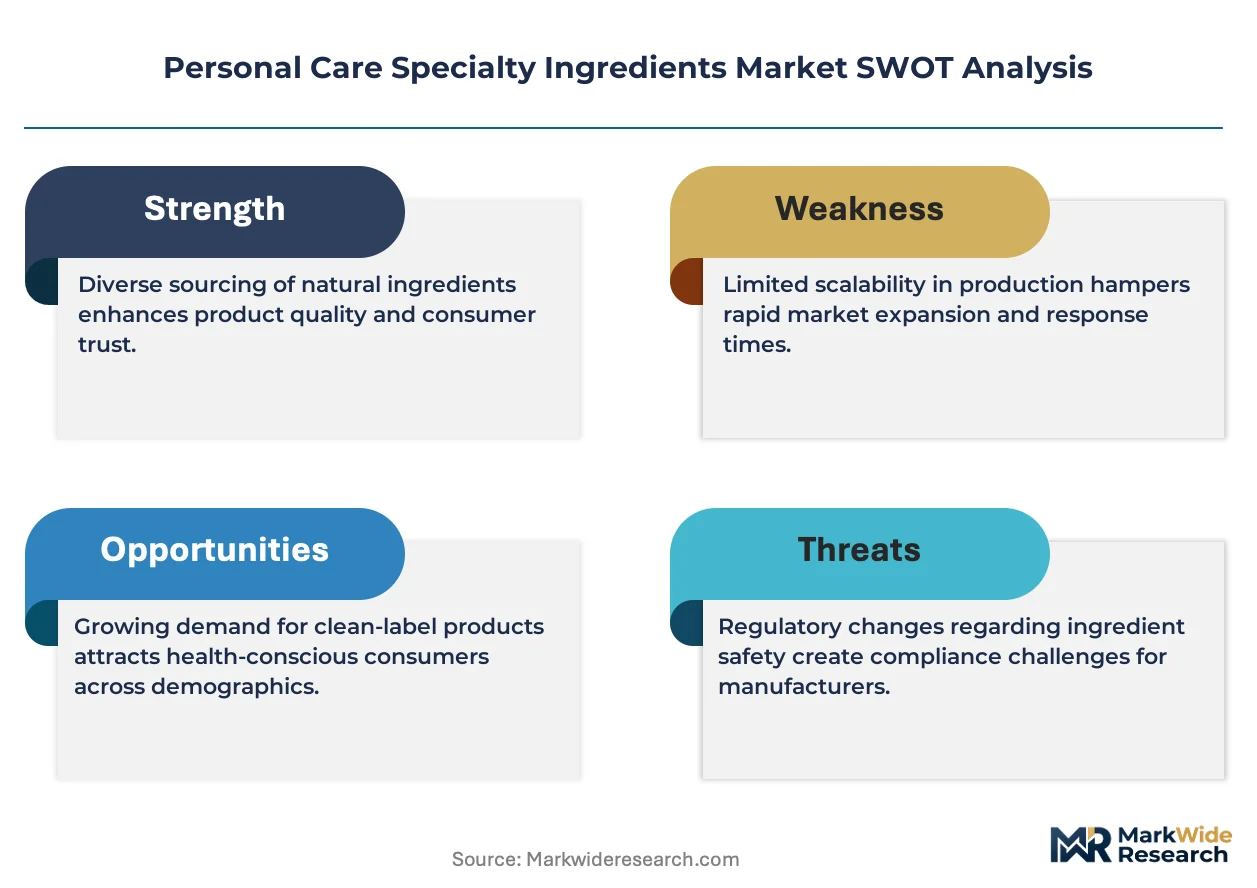
Market Dynamics
Biotechnology-driven ingredient synthesis is rewriting the cost-performance equation for active molecules in personal care. BASF SE leverages its integrated biotechnology platforms to anchor supply of fermented ceramides and peptides at industrial scale. Croda International Plc sustains premium positioning through specialized lipid chemistry that dominates the high-end emollient segment. Evonik Industries AG competes on R&D intensity, particularly in silicone alternatives and biobased surfactants that navigate tightening environmental standards.
Product Architecture
Personal care specialty ingredients comprise functionally active and auxiliary compounds formulated at precise concentrations to deliver sensory, preservation, or therapeutic benefits in finished consumer products. These materials typically require molecular weights below 10,000 daltons for skin penetration, with manufacturing processes spanning enzymatic catalysis, solvent extraction, and controlled polymerization to achieve batch-to-batch consistency. Emollients and thickeners occupy the largest value pools given their irreplaceable role in texture engineering, while bio-based surfactants represent the fastest-expanding category as formulators phase out petrochemical ethoxylates. Preservatives remain structurally constrained by regulatory tightening, pushing margin concentration toward novel peptide-based antimicrobial systems that command technical premiums.
Regulatory Environment
The EU REACH regulation and ECHA substance evaluations systematically restrict conventional preservatives and synthetic fragrances, forcing ingredient suppliers to validate alternatives through extensive safety dossiers. The FDA and EPA jointly influence the US landscape through cosmetic labeling requirements and antimicrobial chemical reviews that shape permissible actives. China's NMPA and GB standards for cosmetics ingredients impose additional registration burdens that favor established suppliers with dedicated regulatory affairs capacity. Stakeholders must monitor the divergence between EU precautionary restrictions and US risk-based assessments, as this regulatory fragmentation determines which ingredient platforms achieve cross-border commercial viability.
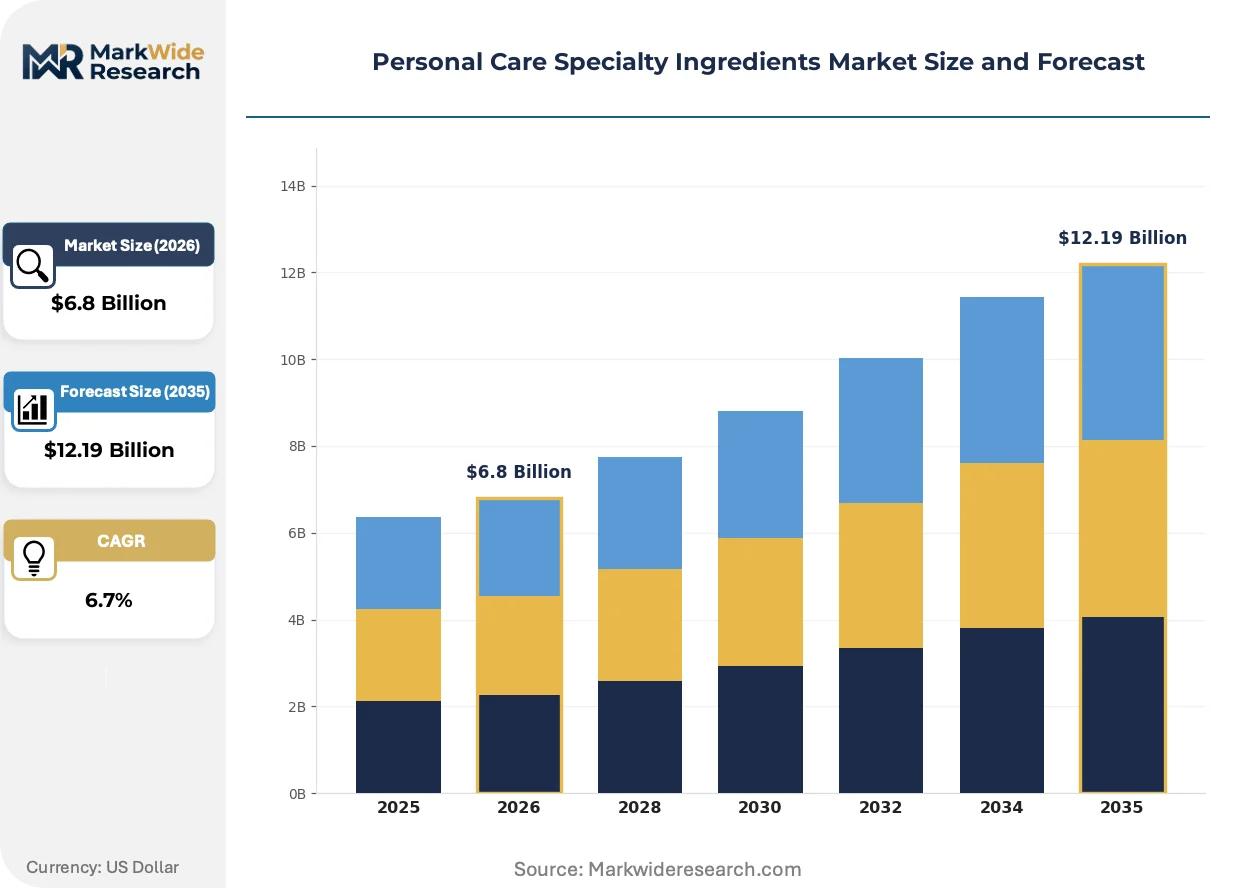
Market Dynamics
Biotechnology platforms are compressing development cycles for active molecules while EU REACH substance evaluations systematically eliminate legacy chemistries, forcing simultaneous innovation and compliance investments across supplier networks.
Growth Catalysts
- EU REACH substance restrictions:Regulatory phase-outs of conventional preservatives and synthetic fragrances create immediate substitution demand for peptide-based antimicrobial systems and biotech-derived alternatives.
- China domestic beauty brand scaling:Local champions like Bloomage Biotech and Proya build captive fermentation capacity, pulling regional supply chains toward biomanufacturing hubs in Shanghai and Guangzhou.
- Multifunctional active convergence:Single-molecule formulations delivering barrier repair plus microbiome balance reduce SKU complexity for skincare brands and command formulation premiums.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and fatty alcohol price swings compress margins for surfactant manufacturers, particularly those without backward integration into oleochemical supply.
- Regulatory dossier costs:ECHA safety data requirements and China's NMPA registration burdens favor established suppliers with dedicated regulatory affairs teams, raising barriers for mid-scale entrants.
- Enzymatic catalysis scale limits:Batch-to-batch consistency challenges in fermentation-derived ceramides constrain supply elasticity during demand spikes.
Strategic Opportunities
- India personal care manufacturing:PLI scheme incentives for specialty chemicals and underdeveloped local biotech ingredient capacity create first-mover advantages for fermentation platform investors.
- Silicone-alternative convergence:Biobased emollients combined with sensorial engineering from cosmetic chemistry address clean-label preferences without sacrificing texture performance.
- Direct-to-brand distribution:Bypassing traditional distributor networks through digital sampling platforms reduces customer acquisition costs for niche active suppliers targeting indie beauty brands.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology and downstream processing expertise concentrates at a handful of European and Chinese contract manufacturers, constraining capacity expansion timelines.
- Cross-regulatory compliance synchronization:Divergent safety assessment protocols between EU precautionary standards and US FDA risk-based evaluations force redundant toxicology studies and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care Specialty Ingredients Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Thickeners, Surfactants, Preservatives Application: Hair Care, Skin Care, Oral Care, Makeup Form: Liquid, Powder, Gel, Cream Source: Natural, Synthetic, Organic, Bio-based |
| Companies Covered | Dow Inc., Ashland Global Holdings, BASF SE, Lubrizol Corporation, Solvay S.A., Croda International Plc, Clariant AG, Syensqo SA/NV, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care Specialty Ingredients Market Evolving Landscape
Ingredient synthesis is migrating from petrochemical platforms toward precision fermentation and cell-free enzymatic systems, compressing molecular development timelines while expanding the accessible chemical space for cosmetic actives.
Precision fermentation technology is hybridizing pharmaceutical-grade manufacturing discipline with cosmetic ingredient economics. Specialty chemical suppliers now adopt GMP-adjacent process controls historically reserved for drug actives. This convergence enables pharmaceutical and cosmetic co-manufacturing facilities, spreading capital intensity across regulated industries while raising quality benchmarks for skincare actives.
REACH authorization requirements and ECHA SVHC candidate list expansions are systematically removing parabens, formaldehyde releasers, and certain isothiazolinones from permissible preservative palettes. Formulators respond by accelerating peptide-based antimicrobial development and hurdle technology combining mild organic acids with chelating agents. The preservative segment experiences the fastest regulatory turnover, with novel systems commanding technical premiums during transition periods.
Beauty brand R&D teams now embed microbiome testing protocols into early-stage formulation development, shifting from generic claims to strain-specific efficacy demonstrations. This behavioral pivot elevates suppliers with clinical testing infrastructure and published skin microbiome datasets. European indie brands and Chinese domestic champions lead this transition, pressuring multinational heritage brands to retrofit substantiation capabilities.
Personal Care Specialty Ingredients Market Segmentation
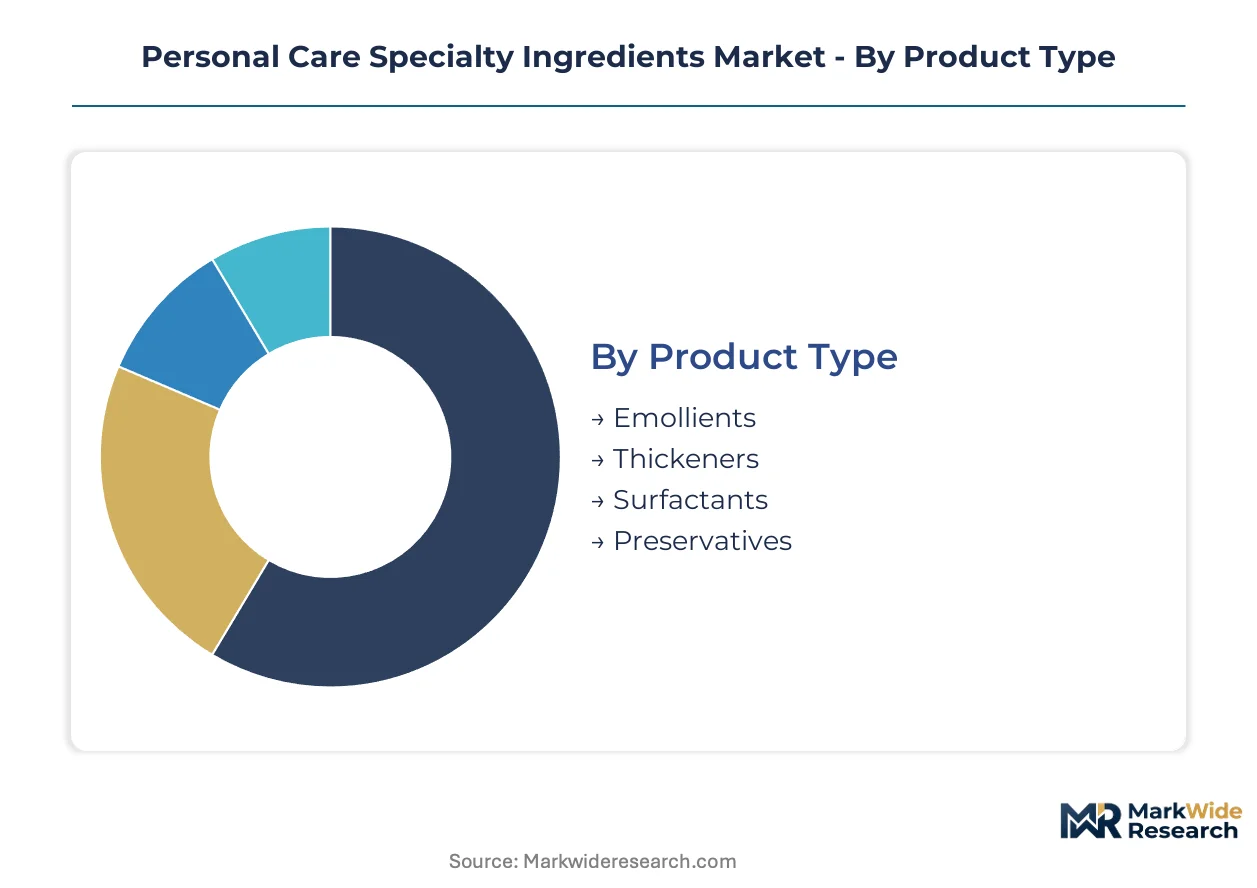
Ingredient segmentation in personal care specialty chemicals determines formulation economics and regulatory pathway selection. Formulators balance performance specifications against REACH compliance costs and microbiome claim substantiation requirements when allocating R&D budgets across segment categories.
Product Type:
Cost tier differentiation separates commodity surfactants from premium peptide-based actives, with margin concentration shifting toward biotech-derived platforms.
- Emollients:Lipid chemistry spanning esters, fatty alcohols, and plant-derived oils delivers skin barrier function and sensory modulation. Demand concentrates in high-end skin care formulations across Germany and France, where clean-label preferences accelerate silicone-alternative adoption despite higher raw material costs.
- Thickeners:Rheology modifiers including carbomers, cellulose derivatives, and associative polymers control product texture and suspension stability. Chinese domestic brands in Shanghai and Guangzhou drive volume, pulling regional supply chains toward localized acrylic acid derivative production.
- Surfactants:Surface-active agents reduce interfacial tension for cleansing and emulsification functions.
- Preservatives:Antimicrobial systems prevent microbial contamination in aqueous formulations.
Emollients hold installed capacity. Thickeners are rotating up the share rankings.
Application:
Application scope determines clinical testing requirements and regulatory dossier complexity, with skin care commanding the most intensive substantiation protocols.
- Skin Care:Facial moisturizers, serums, and treatment products incorporate barrier-repair ceramides and microbiome-targeted actives at precise concentrations. European indie brands and Chinese champions like Bloomage Biotech lead strain-specific efficacy demonstrations, elevating suppliers with published skin microbiome datasets.
- Hair Care:Shampoos, conditioners, and styling products rely on cationic surfactants and conditioning polymers for manageability and damage repair. Formulators in India prioritize sulfate-free systems under PLI scheme incentives, creating substitution demand for mild biosurfactants.
- Oral Care:Toothpastes and mouthwashes require flavor-compatible actives with established safety profiles.
- Makeup:Color cosmetics demand pigment-dispersing emollients and film-forming polymers for wear resistance.
Skin care captures formulation premiums. Hair care is climbing the fastest.
Form:
Physical state dictates manufacturing equipment requirements and supply chain handling protocols, with liquid concentrates dominating industrial-scale production.
- Liquid:Pumpable concentrates and dispersions enable continuous manufacturing and automated dosing systems. BASF SE and Evonik Industries AG anchor industrial supply from Ludwigshafen and Essen, serving contract manufacturers with just-in-time delivery requirements.
- Powder:Spray-dried actives and excipients offer extended shelf stability and reduced shipping costs. Japanese formulators in Osaka and Tokyo specify pharmaceutical-grade particle size distributions for pressed powder cosmetics.
- Gel:Pre-hydrated polymer networks simplify cold-process formulation.
- Cream:Pre-emulsified bases reduce manufacturing complexity for small-batch producers.
Liquid holds installed capacity. Powder is rotating up the share rankings.
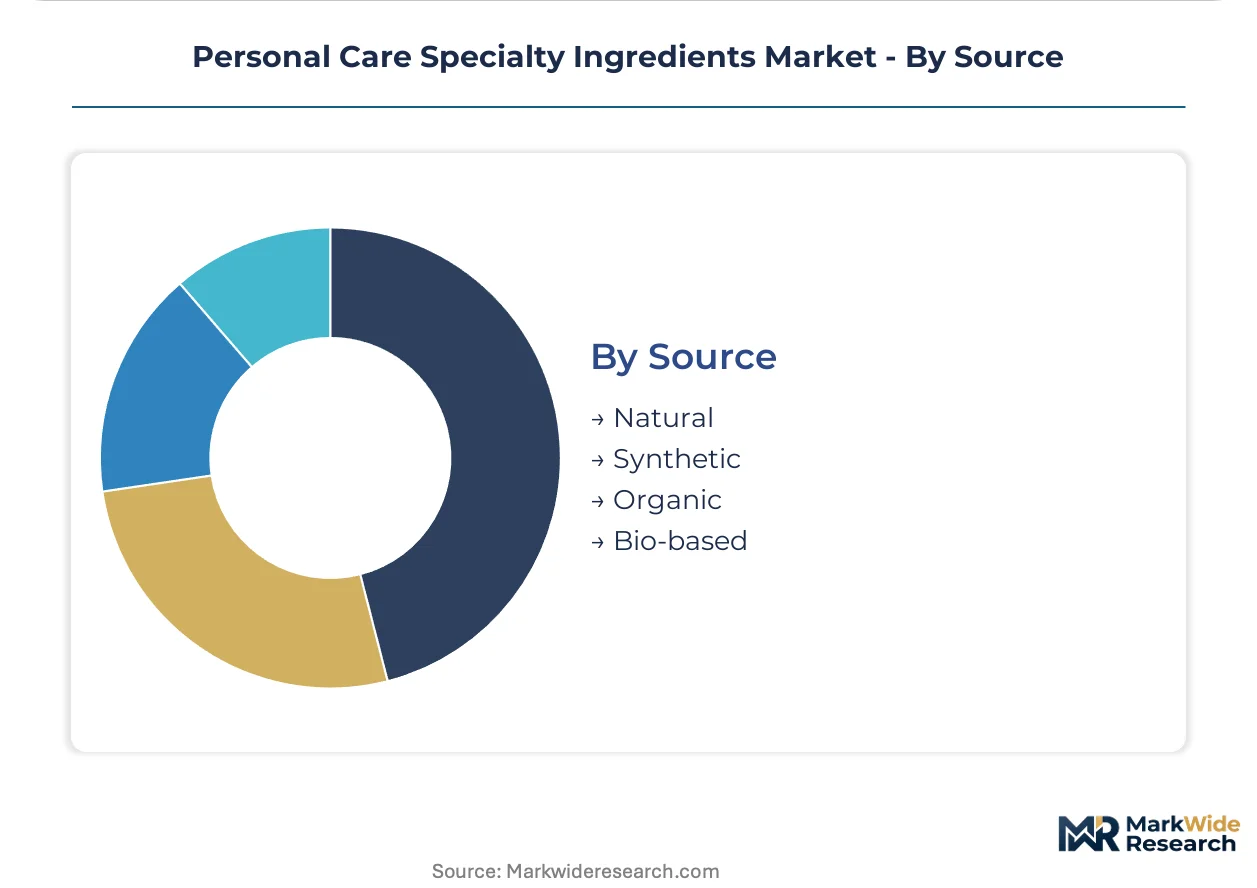
Source:
Feedstock origin determines regulatory classification and consumer positioning, with bio-based platforms capturing investment amid petrochemical volatility.
- Natural:Botanically derived extracts and oils require supply chain traceability and contamination controls. Croda International Plc sustains premium positioning through specialized lipid chemistry sourced from established agricultural cooperatives.
- Synthetic:Petrochemical-derived molecules offer batch consistency and cost predictability. Ethylene oxide price swings compress margins for surfactant manufacturers without backward integration into oleochemical supply.
- Organic:Certified agricultural inputs meet COSMOS and USDA standards for clean-label positioning.
- Bio-based:Fermentation-derived and enzymatically synthesized molecules navigate tightening environmental standards.
Synthetic holds installed capacity. Bio-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical exports supply formulation houses across France and the United Kingdom, establishing Rhine-Ruhr industrial corridors as the primary trade-flow artery for personal care actives into Western European beauty manufacturing.
China
Domestic champions Bloomage Biotech and Proya scale captive fermentation capacity for hyaluronic acid and peptide actives. NMPA registration requirements under GB standards favor established suppliers with dedicated regulatory affairs teams. Shanghai and Guangzhou biomanufacturing hubs pull regional supply chains toward precision fermentation platforms.
United States
Indie beauty brands in Los Angeles and New York Metro drive demand for microbiome-targeted actives with clinical substantiation. FDA cosmetic labeling requirements and EPA antimicrobial chemical reviews shape permissible preservative systems. New Jersey and Texas chemical corridors anchor surfactant and emollient production for North American formulators.
Germany
REACH authorization requirements and ECHA SVHC candidate list expansions systematically eliminate parabens and formaldehyde releasers from preservative palettes. BASF SE leverages integrated biotechnology platforms at Ludwigshafen for industrial-scale fermented ceramides. Rhine-Ruhr specialty chemical clusters supply silicone alternatives and biobased surfactants across EU markets.
India
PLI scheme incentives for specialty chemicals attract fermentation platform investors to Maharashtra and Gujarat. Sulfate-free hair care formulations create substitution demand for mild biosurfactants among domestic brands. Mumbai and Ahmedabad manufacturing clusters expand oleochemical backward integration for surfactant feedstock security.
France
Clean-label preferences accelerate silicone-alternative adoption in Paris and Lyon premium skincare formulations. ANSM cosmetic safety assessments align with EU REACH precautionary standards. Île-de-France and Auvergne-Rhône-Alpes anchor lipid chemistry innovation for high-end emollient segments serving heritage beauty houses.
Personal Care Specialty Ingredients Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The supplier base concentrates around integrated chemical conglomerates with fermentation platforms, specialized lipid chemistry houses, and regional surfactant manufacturers. Three archetypes dominate: biotechnology-anchored active suppliers, premium emollient specialists, and scale-driven surfactant producers. Competitive moves center on backward integration into oleochemical supply and strategic partnerships with indie beauty brands for direct distribution.
Within the biotechnology-anchored tier, BASF SE and Evonik Industries AG exemplify integrated platform players with industrial-scale fermentation capabilities. Croda International Plc occupies a position among specialized lipid chemistry houses serving premium formulation segments. These three entities represent distinct competitive vectors—scale-driven biomanufacturing, R&D-intensive silicone alternatives, and sensory-engineered emollient systems—that define strategic positioning across the ingredient value chain.
| Leading Market Players |
|---|
| Dow Inc. |
| Ashland Global Holdings |
| BASF SE |
| Lubrizol Corporation |
| Solvay S.A. |
| Croda International Plc |
| Clariant AG |
| Syensqo SA/NV |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Rhine-Ruhr container corridors anchor cost dynamics for specialty ingredient logistics, linking German fermentation hubs to French formulation houses. Supply concentration in Ludwigshafen and Essen creates tiered pricing power, while downstream brands differentiate on biotech certification grade rather than commodity spot benchmarks.
Pricing Analysis
Prior-generation petrochemical surfactants trade at compressed margins, current-generation fermented ceramides command formulation premiums, and next-generation cell-free enzymatic actives sit at pre-commercial price discovery. Three-tier pricing structure across premium biotech-certified, standard bio-based, and economy petrochemical levels separates buyers by substantiation requirements. Cost compression in commodity thickeners is intensifying because Chinese acrylic acid derivative capacity expansion outpaces regional demand growth. Indie beauty brands in Los Angeles exhibit highest price sensitivity, while Paris heritage houses accept technical premiums for microbiome-validated actives.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain working capital for mid-scale fermentation suppliers, forcing supply-chain finance facility adoption. Manufacturing concentrates in Germany, China, and India, with raw material dependencies spanning oleochemical feedstocks, fermentation nutrients, and pharmaceutical-grade solvents. Single-source vulnerability in industrial microbiology talent constrains batch-to-batch consistency for peptide-based antimicrobials. Distribution runs through direct-to-brand digital platforms and traditional specialty chemical distributors serving contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as microbiome claim substantiation requirements splinter demand across specialized testing infrastructure providers. Clean-label preferences create niches for regional biotech champions with published skin microbiome datasets.
For Market Incumbents: Entrench biotechnology platform advantages through captive fermentation capacity additions in Shanghai and Guangzhou biomanufacturing hubs. Backward integration into oleochemical supply secures surfactant feedstock margins against ethylene oxide volatility. Patent-protected peptide-based antimicrobial systems defend against commodity preservative substitution.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat PLI incentive zones represent the most penetrable entry point for fermentation platform investors, given underdeveloped local biotech ingredient capacity and sulfate-free hair care substitution demand. Direct-to-brand digital sampling platforms bypass distributor markups for indie beauty brand acquisition. Microbiome testing service bundling creates differentiated positioning against commodity active suppliers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fermentation assets and stranded preservative portfolios facing REACH phase-outs. Five-to-ten year viability hinges on regulatory affairs capacity for cross-border dossier navigation. Signal to watch: ECHA SVHC candidate list expansion velocity accelerating novel antimicrobial development timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Supply | Croda International Plc secures lipid chemistry feedstock margins against agricultural commodity swings. |
| Precision Fermentation Capacity Expansion | BASF SE anchors industrial-scale ceramide supply for barrier-repair skincare formulations. |
| Direct-to-Brand Digital Platform Launch | Niche active suppliers reduce customer acquisition costs targeting Los Angeles indie beauty brands. |
| Microbiome Testing Infrastructure Investment | European indie brands and Chinese champions demand strain-specific efficacy demonstration capabilities. |
| Regulatory Affairs Capability Buildout | Established suppliers navigate divergent EU precautionary and US FDA risk-based assessment protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, ECHA substance evaluation registers, and NMPA cosmetic ingredient filings. Interviews with fermentation plant managers, procurement leads at downstream skincare OEMs, technical R&D directors, and regulatory affairs specialists inform capacity and pricing dynamics. Bottom-up volume modeling triangulates against top-down value estimates from specialty chemical distributor channel checks.
Forecast inputs span biotechnology platform adoption curves, REACH authorization timelines, and China domestic brand scaling trajectories across the analysis window. Segmentation dimensions include ingredient function, application category, physical form, and feedstock origin. CAGRs derive from elasticity-adjusted volume projections and price-premium capture rates for biotech-derived actives. Fermentation scale-up constraints and regulatory dossier cost inflation feature as industry-specific demand dampeners.
Macroeconomic conditions sit as an overlay; deviation in ethylene oxide pricing, euro-yuan exchange rates, or EU-China regulatory harmonization progress would shift the trajectory. Forecasts reflect documented assumptions regarding biotech platform maturation and preservative substitution velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Specialty Beverage Stabilizers Market