
 Spain Probiotic Drinks Market | 2026-2036
Spain Probiotic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Probiotic Drinks Market Insights
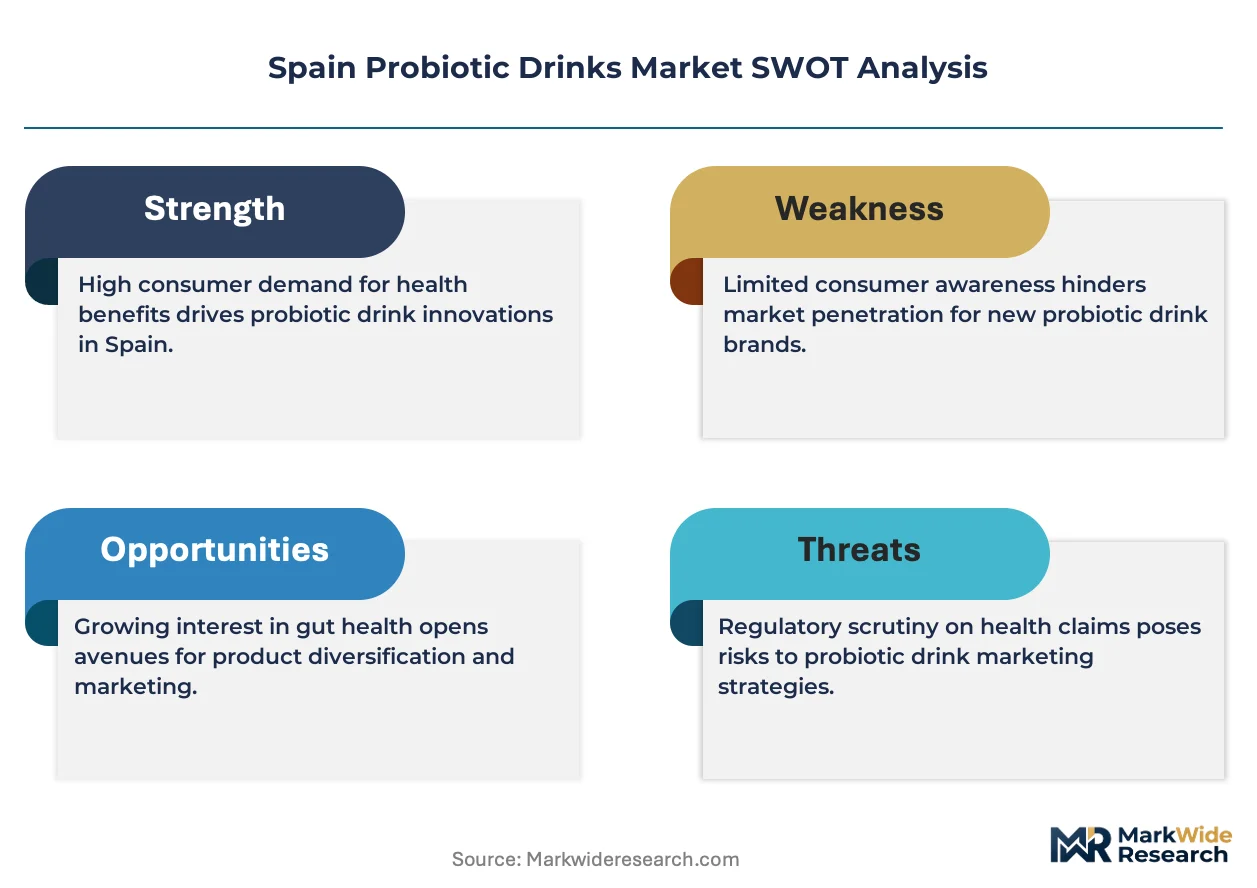
EU health claims authorization under Regulation (EC) No 1924/2006 is rotating competitive access, as only strains with validated probiotic dossiers qualify for on-label functional claims. DANONE Spain leverages its extensive refrigerated distribution network to sustain shelf dominance across Iberian retail chains. YAKULT ESPAÑA S.A. anchors its position through dedicated home-delivery infrastructure and pharmacist channel relationships in metropolitan zones. KAIKU CORPORACIÓN ALIMENTARIA, S.L. differentiates via Basque-country production heritage and regional co-operative sourcing models.
Spain probiotic drinks comprise live microbial cultures suspended in fermented liquid matrices, typically containing minimum 10^6 CFU per milliliter at consumption, delivering gastrointestinal and immune-modulatory benefits through active colonization. Fermented dairy occupies the dominant value share given established consumer acceptance and daily consumption rituals, while kombucha registers accelerated growth trajectory driven by younger demographics seeking low-alcohol alternatives. Supermarkets control primary volume flows, though health food stores capture disproportionate margin pools through premium positioning and personalized consultation services.
AESAN enforces Spain's implementation of EU Food Information to Consumers Regulation, mandating precise strain enumeration and storage condition disclosure that elevates compliance costs for smaller fermenters. The EU Green Deal's Farm to Fork strategy pressures packaging sustainability and agricultural input traceability across the supply base. Stakeholders must monitor evolving strain-specific health claim approvals and carbon footprint auditing requirements to secure long-term market authorization.
Market Dynamics
EU strain-specific health claim authorization under EFSA guidance is compressing competitive access, forcing reformulation investments and eliminating non-dossiered cultures from functional positioning claims across Iberian retail shelves.
Growth Catalysts
- Urban health consciousness:Madrid and Barcelona consumers integrate fermented beverages into daily rituals, expanding household penetration beyond traditional yogurt occasions.
- AESAN food safety alignment:Spain's implementation of EU Food Information to Consumers Regulation elevates consumer trust through mandatory live culture enumeration and cold-chain transparency.
- Plant-based fermentation advances:Oat and almond milk matrices now sustain viable probiotic loads, unlocking lactose-intolerant and vegan demographics previously excluded from dairy-centric offerings.
Market Restraints
- Refrigerated distribution costs:Cold-chain requirements for 10^6 CFU/ml viability elevate logistics spend versus ambient beverage categories.
- Strain validation concentration:EFSA-approved probiotic dossiers cluster with a limited cohort of culture suppliers, creating input dependency.
- Kombucha alcohol variability:Secondary fermentation produces trace ethanol levels that trigger beverage-alcohol reclassification risks under Spanish excise frameworks.
Strategic Opportunities
- Andalusian and Galician expansion:Secondary metropolitan zones show underpenetrated functional beverage adoption relative to Madrid-Barcelona saturation.
- Pharmacist channel development:Professional recommendation networks in Valencia and Seville offer credibility positioning distinct from mass retail.
- EU Green Deal packaging mandates:Farm to Fork strategy incentives for recyclable and bio-based materials create first-mover sustainability branding potential.
Industry Challenges
- Live culture stability expertise:Shelf-life engineering for ambient-stable probiotic matrices demands specialized fermentation science talent scarce in Iberian food technology labor pools.
- Multi-strain compatibility testing:Synergistic culture combinations require extensive stability validation, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Probiotic Drinks Market |
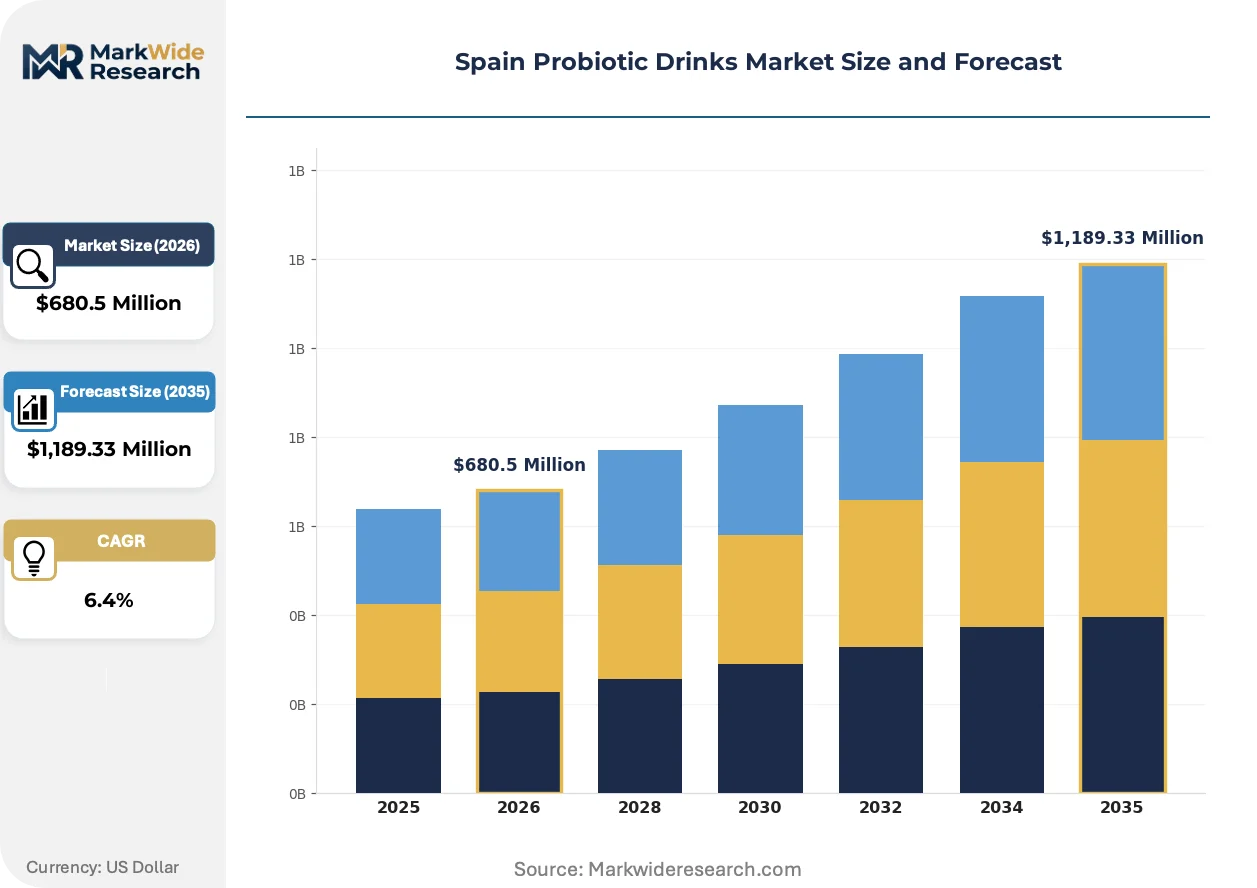
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,189.33 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Probiotic Juices, Fermented Dairy Distribution Channel: Supermarkets, Online Stores, Health Food Stores, Convenience Stores Customer Type: Health-Conscious Consumers, Fitness Enthusiasts, Parents, Seniors Flavor Profile: Berry, Citrus, Ginger, Vanilla |
| Companies Covered | Grupo Postres Reina S.L., En Komvida Kombucha, S.L., MUN FERMENTS SL, DANONE Spain, YAKULT ESPAÑA S.A., NESTLÉ LACTALIS NESTLÉ REFRIGERATED DAIRY PRODUCTS IBERIA, KAIKU CORPORACIÓN ALIMENTARIA, S.L., ADM, Probi AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Probiotic Drinks Market Trends and Innovations
Spanish probiotic drink development is pivoting toward strain-specific functional positioning, precision fermentation, and channel-specific formulation as manufacturers seek differentiation beyond generic digestive health claims.
Microencapsulation technology using alginate and pectin coatings is miniaturizing protective matrices around live cultures, enabling ambient distribution without refrigeration. Basque and Catalonian producers are piloting these systems for pharmacy and direct-to-consumer channels. The compression of cold-chain dependency is reshaping margin structures and geographic reach.
EU Nutrition and Health Claims Regulation (EC) No 1924/2006 is tightening strain-specific authorization requirements, invalidating generic "probiotic" labeling for non-dossiered cultures. Spanish manufacturers must submit individual strain clinical packages to EFSA for functional claim eligibility. Fermented dairy incumbents with validated strain libraries gain regulatory moat advantages over kombucha entrants lacking comparable documentation.
Subscription-based home delivery is displacing supermarket bulk purchasing among metropolitan millennials seeking personalized strain rotation and freshness guarantees. Madrid-based start-ups offer monthly curated boxes with microbiome testing integration. This behavioral shift concentrates lifetime value capture and reduces price sensitivity versus retail shelf competition.
Spain Probiotic Drinks Market Segmentation
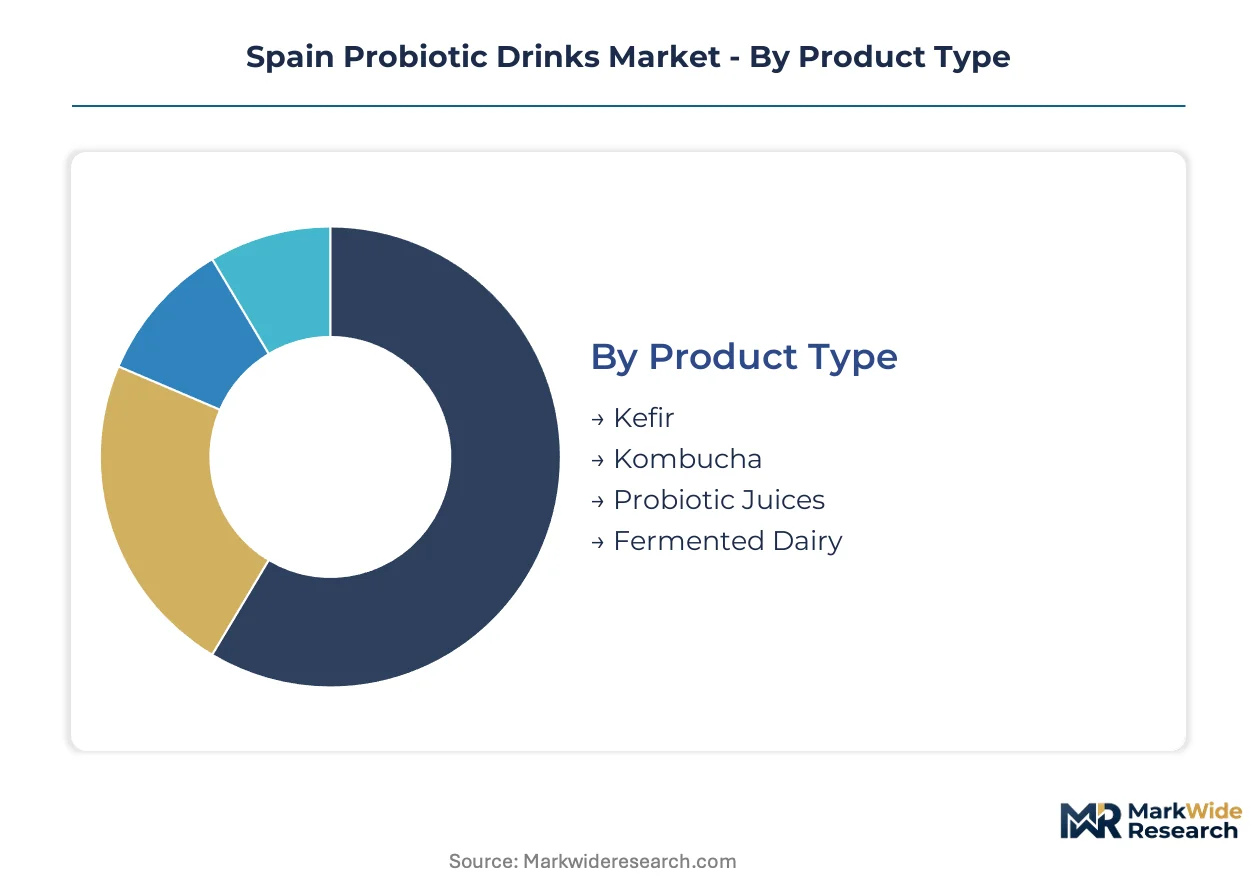
Segmentation in the Spain probiotic drinks market reveals how AESAN's strain-specific labeling requirements and EFSA health claim protocols create divergent compliance burdens across product matrices. Manufacturers must align formulation investments with channel cold-chain capabilities and demographic consumption rituals to secure viable positioning.
Product Type:
EFSA's strain-by-strain authorization under Regulation (EC) No 1924/2006 fragments competitive access, as only dossiered cultures qualify for functional gastrointestinal claims on Spanish retail shelves.
- Fermented Dairy:Traditional yogurt and drinkable kefir matrices deliver 10^6 CFU/ml viability through established cold-chain infrastructure. Basque co-operatives and Catalan dairy clusters dominate household penetration in Madrid and Barcelona, where daily consumption rituals anchor repeat purchase frequency.
- Kombucha:Tea-based fermentation with SCOBY cultures generates trace ethanol variability that triggers Spanish excise reclassification risks. Younger demographics in Barcelona's metropolitan zone drive trial adoption, though secondary fermentation unpredictability constrains mass retail scaling.
- Kefir:Caucasus-origin fermented milk with diverse yeast-bacterial symbiosis supports broader digestive health positioning. Andalusian producers leverage regional dairy heritage for differentiation.
- Probiotic Juices:Fruit matrices with microencapsulated cultures face pH stability challenges requiring specialized shelf-life engineering. Valencia citrus processors experiment with ambient-stable formulations.
Established volume favors fermented dairy; emerging adoption favors kombucha.
Distribution Channel:
Cold-chain cost tiers stratify channel economics, with refrigerated logistics consuming margin share in direct proportion to temperature sensitivity.
- Supermarkets:Mercadona, Carrefour España, and El Corte Inglés hypermarket networks control primary volume flows through dedicated refrigerated aisles. National distribution agreements demand 10^6 CFU/ml viability guarantees across 72-hour delivery windows.
- Health Food Stores:Herbolarios and specialized retailers in Barcelona's Gràcia district capture disproportionate margin pools through pharmacist-grade consultation and strain-specific curation. Premium positioning justifies 40-60% price elevation over mass retail.
- Online Stores:Direct-to-consumer platforms enable subscription-based freshness guarantees and microbiome test integration. Madrid-based start-ups concentrate lifetime value capture among metropolitan millennials.
- Convenience Stores:Ambient-stable probiotic shots with microencapsulation technology penetrate gas station and urban kiosk networks. Shelf-life engineering investments offset refrigeration absence.
Volume concentrates in supermarkets; margin concentrates in health food stores.
Customer Type:
Demographic targeting aligns strain selection with life-stage health priorities, from pediatric immunity to senior digestive maintenance.
- Health-Conscious Consumers:Urban professionals in Madrid integrate fermented beverages into preventive wellness routines. EFSA-authorized gastrointestinal claims drive purchase decisions over generic probiotic labeling.
- Parents:Pediatric-formulated drinkable yogurts with Lactobacillus rhamnosus GG target immunity positioning for school-age children. Galician dairy processors specialize in reduced-sugar variants.
- Fitness Enthusiasts:Post-workout recovery positioning with protein-fortified kefir gains traction in Barcelona gym channels. Strain-specific muscle recovery claims remain unauthorized, limiting functional messaging.
- Seniors:Digestive comfort and nutrient absorption formulations address aging gastrointestinal sensitivity. Pharmacy channel relationships in Valencia support credibility positioning.
Health-conscious consumers anchor volume; parents represent the steepest expansion trajectory.
Flavor Profile:
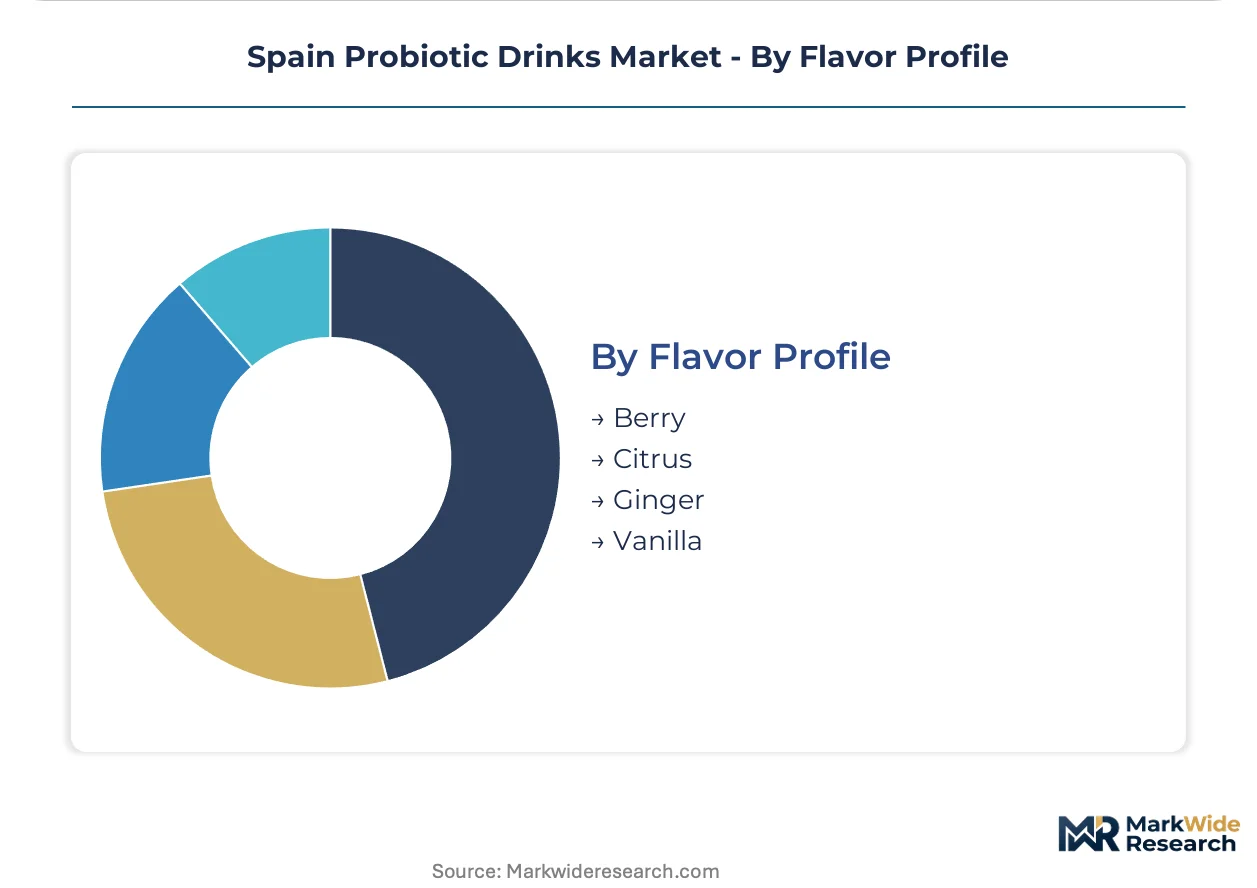
Regional agricultural sourcing and fermentation biochemistry constrain flavor development, as live culture viability interacts with pH and polyphenol content.
- Berry:Strawberry and blueberry formulations mask kombucha's acetic acid sharpness while supplying antioxidant synergism. Basque producers source from regional cultivation cooperatives.
- Citrus:Valencia orange and lemon profiles dominate probiotic juice segments, leveraging proximity to Spain's primary citrus belt. pH stability challenges require microencapsulation investment.
- Ginger:Zingiber officinale addition supports digestive positioning in kombucha and kefir variants. Andalusian organic ginger suppliers serve craft fermenters.
- Vanilla:Planifolia extract softens fermented dairy's lactic acid bite for pediatric and senior palates. Madagascar and Tahitian sourcing elevates premium tier positioning.
Berry and citrus dominate current formulations; ginger gains share fastest in functional positioning segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious urban professionals in Madrid and Barcelona drive concentrated demand for functional fermented beverages, while secondary metropolitan zones present expansion vectors for chilled distribution networks.
Madrid
Preventive wellness routines among metropolitan professionals sustain daily consumption rituals for drinkable yogurts and kefir variants. AESAN's cold-chain transparency mandates elevate compliance investments for refrigerated logistics providers serving the capital's supermarket networks. Pharmacy channel relationships in Chamberí and Salamanca districts support credibility positioning for pediatric and senior formulations.
Catalonia
Barcelona's younger demographics accelerate kombucha trial adoption through specialized herbolarios and craft fermenter taprooms. EFSA's strain-specific authorization requirements under Regulation (EC) No 1924/2006 force reformulation investments among Catalan dairy processors. Microencapsulation pilots in the metropolitan zone aim to reduce refrigeration dependency for direct-to-consumer channels.
Basque Country
Regional co-operative sourcing models and dairy heritage anchor fermented milk production clusters around Vitoria-Gasteiz and Bilbao. EU Green Deal Farm to Fork incentives pressure packaging sustainability transitions among Basque producers. Alginate coating research at local food technology institutes targets ambient-stable probiotic viability for pharmacy distribution.
Andalusia
Underpenetrated functional beverage adoption in Seville and Málaga creates whitespace for pharmacist channel development and gym-based recovery positioning. Spanish excise frameworks generate compliance complexity for kombucha secondary fermentation variability. Valencia citrus belt proximity supports probiotic juice experimentation with regional agricultural inputs.
Valencia
Senior-focused digestive comfort formulations gain traction through established pharmacy networks in the metropolitan zone. pH stability challenges in fruit matrices demand specialized shelf-life engineering from Valencia processors. Microbiome testing integration in subscription models concentrates lifetime value capture among metropolitan millennials.
Spain Probiotic Drinks Market Competitive Landscape
Player mix skews toward diversified dairy conglomerates with validated strain libraries, creating tiered access where EFSA dossier possession determines functional claim eligibility. Refrigerated distribution infrastructure and pharmacist channel relationships constitute primary defensive moats. Strategic archetypes include culture-integrated dairy majors, specialized kombucha craft fermenters, and regional co-operative heritage brands. Competitive moves concentrate on home-delivery infrastructure expansion and sustainability certification acquisition under EU Green Deal frameworks.
Within the diversified dairy tier, DANONE Spain and YAKULT ESPAÑA S.A. exemplify scale-driven archetypes with established refrigerated logistics and professional recommendation networks. KAIKU CORPORACIÓN ALIMENTARIA, S.L. occupies a position representing regional co-operative heritage differentiation through Basque-country production provenance. These three S.A. and S.L. structured entities anchor the competitive spectrum between multinational infrastructure and territorial sourcing authenticity.
| Leading Market Players |
|---|
| Grupo Postres Reina S.L. |
| En Komvida Kombucha, S.L. |
| MUN FERMENTS SL |
| DANONE Spain |
| YAKULT ESPAÑA S.A. |
| NESTLÉ LACTALIS NESTLÉ REFRIGERATED DAIRY PRODUCTS IBERIA |
| KAIKU CORPORACIÓN ALIMENTARIA, S.L. |
| ADM |
| Probi AB |
| Others |
Pricing and Supply Chain Analysis
Long-term refrigerated distribution contracts with cold-chain logistics providers lock in shelf access and cost visibility for Spanish probiotic drink manufacturers serving Mercadona and Carrefour España networks. AESAN's live culture enumeration mandates elevate compliance investments that concentrate pricing power among incumbents with validated EFSA strain dossiers.
Pricing Analysis
Cost-plus contracts with dairy culture suppliers indexed to EU dairy commodity benchmarks dominate input procurement for Spanish fermented beverage producers. Three-tier pricing structure across premium pharmacist-channel formulations, standard supermarket SKUs, and economy private-label lines separates margin pools by certification grade and cold-chain investment. Pricing pressure stems from microencapsulation R&D costs required for ambient-stable probiotic viability. Health food store consumers show lowest price sensitivity; convenience store shoppers drive volume at compressed margins.
Supply Chain Analysis
Just-in-time cold-chain logistics dominate inventory strategy for live culture viability, though strategic stockpiling of EFSA-dossiered strains buffers against supplier concentration risk. France, Denmark, and the Netherlands anchor European probiotic culture supply. Raw material dependencies span dairy substrates from Galician and Basque cooperatives, tea extracts for kombucha SCOBY fermentation, and alginate coatings for microencapsulation. Single-source vulnerability clusters with limited EFSA-approved strain suppliers. Distribution runs through dedicated refrigerated aisles in Iberian supermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain probiotic drinks market sits at a post-pandemic wellness cyclical recovery driven by persistent urban health consciousness in Madrid and Barcelona metropolitan zones.
For Market Incumbents: Secure EFSA strain dossier extensions ahead of regulatory tightening under EU Nutrition and Health Claims Regulation revisions. Deepen backward integration into Basque and Galician dairy cooperative supply to defend against kombucha craft fermenter encroachment in premium channels. For New Entrants and Emerging Players: Anchor in Andalusian pharmacist networks and Seville gym-based recovery positioning where functional beverage penetration lags Madrid-Barcelona saturation. Target subscription-based home delivery with microbiome testing integration as the most penetrable go-to-market angle among metropolitan millennials. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional heritage brands with validated strain libraries and established cold-chain infrastructure. Long-term viability over a five-to-ten-year window hinges on EU Green Deal packaging compliance and carbon footprint audit capabilities. Watch EFSA strain-specific claim authorization velocity as the inflection indicator for competitive access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Strain Dossier Investment | Regulatory moat creation under EU Nutrition and Health Claims Regulation locks in functional claim eligibility. |
| Microencapsulation R&D Scale-Up | Ambient-stable probiotic viability reduces cold-chain dependency and expands convenience store penetration. |
| Basque Cooperative Supply Integration | Regional dairy heritage sourcing strengthens premium positioning and EU Green Deal traceability compliance. |
| Pharmacist Channel Partnership Development | Professional recommendation networks in Valencia and Seville build credibility distinct from mass retail competition. |
| Subscription Platform Launch | Direct-to-consumer freshness guarantees and microbiome testing integration concentrate lifetime value capture. |
Research Methodology
A spread of perspectives from brand managers at fermented dairy majors, category buyers at Mercadona and Carrefour España, cold-chain logistics planners, AESAN regulatory affairs specialists, and Basque cooperative supply directors converged on the working assumptions. Secondary validation drew from AESAN food safety bulletins, EFSA strain authorization registers, EU dairy commodity price indices, and Nielsen retail audit data for Iberian refrigerated beverage categories. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segmentation dimensions modeled encompass product matrix type, distribution channel cold-chain tier, customer demographic life-stage, and regional metropolitan penetration level across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and strain authorization timelines. Forecast inputs incorporated live culture viability degradation curves and refrigerated logistics cost inflation assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained AESAN enforcement consistency and EFSA dossier approval velocity; material deviation would warrant model refresh. Revision becomes warranted when kombucha excise reclassification risk or EU Green Deal packaging mandate acceleration crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Liquid Breakfast Products Market