
 Food Inclusions Market | 2026-2036
Food Inclusions Market Size, Share, and Industry Trends Forecast 2026-2036
Food Inclusions Market Analysis
Asia-Pacific capacity expansion for fruit and nut processing is reconfiguring global supply availability for confectionery inclusions. Kerry Group leverages integrated flavor systems to sustain bakery sector partnerships across multiple continents. Cargill anchors its position through broad oilseed and chocolate processing infrastructure. Barry Callebaut competes on bean-to-bar traceability programs that differentiate premium chocolate chip offerings.
Food inclusions denote discrete particulate or semi-solid ingredients engineered for texture, flavor, and visual contrast within finished food matrices, typically specified by moisture content, particle size distribution, and water activity parameters to ensure shelf-life stability. Chocolate chips and dried fruits lead type-based revenue pools due to their versatility across baking and dairy applications, while sprinkles occupy a mature, price-sensitive niche concentrated in seasonal confectionery. Chunks and granules command margin premiums in snack foods where controlled bite experience drives consumer repeat purchase.
FDA food additive regulations and EFSA novel food assessments shape inclusion formulation standards, particularly for engineered textures and imported botanical materials. The EU Green Deal's deforestation-free supply chain requirements and REACH chemical compliance frameworks constrain sourcing flexibility for nut and cocoa-based inclusions. Stakeholders must monitor evolving clean-label certification thresholds and regional allergen labeling mandates to maintain formulation agility and market access across jurisdictions.
Market Dynamics
Clean-label reformulation mandates from EFSA and FDA are compressing formulation timelines while fragmenting supplier qualification requirements across the bakery and confectionery value chain.
Growth Catalysts
- EFSA clean-label guidance:Bakery manufacturers across Germany and France accelerate reformulation to eliminate artificial colors and preservatives, expanding demand for natural fruit and nut inclusions.
- Texture engineering protocols:Snack food producers deploy controlled moisture and particle size specifications to differentiate bite experience in premium positioning.
- Bean-to-bar traceability infrastructure:Chocolate inclusion sourcing now requires documented provenance from cocoa cooperatives through finished chip, reshaping procurement criteria.
Market Restraints
- Cocoa butter price volatility:Chocolate inclusion margins compress when cocoa futures spike, forcing reformulation toward compound coatings with inferior sensory profiles.
- EU Green Deal deforestation compliance:Nut and cocoa sourcing faces documentation burdens that disqualify traditional suppliers lacking geospatial traceability systems.
- Allergen cross-contamination protocols:Dedicated production lines for nut-free inclusions require capital investment that smaller processors cannot absorb.
Strategic Opportunities
- India's organized retail expansion:Modern trade channels in Mumbai and Delhi create first-mover positioning for Western-style baking inclusions targeting affluent consumers.
- Plant-based dairy convergence:Oat and almond milk ice cream formulations require inclusion systems engineered for non-dairy fat matrices and alternative freezing curves.
- US FDA bioengineered food disclosure:Non-GMO and organic certification premiums widen for fruit inclusions as disclosure mandates reshape consumer scanning behavior.
Industry Challenges
- Water activity calibration expertise:Shelf-life modeling for inclusions in high-moisture bakery applications requires scarce food engineering talent conversant in both kinetics and sensory science.
- Legacy ERP integration:Lot-level traceability systems for EU Green Deal compliance conflict with decades-old manufacturing execution software at mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Inclusions Market |
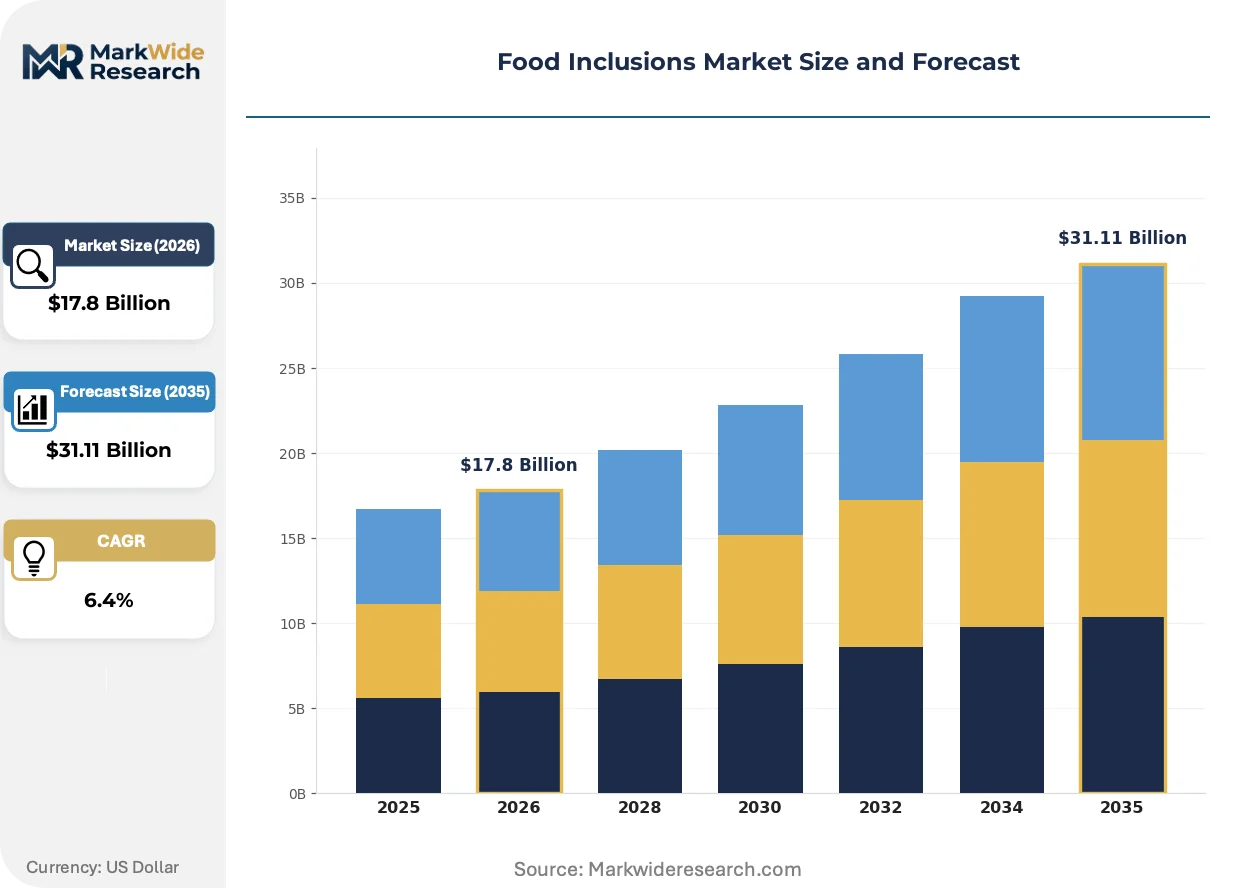
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Chocolate Chips, Nuts, Dried Fruits, Sprinkles Application: Baking, Snack Foods, Confectionery, Dairy Products Form: Chunks, Granules, Powder, Pieces End User: Food Manufacturers, Retailers, Restaurants, Bakeries |
| Companies Covered | Kerry Group, Agrana, Cargill, Puratos Group, Sensient Technologies, Archer Daniels Midland Company, Tate & Lyle, Taura Natural Ingredients, Barry Callebaut, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Inclusions Market Emerging Trajectories
Formulation science is pivoting toward engineered texture systems that deliver controlled sensory release across diverse moisture environments in finished foods.
Encapsulated flavor delivery technology is migrating from confectionery into bakery inclusions, where lipid-based shell systems protect volatile compounds through high-temperature processing. Artisanal bread producers in Italy and Spain adopt these systems to maintain aromatic intensity in crust applications. The shift compresses traditional spray-dried flavor economics while opening margin capture for suppliers with microencapsulation capabilities.
REACH chemical compliance frameworks are forcing reformulation of engineered texture modifiers derived from modified starches and hydrocolloids. ECHA substance evaluation protocols now scrutinize cross-linked phosphate starches common in bake-stable fruit pieces. Inclusion manufacturers serving EU markets accelerate natural hydrocolloid substitution programs, with pectin and citrus fiber systems gaining qualification traction.
Direct procurement from ingredient originators is displacing traditional distribution intermediaries in premium chocolate inclusion sourcing. Bean-to-bar chocolate makers now supply calibrated chip and chunk specifications directly to artisanal bakeries in San Francisco and Brooklyn, bypassing conventional ingredient distributors. The pattern concentrates most visibly in single-origin and certified fair-trade segments where provenance documentation commands price premiums.
Food Inclusions Market Segmentation
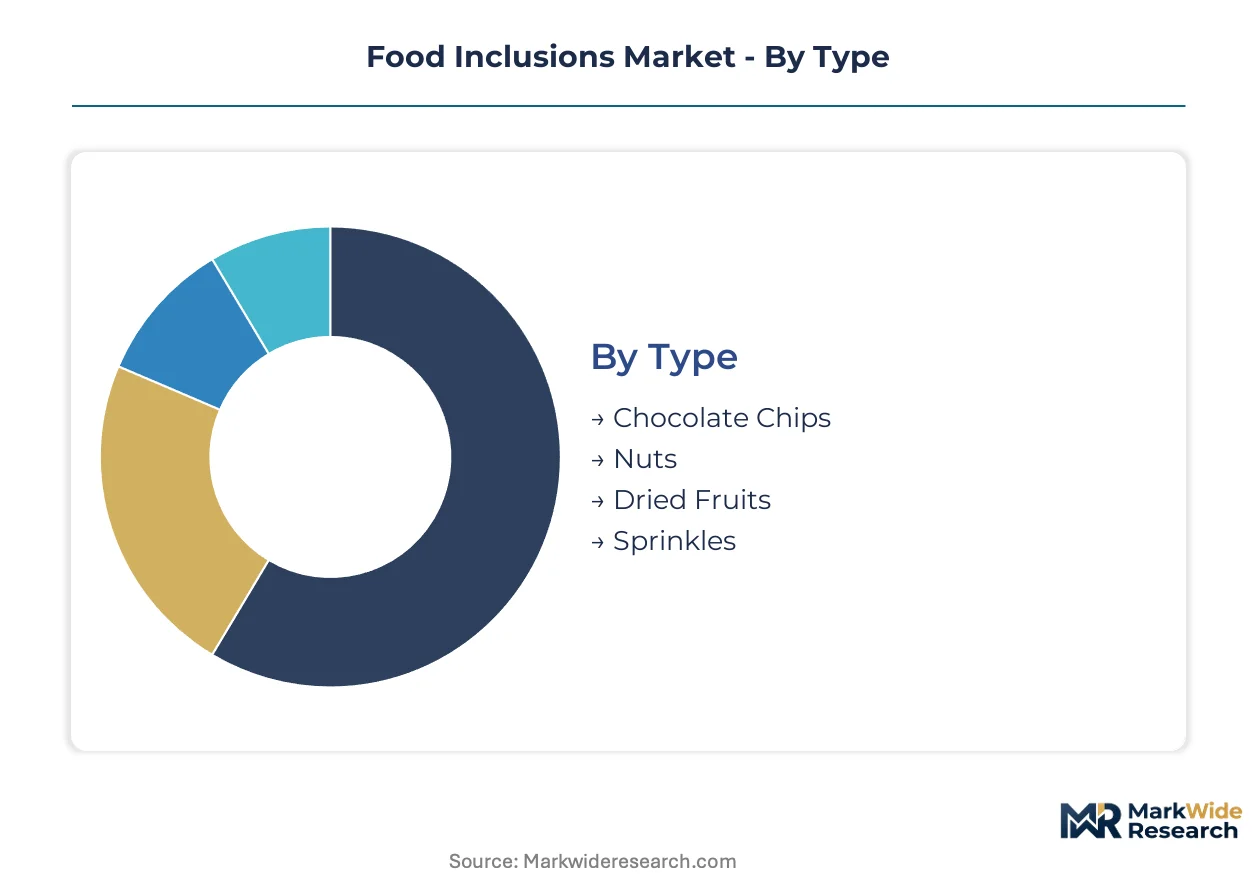
Food inclusions demand fragments across distinct technical specifications and purchasing contexts. Manufacturers must align particle engineering, moisture stability, and procurement scale to capture value in this heterogeneous market.
Type:
Cost tier stratification separates commodity bulk ingredients from precision-engineered particulate systems with documented provenance.
- Chocolate Chips:Calibrated cocoa butter content and tempering profiles define bake-stability specifications. Premium positioning in Germany's artisanal baking sector and US snack channels now requires bean-to-bar documentation under EU Green Deal and FDA bioengineered disclosure frameworks.
- Nuts:Water activity control and oil migration resistance determine shelf-life performance in high-fat matrices. Allergen segregation protocols and deforestation-free sourcing documentation reshape procurement economics across European confectionery applications.
- Dried Fruits:Standard inclusion for cost-optimized bakery formulations with established supply infrastructure.
- Sprinkles:Mature price-sensitive segment concentrated in seasonal confectionery with limited technical differentiation.
Chocolate chips command the established base. The steepest expansion runs through nuts as clean-label protein fortification accelerates.
Application:
End-use environment dictates moisture compatibility requirements and thermal stress tolerances for inclusion matrices.
- Baking:Maillard reaction exposure and oven spring dynamics require engineered moisture retention and structural integrity through thermal cycling. Germany and France lead reformulation intensity as EFSA clean-label guidance eliminates artificial preservatives.
- Snack Foods:Controlled bite mechanics and fat migration resistance differentiate premium positioning. Texture engineering protocols now specify particle size distributions calibrated to jaw force measurements in extruded and puffed applications.
- Confectionery:Fat bloom resistance and snap retention govern chocolate inclusion performance in enrobed products.
- Dairy Products:Freeze-thaw stability and non-dairy fat matrix compatibility gain priority as oat and almond milk ice cream formulations proliferate.
Baking anchors volume concentration. Dairy products are climbing the fastest as plant-based frozen dessert segments expand formulation requirements.
Form:
Physical geometry determines dispersion uniformity, mouthfeel modulation, and processing equipment compatibility.
- Chunks:Discrete mass units delivering pronounced textural contrast and visual differentiation in premium applications.
- Granules:Controlled particle size distributions enable surface adhesion in coating applications and uniform distribution in high-speed mixing operations.
- Powder:Fine fraction for color dispersion and rapid flavor release in dry mix applications.
- Pieces:Intermediate sizing for balanced texture contribution without equipment jamming in automated production lines.
Chunks dominate premium positioning. Granules are gaining share fastest as snack food producers optimize bite experience engineering.
End User:
Customer scale and technical capability determine specification complexity and supplier relationship intensity.
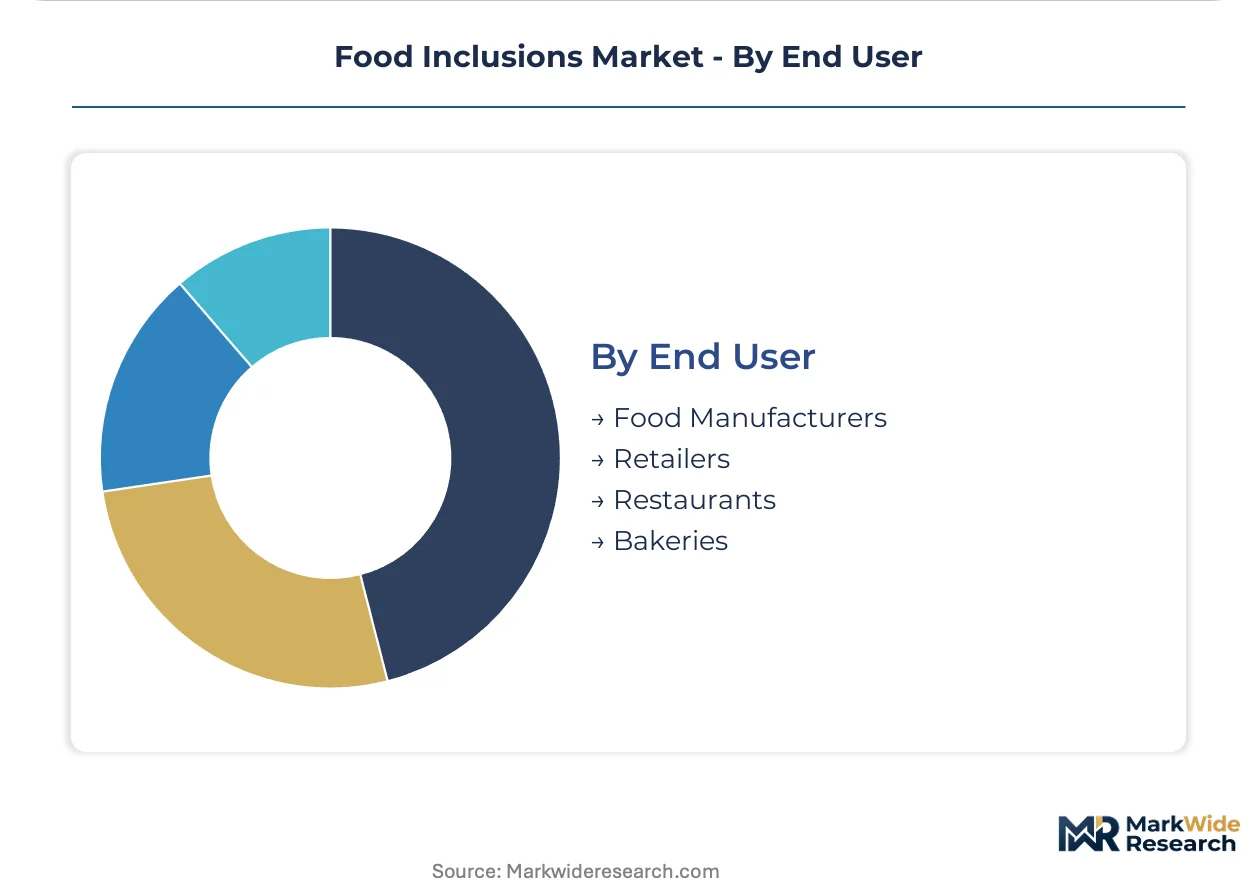
- Food Manufacturers:High-volume procurement with rigorous HACCP integration and lot-level traceability mandates. Mid-tier processors struggle with legacy ERP integration against EU Green Deal compliance requirements.
- Retailers:Private-label development demands flexible minimum order quantities and rapid formulation turnaround for seasonal programs.
- Restaurants:Menu differentiation through signature inclusions with limited technical specification but high visual impact requirements.
- Bakeries:Direct sourcing relationships with bean-to-bar chocolate makers bypassing traditional distribution in San Francisco and Brooklyn artisanal clusters.
Food manufacturers represent the volume anchor. Bakeries are expanding most quickly as direct procurement patterns reshape channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing infrastructure for fruit and nut inclusions clusters in Germany, the United States, India, China, and Brazil. Each jurisdiction applies distinct regulatory frameworks to sourcing documentation and clean-label formulation standards.
United States
Premium snack channels and artisanal bakeries in San Francisco and Brooklyn drive demand for bean-to-bar chocolate inclusions with documented provenance. FDA bioengineered food disclosure mandates reshape consumer scanning behavior and widen non-GMO certification premiums. Direct procurement from originators is displacing traditional distribution intermediaries in these coastal clusters.
Germany
Artisanal baking sectors across Bavaria and North Rhine-Westphalia accelerate reformulation to eliminate artificial colors and preservatives. EFSA clean-label guidance compresses formulation timelines while fragmenting supplier qualification requirements. Barry Callebaut competes on traceability programs that differentiate premium chocolate chip offerings in these industrial zones.
India
Modern trade expansion in Mumbai and Delhi creates first-mover positioning for Western-style baking inclusions targeting affluent consumers. FSSAI labeling mandates and import documentation requirements constrain sourcing flexibility for nut-based formulations. Asia-Pacific capacity expansion for fruit and nut processing is reconfiguring global supply availability from processing hubs in Maharashtra and Gujarat.
China
Confectionery manufacturers in the Yangtze River Delta and Pearl River Delta scale production of engineered texture systems for controlled sensory release. SAMR food additive regulations and GB standards shape inclusion formulation protocols for modified starches and hydrocolloids. Domestic processors invest in microencapsulation capabilities to capture margin from migrating flavor delivery technology.
Brazil
São Paulo-based food manufacturers integrate South American nut sourcing with deforestation-free documentation for EU export compliance. ANVISA allergen labeling mandates and geospatial traceability requirements reshape procurement economics for cocoa and nut inclusions. Local processors struggle with legacy ERP integration against lot-level traceability mandates for European confectionery supply chains.
Food Inclusions Market Vendor Landscape
Integrated ingredient conglomerates and specialized texture engineering houses split the market across distinct capability vectors. The vendor base organizes around three strategic archetypes: broad-spectrum agricultural processors with oilseed and chocolate infrastructure, precision flavor system integrators with bakery sector partnerships, and bean-to-bar traceability specialists with direct artisanal relationships. Consolidation pressure concentrates among mid-tier processors lacking capital for dedicated allergen-segregated production lines. Geographic expansion and backward integration into origin sourcing represent the dominant competitive moves.
Within the integrated processing tier, Cargill anchors its position through broad oilseed and chocolate processing infrastructure spanning multiple continents. Kerry Group exemplifies the flavor system integrator archetype with sustained bakery sector partnerships. Barry Callebaut occupies a specialized position competing on bean-to-bar traceability programs that differentiate premium offerings. These three entities represent distinct strategic postures rather than comparable scale metrics.
| Leading Market Players |
|---|
| Kerry Group |
| Agrana |
| Cargill |
| Puratos Group |
| Sensient Technologies |
| Archer Daniels Midland Company |
| Tate & Lyle |
| Taura Natural Ingredients |
| Barry Callebaut |
| Others |
Supply Flow & Price Mechanics
Cocoa processing concentration in Côte d'Ivoire and Ghana anchors margin capture downstream, where chocolate inclusion specifications command tiered premiums based on bean-to-bar documentation and deforestation-free certification compliance.
Pricing Analysis
EU Green Deal deforestation regulations dictate the pricing tier structure across premium, standard, and economy levels. Certification premiums for traceable cocoa and nut inclusions widen as documentation burdens disqualify uncertified suppliers. Cost compression in commodity-grade dried fruit runs through oversupply in Asia-Pacific processing hubs. Private-label retail buyers exhibit highest price sensitivity, while artisanal bakeries in Germany and the US absorb premiums for provenance-verified chocolate chips.
Supply Chain Analysis
EU Green Deal due diligence requirements and FDA bioengineered disclosure mandates constrain sourcing flexibility for cross-border ingredient flows. Supply concentrates in Germany for engineered texture systems, the United States for premium chocolate processing, and India for expanded fruit and nut capacity. Cocoa butter, specialty nuts, and natural hydrocolloids constitute critical input dependencies. Single-source vulnerability persists in bean-to-bar chocolate traceability infrastructure. Distribution runs through integrated ingredient conglomerates and direct procurement relationships with artisanal bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food inclusions sit in early-cycle expansion as clean-label reformulation mandates across EFSA and FDA jurisdictions accelerate substitution demand for natural fruit, nut, and engineered texture systems.
For Market Incumbents: Harden deforestation-free sourcing documentation through geospatial traceability investments that preempt EU Green Deal compliance disqualification. Deepen backward integration into cocoa cooperatives and nut originators to secure bean-to-bar provenance credentials that command pricing premiums in Germany's artisanal baking sector and US premium snack channels. For New Entrants and Emerging Players: Pursue white-space positioning in India's modern trade expansion across Mumbai and Delhi, where Western-style baking inclusions penetrate affluent consumer segments with limited incumbent saturation. Target plant-based dairy convergence applications, where freeze-thaw stable inclusion systems for oat and almond milk ice cream formulations remain underdeveloped. Lead with microencapsulation capabilities that capture margin from migrating flavor delivery technology. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier processors lacking capital for dedicated allergen-segregated production lines and legacy ERP modernization. The 5-10 year viability window favors acquisition targets with demonstrated EU Green Deal compliance infrastructure and established bakery sector partnerships. Monitor FSSAI and SAMR regulatory alignment progress as the signal for Asia-Pacific capacity reconfiguration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Sourcing | Secures deforestation-free cocoa and nut documentation required under EU Green Deal compliance frameworks. |
| Microencapsulation Capability Investment | Captures margin from flavor delivery technology migration into high-temperature bakery applications. |
| Allergen-Segregated Production Line Addition | Enables qualification for nut-free inclusion demand from clean-label reformulating manufacturers. |
| Direct Procurement Relationship Development | Bypasses traditional distribution intermediaries in San Francisco and Brooklyn artisanal bakery clusters. |
| Natural Hydrocolloid Substitution Program | Addresses REACH compliance scrutiny of modified starches in bake-stable fruit piece formulations. |
Methodological Framework
A spread of perspectives from bakery R&D directors, confectionery procurement leads, ingredient supplier technical sales heads, and food manufacturing quality assurance managers converged on the working assumptions. Primary field engagement combined with secondary validation from FDA food additive guidance documents, EFSA novel food assessment records, EU Green Deal implementation texts, and customs trade data for cocoa and nut flows. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include inclusion type, application environment, physical form geometry, and end-user scale tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and capacity expansion announcements. Forecast inputs incorporated EFSA clean-label guidance implementation pace and Asia-Pacific fruit and nut processing capacity buildout schedules.
Macroeconomic conditions sit as an overlay; deviation in cocoa futures volatility, shipping rate spikes, or currency fluctuation in key processing hubs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and clean-label certification adoption curves. Material shifts in EU Green Deal due diligence deadlines or FDA bioengineered disclosure enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Food Humectants Market