
 Gentian Market | 2026-2036
Gentian Market Size, Share, and Industry Trends Forecast 2026-2036
Gentian Market Foresight
Pharmaceutical manufacturer demand is hardening as gentian root extract gains formulary inclusion for functional digestive therapies. DLC Laboratories leverages its extraction capabilities to serve contract manufacturing relationships across North America. Shaanxi Jintai Biological Engineering anchors supply through cultivated gentian sourcing in China's Shaanxi province. Nature's Answer differentiates via alcohol-free tincture lines targeting label-conscious consumers.
Gentian comprises bitter iridoid glycosides, primarily gentiopicroside and amarogentin, extracted from Gentiana lutea root through maceration or percolation in aqueous ethanol for use in digestive stimulants, beverages, and standardized supplements. Gentian root extract leads product type value pools due to concentration flexibility across pharmaceutical and nutraceutical applications. Beverage flavoring represents the fastest-growing application segment as craft bitters and functional aperitifs expand distribution. Nutraceutical companies dominate end-user demand, though cosmetic manufacturers are emerging as a niche buyer class for gentian's claimed skin-toning properties.
FDA dietary supplement cGMPs and EMA's Traditional Herbal Medicinal Products Directive govern extract standardization, while China's NMPA and SAMR oversee domestic gentian-derived drug approvals. These frameworks elevate testing burdens for new entrants but reinforce incumbent positions among certified suppliers. Stakeholders must monitor evolving novel food consultations in Europe and botanical drug pathway clarifications in the United States to anticipate access shifts.
Market Dynamics
Pharmaceutical formulators are consolidating gentian root extract procurement around certified suppliers as EMA's Traditional Herbal Medicinal Products Directive tightens documentation requirements for digestive therapeutics. This regulatory compression is reshaping supplier qualification timelines and contract manufacturing relationships.
Growth Catalysts
- Traditional Herbal Medicinal Products Directive:EMA's framework accelerates formulary inclusion for standardized gentian extracts in EU pharmacy channels, creating predictable demand from German and French manufacturers.
- Craft beverage bitters:Mixology culture in urban centers drives gentian-based aperitif formulations, expanding volume through specialty distributors and on-premise accounts.
- Digestive wellness positioning:Nutraceutical brands reformulate around gentiopicroside-standardized extracts to capture consumer preference for botanical alternatives to synthetic antacids.
Market Restraints
- Wild gentian scarcity:Gentiana lutea harvest restrictions in Alpine regions constrain raw material availability, forcing dependence on cultivated stock from Shaanxi province with longer lead times.
- Novel food consultation costs:EFSA's pre-market safety assessments for new gentian-derived ingredients impose six-figure regulatory burdens that exclude smaller European entrants.
- Bitter receptor substitution:Synthetic bittering agents and hop-derived alternatives compete on cost and flavor consistency in mass-market beverage applications.
Strategic Opportunities
- Cosmetic toning applications:Korean and French skincare formulators are testing gentian extract for claimed astringent properties, opening a premium-priced adjacent category.
- Alcohol-free tincture formats:Glycerite and liposomal delivery systems address label-conscious consumers in North American natural retail channels.
- SAMR botanical drug pathway:China's streamlined approval process for traditional medicine-derived therapeutics offers faster market access than FDA botanical drug guidance.
Industry Challenges
- Phytochemical standardization expertise:Analytical chemists capable of validating gentiopicroside and amarogentin content across harvest batches command premium salaries, constraining quality control scaling.
- Extraction equipment retrofitting:Transitioning from maceration to supercritical CO2 systems for cleaner-label extracts requires capital deployment that mid-tier processors struggle to finance.
- Multi-jurisdiction dossier maintenance:Simultaneous compliance with FDA cGMPs, EMA THMPD, and NMPA drug master file requirements fragments regulatory affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gentian Market |
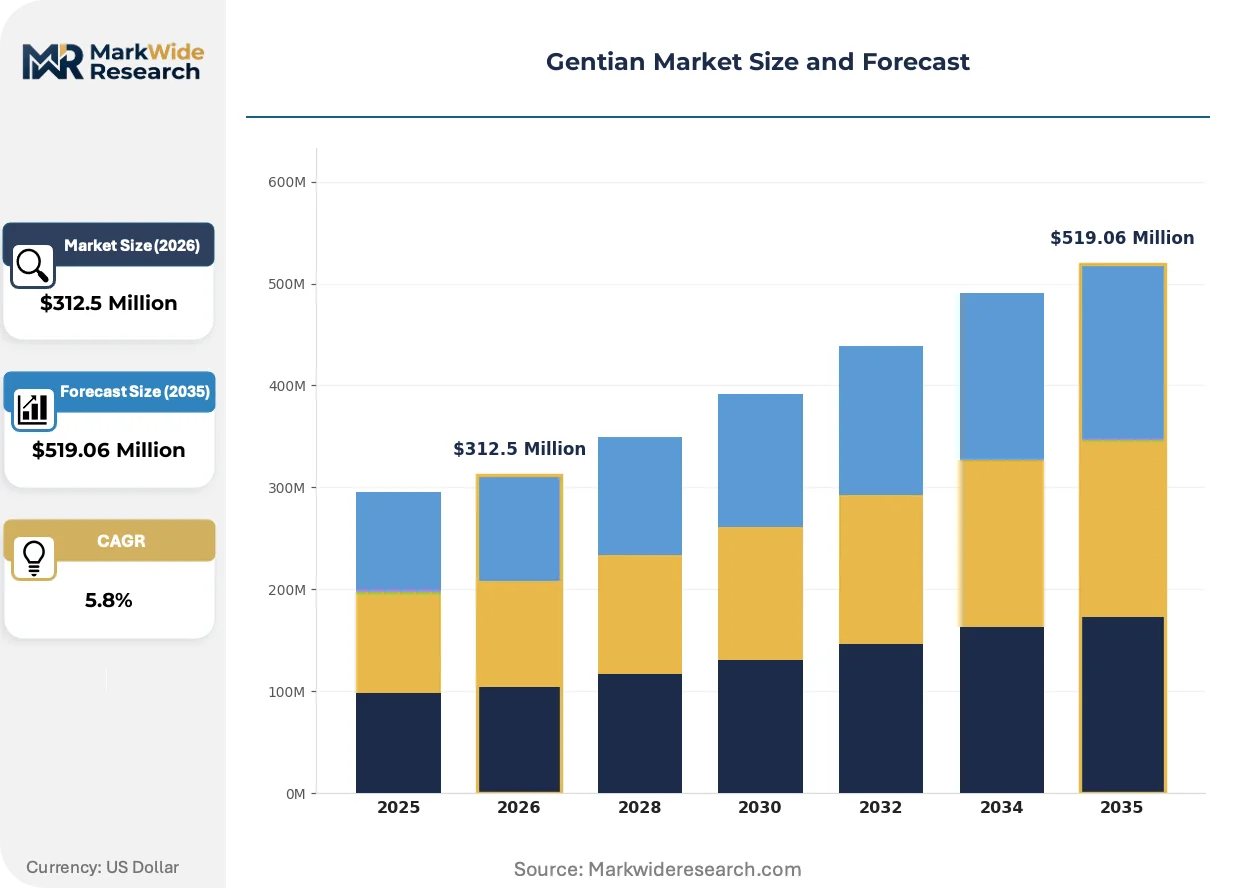
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gentian Root Extract, Gentian Powder, Gentian Tincture, Gentian Capsules, Gentian Tea Application: Digestive Aid, Herbal Supplement, Beverage Flavoring, Traditional Medicine, Cosmetic Ingredient End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Beverage Producers, Cosmetic Manufacturers, Herbalists Packaging Type: Glass Bottles, Plastic Containers, Sachets, Blister Packs, Bulk Bags |
| Companies Covered | DLC Laboratories, Shaanxi Jintai Biological Engineering, APC Pure, Nature’s Answer, Changsha Vigorous-Tech, Swanson Health Products, Sichuan Xiaoye Bencao Biotechnology, Vital Nutrients, Bell’s Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gentian Market Shifts & Advancements
Supercritical fluid extraction and targeted delivery formats are displacing conventional maceration methods, while regulatory harmonization efforts across pharmaceutical and food-grade applications create new formulation pathways for gentian-derived actives.
Supercritical CO2 extraction technology is converging with gentian root processing to eliminate residual ethanol in pharmaceutical-grade extracts. German and Swiss contract manufacturers are retrofitting extraction lines to serve alcohol-free supplement brands. This technology compression is enabling clean-label positioning that commands shelf-space premiums in US natural retail channels.
EMA's consolidated guidance on herbal substance identification now mandates DNA barcoding alongside chromatographic fingerprinting for THMPD registrations. The industrial consequence is a doubling of analytical costs for new gentian extract submissions. Small and mid-sized European suppliers are responding by pooling reference standard libraries through trade associations.
Direct-to-practitioner distribution is bypassing traditional wholesale channels for high-potency gentian extracts. Functional medicine clinicians in California and New York now source standardized bitters through specialized compounding pharmacies. This channel disintermediation concentrates demand among certified suppliers capable of lot-specific certificates of analysis.
Gentian Market Segmentation
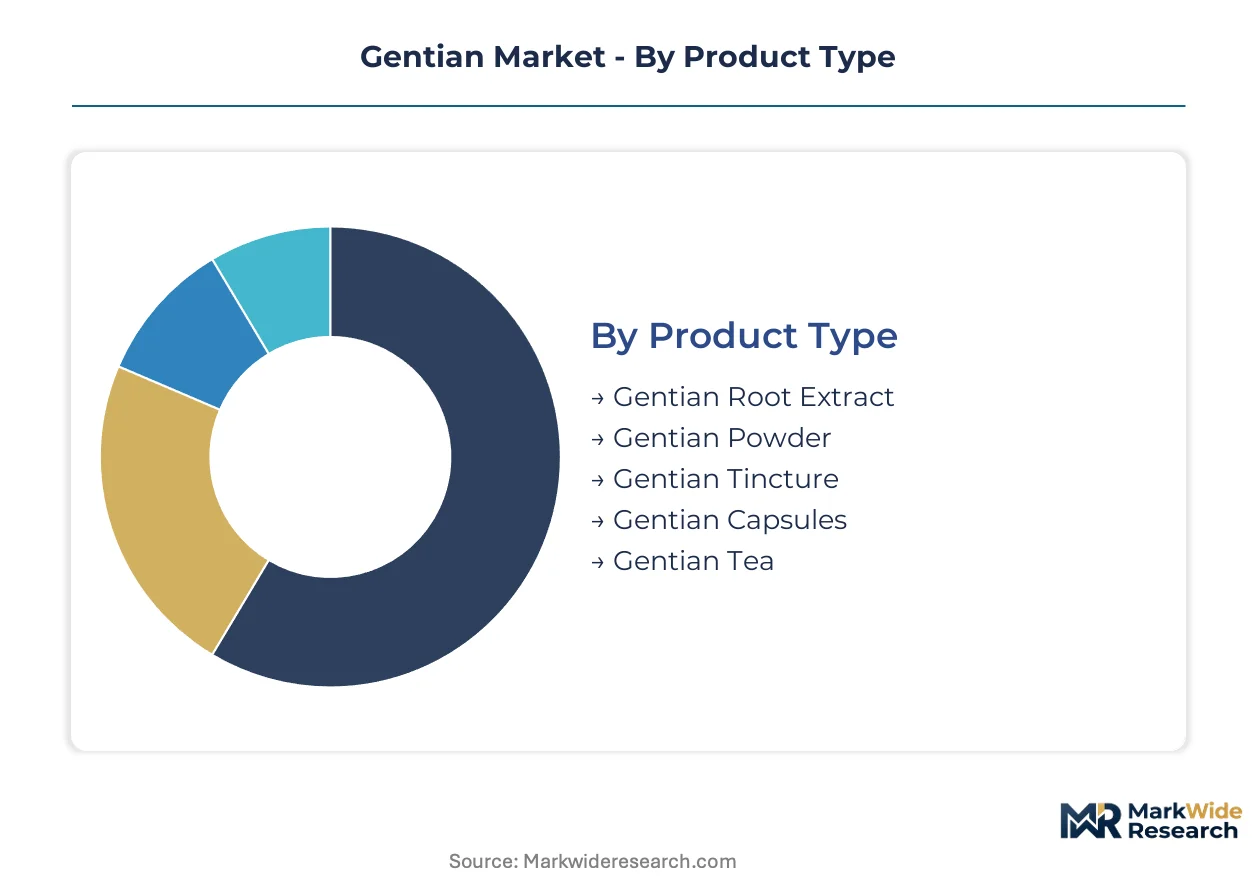
Gentian's bitter iridoid glycosides concentrate differently across extract formats, creating distinct supply chain configurations for pharmaceutical standardization versus beverage flavoring. Segmentation reveals how procurement patterns split between certified THMPD suppliers serving EU pharmacy channels and bulk processors supplying craft bitters manufacturers.
Product Type:
Supply concentration tilts toward extraction facilities capable of gentiopicroside standardization, with Shaanxi province cultivation supporting volume throughput while Alpine wild harvest satisfies premium pharmaceutical specifications.
- Gentian Root Extract:Aqueous ethanol extraction yields concentrated bitter principles for pharmaceutical and nutraceutical applications. German manufacturers absorb the bulk of EU THMPD-certified supply for digestive therapeutics, though lead times extend when Alpine wild stock replaces cultivated feedstock.
- Gentian Tincture:Hydroalcoholic maceration preserves volatile compounds for traditional medicine practitioners. North American natural retail channels drive demand for alcohol-free glycerite variants processed through contract manufacturers in California and New York.
- Gentian Powder:Spray-dried preparations serve encapsulation and tea blending operations.
- Gentian Capsules:Standardized-dose formats target nutraceutical shelf placement.
- Gentian Tea:Whole or cut root for direct-to-consumer herbal preparation.
Gentian root extract absorbs the bulk of installed capacity; gentian tincture is expanding most quickly through practitioner-direct channels.
Application:
Cost tier differentiation separates pharmaceutical-grade extracts commanding premium pricing from commodity beverage bittering agents competing on volume scale.
- Digestive Aid:Standardized extracts deliver measured gentiopicroside doses for functional digestive therapies. EMA's THMPD framework locks in pharmacy channel access for certified suppliers, creating predictable offtake from German and French formulators.
- Beverage Flavoring:Gentian's bitter profile anchors aperitif and craft bitters formulations. Urban mixology culture in New York and London drives specialty distributor volume, though synthetic alternatives erode mass-market penetration.
- Herbal Supplement:Capsule and tablet formats for self-directed wellness consumption.
- Traditional Medicine:Whole root and tincture for practitioner-prescribed protocols.
- Cosmetic Ingredient:Extracts for claimed astringent and skin-toning properties in Korean and French skincare development.
Digestive aid applications command the deepest supply commitments; beverage flavoring climbs the fastest as craft distribution expands.
End User:
Customer type determines certification burden, with pharmaceutical manufacturers requiring THMPD dossiers while beverage producers operate under food-grade novel food consultations.
- Nutraceutical Companies:Reformulation around botanical digestive alternatives drives standardized extract procurement. Label-conscious positioning favors alcohol-free tincture lines and third-party tested certificates of analysis.
- Pharmaceutical Manufacturers:THMPD compliance mandates DNA barcoding and chromatographic fingerprinting for EU market access. Consolidation around certified suppliers compresses qualification timelines for new entrants.
- Beverage Producers:Craft and mass-market bitters formulators sourcing flavor extracts.
- Cosmetic Manufacturers:Premium skincare brands testing gentian for astringent claims.
- Herbalists:Small-batch practitioners sourcing through compounding pharmacies.
Nutraceutical companies anchor current volume; cosmetic manufacturers are gaining share fastest through premium positioning trials.
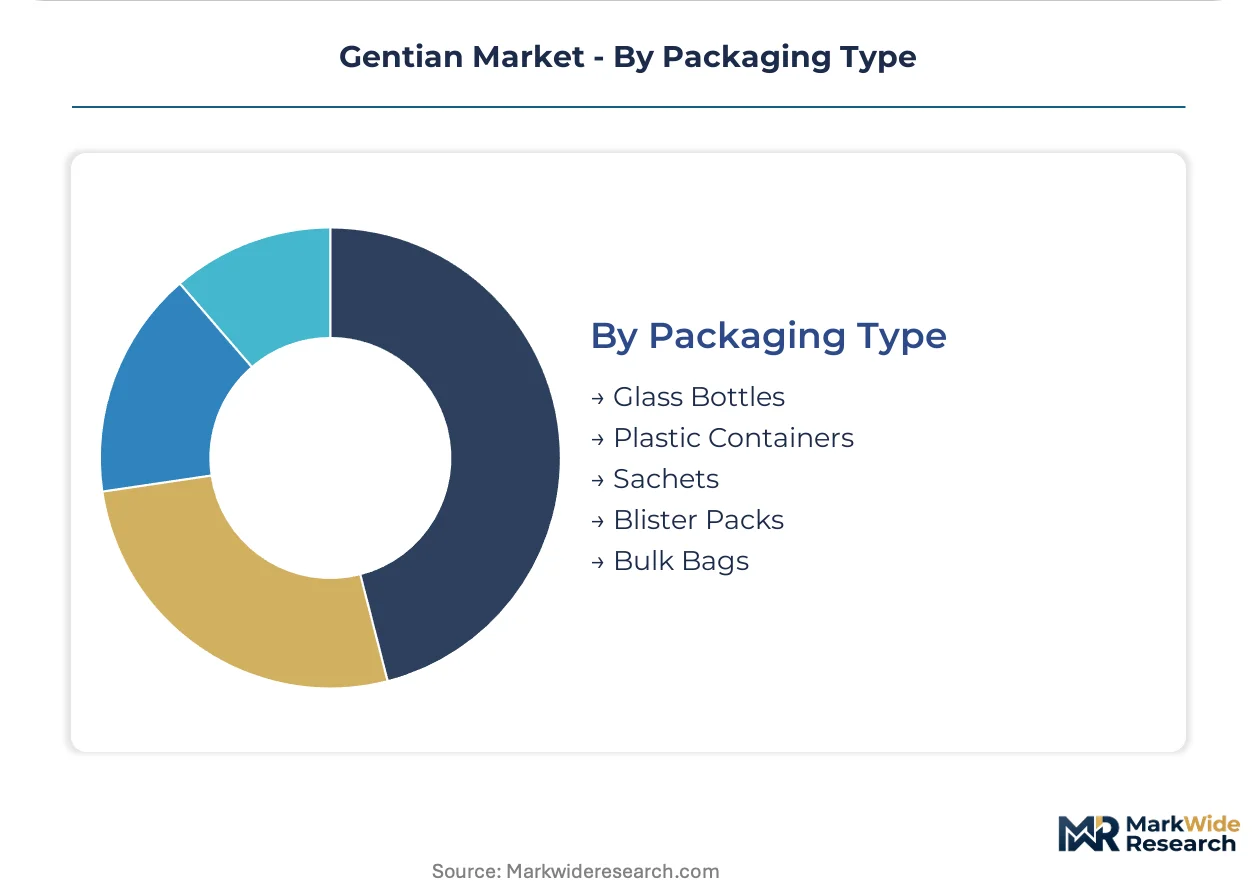
Packaging Type:
Volume scale dictates packaging economics, with bulk bags serving extraction facilities while unit-dose formats address retail shelf requirements.
- Glass Bottles:Amber and cobalt glass protects photosensitive tinctures from degradation. Premium positioning in natural retail channels commands shelf-space allocation through visible quality signaling.
- Bulk Bags:Multi-wall paper and woven polypropylene containers serve extraction and manufacturing inputs. Shaanxi processors ship cultivated root stock in containerized quantities to European and North American contract manufacturers.
- Plastic Containers:HDPE and PET for powder and capsule retail formats.
- Blister Packs:Unit-dose protection for pharmaceutical and travel-size supplement positioning.
- Sachets:Single-serve tea and powder convenience formats.
Bulk bags carry the heaviest throughput tonnage; glass bottles steepen their expansion trajectory through premium channel placement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine protected zones and Shaanxi cultivation corridors concentrate supply-side investment, while EU pharmacy channels and North American natural retail networks pull demand through differentiated regulatory pathways.
Germany
Pharmaceutical manufacturers in Bavaria and Baden-Württemberg absorb THMPD-certified gentian extract for digestive therapeutics. EMA's Traditional Herbal Medicinal Products Directive locks in pharmacy channel access, creating predictable offtake from Heidelberg and Munich formulators. The Black Forest region hosts extraction facilities serving contract manufacturing relationships across the EU.
China
Cultivated gentian from Shaanxi province supplies global pharmaceutical and nutraceutical processors through containerized bulk shipments. NMPA and SAMR oversight of botanical drug approvals streamlines domestic market access compared to FDA pathways. Xi'an-based processors anchor extraction capacity serving European and North American contract manufacturers.
United States
Functional medicine clinicians in California and New York source high-potency gentian extracts through direct-to-practitioner channels. FDA dietary supplement cGMPs elevate testing burdens for new entrants while reinforcing incumbent positions among certified suppliers. Brooklyn and Los Angeles craft bitters producers drive beverage flavoring demand through specialty distributors.
France
Skincare formulators in Provence-Alpes-Côte d'Azur test gentian extract for claimed astringent properties in premium cosmetic development. ANSM registration requirements for traditional herbal products parallel EMA frameworks. Grasse-based cosmetic laboratories source botanical extracts through established Alpine supply chains.
Switzerland
Contract manufacturers in Basel and Zurich retrofit extraction lines for supercritical CO2 processing of alcohol-free pharmaceutical-grade extracts. Swissmedic oversight of herbal medicinal products aligns with EU THMPD standards. Swiss facilities serve clean-label supplement brands commanding shelf-space premiums in North American natural retail channels.
Gentian Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade standardization favoring certified extraction facilities while beverage flavoring tolerates bulk commodity sourcing. The supplier base concentrates around Alpine wild-harvest networks and Shaanxi cultivation operations, creating geographic dualism in raw material access. Three archetypes dominate: THMPD-certified pharmaceutical suppliers, alcohol-free tincture specialists, and cultivated-gentian volume processors. Competitive moves center on extraction technology retrofitting and multi-jurisdiction dossier maintenance capabilities.
Among North American branded specialists, Nature's Answer and Vital Nutrients occupy positions addressing label-conscious consumers through alcohol-free delivery formats. Shaanxi Jintai Biological Engineering anchors the cultivated-supply tier, representing the volume-driven archetype serving contract manufacturing relationships. These three exemplify how geographic origin and formulation positioning stratify competitive space without requiring uniform certification investments.
| Leading Market Players |
|---|
| DLC Laboratories |
| Shaanxi Jintai Biological Engineering |
| APC Pure |
| Nature's Answer |
| Changsha Vigorous-Tech |
| Swanson Health Products |
| Sichuan Xiaoye Bencao Biotechnology |
| Vital Nutrients |
| Bell's Healthcare |
| Others |
Supply & Pricing Matrix
EMA's Traditional Herbal Medicinal Products Directive gates both qualified supply and premium-tier pricing access, compressing supplier qualification timelines while rewarding certified incumbents with pharmacy channel premiums. Wild gentian scarcity in Alpine protected zones and cultivation dependence on Shaanxi province create lead-time-driven price stratification that rewards inventory positioning.
Pricing Analysis
Short lead-time premiums command substantial markups over spot inventory discounts in gentian procurement, with THMPD-certified extracts from Alpine wild harvest drawing the steepest premiums. Three-tier pricing structure across certified pharmaceutical, food-grade standard, and commodity beverage grades reflects documentation burden and DNA barcoding compliance costs. Pricing pressure stems from synthetic bittering agent substitution in mass-market beverage channels, eroding volume-based contract terms. Beverage producers exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premiums for lot-specific certificates of analysis.
Supply Chain Analysis
China's cultivated gentian content rules and EU herbal substance identification mandates are reshaping sourcing toward documented provenance chains. Supply concentrates in China's Shaanxi province, Germany's Black Forest extraction corridor, and Swiss contract manufacturing facilities. Raw material flows draw from cultivated gentian root stock, aqueous ethanol processing inputs, and supercritical CO2 extraction equipment. Single-source vulnerability runs through Alpine wild harvest restrictions under protected zone regulations. Distribution runs through containerized bulk shipments to contract manufacturers, with direct-to-practitioner channels bypassing traditional wholesale for high-potency extracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA's THMPD framework erects a barrier-to-entry moat that entrenches certified suppliers and fragments regulatory affairs resources for aspirants.
For Market Incumbents: Extend certification dossier coverage across FDA cGMPs and NMPA drug master file requirements to preempt multi-jurisdiction qualification bottlenecks. Deepen backward integration into Shaanxi cultivation operations to secure feedstock against Alpine wild harvest volatility. Anchor capacity in supercritical CO2 extraction technology to capture alcohol-free supplement premiums.
For New Entrants and Emerging Players: Launch via direct-to-practitioner distribution channels targeting functional medicine clinicians in California and New York, bypassing incumbent-dominated wholesale networks. Cosmetic toning applications in Korean and French skincare present the most penetrable white-space, with glycerite delivery formats offering label-conscious differentiation. Pursue SAMR botanical drug pathway approvals for faster market access than FDA alternatives.
For Investors and Strategic Acquirers: EMA's consolidated guidance mandating DNA barcoding alongside chromatographic fingerprinting is the leading indicator that analytical chemistry capabilities will concentrate value capture among certified extraction facilities. The five-to-ten year viability window favors acquisition targets with existing THMPD dossiers and Shaanxi cultivation relationships. Monitor novel food consultation outcomes in Europe as inflection signals for beverage segment access.
| Strategic Initiative | Industry Significance |
|---|---|
| THMPD Certification Investment | EMA's DNA barcoding mandate doubles analytical costs and consolidates supplier tiers. |
| Supercritical CO2 Extraction Retrofit | Swiss and German contract manufacturers capture alcohol-free supplement premiums. |
| Shaanxi Cultivation Integration | Backward control over cultivated feedstock mitigates Alpine wild harvest restrictions. |
| Direct-to-Practitioner Channel Buildout | California and New York clinicians source high-potency extracts outside wholesale. |
| Cosmetic Application Development | Korean and French skincare formulators test gentian for premium astringent positioning. |
Research Methodology
Document review covered FDA cGMP guidance documents, EMA THMPD registration databases, and NMPA botanical drug approval filings, complemented by interviews with extraction facility technical directors, pharmaceutical regulatory affairs leads, nutraceutical procurement managers, and cosmetic formulator R&D heads. Secondary validation drew from customs trade records, SEC 10-K filings of listed botanical extract processors, and EFSA novel food consultation registers. Bottom-up volume modeling triangulated against top-down market sizing across extract format segments.
Cross-referencing historical shipment data against expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type concentration tiers, application-grade specifications, end-user certification requirements, and regional regulatory cluster pathways. CAGRs derived from trend extrapolation of gentiopicroside-standardized extract demand and craft beverage bitters volume expansion. Forecast inputs incorporated THMPD registration pipeline visibility and Shaanxi cultivation yield projections.
Regulatory pathway delays, synthetic bittering agent substitution acceleration, and Alpine protected zone harvest restriction extensions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around EMA guidance stability and SAMR botanical drug pathway continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Food Decorations and Inclusions Market