
 Specialty Mint Oils Market | 2026-2036
Specialty Mint Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Mint Oils Market Analytics
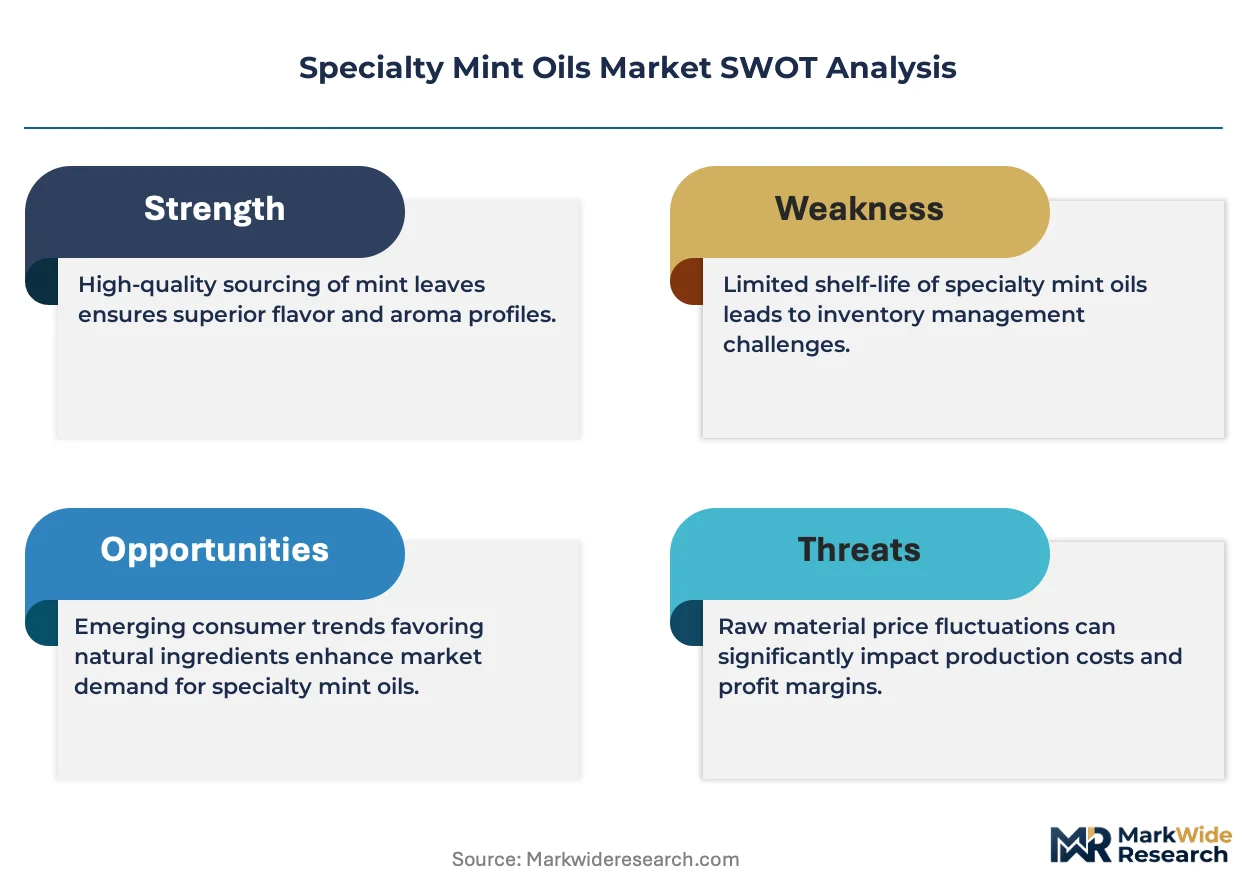
Asset-light contract distillation and third-party toll manufacturing is fragmenting competitive barriers in specialty mint oils, enabling mid-scale processors to challenge integrated incumbents. Symrise AG leverages captive peppermint farms in North America to sustain supply security through backward integration into agricultural operations. Givaudan SA anchors its position through proprietary extraction technologies that yield higher menthofuran purity grades. AOS Products Pvt. Ltd. dominates bulk Indian spearmint oil exports through direct farmer contracting networks in the Indo-Gangetic belt.
Specialty mint oils comprise steam-distilled essential oils derived from Mentha species, typically containing 30-50% menthol by weight in peppermint grades, with specifications varying by terpene profile, optical rotation, and ester content for pharmaceutical versus flavor applications. Peppermint oil leads volume consumption due to entrenched demand from oral care and confectionery formulators, while spearmint oil occupies faster-growing niches in clean-label beverage flavoring where carvone-dominant profiles replace synthetic alternatives. Aromatherapy applications compete with cosmetics for premium-priced Corsican mint oil, as limited Mediterranean harvest volumes restrict supply expansion despite rising spa-channel demand.
FDA food additive regulations under 21 CFR 182.20 govern peppermint and spearmint oil safety for ingestible applications, while REACH compliance in Europe mandates full terpene constituent disclosure for cosmetic-grade imports. India's BIS certification for essential oil purity and the FSSAI's flavoring substance standards shape export-readiness for domestic distillers. Stakeholders must monitor evolving EU Deforestation Regulation traceability requirements that could reclassify mint cultivation areas by compliance tier.
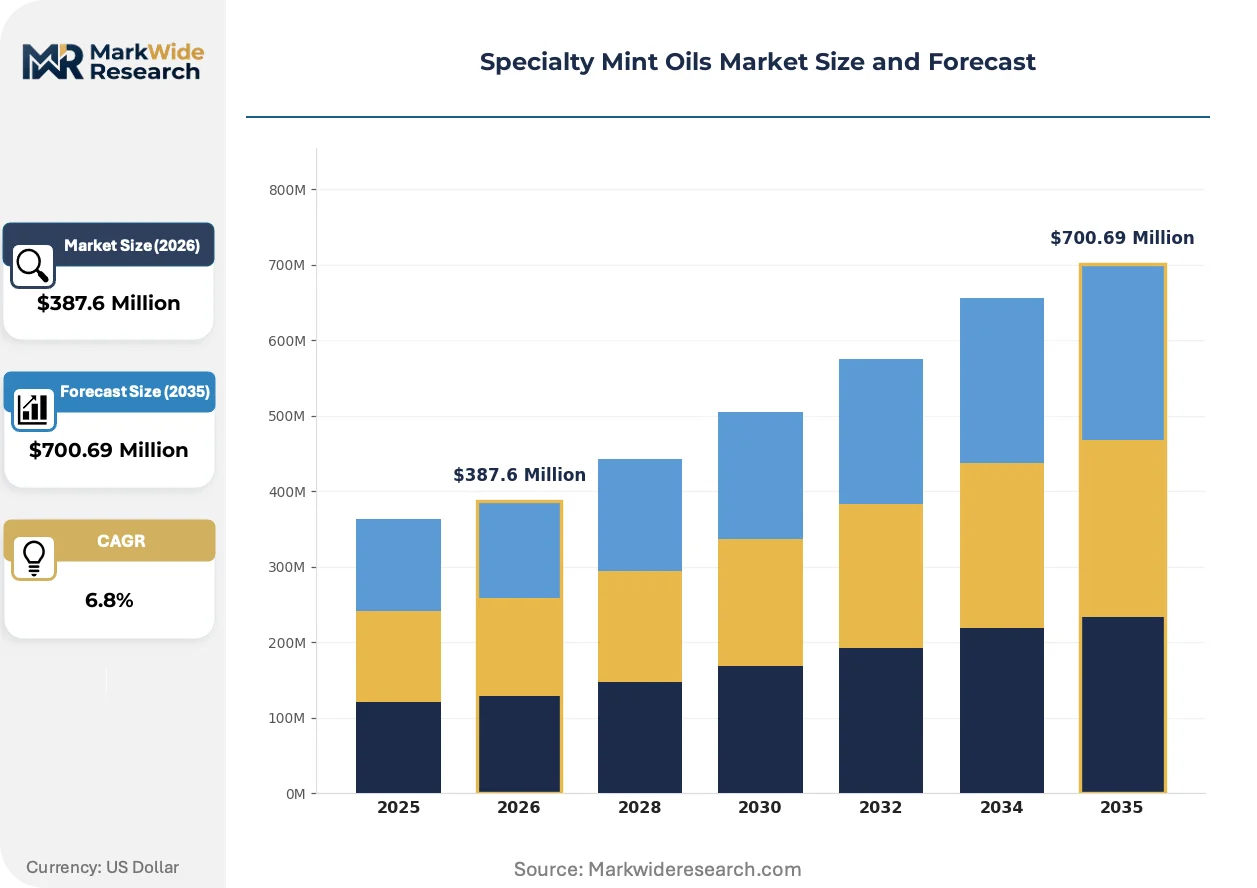
Market Dynamics
Contract distillation networks in Uttar Pradesh and Madhya Pradesh are fragmenting supply-side concentration, enabling mid-scale processors to challenge integrated incumbents through asset-light toll manufacturing arrangements.
Growth Catalysts
- EU Green Deal bio-based mandates:Chemical formulators across Germany and France redirect procurement toward sustainably cultivated menthol derivatives, creating certified supply premiums for compliant Indian distillers.
- Health supplement sector demand:Natural menthol derivative requirements from nutraceutical manufacturers intensify as synthetic alternatives face EFSA scrutiny under novel food regulations.
- Clean-label beverage formulation:Carvone-dominant spearmint oil profiles displace synthetic flavoring agents in premium soft-drink launches across North American and European markets.
Market Restraints
- Monsoon-dependent raw material volatility:Mentha arvensis cultivation in the Indo-Gangetic belt faces yield compression from irregular precipitation patterns, destabilizing contract pricing for distillation clusters.
- Limited Mediterranean harvest volumes:Corsican mint oil supply cannot expand despite spa-channel demand growth, capping aromatherapy segment scalability.
- REACH terpene disclosure burdens:Full constituent reporting requirements for cosmetic-grade imports create documentation friction for small-batch Indian exporters.
Strategic Opportunities
- EU Deforestation Regulation traceability tiers:Early compliance certification positions suppliers for preferential sourcing status as reclassification deadlines approach for mint cultivation areas.
- Spa-channel premium positioning:Limited-harvest Mediterranean mint oils command price multiples in wellness resort procurement, rewarding geographic rarity marketing.
- Backward integration into captive farming:Processor investment in direct farmer contracting networks secures optical rotation and ester specification control for pharmaceutical-grade output.
Industry Challenges
- BIS certification timeline compression:Essential oil purity testing backlogs at Indian standards laboratories delay export-readiness for seasonal harvest batches.
- Menthofuran specification precision:Proprietary extraction technology gaps constrain domestic processors from matching Givaudan-grade purity benchmarks for high-value pharmaceutical contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Mint Oils Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peppermint Oil, Spearmint Oil, Field Mint Oil, Corsican Mint Oil Application: Food & Beverages, Cosmetics, Pharmaceuticals, Aromatherapy Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Food Manufacturers, Personal Care Brands, Health Supplement Companies, Aromatherapy Practitioners |
| Companies Covered | The Lebermuth Company, Symrise AG, doTERRA International LLC, Aromaaz International, AOS Products Pvt. Ltd., Young Living Essential Oils, Givaudan SA, Synthite Industries Ltd., Ultra International B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Mint Oils Market Evolving Landscape
Steam distillation infrastructure is fragmenting across decentralized processing nodes, while regulatory traceability mandates and buyer consolidation reshape competitive requirements for documentation and scale.
Supercritical CO2 extraction is migrating from laboratory-scale pilot units to commercial deployment among mid-tier Indian processors seeking menthofuran purity grades above 50%. Oral care formulators in Germany and Switzerland qualify these outputs for premium therapeutic claims. The technology is migrating from artisanal batch processing toward continuous-flow configurations that compress unit economics for spearmint oil fractions.
REACH compliance mandates under ECHA guidance now require full terpene constituent disclosure for cosmetic-grade mint oil imports into European markets. Small-batch Indian distillers face documentation infrastructure investments or exclusion from premium fragrance house supplier lists. Pharmaceutical-grade peppermint oil specifications face the most stringent scrutiny, driving consolidation among exporters with in-house analytical capabilities.
Buyer concentration among health supplement contract manufacturers is compressing supplier qualification cycles from multi-year relationships to single-season trials. Direct farmer contracting networks in Uttar Pradesh now bypass traditional commission agents, transferring price discovery power to processors with captive cultivation arrangements. This pattern concentrates procurement leverage among three to four integrated Indian exporters with established FSSAI compliance track records.
Specialty Mint Oils Market Segmentation
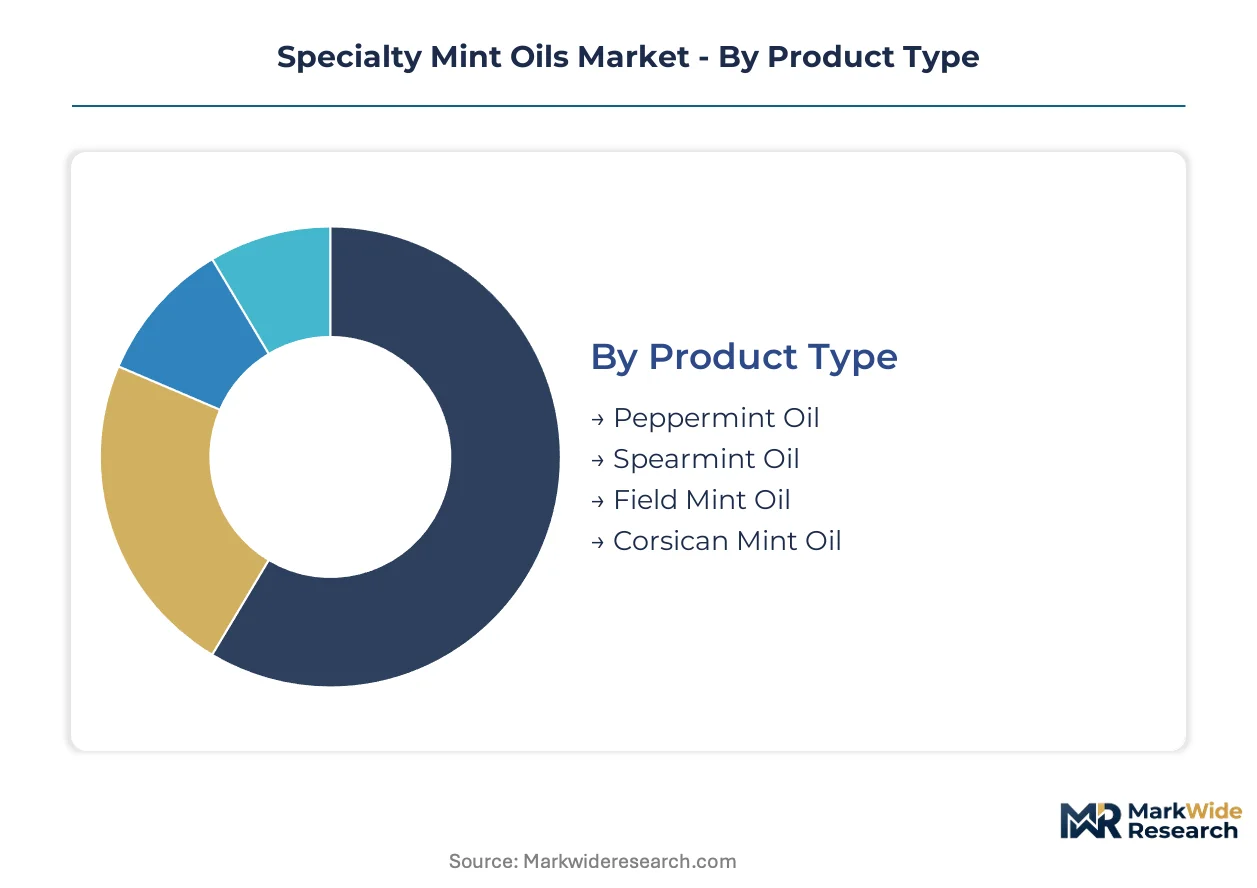
Specialty mint oil specifications diverge sharply across end-use requirements, with pharmaceutical-grade menthol purity demands, flavoring terpene profiles, and aromatherapy botanical authenticity creating distinct commercial tiers. Segmentation reveals how cultivation geography, extraction technology, and regulatory compliance stratify supplier positioning across value chains.
Product Type:
Use-case spectrum spans therapeutic menthol concentration, flavoring carvone profiles, and boutique spa-channel rarity.
- Peppermint Oil:Steam-distilled essential oil containing 30-50% menthol by weight, with optical rotation and ester content specifications varying for pharmaceutical versus flavor applications. Oral care and confectionery formulators in Germany and Switzerland anchor volume demand, though menthofuran purity benchmarks from Givaudan-grade extraction technology constrain supplier qualification for high-value pharmaceutical contracts.
- Spearmint Oil:Carvone-dominant terpene profile displaces synthetic flavoring agents in clean-label beverage formulations across North American markets. Premium soft-drink launches favor this grade for its milder sensory character, with continuous-flow supercritical CO2 extraction compressing unit economics for mid-tier Indian processors seeking entry.
- Field Mint Oil:Mentha arvensis-derived oil supplying bulk natural menthol derivatives to health supplement contract manufacturers facing EFSA scrutiny of synthetic alternatives.
- Corsican Mint Oil:Limited Mediterranean harvest volumes restrict supply expansion despite rising spa-channel demand in wellness resort procurement.
Established volume favors Peppermint Oil; emerging adoption favors Spearmint Oil.
Application:
Regulatory intensity and formulation complexity create divergent margin structures across consumption channels.
- Food & Beverages:FDA 21 CFR 182.20 governs safety for ingestible applications, while clean-label formulation trends in premium soft drinks concentrate demand for carvone-dominant spearmint profiles. REACH terpene disclosure requirements for flavoring substances create documentation friction for small-batch Indian exporters.
- Pharmaceuticals:Menthofuran purity grades above 50% qualify for therapeutic claims in oral care and topical analgesic formulations. Supercritical CO2 extraction migration from laboratory pilot units to commercial deployment among Indian processors is reshaping competitive access to this high-specification tier.
- Cosmetics:Full constituent reporting under ECHA guidance for REACH compliance shapes supplier qualification cycles, consolidating procurement leverage among exporters with in-house analytical capabilities.
- Aromatherapy:Boutique Mediterranean mint oils command price multiples in spa-channel procurement, rewarding geographic rarity marketing despite supply scalability constraints.
Pharmaceutical-grade specifications concentrate procurement leverage; aromatherapy commands the steepest price premiums.
Distribution Channel:
Channel selection reflects batch size, certification requirements, and buyer technical sophistication.
- Direct Sales:Captive contracting networks in Uttar Pradesh and Madhya Pradesh bypass traditional commission agents, transferring price discovery power to processors with backward integration into agricultural operations. Health supplement manufacturers compress supplier qualification cycles through single-season trials rather than multi-year relationships.
- Specialty Stores:Boutique aromatherapy and premium cosmetic-grade oils reach wellness practitioners and formulators requiring optical rotation and ester specification documentation.
- Online Retail:Small-volume cosmetic and aromatherapy grades reach dispersed end-users, though BIS certification backlogs at Indian standards laboratories delay export-readiness for seasonal harvest batches.
- Supermarkets:Mass-market food-grade peppermint and spearmint oils for home culinary use, with FSSAI flavoring substance standards shaping domestic Indian shelf access.
Direct Sales concentrate pharmaceutical and supplement volume; Specialty Stores capture aromatherapy premium extraction.
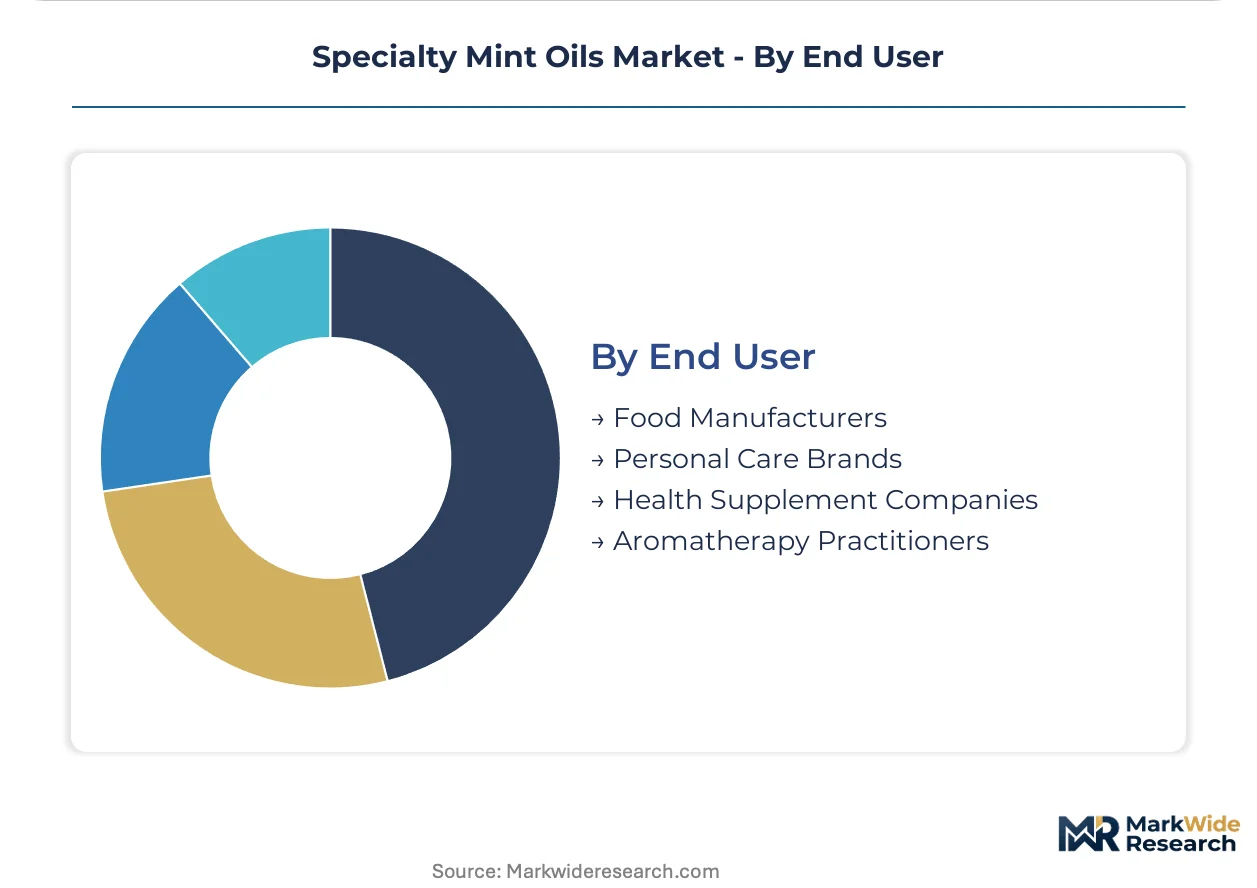
End User:
Buyer consolidation and technical specification intensity stratify supplier relationships across consumption categories.
- Health Supplement Companies:Natural menthol derivative requirements intensify as synthetic alternatives face EFSA novel food regulation scrutiny. Procurement concentrates among three to four integrated Indian exporters with established FSSAI compliance track records.
- Food Manufacturers:Clean-label beverage formulators in North America and Europe drive carvone-dominant spearmint oil displacement of synthetic flavoring agents.
- Personal Care Brands:REACH cosmetic-grade import mandates require full terpene constituent disclosure, favoring suppliers with documentation infrastructure investments.
- Aromatherapy Practitioners:Limited-harvest Mediterranean mint oil demand from wellness resorts rewards geographic rarity positioning despite supply expansion constraints.
Health Supplement Companies are consolidating supplier bases fastest; Aromatherapy Practitioners sustain the highest price tolerance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal bio-based chemical mandates are redirecting procurement strategies across Germany and France toward certified sustainable cultivation. India's contract farming networks in Uttar Pradesh and Madhya Pradesh anchor bulk raw material supply to distillation clusters. Switzerland and the United States concentrate high-specification pharmaceutical and flavor house demand.
Germany
Oral care formulators in Germany drive demand for menthofuran-pure peppermint oil grades. REACH compliance under ECHA guidance mandates full terpene constituent disclosure for cosmetic-grade imports. The Cologne-Düsseldorf industrial corridor hosts flavor house procurement operations qualifying supercritical CO2 extraction outputs for therapeutic claims.
India
Health supplement contract manufacturers intensify natural menthol derivative procurement from Mentha arvensis cultivators. FSSAI flavoring substance standards and BIS certification requirements shape export-readiness for domestic distillers. Contract farming networks in Uttar Pradesh bypass traditional commission agents, transferring price discovery power to processors with captive cultivation arrangements.
Switzerland
Swissmedic-regulated pharmaceutical formulators qualify premium peppermint oil specifications for topical analgesic applications. The Basel pharmaceutical cluster demands optical rotation and ester content precision that constrains supplier qualification. Geneva-based fragrance houses consolidate procurement leverage among exporters with in-house analytical capabilities.
United States
Clean-label beverage formulators across North American markets displace synthetic flavoring agents with carvone-dominant spearmint oil profiles. FDA 21 CFR 182.20 governs safety for ingestible peppermint and spearmint oil applications. The New Jersey flavor and fragrance corridor channels premium soft-drink launch demand toward certified supply tiers.
France
Spa-channel wellness resorts command price multiples for limited-harvest Mediterranean mint oils despite supply scalability constraints. ANSM cosmetic safety standards intersect with EU Deforestation Regulation traceability requirements for botanical authenticity claims. The Provence-Alpes-Côte d'Azur region concentrates aromatherapy procurement networks seeking geographic rarity positioning.
Specialty Mint Oils Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Asset-light contract distillation and third-party toll manufacturing arrangements enable mid-scale processors to challenge integrated incumbents. Three archetypes dominate: backward-integrated agricultural operators, proprietary extraction technology holders, and bulk export specialists with direct farmer contracting networks. Competitive moves concentrate on captive farming investments and supercritical CO2 extraction technology licensing.
Among integrated agricultural operators, Symrise AG exemplifies backward integration into captive peppermint farms. Givaudan SA occupies a position within proprietary extraction technology tiers. AOS Products Pvt. Ltd. anchors the bulk export specialist archetype through direct farmer contracting networks in the Indo-Gangetic belt. These three entities represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| The Lebermuth Company |
| Symrise AG |
| doTERRA International LLC |
| Aromaaz International |
| AOS Products Pvt. Ltd. |
| Young Living Essential Oils |
| Givaudan SA |
| Synthite Industries Ltd. |
| Ultra International B.V. |
| Others |
Value Network & Pricing Analysis
Monsoon-dependent yield volatility in the Indo-Gangetic belt compresses both pricing tier spreads and supply chain configuration, forcing pharmaceutical-grade menthofuran purity premiums to widen against commodity flavor-grade benchmarks while contract farming networks restructure around captive cultivation arrangements.
Pricing Analysis
Certification level creates the primary spread across BIS-verified export tiers, FSSAI-compliant domestic grades, and uncertified spot-market lots. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial flavor levels reflects menthol concentration and optical rotation precision. Pricing pressure stems from REACH terpene disclosure burdens compressing margins for small-batch Indian exporters. Health supplement contract manufacturers exhibit highest price sensitivity due to consolidated procurement leverage, while Swissmedic-regulated pharmaceutical formulators tolerate steep premiums for specification certainty.
Supply Chain Analysis
Extended payment terms from German and Swiss flavor houses now reach 90-120 days, forcing mid-scale Uttar Pradesh processors toward supply-chain finance facilities anchored by confirmed export orders. Raw material sourcing concentrates in India, with secondary dependencies on Egyptian and Chinese menthol derivatives for gap-filling. Mentha arvensis cultivation rests on monsoon precipitation patterns vulnerable to El Niño disruption. Distribution runs through direct sales channels for pharmaceutical and supplement volumes, while specialty stores and online retail fragment aromatherapy and cosmetic grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: REACH compliance and BIS certification create switching costs that lock qualified suppliers into multi-year pharmaceutical and flavor house relationships.
For Market Incumbents: Harden backward integration into captive farming networks across Uttar Pradesh and Madhya Pradesh to secure optical rotation control against contract distillation challengers. Accelerate supercritical CO2 extraction technology licensing to defend menthofuran purity benchmarks from mid-tier processor encroachment. Prioritize EU Deforestation Regulation traceability certification ahead of reclassification deadlines to capture preferential sourcing status. For New Entrants and Emerging Players: Carvone-dominant spearmint oil for North American clean-label beverage launches represents the most penetrable entry point, with continuous-flow extraction unit economics now accessible at mid-scale deployment. Corsican mint oil spa-channel procurement offers boutique positioning despite supply scalability constraints. Target toll manufacturing partnerships with established Indian distillers lacking in-house analytical capabilities as the lowest-capital go-to-market pathway. For Investors and Strategic Acquirers: EU Green Deal bio-based chemical mandates reshape the acquisition landscape toward certified sustainable cultivation assets with established FSSAI compliance track records. Five-to-ten-year viability favors processors combining captive farmer networks with proprietary extraction technology. Monitor BIS certification timeline compression at Indian standards laboratories as an early signal of export-readiness bottlenecks constraining seasonal harvest monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Farming | Direct farmer contracting in Uttar Pradesh secures raw material specification control for pharmaceutical-grade output. |
| Supercritical CO2 Extraction Licensing | Technology transfer enables mid-tier processors to achieve Givaudan-grade menthofuran purity benchmarks. |
| EU Deforestation Regulation Compliance | Early traceability certification positions suppliers for preferential sourcing status ahead of reclassification deadlines. |
| REACH Documentation Infrastructure Investment | In-house analytical capabilities consolidate procurement leverage among cosmetic-grade exporters to European fragrance houses. |
| Spa-Channel Geographic Rarity Marketing | Limited-harvest Mediterranean mint oils command price multiples in wellness resort procurement networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with essential oil distillation plant managers, procurement leads at German and Swiss flavor houses, BIS certification laboratory directors, and health supplement contract manufacturing executives; and secondary validation through customs trade records, FSSAI flavoring substance filings, ECHA REACH registration databases, and SEC 10-K disclosures from integrated agricultural operators. Bottom-up volume triangulation across Mentha arvensis cultivation estimates and top-down value reconciliation against export shipment values anchored the market sizing framework.
Forecast inputs span product type segmentation across peppermint, spearmint, field mint, and Corsican mint oil grades; application tiers spanning pharmaceuticals, food and beverages, cosmetics, and aromatherapy; and distribution channel dynamics across direct sales, specialty stores, online retail, and supermarket penetration. CAGRs across the analysis window derive from regression against historical cultivation area expansion, extraction technology adoption curves, and regulatory compliance cost trajectories. Industry-specific inputs include monsoon precipitation pattern volatility indices and EU bio-based chemical mandate implementation timelines.
Practitioners should monitor BIS certification backlog duration, REACH terpene disclosure requirement amendments, and El Niño Southern Oscillation forecasts for early signals of supply constraint or regulatory friction. Macroeconomic deviation in health supplement demand, regulatory acceleration in deforestation traceability, or breakthrough extraction technology diffusion would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Aromatherapy Oils Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Madecassoside Market