
 Pericarp Waste Market | 2026-2036
Pericarp Waste Market Size, Share, and Industry Trends Forecast 2026-2036
Pericarp Waste Market Analytics
The EU Green Deal is decoupling pericarp waste disposal from linear landfill models across European food processing chains. Novozymes leverages enzyme-based bioconversion platforms to unlock cellulosic sugars from citrus and banana pericarp at commercial scale. DuPont anchors high-performance fiber extraction for compostable packaging substrates, while Veolia Environment competes through integrated waste-to-resource infrastructure spanning collection through anaerobic digestion.
Pericarp waste comprises the outer peel, mesocarp, and endocarp tissues of fruits, typically containing 20-40% cellulose, 10-15% pectin, and 5-10% essential oils by dry weight, with industrial valorization targeting extraction of dietary fiber, bioactive compounds, and lignocellulosic feedstocks. Peels dominate current volume flows due to established pectin recovery infrastructure, while Seeds represent the fastest-expanding margin pool as cold-press oil extraction scales for cosmetics and nutraceutical offtake. Biofuels applications within the Application dimension are attracting capital as anaerobic digestion yields improve for wet pericarp streams with high moisture content.
REACH compliance in Europe governs chemical safety in extracted pectin and essential oil products, while the EPA's renewable fuel standard pathways in the United States validate pericarp-derived biogas for compliance credit generation. Brazil's ANVISA and the country's national agricultural regulator both oversee residue safety in animal feed formulations using dried citrus pulp. Stakeholders must track evolving compostability certification requirements across multiple jurisdictions to secure premium offtake agreements.
Market Dynamics
EU Green Deal circular economy mandates are forcing food processors to abandon linear landfill disposal for agricultural residues, creating structural pull for pericarp valorization infrastructure across European supply chains.
Growth Catalysts
- REACH compliance pathways:ECHA's chemical safety frameworks validate pectin and essential oil extracts for cosmetic and nutraceutical applications, opening premium offtake channels.
- Bioenergy feedstock procurement:Food industry buyers in anaerobic digestion and biogas applications are scaling long-term supply agreements for wet pericarp streams with high moisture content.
- São Paulo citrus cluster concentration:Brazil's processing hub generates sufficient feedstock volumes to justify dedicated collection and pre-treatment infrastructure.
Market Restraints
- Seasonal input volatility:Citrus and banana harvest cycles create supply discontinuities that strain continuous-processing biorefinery economics.
- Moisture handling costs:Wet pericarp streams at 80-85% water content require energy-intensive drying or specialized anaerobic systems before transport.
- Compost substitution threat:Municipal green waste and post-consumer food scraps compete for the same anaerobic digestion capacity at lower collection costs.
Strategic Opportunities
- Seed oil extraction scaling:Cold-press platforms for citrus seeds are penetrating cosmetics and nutraceutical channels with higher margin profiles than peel fiber.
- Compostable packaging substrates:High-performance cellulose extraction from pericarp mesocarp is displacing virgin wood pulp in molded fiber applications.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates are forcing food manufacturers to quantify agricultural residue valorization rates.
Industry Challenges
- Enzyme bioconversion talent scarcity:Commercial-scale cellulosic sugar extraction requires specialized biochemists familiar with Novozymes-type platform optimization.
- Multi-jurisdiction compostability certification:Securing premium offtake requires navigating divergent biodegradability standards across EU member states, US states, and Asian import markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pericarp Waste Market |
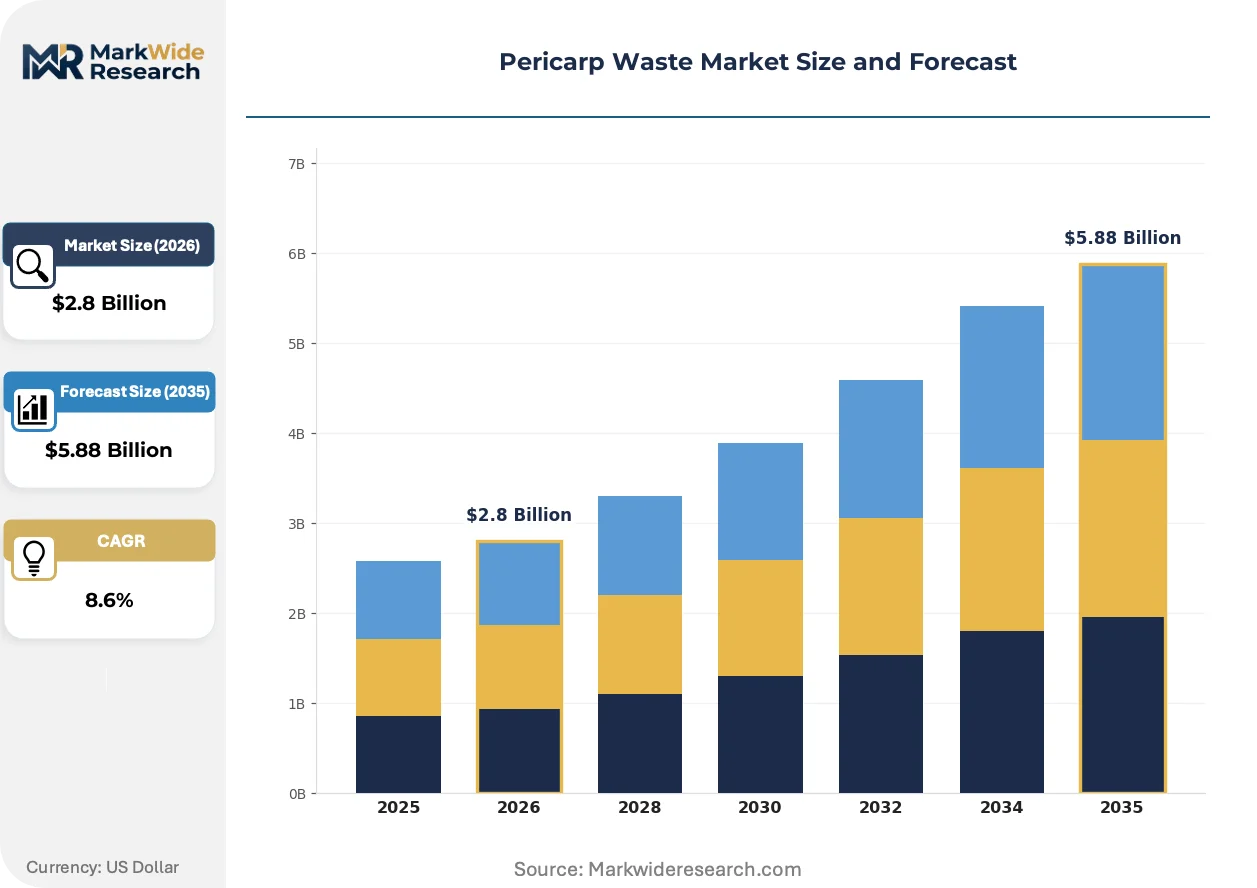
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peels, Pulp, Seeds, Fiber End User: Food Industry, Agriculture, Cosmetics, Bioenergy Application: Animal Feed, Fertilizers, Packaging, Biofuels Distribution Channel: Direct Sales, Online Retail, Wholesale, Exports |
| Companies Covered | DuPont, Novozymes, Veolia Environment, Suez Environment, Waste Management Inc., Clean Harbors Inc., Stericycle Inc., Republic Services Inc., Covanta Holding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pericarp Waste Market Evolving Landscape
Enzymatic bioconversion platforms are compressing the cost curve for cellulosic sugar extraction, while regulatory disclosure mandates and buyer consolidation are reshaping how valorization services are contracted and priced.
Cellulase-pectinase enzyme cocktails are integrating into continuous biorefinery operations to unlock fermentable sugars from citrus and banana pericarp at commercial throughput. Biofuel producers in Brazil and the US are adopting these platforms to meet renewable fuel standard obligations. The technology is integrating upstream collection infrastructure with downstream fermentation capacity, collapsing previously separate processing steps.
REACH authorization requirements for chemical extracts are tightening purity specifications for pectin destined for food and pharmaceutical applications. EFSA safety assessments now govern maximum residue levels for pesticides carried through from agricultural sources. European pectin manufacturers are responding by investing in organic-certified feedstock sourcing and advanced filtration systems.
Long-term offtake contracting is displacing spot-market purchasing for pericarp-derived feedstocks as bioenergy buyers seek supply security. Food manufacturers with captive processing volumes are internalizing collection and pre-treatment rather than selling to third-party aggregators. Brazil's São Paulo state exhibits the most advanced contracting structures, with multi-year agreements linking citrus processors directly to anaerobic digestion facility operators.
Pericarp Waste Market Segmentation
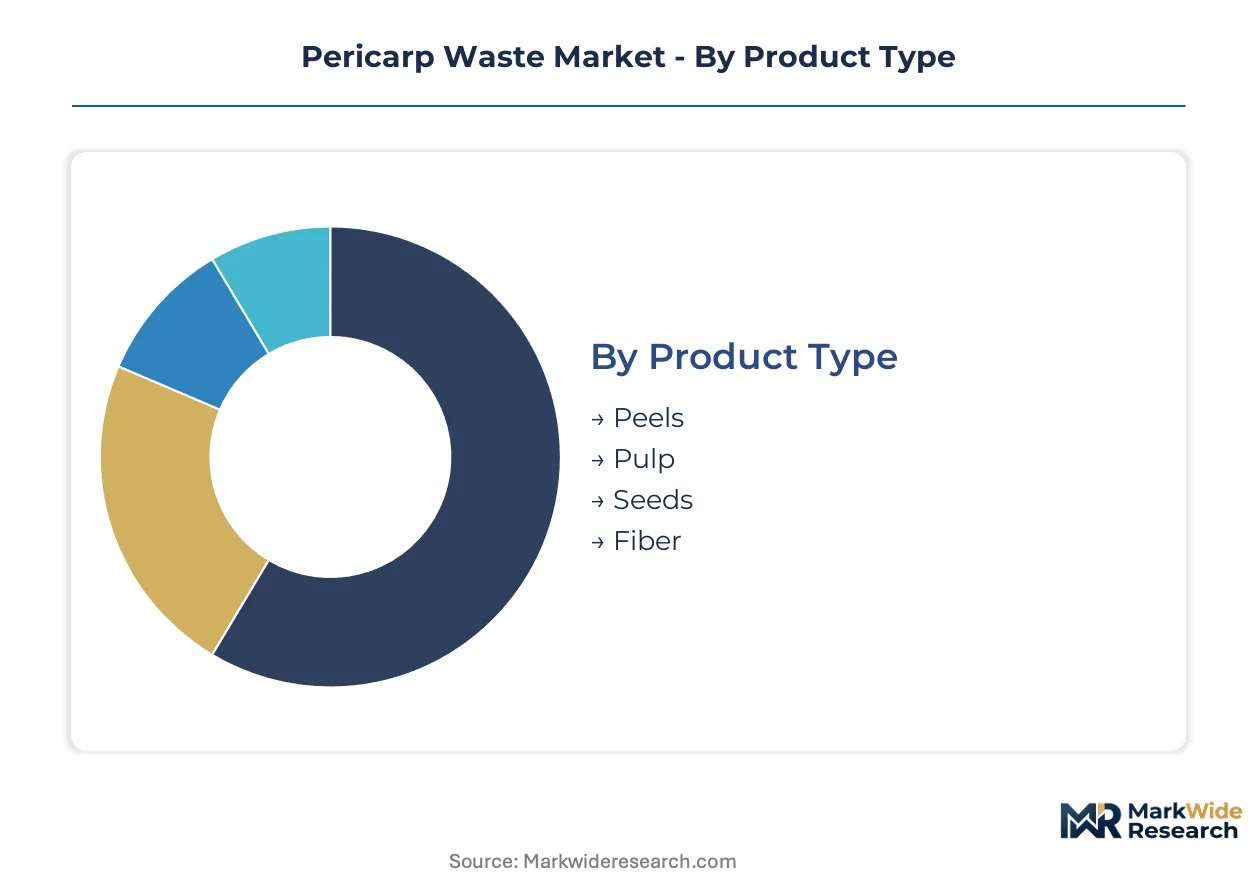
Pericarp waste valorization requires precise feedstock matching to downstream specifications. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that determine competitive positioning.
Product Type:
Peels command volume flows due to established pectin recovery infrastructure, while Seeds capture premium pricing through cold-press oil extraction.
- Peels:Comprising 20-40% cellulose, 10-15% pectin, and 5-10% essential oils by dry weight, peels from citrus and banana processing dominate current tonnage. Demand concentrates in São Paulo state's citrus clusters where dedicated collection infrastructure justifies continuous biorefinery operations. Moisture content at 80-85% requires energy-intensive drying or specialized anaerobic systems before transport.
- Seeds:Cold-press platforms extract oils for cosmetics and nutraceutical channels with higher margin profiles than peel fiber. ANVISA oversight governs residue safety in Brazilian seed oil destined for animal feed formulations. REACH compliance pathways validate purity specifications for pharmaceutical-grade extracts entering European markets.
- Pulp:Wet streams with high fermentable sugar content serve anaerobic digestion facilities seeking renewable fuel standard credits.
- Fiber:Mesocarp-derived cellulose displaces virgin wood pulp in molded fiber packaging applications.
Mature deployment sits with Peels. Newer deployment is concentrated in Seeds.
End User:
Food Industry procurement anchors baseline demand, while Bioenergy buyers are scaling long-term supply agreements for wet feedstock streams.
- Food Industry:Pectin manufacturers extract gelling agents for confectionery and pharmaceutical applications under EFSA safety assessments. EU Green Deal circular economy mandates force processors to abandon linear landfill disposal, creating structural pull for valorization infrastructure.
- Bioenergy:Anaerobic digestion operators in Brazil and the US adopt enzymatic bioconversion platforms to meet renewable fuel standard obligations. EPA pathway validation enables compliance credit generation from pericarp-derived biogas.
- Agriculture:Dried citrus pulp enters animal feed formulations under Brazil's national agricultural regulator oversight.
- Cosmetics:Essential oil extracts face tightening REACH authorization requirements for chemical purity in premium skincare channels.
Procurement consolidation favors Food Industry. Bioenergy contracting exhibits the steepest expansion trajectory.
Application:
Animal Feed represents established offtake, while Biofuels applications attract capital as anaerobic digestion yields improve.
- Animal Feed:Dried citrus pulp provides ruminant nutrition with established safety protocols under ANVISA and Brazil's agricultural regulator. São Paulo processors sell directly to feed compounders under multi-year agreements.
- Biofuels:Wet pericarp streams with high moisture content generate biogas for renewable fuel standard compliance. Enzyme-based bioconversion unlocks cellulosic sugars at commercial throughput.
- Fertilizers:Composted pericarp returns nutrients to agricultural soils with lower processing complexity than extraction routes.
- Packaging:High-performance cellulose extraction from mesocarp tissues targets compostable substrate specifications.
Volume concentration remains with Animal Feed. Technology investment flows toward Packaging.
Distribution Channel:
Direct Sales dominate feedstock procurement, while Wholesale intermediaries face margin compression from buyer consolidation.
- Direct Sales:Citrus processors in São Paulo state link directly to anaerobic digestion facility operators under multi-year offtake contracts. Food manufacturers with captive processing volumes internalize collection and pre-treatment rather than selling to third-party aggregators.
- Wholesale:Aggregators face displacement as bioenergy buyers seek supply security through long-term contracting with source facilities.
- Exports:Pectin and essential oil extracts ship to European cosmetic and nutraceutical manufacturers under REACH compliance documentation.
- Online Retail:Specialty fiber and seed oil products reach small-scale cosmetics formulators through digital channels.
Contract maturity centers on Direct Sales. Channel experimentation is expanding in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's citrus processing belt anchors pericarp waste valorization activity, with concentrated feedstock volumes justifying dedicated collection infrastructure and continuous biorefinery operations.
Brazil
São Paulo citrus clusters generate sufficient peel volumes to support enzyme-based bioconversion platforms. ANVISA oversees residue safety in animal feed formulations using dried citrus pulp. Multi-year offtake contracts link processors directly to anaerobic digestion facility operators across the state's processing belt.
United States
Florida and California citrus processors supply wet pericarp streams to bioenergy buyers seeking renewable fuel standard compliance credits. EPA pathway validation enables biogas-derived credit generation from agricultural residues. The Southeast and Central Valley regions host the densest anaerobic digestion facility networks.
Germany
Bavarian and North Rhine-Westphalian food manufacturers face EU Green Deal mandates to abandon linear landfill disposal for agricultural residues. ECHA REACH frameworks govern chemical safety in pectin extracts destined for pharmaceutical applications. Industrial biogas clusters around Munich and Cologne integrate pericarp feedstocks into existing anaerobic digestion capacity.
India
Maharashtra and Gujarat fruit processing hubs generate banana and mango pericarp volumes for emerging fiber extraction operations. FSSAI safety protocols govern pectin and dietary fiber products entering domestic food channels. Nashik and Surat industrial corridors attract compostable packaging substrate manufacturers seeking alternative cellulose sources.
Netherlands
Randstad food processors deploy integrated waste-to-resource infrastructure under EU circular economy directives. EFSA safety assessments now govern maximum residue levels for pesticide carry-through in pectin destined for confectionery applications. Rotterdam port logistics enable pectin and essential oil exports to European cosmetic manufacturers.
Pericarp Waste Market Competitive Landscape
The competitive structure tilts toward integrated waste management conglomerates with captive collection infrastructure. Tier-one positions cluster around enzyme technology licensors and high-performance fiber extractors, while regional specialists compete on feedstock proximity. Strategic moves concentrate on backward integration into collection networks and multi-year offtake contracting to secure supply continuity against seasonal input volatility.
Among biotechnology-focused licensors, Novozymes occupies a position exemplifying enzyme platform commercialization for cellulosic sugar extraction. DuPont represents the materials science archetype targeting compostable packaging substrates through fiber engineering. Veolia Environment anchors the integrated infrastructure tier, spanning collection logistics through anaerobic digestion operations. These three entities collectively illustrate the tripartite competitive structure: biocatalytic technology, advanced materials, and waste-to-resource infrastructure.
| Leading Market Players |
|---|
| DuPont |
| Novozymes |
| Veolia Environment |
| Suez Environment |
| Waste Management Inc. |
| Clean Harbors Inc. |
| Stericycle Inc. |
| Republic Services Inc. |
| Covanta Holding Corporation |
| Others |
Value Network & Pricing Analysis
EU Green Deal circular economy mandates are forcing food processors to abandon linear landfill disposal, compelling supply chain reconfiguration toward valorization infrastructure and compressing margins on commodity-grade pericarp streams.
Pricing Analysis
Value-based pricing tied to biogas yield per dry ton anchors contract structures for wet pericarp feedstocks. Three-tier pricing structure across pharmaceutical-grade pectin, food-grade fiber, and industrial biogas feedstock separates premium extracts from standard compost inputs. Cost compression in industrial-grade streams is intensifying because municipal green waste competes for anaerobic digestion capacity at lower collection costs. Bioenergy buyers exhibit highest price sensitivity due to renewable fuel standard credit volatility, while cosmetics manufacturers accept premium pricing for cold-pressed seed oils.
Supply Chain Analysis
Direct-to-biorefinery channels handle concentrated demand from São Paulo citrus processors and Florida juice manufacturers. Supply concentrates in Brazil, the United States, and India where citrus and banana processing clusters generate captive feedstock volumes. Raw material flows draw from cellulase-enzyme inputs, specialized anaerobic digester infrastructure, and cold-press extraction equipment. Single-source vulnerability around São Paulo's seasonal harvest creates supply discontinuity risk for continuous-processing biorefineries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pericarp waste market is becoming a vertical-integration race as enzyme technology licensors and waste management conglomerates compete to control upstream collection networks and downstream fermentation capacity.
For Market Incumbents: Anchor defensive positioning through multi-year offtake contracting with São Paulo citrus processors to lock supply continuity against seasonal input volatility. Pursue backward integration into pre-treatment infrastructure to capture margin currently lost to third-party aggregators. Novozymes-type platform optimization capabilities represent the critical lever for maintaining cellulosic sugar extraction yields as competitor enzyme cocktails enter commercial scale. For New Entrants and Emerging Players: Launch via direct sales to anaerobic digestion facility operators in India's Maharashtra and Gujarat fruit processing belts, where compostable packaging substrate demand outstrips local cellulose supply. Target seed oil extraction for cosmetics channels as the most penetrable white-space segment, leveraging ANVISA compliance pathways as a differentiated entry angle against established peel-focused competitors. For Investors and Strategic Acquirers: Re-rating potential sits with integrated waste-to-resource infrastructure operators given EU CSRD disclosure mandates forcing food manufacturers to quantify agricultural residue valorization rates. Acquisition focus should center on mid-scale Brazilian collection networks with captive São Paulo feedstock access. Watch for inflection when REACH authorization requirements tighten pectin purity specifications, triggering consolidation among European extractors lacking organic-certified sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive São Paulo citrus peel supply secures continuous biorefinery operations against seasonal volatility. |
| Enzyme Platform Licensing Agreement | Novozymes-type cellulase-pectinase cocktails unlock commercial cellulosic sugar extraction at anaerobic digestion scale. |
| Long-term Supply Agreement | Multi-year offtake contracts with bioenergy buyers reduce exposure to renewable fuel standard credit price swings. |
| Green Certification Program | Organic-certified feedstock sourcing satisfies tightening EFSA pesticide residue limits for pharmaceutical-grade pectin. |
| Joint Venture | Partnerships between enzyme licensors and waste management operators collapse upstream collection and downstream fermentation steps. |
Research Methodology
Independent corroboration across regulatory filings, trade customs data, and biorefinery operator disclosures underwrites the qualitative findings in this study. Primary interviews with citrus processing plant managers, anaerobic digestion facility operators, enzyme platform R&D directors, and pectin manufacturer procurement leads combined with secondary validation from ANVISA residue safety protocols, EPA renewable fuel standard pathway documentation, and ECHA REACH authorization frameworks. Bottom-up feedstock volume modeling and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical biogas yield improvements and pectin extraction efficiency trends established the forecast framework across the projection horizon. Segmentation dimensions modeled include product type hierarchy, end-user procurement consolidation patterns, application technology readiness, and distribution channel maturity. CAGRs derived from installed anaerobic digestion capacity expansion trajectories and enzyme bioconversion platform adoption curves. Industry-specific inputs incorporated EU Green Deal implementation timelines and Brazil's citrus harvest cycle variability.
Seasonal input volatility, regulatory authorization delays, and compost substitution competition are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Madecassoside Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market