
 Dessert Variegates Market | 2026-2036
Dessert Variegates Market Size, Share, and Industry Trends Forecast 2026-2036
Dessert Variegates Market Outlook
ISO 22000 certification is rotating as the primary gate for supplier qualification across frozen dessert supply chains. Barry Callebaut leverages its integrated cocoa processing network to secure premium chocolate variegate contracts. Kerry Group anchors European manufacturing with specialized fruit and caramel systems for industrial bakeries. Sensient Technologies differentiates through natural color stability R&D in high-acid fruit matrices.
Dessert variegates comprise concentrated flavor inclusions—typically 40-70 Brix fruit preparations, tempered chocolate fragments, or nut praline pastes—engineered for controlled dispersion in frozen or baked matrices. Their primary function is delivering textural contrast and flavor bursts without compromising base product integrity. Liquid variegates lead volume in ice cream applications where pumpability governs line efficiency, while paste and chunk forms command margin premiums in artisanal pastry segments. Fruit variegates compete most intensely across clean-label portfolios, with caramel systems occupying stable positions in indulgence-positioned confectionery.
FDA enforcement of FSMA preventive controls directly shapes variegate supplier validation requirements in U.S. dairy processing. EFSA novel food assessments and EU flavoring regulation (EC) No 1334/2008 constrain botanical and extract-based innovation timelines in European markets. Stakeholders must monitor evolving front-of-pack labeling mandates across multiple jurisdictions, as sugar content disclosure rules will reconfigure formulation priorities for caramel and chocolate variegate portfolios.
Market Dynamics
FSMA preventive controls enforcement is forcing dairy processors to revalidate variegate suppliers against microbial hazard thresholds, compressing qualification timelines and consolidating procurement toward ISO 22000-certified manufacturers.
Growth Catalysts
- Clean-label mandates:EFSA novel food assessments under EU flavoring regulation (EC) No 1334/2008 are accelerating botanical extract approvals for natural color stability in high-acid fruit matrices.
- Artisanal bakery concentration:Germany, Italy, and France are driving demand for paste and chunk variegates in premium pastry applications where textural contrast commands margin premiums.
- Pumpable liquid systems:Continuous freezer line efficiency requirements in industrial ice cream manufacturing are pulling adoption of low-viscosity fruit preparations engineered for controlled dispersion.
Market Restraints
- Cocoa butter price volatility:Chocolate variegate margins compress when cocoa futures spike, forcing reformulation toward compound coatings that sacrifice clean-label positioning.
- Supplier concentration risk:Premium chocolate variegate capacity clusters in integrated cocoa processing networks, creating single-source vulnerability for North American dairy processors.
- Technical limitation:Natural color stability in high-acid fruit matrices remains constrained by anthocyanin degradation during thermal processing, limiting shelf-life claims.
Strategic Opportunities
- Underpenetrated markets:Brazil's ANVISA is streamlining novel food approvals, opening pathways for botanical variegates in frozen dessert applications previously blocked by regulatory friction.
- Regulatory tailwind:EU Green Deal packaging mandates are incentivizing concentrated variegate formats that reduce water weight and transportation emissions across frozen supply chains.
- Technology convergence:Encapsulation technology paired with natural preservative systems is enabling clean-label caramel variegates with extended ambient stability for bakery distribution.
Industry Challenges
- Certification timeline compression:FDA FSMA supplier validation requirements are extending procurement cycles by 4-6 months as dairy processors implement environmental monitoring protocols.
- Capex intensity:Continuous variegate dosing equipment for high-speed freezer lines demands capital outlays that freeze out mid-tier ice cream manufacturers.
- Skill gap:Formulation chemists with expertise in high-Brix fruit preparation rheology and freeze-thaw stability remain scarce across European industrial bakery supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dessert Variegates Market |
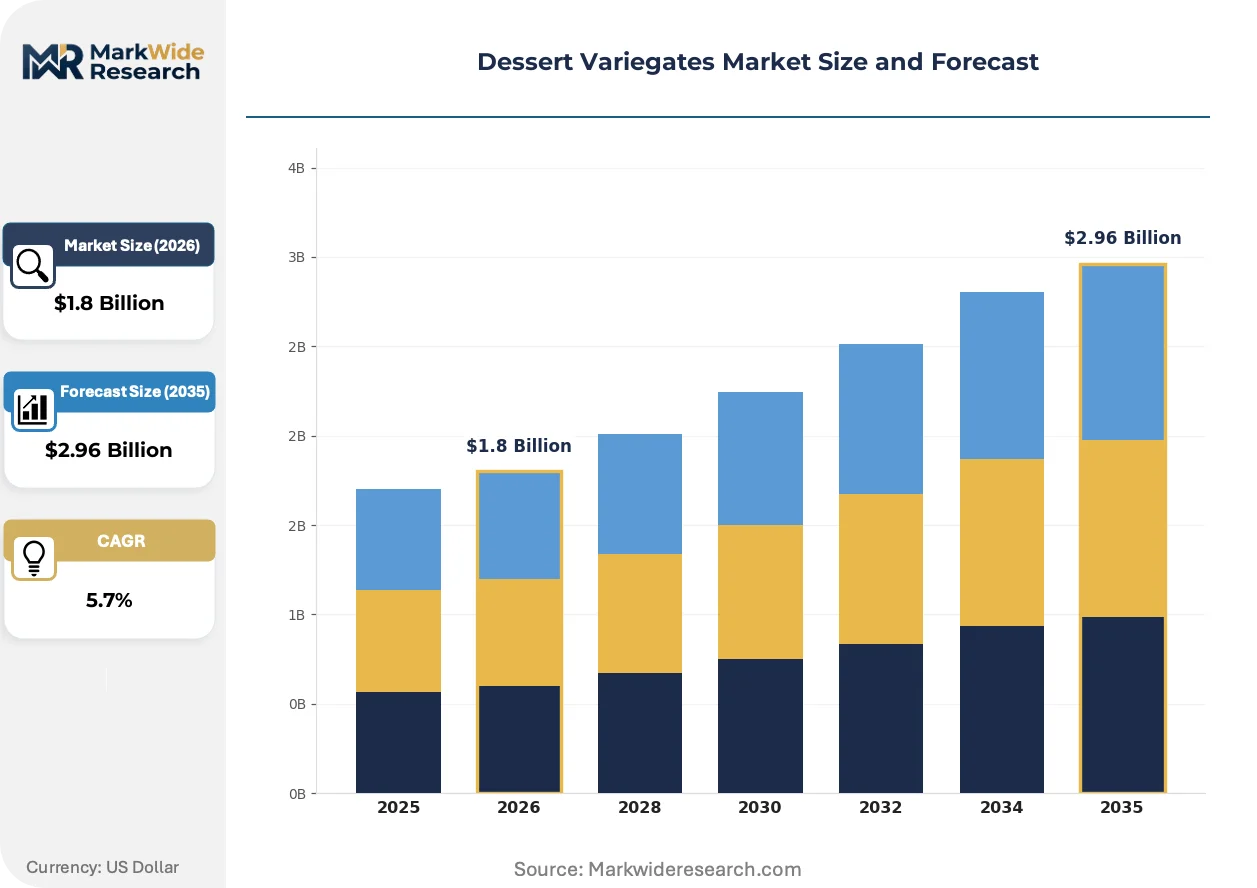
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Fruit, Nut, Caramel Application: Cakes, Ice Cream, Pastries, Confectionery Form: Liquid, Powder, Paste, Chunk Distribution Channel: Retail, Wholesale, Online, Food Service |
| Companies Covered | ADM, Cargill, Barry Callebaut, Firmenich, Givaudan, Kerry Group, Sensient Technologies, International Flavors & Fragrances, DuPont Nutrition & Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dessert Variegates Market Strategic Shifts
Active fermentation of fruit substrates is reshaping variegate development, delivering clean-label acidity modulation without synthetic acidulants while creating novel texture profiles in frozen applications.
Encapsulated natural color systems using modified starch matrices are displacing synthetic dye alternatives in high-acid fruit variegates. Premium ice cream manufacturers in North America are adopting these systems at pilot scale. The technology is compressing reformulation cycles previously consumed by stability testing failures.
EU front-of-pack Nutri-Score labeling requirements are tightening formulation constraints for caramel and chocolate variegates. Manufacturers are reducing added sugars and deploying fiber-based bulking agents to maintain viscosity. Indulgence-positioned confectionery segments in France and Germany are responding fastest with reduced-sugar line extensions.
Direct supplier relationships between variegate manufacturers and artisanal bakeries are bypassing traditional ingredient distributors. Specialty pastry chefs in Milan and Paris are specifying custom Brix levels and particle sizes. This channel shift is most visible in Mediterranean markets where provenance storytelling drives menu differentiation.
Dessert Variegates Market Segmentation
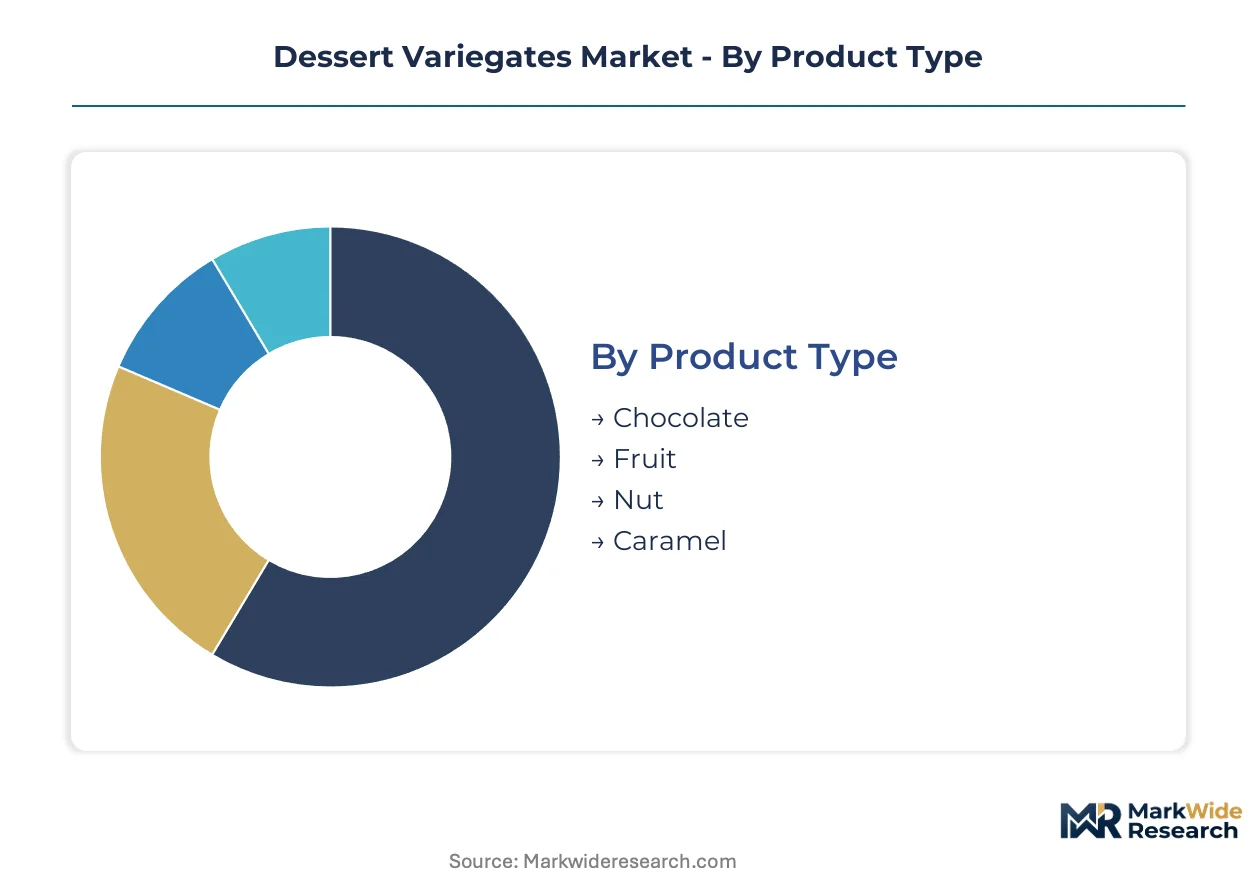
Dessert variegates serve divergent technical requirements across frozen, baked, and confectionery matrices. Segmentation reveals how formulation specifications, rheological properties, and regulatory compliance thresholds reshape procurement priorities for industrial buyers versus artisanal end-users.
Product Type:
EFSA flavoring regulation (EC) No 1334/2008 and FDA FSMA preventive controls create divergent compliance burdens across botanical, cocoa-derived, and dairy-based ingredient categories.
- Chocolate:Tempered cocoa butter-based fragments and compound coatings deliver controlled melt profiles in frozen applications. North American premium ice cream brands are accelerating clean-label adoption despite cocoa futures volatility compressing margins. Integrated cocoa processing networks dominate supplier qualification.
- Fruit:High-Brix preparations (40-70 Brix) engineered for pumpability and freeze-thaw stability anchor clean-label portfolios. Anthocyanin degradation in high-acid matrices remains the primary technical constraint for shelf-life claims in European markets.
- Nut:Praline pastes and roasted particulate systems provide textural contrast in artisanal pastry segments. Allergen labeling mandates under EU Regulation (EU) No 1169/2011 intensify production line segregation requirements.
- Caramel:Indulgence-positioned systems face reformulation pressure from EU front-of-pack Nutri-Score requirements. Fiber-based bulking agents and reduced-sugar formulations are displacing traditional glucose syrup bases in France and Germany.
Chocolate handles the majority of throughput; fruit is the fastest mover on share.
Application:
Continuous freezer line efficiency requirements in industrial manufacturing favor pumpable formats, while artisanal segments prioritize viscosity control and visual differentiation.
- Cakes:Paste and chunk variegates dominate layer cake and muffin applications where thermal stability during baking governs specification. Germany, Italy, and France drive demand concentration for premium pastry inclusions.
- Ice Cream:Liquid variegates lead volume where dosing equipment compatibility and controlled dispersion determine line efficiency. Low-viscosity fruit preparations are displacing higher-viscosity alternatives in high-speed manufacturing.
- Pastries:Custom Brix levels and particle sizes specified directly by artisanal bakers in Milan and Paris are bypassing traditional distribution channels. Provenance storytelling accelerates direct supplier relationships.
- Confectionery:Extended ambient stability requirements favor encapsulated natural color systems and modified starch matrices. Reduced-sugar line extensions are responding fastest to tightening labeling mandates.
Ice cream handles the majority of throughput; pastries are expanding most quickly on share.
Form:
Capital intensity for dosing equipment and packaging format regulations under EU Green Deal mandates reshape format adoption curves.
- Liquid:Pumpable systems engineered for controlled dispersion dominate industrial ice cream manufacturing. Concentrated formats reducing water weight are gaining preference under emissions reduction incentives.
- Powder:Spray-dried and agglomerated formats serve ambient distribution requirements in bakery applications. Reconstitution properties and dust control govern specification in automated production environments.
- Paste:High-viscosity preparations command margin premiums in artisanal segments where textural contrast and visual ribboning differentiate finished products. Custom rheology specifications proliferate in Mediterranean markets.
- Chunk:Tempered chocolate fragments and nut praline pieces deliver discrete flavor bursts. Size distribution and hardness specifications vary sharply between frozen and baked application requirements.
Liquid handles the majority of throughput; paste is climbing the fastest on share.
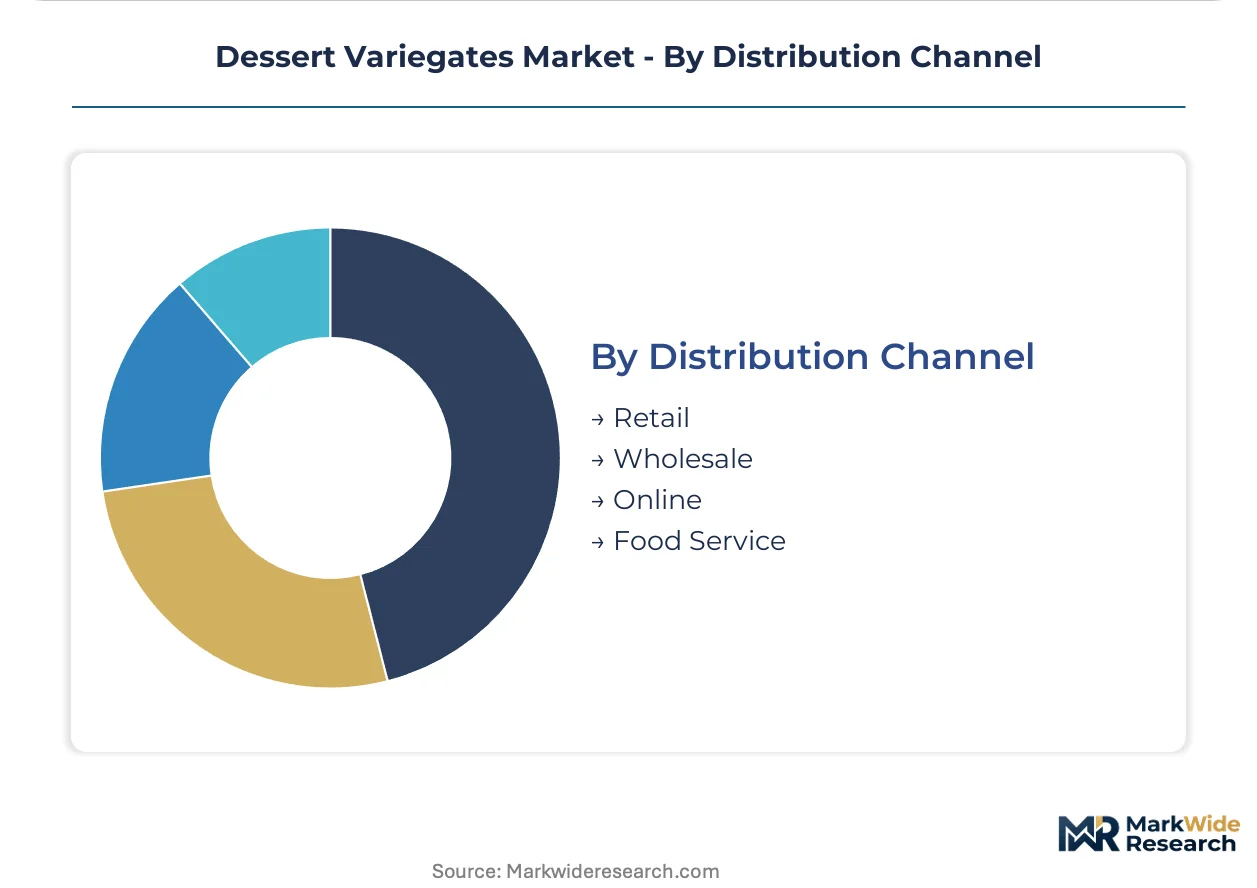
Distribution Channel:
Direct procurement relationships and e-commerce platform compliance requirements are fragmenting traditional ingredient distributor dominance.
- Retail:Packaged consumer formats face front-of-pack labeling mandates across multiple jurisdictions. Sugar content disclosure rules are reconfiguring formulation priorities for caramel and chocolate portfolios.
- Wholesale:Traditional ingredient distributors retain volume in mid-tier manufacturing segments. ISO 22000 certification has become the primary gate for supplier qualification in frozen dessert supply chains.
- Online:E-commerce platforms for specialty ingredients are accelerating access for artisanal bakers to custom specification variegates. Cold chain logistics requirements constrain frozen format availability.
- Food Service:Direct supplier relationships with pastry chefs and dessert menu developers emphasize provenance documentation and small-batch flexibility. This channel is expanding most quickly in urban clusters across France and Italy.
Wholesale handles the majority of throughput; food service is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of FSMA preventive controls is consolidating supplier relationships toward ISO 22000-certified manufacturers in the United States. Germany's artisanal bakery sector commands premium pricing for paste variegates with provenance documentation. Brazil's ANVISA regulatory streamlining is opening novel food pathways previously blocked by approval friction.
United States
Premium ice cream manufacturers in the Midwest and Northeast are accelerating clean-label variegate adoption despite cocoa futures volatility. FDA FSMA preventive controls enforcement is extending supplier qualification timelines by 4-6 months as environmental monitoring protocols take effect. Wisconsin and Vermont dairy processing clusters are consolidating procurement toward integrated cocoa processing networks to secure chocolate variegate supply.
Germany
Artisanal bakeries in Bavaria and Baden-Württemberg are driving demand for high-viscosity paste variegates with custom Brix specifications. EU front-of-pack Nutri-Score labeling is forcing reformulation of caramel systems toward fiber-based bulking agents and reduced-sugar bases. Stuttgart and Munich industrial zones anchor concentrated fruit preparation manufacturing for European bakery supply chains.
Brazil
ANVISA streamlining of novel food approvals is enabling botanical extract variegates in frozen dessert applications previously stalled by regulatory backlog. São Paulo and Minas Gerais dairy processors are piloting encapsulated natural color systems from modified starch matrices. The Southeast region's expanding cold chain infrastructure is supporting concentrated variegate formats that reduce water weight and transportation emissions.
France
Direct supplier relationships between variegate manufacturers and Parisian pastry chefs are bypassing traditional ingredient distributors. EU Green Deal packaging mandates are incentivizing concentrated formats across frozen supply chains. The Île-de-France and Provence-Alpes-Côte d'Azur regions lead indulgence-positioned confectionery reformulation responding fastest to tightening sugar disclosure rules.
Italy
Milan and Turin specialty pastry chefs are specifying custom particle sizes and Brix levels for provenance-driven menu differentiation. EFSA novel food assessments under EU flavoring regulation (EC) No 1334/2008 are accelerating botanical extract approvals for natural color stability. The Lombardy and Piedmont clusters anchor Mediterranean demand for textural contrast in premium pastry applications.
Dessert Variegates Market Competitive Environment
Player mix skews toward integrated ingredient conglomerates with captive cocoa processing and specialized flavor houses with natural color R&D capabilities. Three archetypes dominate: diversified agricultural processors controlling upstream commodity supply, European flavor specialists with high-acid fruit matrix expertise, and integrated chocolate manufacturers with tempering technology. Competitive moves concentrate on strategic partnerships with artisanal bakery clusters and capacity expansion in pumpable liquid format production.
Among integrated cocoa processors, Barry Callebaut exemplifies the network-controlled supply archetype through its vertically organized bean-to-variegate infrastructure. Kerry Group represents the European flavor systems specialist, anchoring industrial bakery supply with fruit and caramel preparation capabilities. Sensient Technologies occupies the natural color stability tier, with high-acid matrix R&D positioning for clean-label ice cream reformulation cycles. These three entities illustrate how supplier qualification gates are consolidating procurement toward ISO 22000-certified manufacturers with multi-jurisdiction regulatory navigation capabilities.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| Barry Callebaut |
| Firmenich |
| Givaudan |
| Kerry Group |
| Sensient Technologies |
| International Flavors & Fragrances |
| DuPont Nutrition & Biosciences |
| Others |
Value Chain & Pricing Dynamics
Fiber-based bulking agents replacing glucose syrup bases in EU caramel formulations simultaneously relocate manufacturing gravity toward German and French specialty ingredient clusters and compress margin structures for traditional glucose-dependent suppliers. This substitution dynamic concentrates pricing power with integrated formulators possessing multi-jurisdiction clean-label certification while fragmenting procurement options for mid-tier buyers locked into legacy supply agreements.
Pricing Analysis
Certification level (ISO 22000/FDA-grade) creates the primary spread between premium and standard tiers in frozen dessert supply chains. Three-tier pricing structure across premium, standard, and economy levels governs procurement, with volume scale and customization depth as secondary differentiation factors. Cost compression in standard-tier fruit preparations is intensifying because anthocyanin stability failures trigger reformulation cycles. Industrial dairy processors exhibit highest price sensitivity; artisanal pastry chefs in Milan and Paris demonstrate lowest sensitivity due to provenance-driven specification requirements.
Supply Chain Analysis
Strategic stockpiling of cocoa butter and high-Brix fruit concentrates dominates inventory strategy over just-in-time approaches given commodity volatility and seasonal harvest windows. Supply concentrates in Belgium (integrated cocoa processing), Germany (fruit preparation manufacturing), and the United States (dairy processor demand clusters). Raw material dependencies encompass cocoa butter, glucose syrup, and natural color extracts. Single-source vulnerability in premium chocolate variegate capacity creates structural risk. Distribution runs through ISO 22000-certified wholesale channels with direct food service relationships expanding fastest in Mediterranean urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dessert Variegates Market is cycling through a recovery phase driven by clean-label reformulation mandates tightening across EU and North American regulatory jurisdictions.
For Market Incumbents: Secure backward integration into cocoa processing networks to eliminate single-source vulnerability for premium chocolate variegate supply. Anchor capacity expansion in Bavaria and Baden-Württemberg to capture artisanal bakery demand concentration. FSMA preventive controls enforcement represents the primary regulatory threat compressing qualification timelines; ISO 22000 certification investment is the critical lever for procurement consolidation defense. For New Entrants and Emerging Players: ANVISA's streamlined novel food approval fast-track opens immediate white-space in Brazil's Southeast dairy processing corridor. Target underpenetrated botanical extract variegates in frozen dessert applications previously blocked by regulatory friction. Direct e-commerce platform positioning for specialty pastry chefs in Milan and Paris provides the most penetrable go-to-market angle bypassing traditional distributor dominance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European flavor houses possessing high-acid fruit matrix R&D capabilities but limited geographic scale. Long-term viability across the projection horizon hinges on clean-label transition completion and regulatory navigation capacity. Watch for ANVISA approval velocity crossing thresholds as the inflection indicator for emerging market expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | FDA FSMA enforcement locks in procurement consolidation toward certified manufacturers exclusively. |
| Encapsulated Natural Color R&D Partnership | Sensient Technologies' modified starch matrix development accelerates clean-label ice cream reformulation cycles. |
| Direct Food Service Channel Expansion | Parisian and Milanese pastry chef relationships bypass traditional distributor margins entirely. |
| Concentrated Format Production Scale-Up | EU Green Deal packaging mandates incentivize water-weight reduction across frozen supply chains. |
| Botanical Extract Novel Food Approval | ANVISA streamlining unlocks previously blocked frozen dessert applications in Southeast Brazil. |
Study Parameters
Desk research of EFSA novel food assessment databases, FDA FSMA guidance documents, and EU flavoring regulation filings preceded structured interviews with frozen dessert procurement directors, artisanal bakery supply chain managers, cocoa processing network executives, and natural color R&D formulators. Secondary validation drew from customs trade data, SEC 10-K filings of integrated ingredient conglomerates, and ANVISA regulatory bulletins. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Variance decomposition across product type, application, form, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs encompassed cocoa futures volatility patterns and clean-label certification adoption curves across dairy processing clusters.
Decision-makers should treat outputs as directional under assumptions of sustained FSMA enforcement intensity and EU Green Deal packaging mandate adherence; material deviation would warrant model refresh. Cocoa butter price spikes exceeding historical bands, ANVISA approval backlogs re-emerging, or anthocyanin stability breakthroughs altering shelf-life claims represent primary revision triggers. Revision becomes warranted when regulatory compliance cost trajectories cross thresholds forcing mid-tier manufacturer exit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Cupuacu Butter Market