
 Food Acidulants Market | 2026-2036
Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Food Acidulants Market Analysis
The EU Green Deal is repositioning acidulant procurement toward bio-based and fermentation-derived inputs. Jungbunzlauer Suisse AG leverages its Swiss fermentation expertise to supply citric acid across European clean-label portfolios. Corbion N.V. anchors its position through lactic acid specialization for dairy and plant-based applications. Cargill Inc. competes on global grain-based feedstock access, sustaining cost advantages in malic acid production.
Food acidulants are organic compounds—principally citric, malic, lactic, and tartaric acids—added to adjust pH, enhance flavor profiles, and extend shelf stability in processed foods, typically dosed between 0.1% and 1.5% by weight. Citric acid dominates volume due to its versatility across beverages and confectionery, while lactic acid captures expanding share in dairy alternatives and fermented products. Malic acid differentiates within sports and energy drinks where tartness modulation matters, and tartaric acid occupies niche but stable positions in bakery and wine-derived applications.
The European Food Safety Authority (EFSA) evaluates acidulant safety thresholds under EU food additive regulations, while the FDA governs GRAS status and labeling in the United States; China's National Health Commission sets GB standards for acidulant purity and maximum usage levels. These frameworks shape formulation choices, import compliance costs, and clean-label marketing claims across jurisdictions. Stakeholders must monitor evolving fermentation carbon intensity standards and regional maximum-level adjustments to secure formulation continuity and market access.
Market Dynamics
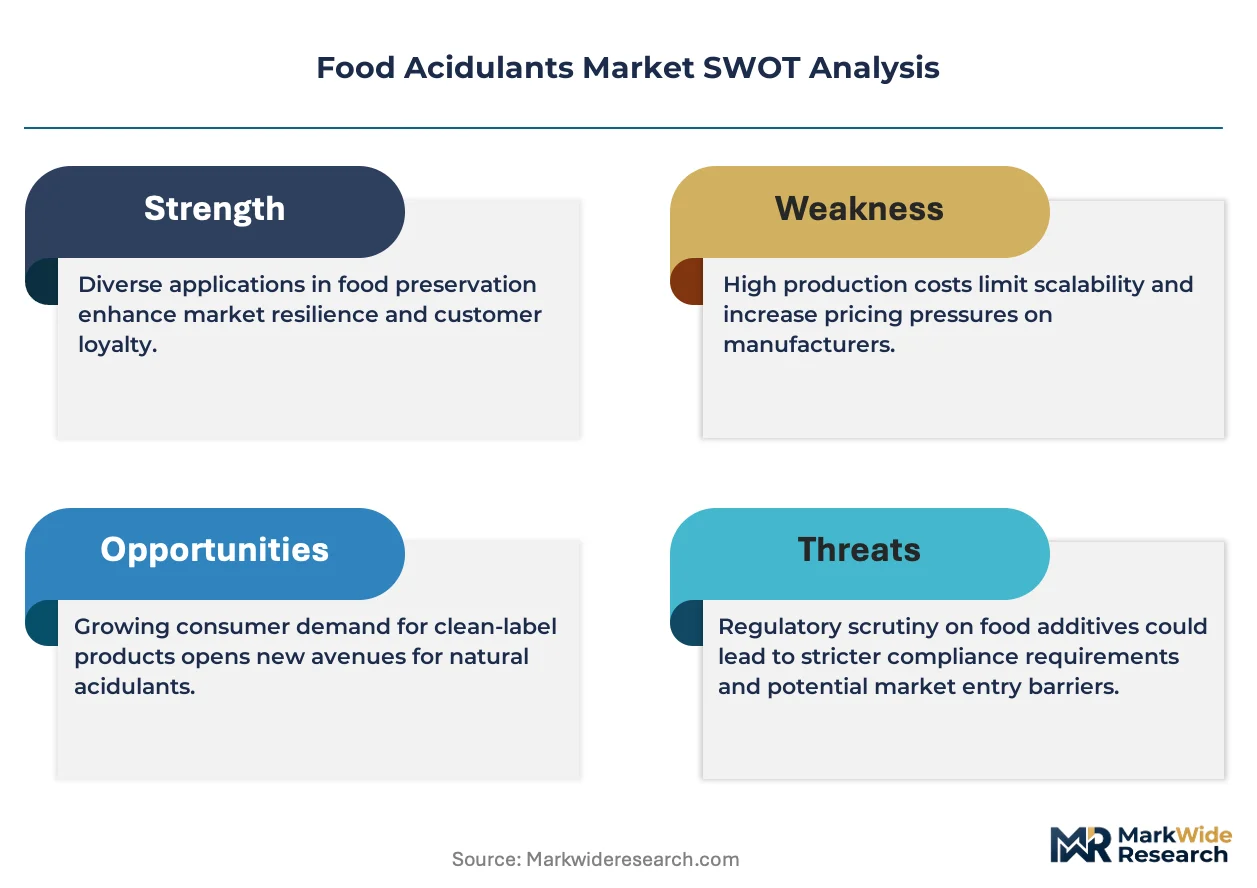
The EU Green Deal's clean-label mandates are restructuring acidulant procurement, forcing manufacturers to abandon petrochemical-derived citric acid in favor of fermentation-based alternatives with verifiable carbon footprints.
Growth Catalysts
- EU Green Deal compliance mandates:European beverage manufacturers face binding requirements to reduce synthetic additive content, accelerating demand for bio-based acidulants in functional drinks and plant-based dairy alternatives.
- China's processed food output expansion:Domestic production of ready-to-drink beverages and convenience foods in Chinese manufacturing clusters is absorbing record volumes of citric and lactic acid for pH stabilization and shelf-life extension.
- Fermentation technology maturation:Industrial biotechnology advances have collapsed production costs for microbial-derived acids, enabling price parity with synthetic equivalents across European and North American supply chains.
Market Restraints
- Feedstock price volatility:Corn and molasses costs swing with agricultural commodity cycles, compressing margins for grain-dependent malic and citric acid producers in the US Corn Belt.
- Supply concentration in Chinese fermentation capacity:Over 60% of global citric acid fermentation infrastructure sits in Shandong and Jiangsu provinces, creating single-source vulnerability for international formulators.
- Clean-label substitution pressure:Vinegar and citrus juice concentrates are capturing shelf-stable sauce and dressing applications where acidulants once dominated, eroding volume in mature categories.
Strategic Opportunities
- India's underpenetrated beverage sector:FSSAI's evolving standards for acidified drinks and carbonated beverages are opening formulation partnerships with domestic dairy and juice processors in Maharashtra and Karnataka.
- Precision fermentation convergence:Integration of synthetic biology with continuous processing is enabling custom acidulant blends tailored to specific pH curves in sports nutrition and medical foods.
- Direct-to-manufacturer e-procurement channels:Digital platforms are disintermediating traditional chemical distributors, allowing mid-sized acidulant producers to capture margin previously lost to regional wholesalers.
Industry Challenges
- Clean-label certification timelines:EFSA's extended safety re-evaluation cycles for existing acidulant approvals are delaying product launches and freezing reformulation pipelines for 18-24 months.
- Legacy equipment incompatibility:Existing tank farms and dosing systems at European dairy processors require capital-intensive retrofitting to handle hygroscopic lactic acid variants without contamination risk.
- Carbon accounting integration:Suppliers must build in-house lifecycle assessment capabilities to satisfy Scope 3 disclosure requirements under CSRD, straining mid-tier technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Acidulants Market |
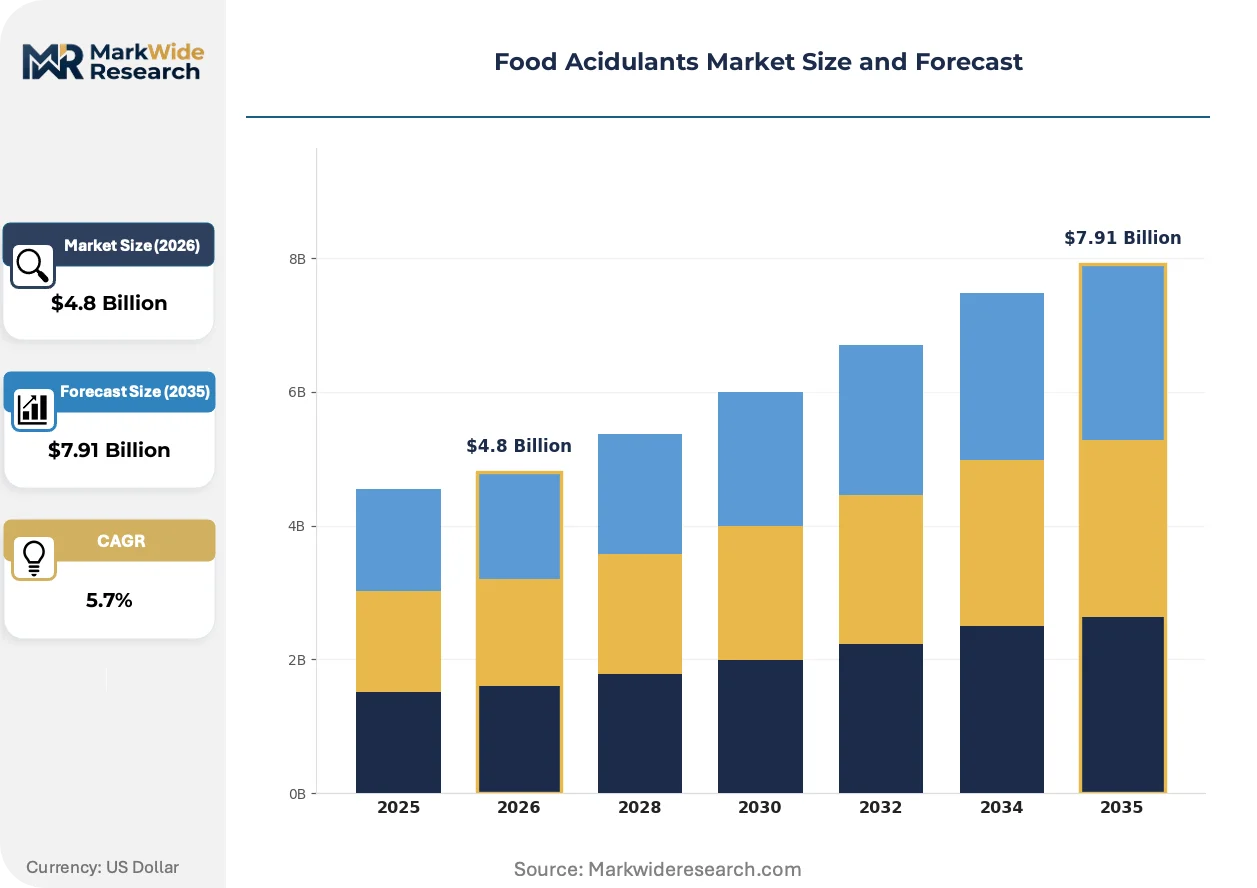
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Malic Acid, Lactic Acid, Tartaric Acid Application: Beverages, Dairy Products, Confectionery, Bakery Form: Liquid, Powder, Granular, Tablet End User: Food Manufacturers, Beverage Producers, Retailers, Restaurants |
| Companies Covered | Jungbunzlauer Suisse AG, Bartek Ingredients Inc., Archer Daniels Midland Co., Prinova Group LLC, Tate & Lyle PLC, Corbion N.V., BRENNTAG SE, Univar Solutions Inc., Cargill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Acidulants Market Emerging Trajectories
Fermentation-derived acidulants are capturing share from petrochemical routes as carbon accounting becomes a procurement filter. Regulatory pressure and biotechnology advances are converging to reshape competitive positioning.
Precision fermentation platforms producing tailored organic acid profiles are overtaking conventional batch fermentation in European pharmaceutical and infant nutrition applications. German and Swiss contract manufacturers are adopting these systems to meet EFSA's tightened purity specifications for sensitive end-uses. The technology is overtaking established supply relationships by offering lot-specific certificates of analysis with full carbon footprint attribution.
REACH's expanded registration requirements for food-contact substances are forcing acidulant importers to submit comprehensive toxicological dossiers for existing products. The regulation is compressing the supplier base to firms with dedicated regulatory affairs teams capable of navigating ECHA's substance evaluation timelines. Specialty acidulants for wine-derived and natural-identical applications face the steepest compliance burdens.
Buyer concentration among multinational beverage conglomerates is consolidating procurement decisions into centralized technical teams with mandate authority over global formulation standards. Regional flavor houses and mid-sized dairy processors are losing direct supplier relationships as Cargill and Jungbunzlauer negotiate frame contracts covering multiple continents. This pattern is most visible in North American and Western European markets where three customers now account for the majority of acidulant volume.
Food Acidulants Market Segmentation
Acidulant selection cascades through formulation economics, regulatory compliance, and end-use performance requirements. Manufacturers configure procurement around pH stability needs, clean-label positioning, and dosing system compatibility across liquid and solid delivery formats.
Product Type:
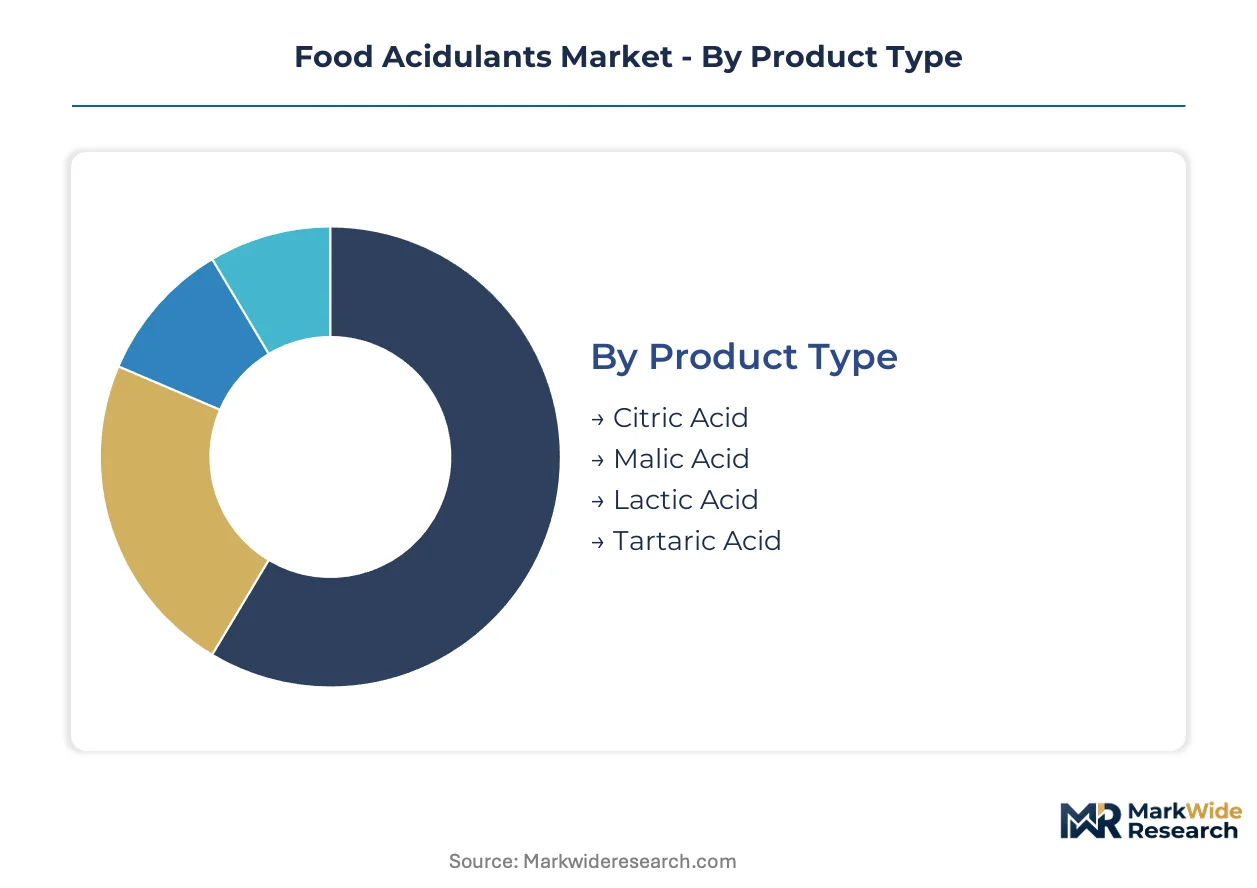
Citric acid commands volume leadership through cost-efficient fermentation production, while lactic acid captures premium positioning in fermentation-derived and dairy-adjacent applications.
- Citric Acid:Produced via Aspergillus niger fermentation from molasses or corn steep liquor, this acid delivers sharp, clean tartness with excellent water solubility. Beverage producers in China and Germany absorb the largest volumes for pH adjustment in carbonated drinks and fruit-flavored waters, constrained only by Shandong province supply concentration risks.
- Lactic Acid:Fermentation-derived from corn or sugar beet feedstock, offering milder acidity with antimicrobial properties that extend shelf life in refrigerated applications. Demand concentrates in plant-based dairy alternatives across European clean-label portfolios, where EFSA's additive re-evaluations favor fermentation-based credentials.
- Malic Acid:Grain-derived acid with prolonged tartness perception valued in sports nutrition formulations.
- Tartaric Acid:Wine industry byproduct acid retaining niche positions in bakery leavening and specialty confectionery.
Mature deployment sits with citric acid across mass-market beverages. Newer deployment is concentrated in lactic acid for fermented and plant-based product lines.
Application:
Formulation intensity varies sharply by category, with beverages demanding precise pH curves and dairy requiring antimicrobial functionality alongside acidification.
- Beverages:Acidulants stabilize flavor profiles, enhance preservative efficacy, and maintain clarity in carbonated and still drinks. Functional beverage producers in Maharashtra and Karnataka are expanding citric and malic acid procurement as FSSAI standards evolve for acidified drink categories.
- Dairy Products:Lactic acid dominates cultured dairy and cheese production, with fermentation-derived grades capturing share in yogurt and kefir applications. European dairy processors retrofit dosing equipment to handle hygroscopic acid variants without moisture contamination.
- Confectionery:Citric acid coatings deliver sour flavor bursts in gummy and hard candy segments.
- Bakery:Tartaric acid and cream of tartar stabilize egg foams and regulate leavening reaction rates.
Volume concentration rests with beverage applications. Margin expansion is climbing fastest in dairy alternatives.
Form:
Physical format selection determines handling infrastructure, dissolution kinetics, and dosing precision in automated production environments.
- Liquid:Pre-dissolved acid solutions enable direct injection into continuous processing lines, eliminating dust exposure and hydration delays. Large-scale beverage bottlers in Jiangsu province specify liquid citric acid for high-speed filling operations where batch consistency is paramount.
- Powder:Spray-dried crystalline acids offer lowest unit cost and flexible reconstitution, dominating dry mix and seasoning applications. Bakery and confectionery manufacturers in the US Corn Belt prefer powder formats for extended shelf stability and freight efficiency.
- Granular:Free-flowing crystals reduce caking in humid storage conditions, preferred by Southeast Asian processors.
- Tablet:Compressed acid units enable precise unit-dosing in artisanal and small-batch production settings.
Established infrastructure favors powder and liquid formats. Granular adoption is expanding most quickly in high-humidity processing environments.
End User:
Procurement scale and technical sophistication diverge sharply between multinational formulators and fragmented foodservice operators.
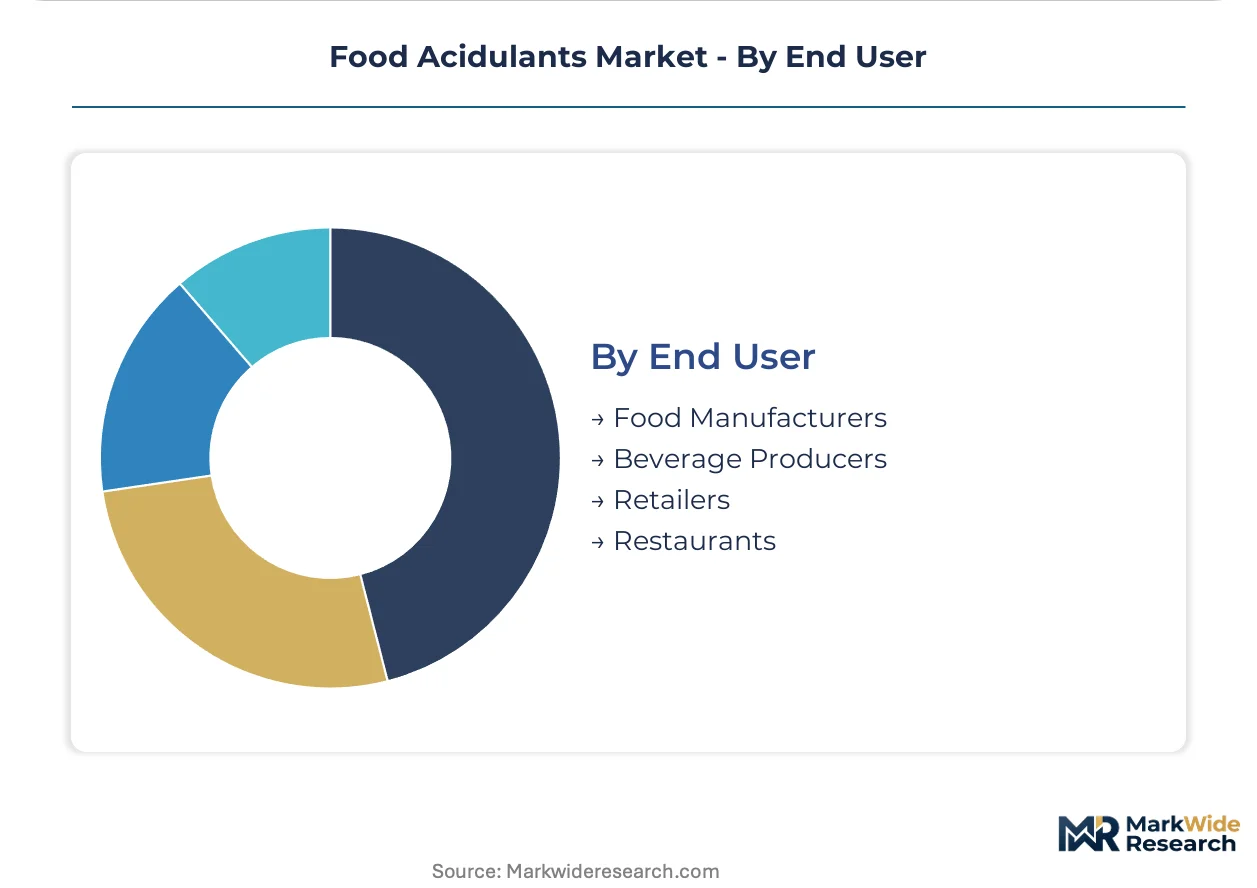
- Food Manufacturers:Integrated processors with dedicated R&D functions specify acidulant grades by purity certificate and carbon footprint attribution. Swiss and German contract manufacturers leverage precision fermentation platforms for lot-specific acidulant blends in infant nutrition and medical food segments.
- Beverage Producers:Centralized technical teams at multinational conglomerates negotiate frame contracts spanning multiple continents, consolidating supplier relationships toward Jungbunzlauer and Cargill for citric and malic acid volumes.
- Retailers:Private-label brand owners specify acidulant inclusion through co-manufacturer agreements rather than direct chemical procurement.
- Restaurants:Foodservice operators rely on pre-formulated sauces and dressings where acidulants are embedded in supplier recipes.
Direct procurement concentrates with food manufacturers and beverage producers. Retailer and restaurant channels access acidulants through indirect formulation partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of fermentation-derived citric acid while European and North American markets absorb premium bio-based grades for clean-label formulations.
China
Shandong and Jiangsu provinces host over 60 percent of global citric acid fermentation capacity, supplying mass-market beverage processors with cost-competitive acidulant volumes. The National Health Commission enforces GB standards for acidulant purity and maximum usage levels in processed foods. Qingdao-based fermentation clusters are expanding lactic acid output to serve domestic plant-based dairy alternatives.
Germany
Beverage conglomerates in Bavaria and North Rhine-Westphalia specify fermentation-derived acidulants with verifiable carbon footprints for clean-label portfolios. EFSA's additive re-evaluation cycles under EU food additive regulations delay product launches by 18-24 months. Hamburg's contract manufacturers are retrofitting dosing equipment to handle hygroscopic lactic acid variants for dairy applications.
United States
Corn Belt processors in Illinois and Iowa leverage grain feedstock access for malic acid production serving sports nutrition and carbonated beverage markets. The FDA governs GRAS status and labeling requirements for acidulant inclusion. Wisconsin dairy clusters are absorbing record volumes of lactic acid for fermented product lines and plant-based alternatives.
India
Maharashtra and Karnataka beverage processors are expanding citric and malic acid procurement as FSSAI evolves standards for acidified drinks and carbonated categories. The Food Safety and Standards Authority of India is tightening additive specifications for domestic and imported acidulants. Mumbai-Pune manufacturing corridors are attracting formulation partnerships with multinational acidulant suppliers.
Switzerland
Precision fermentation specialists in Basel and Zurich supply lot-specific acidulant blends with full carbon footprint attribution for infant nutrition and medical food segments. Swissmedic maintains stringent purity specifications for sensitive end-use applications. Swiss contract manufacturers are adopting continuous processing systems to meet EFSA's tightened certification timelines.
Food Acidulants Market Vendor Landscape
The competitive structure tilts toward fermentation specialists with integrated carbon accounting capabilities. Three tiers have emerged: multinational grain processors with captive feedstock access, European biotechnology firms with precision fermentation platforms, and regional distributors consolidating procurement for mid-sized formulators. Capacity expansion and strategic partnerships dominate competitive moves as players secure fermentation infrastructure and frame contracts with beverage conglomerates.
Within the fermentation-specialist tier, Jungbunzlauer Suisse AG and Corbion N.V. exemplify European biotechnology positioning, while Cargill Inc. anchors the grain-processor archetype with upstream feedstock control. Jungbunzlauer's Swiss origin signals clean-label credibility, Corbion's Dutch structure reflects lactic acid specialization, and Cargill's US incorporation indicates scale-driven commodity acidulant supply. These three occupy positions spanning premium certified grades to mass-market volumes.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Bartek Ingredients Inc. |
| Archer Daniels Midland Co. |
| Prinova Group LLC |
| Tate & Lyle PLC |
| Corbion N.V. |
| BRENNTAG SE |
| Univar Solutions Inc. |
| Cargill Inc. |
| Others |
Supply Flow & Price Mechanics
Fermentation technology maturation simultaneously collapses production costs and concentrates supply among biotechnology specialists with integrated carbon accounting capabilities. The shift from petrochemical to microbial-derived acidulants restructures procurement economics while binding pricing power to verifiable sustainability credentials under EU Green Deal compliance frameworks.
Pricing Analysis
Cost-down pressure on fermentation-derived grades accelerates because biotechnology advances enable price parity with synthetic equivalents. Three-tier pricing structure separates carbon-certified premium grades from standard fermentation-derived and economy petrochemical-origin acidulants. Price differentiation rests on EFSA certification status and Scope 3 disclosure completeness. Beverage conglomerates with centralized technical teams exhibit lowest price sensitivity, while regional flavor houses face acute margin compression from feedstock volatility.
Supply Chain Analysis
EFSA's extended safety re-evaluation cycles and REACH registration requirements gate supplier participation, compressing the vendor base to firms with dedicated regulatory affairs capabilities. Production concentrates in China, Germany, and Switzerland, with Shandong and Jiangsu provinces hosting over sixty percent of global citric acid fermentation infrastructure. Raw material dependencies center on corn, molasses, and sugar beet feedstocks vulnerable to agricultural commodity cycles. Single-source vulnerability from Chinese fermentation concentration represents the dominant structural risk. Distribution runs through frame contracts negotiated directly with multinational beverage and dairy processors, disintermediating traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Acidulants Market functions as a cost-of-compliance story where EU Green Deal additive mandates and EFSA re-evaluation cycles erect regulatory moats favoring incumbent fermentation specialists with established carbon accounting infrastructure.
For Market Incumbents: To counter clean-label substitution pressure from vinegar and citrus juice concentrates, deepen backward integration into captive corn and molasses feedstock supply in the US Corn Belt while accelerating precision fermentation platform deployment for lot-specific acidulant blends in Swiss and German contract manufacturing facilities. For New Entrants and Emerging Players: Mid-sized dairy processors in Maharashtra and Karnataka represent an underserved buyer archetype requiring localized formulation partnerships as FSSAI standards evolve for acidified beverages. White-space capture demands direct-to-manufacturer e-procurement channel development and hygroscopic lactic acid handling expertise for retrofit-dependent European dairy retrofit markets. For Investors and Strategic Acquirers: Exit pathways concentrate in precision fermentation specialists with integrated lifecycle assessment capabilities serving infant nutrition and medical food segments. Long-term viability favors biotechnology platforms with demonstrated EFSA navigation expertise and frame contract relationships with multinational beverage conglomerates. The inflection signal to monitor is fermentation carbon intensity standard adoption under CSRD Scope 3 disclosure mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn Belt processors secure margin protection against molasses price volatility through captive grain sourcing. |
| Precision Fermentation Platform Deployment | Swiss contract manufacturers meet EFSA purity specifications for sensitive infant nutrition applications. |
| Carbon Certification Investment | Fermentation specialists capture premium positioning under EU Green Deal clean-label procurement mandates. |
| Direct E-Procurement Channel Development | Mid-tier producers disintermediate regional wholesalers to recover margin in fragmented formulator segments. |
| Long-term Frame Contract Negotiation | Multinational acidulant suppliers lock volume commitments with centralized beverage conglomerate technical teams. |
Methodological Framework
SEC 10-K filings, customs and trade databases, and Cefic industry reports formed the secondary backbone, cross-referenced against primary interviews with fermentation plant managers, beverage procurement leads, dairy technical directors, and distribution channel partners. Bottom-up acidulant volume estimates by product grade and application triangulated against top-down market sizing from production capacity analysis.
Historical trendline analysis of fermentation capacity expansion and clean-label certification adoption informed projection modeling across the analysis window. Segmentation dimensions included acidulant type, physical form, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to verified baseline volumes, incorporating feedstock cost indices and EFSA re-evaluation timeline assumptions as industry-specific forecast inputs.
Revisions become necessary when EFSA safety re-evaluation cycles extend beyond modeled timelines or when Chinese fermentation infrastructure faces disruption from environmental enforcement actions. Forecasts reflect assumptions about biotechnology cost curves and regulatory compliance burden stability. A model refresh is warranted upon material change in EU Green Deal carbon intensity thresholds for bio-based additive certification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Argentina Food Acidulants Market