
 Clean Label Ingredients Market | 2026-2036
Clean Label Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Ingredients Market Intelligence
Organic and non-GMO specification tiers is rotating toward the center of procurement decisions by major food manufacturers. Cargill leverages its integrated agricultural supply chain to secure certified raw material streams across multiple continents. Kerry Group plc sustains formulation partnerships with retail chains seeking simplified ingredient statements. Ingredion Incorporated specializes in plant-based texturizers that replace chemically modified alternatives in legacy product lines.
Clean label ingredients comprise food additives and functional components derived from natural sources with minimal processing, typically meeting standards for recognizable nomenclature, absence of artificial colors or synthetic preservatives, and traceable supply chains. These substances serve primarily to maintain shelf stability, texture, and sensory performance in packaged foods while satisfying consumer scrutiny of ingredient panels. Sweeteners and preservatives capture divergent margin structures within the ingredient type dimension, with natural sweetener substitutes commanding premium positions while clean label preservatives face faster volume expansion due to reformulation mandates across bakery and dairy applications. The application split shows beverages and snacks generating disproportionate innovation activity as brands respond to younger demographic preferences for transparent sourcing claims.
The FDA's evolving guidance on "healthy" label claims and the USDA's National Organic Program create compliance thresholds that filter supplier participation in the United States market. REACH and the EU Green Deal's Farm to Fork strategy impose substance restriction and origin documentation requirements that reshape European procurement specifications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs as clean label definitions tighten.
Market Dynamics
Enzymatic modification and fermentation-derived substitutes are compressing synthetic additive demand as bakery and beverage manufacturers accelerate reformulation timelines to meet tightening front-of-pack disclosure mandates.
Growth Catalysts
- Farm to Fork Strategy:The EU Green Deal's additive disclosure rules force legacy product reformulation across dairy and bakery applications, expanding procurement of recognizable ingredient decks.
- Fermentation Platforms:Precision fermentation for natural preservatives and sweeteners scales manufacturing yields while satisfying clean label specifications in beverage formulations.
- German Retail Procurement:Discounter and supermarket chain clean label commitments concentrate purchasing power for certified raw material streams.
Market Restraints
- Organic Input Volatility:Certified agricultural supply shortages and weather-driven crop failures inflate raw material costs for non-GMO corn and wheat derivatives.
- REACH Compliance Burden:ECHA substance restriction documentation requirements extend supplier qualification timelines and strain mid-tier ingredient manufacturers.
- Enzyme Stability Limits:Temperature-sensitive natural preservatives constrain shelf-life extension in ambient distribution chains compared to synthetic alternatives.
Strategic Opportunities
- France Front-of-Pack Mandates:Nutri-Score and ingredient panel transparency laws create captive demand for simplified nomenclature in processed food categories.
- Plant-Based Texturizer Convergence:Clean label starches and hydrocolloids capture reformulation demand from dairy alternative and meat analog producers seeking mouthfeel replication.
- Direct-to-Manufacturer Platforms:Digital ingredient marketplaces bypass traditional distributor markups for mid-size bakery and snack producers.
Industry Challenges
- Cross-Functional Formulation Expertise:Shortage of food scientists skilled in enzymatic process optimization delays product redevelopment cycles.
- Multi-Jurisdiction Certification Lag:Simultaneous USDA Organic, EU Organic, and private retailer standard audits extend time-to-market by 8-14 months.
- Legacy Equipment Retrofit Costs:Clean label ingredient hydration and shear sensitivity require capital-intensive production line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Ingredients Market |
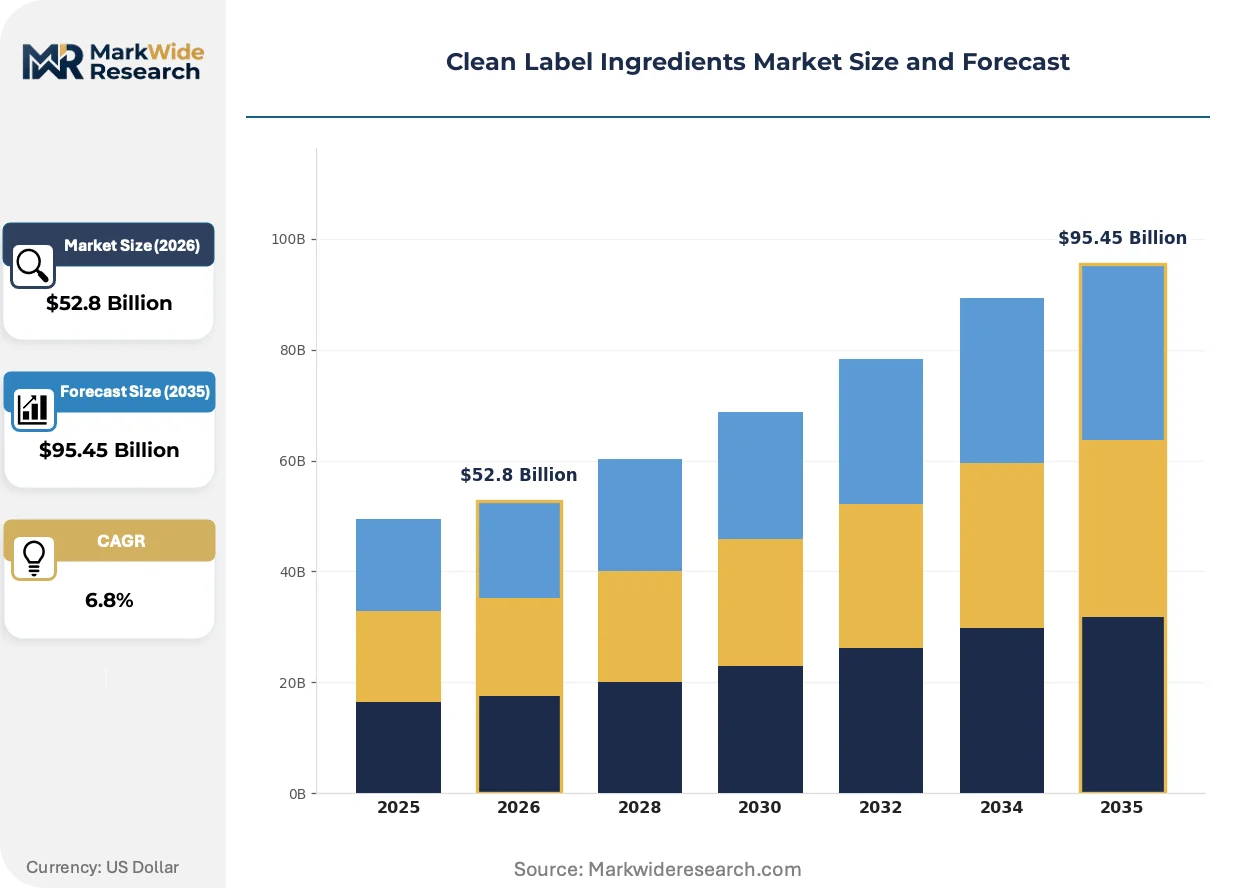
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $95.45 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Sweeteners, Emulsifiers, Preservatives, Thickeners Application: Bakery, Beverages, Dairy, Snacks Form: Powder, Liquid, Granular, Concentrate End User: Food Manufacturers, Beverage Producers, Nutraceuticals, Restaurants |
| Companies Covered | Cargill, Archer Daniels Midland Company, Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, DuPont de Nemours, Inc., Corbion N.V., International Flavors & Fragrances Inc., Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Ingredients Market Strategic Shifts & Innovations
Bioprocessing advances and regulatory disclosure tightening are converging to redefine acceptable ingredient nomenclature across packaged food categories.
Cell-cultured and fermentation-derived natural colors are displacing petroleum-based alternatives in confectionery and beverage applications. Major retail chains in France and Germany now mandate recognizable color sources on front-of-pack displays. This displacement compresses synthetic dye supplier margins while elevating biotech ingredient platforms to strategic status.
REACH substance restriction expansions under ECHA oversight tighten residual solvent limits in extraction processes. Manufacturers face reformulation costs for legacy plant extracts. Bakery applications in Western Europe absorb the highest compliance burden as clean label emulsifier alternatives require novel process validation.
Retailer-led specification audits now dominate supplier selection criteria for North American and European procurement teams. Third-party certification bodies verify supply chain traceability claims. This behavioral shift concentrates contract awards among integrated agricultural processors with captive certified acreage.
Clean Label Ingredients Market Segmentation
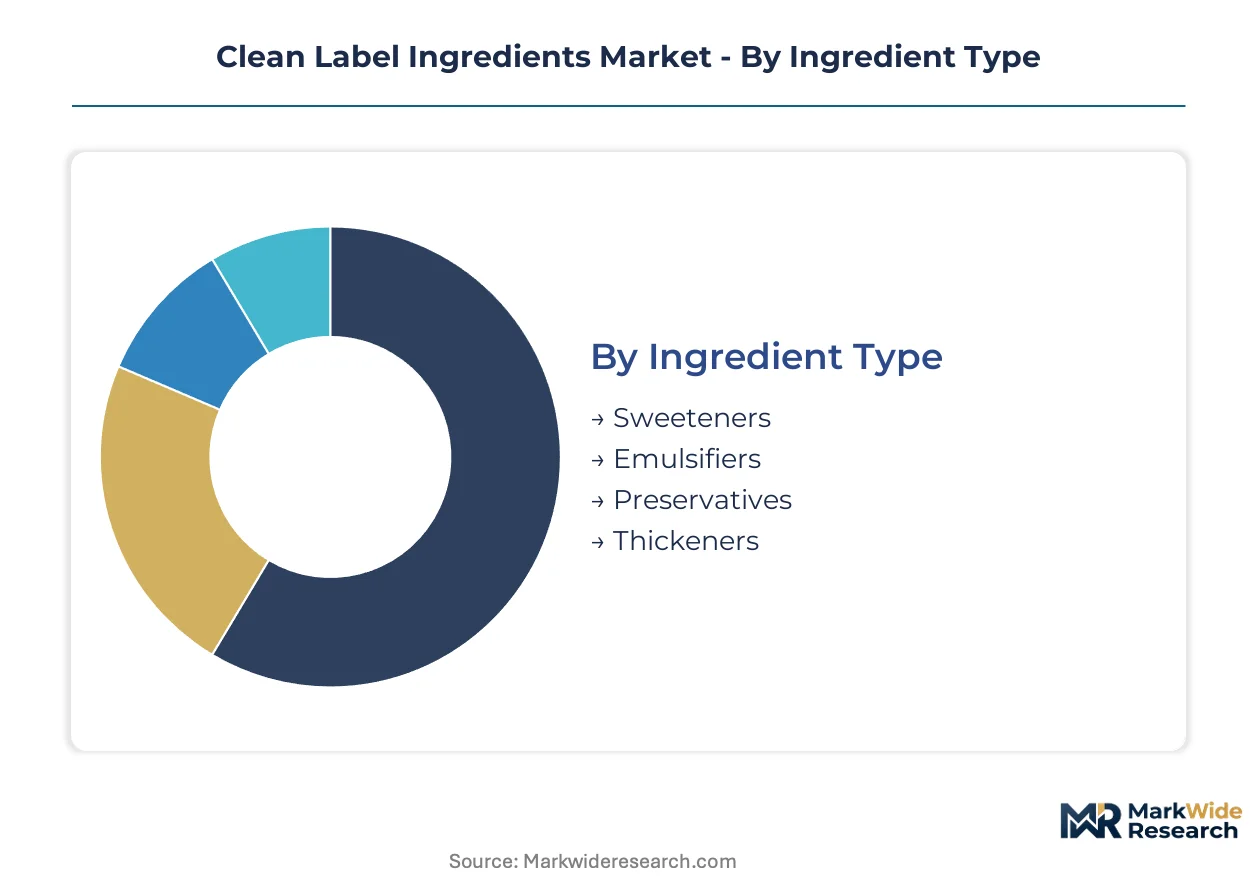
Clean label procurement decisions pivot on ingredient functionality, regulatory compliance thresholds, and manufacturing process compatibility. Segment boundaries blur as enzymatic modification and fermentation platforms create hybrid ingredient classifications that straddle traditional categories.
Ingredient Type:
Sweeteners face the most intense substitution pressure as stevia derivatives and monk fruit extracts displace synthetic high-intensity alternatives, while preservatives encounter rising demand compression from cultured dextrose and vinegar-based systems.
- Sweeteners:Plant-derived high-intensity extracts and crystalline polyols deliver sweetness equivalence with reduced caloric density. Beverage formulators in Germany and France prioritize these for front-of-pack compliance with Nutri-Score regulations.
- Preservatives:Fermentation-derived organic acids and cultured dextrose extend shelf stability without synthetic chemical nomenclature. Bakery applications absorb the fastest volume expansion as EFSA disclosure requirements tighten across Western Europe.
- Emulsifiers:Enzyme-modified lecithin and plant-based mono- and diglycerides replace chemically synthesized alternatives in dairy alternatives.
- Thickeners:Native starches and hydrocolloid blends from tapioca and cassava sources restore mouthfeel in reduced-fat formulations.
Sweeteners retain volume leadership; preservatives hold the steepest expansion curve.
Application:
Cost tier stratification separates premium-positioned beverage formulations from commodity bakery applications where margin compression limits ingredient specification flexibility.
- Beverages:Clean label color stability and acidification systems dominate innovation pipelines. Precision fermentation platforms scale natural preservative inclusion for ambient distribution chains.
- Bakery:Enzymatic dough conditioners and cultured wheat starch replace azodicarbonamide and synthetic emulsifiers. French and German retail chains mandate simplified ingredient panels for private-label bread lines.
- Dairy:Plant-based texturizers replicate mouthfeel in yogurt and cheese alternatives as fermentation-derived stabilizers gain process tolerance.
- Snacks:Expeller-pressed oils and natural antioxidant systems displace TBHQ and BHT in extruded and fried product categories.
Bakery commands absolute volume; beverages generate the highest specification premiums.
Form:
Supply concentration among agricultural processors shapes availability patterns, with powder and liquid formats dominating at different points in the manufacturing value chain.
- Powder:Spray-dried natural colors and encapsulated flavor systems offer extended shelf stability and precise dosing control for dry-mix applications.
- Liquid:Pumpable concentrates simplify incorporation into continuous beverage processing lines and reduce dust exposure in bakery environments.
- Granular:Crystalline polyols and coarse-ground native starches flow freely through standard conveying equipment without caking.
- Concentrate:High-potency extracts reduce transportation costs and storage footprint for manufacturers with limited warehouse capacity.
Powder retains manufacturing ubiquity; liquid formats gain share in beverage-centric supply chains.
End User:
Customer type determines certification burden intensity, with food manufacturers navigating the most complex multi-jurisdiction audit requirements.
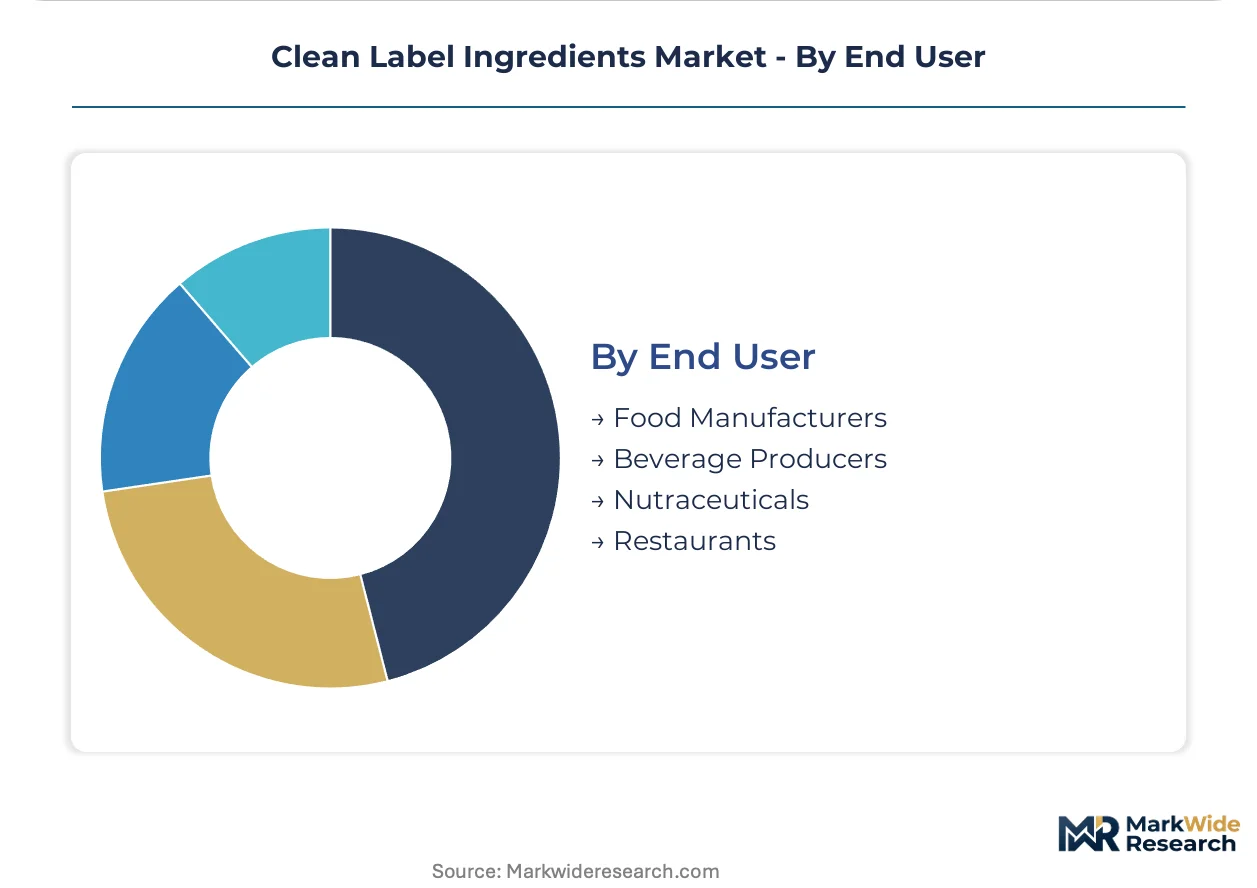
- Food Manufacturers:Integrated procurement teams manage USDA Organic, EU Organic, and private retailer standard compliance simultaneously. Reformulation timelines stretch 8-14 months for legacy product lines.
- Beverage Producers:Ambient distribution requirements drive natural preservative adoption at premium price points. Cold-chain beverage specialists prioritize clean label color stability over extended shelf life.
- Nutraceuticals:Supplement manufacturers leverage clean label positioning for premium pricing in direct-to-consumer channels.
- Restaurants:Foodservice distributors specify clean label ingredients for chain menu transparency initiatives, though volume scale lags packaged goods manufacturers.
Food manufacturers absorb the highest compliance costs; nutraceuticals capture the steepest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in clean label ingredients tilt toward Western European processing hubs sourcing certified agricultural inputs from North and South American growing regions. Germany and France run structural ingredient trade deficits, importing enzymatically modified starches and fermentation-derived preservatives. The United States maintains surplus positions in organic corn derivatives and non-GMO soy isolates.
Germany
Discounter chains Aldi and Lidl enforce clean label procurement standards that cascade through Central European supply chains. The EU Green Deal's Farm to Fork strategy mandates additive disclosure thresholds that accelerate reformulation of legacy bakery lines. North Rhine-Westphalia hosts concentrated food manufacturing clusters where enzymatic texturizer demand outpaces domestic fermentation capacity.
United States
USDA National Organic Program certification underpins premium positioning for corn-derived sweeteners and wheat-based texturizers in export markets. FDA guidance on "healthy" label claims tightens permissible ingredient nomenclature for front-of-pack marketing. Midwest processing corridors in Iowa and Illinois concentrate spray-dried natural color and encapsulated flavor production for North American beverage manufacturers.
France
Nutri-Score labeling laws and ANSM enforcement of additive transparency create captive demand for simplified ingredient decks in processed food categories. EFSA substance restrictions on synthetic emulsifiers force dairy alternative reformulation toward enzyme-modified lecithin. The Paris Basin and Lyon corridor anchor fermentation-derived natural preservative production for pan-European distribution.
United Kingdom
Post-Brexit regulatory divergence from EU additive approvals creates compliance complexity for suppliers serving both markets. FSA enforcement of clean label claims in retail channels drives private-label reformulation timelines. East Anglia and Yorkshire food manufacturing belts absorb imported certified raw materials for bakery and snack applications.
Netherlands
Rotterdam-Antwerp logistics hubs facilitate transshipment of fermentation-derived ingredients from Asian biotech suppliers to European formulators. REACH documentation requirements under ECHA oversight extend supplier qualification cycles for mid-tier manufacturers. The Randstad region concentrates hydrocolloid blending and plant-based texturizer formulation for dairy alternative producers.
Clean Label Ingredients Market Key Industry Players
Concentration sits with integrated agricultural processors controlling certified raw material streams across multiple continents. Mid-tier fermentation specialists and regional hydrocolloid blenders occupy fragmented niches beneath this top tier. Three archetypes dominate: captive supply chain operators, enzymatic modification platforms, and precision fermentation biotechs. Competitive moves center on backward integration into organic acreage and strategic partnerships with retail chains seeking exclusive clean label supply arrangements.
Among North American agricultural conglomerates, Cargill and Archer Daniels Midland Company exemplify the captive supply chain archetype through their control of certified corn and wheat derivative streams. Kerry Group plc represents the formulation partnership model, embedding technical service capabilities within retail customer operations. These three anchors demonstrate how scale, certification depth, and customer integration separate sustainable competitive positions from commodity ingredient trading.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| DuPont de Nemours, Inc. |
| Corbion N.V. |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Others |
Cost & Logistics Intelligence
Fermentation-derived natural preservatives displacing synthetic alternatives simultaneously redraws procurement geography toward Western European biotech hubs and compresses margin structures for legacy chemical suppliers. This substitution dynamic concentrates pricing power among integrated agricultural processors with captive certified acreage while fragmenting downstream formulation markets.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-tiered adjustments. Price differentiation centers on certification grade—USDA Organic and EU Organic tiers command substantial premiums over conventional natural claims—and geographic delivery cost differentials between North American corn belt origins and European processing destinations. Cost compression in commodity bakery texturizers is intensifying because mid-tier manufacturers lack backward integration into certified supply chains. Private-label retail procurement teams exhibit highest price sensitivity, while precision fermentation biotechs with proprietary strain libraries demonstrate lowest sensitivity due to performance-locked formulations.
Supply Chain Analysis
Port congestion on trans-Atlantic lanes from Rotterdam to New York Harbor elevates inbound logistics costs for South American organic corn and cassava derivatives. Supply concentrates in the United States, Brazil, and Germany, with enzymatic modification capacity clustering in Iowa and Illinois while fermentation platforms expand across North Rhine-Westphalia. Raw material dependencies include certified non-GMO corn, tapioca starch, and wheat derivatives. Single-source vulnerability pervades precision fermentation starter cultures. Distribution runs through integrated agricultural processors with direct manufacturer relationships, bypassing traditional distributor markups for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against fermentation-derived ingredients eroding their synthetic additive franchises. Precision fermentation platforms threaten legacy emulsifier and preservative margins through superior performance claims and regulatory tailwinds.
For Market Incumbents: Secure captive certified acreage through long-term supply agreements with organic cooperatives in Iowa and Brazil to lock in non-GMO corn streams. Deepen backward integration into enzymatic modification capacity near major bakery manufacturing clusters in Germany. This defends against precision fermentation biotechs capturing reformulation mandates from Aldi and Lidl procurement teams. For New Entrants and Emerging Players: Technical service gaps in clean label formulation support present the most penetrable white space, as Cargill and Kerry Group prioritize volume accounts over mid-tier bakery producers. Target French dairy alternative manufacturers seeking enzyme-modified lecithin for Nutri-Score compliance. Deploy direct-to-manufacturer digital platforms with rapid sample turnaround and embedded food scientist support to bypass distributor relationships. For Investors and Strategic Acquirers: EFSA substance restriction expansions under ECHA oversight reshape the acquisition landscape toward fermentation specialists with validated natural preservative pipelines. Long-term viability favors precision fermentation biotechs with commercial-scale manufacturing and retail chain partnerships over commodity extractors. Monitor ANSM enforcement actions on additive transparency as the signal indicating acceleration or deceleration in reformulation-driven procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Acreage | Long-term supply agreements with Iowa and Brazilian organic cooperatives lock in non-GMO corn derivatives. |
| Fermentation Platform Scale-Up | Commercial manufacturing capacity for natural preservatives captures EFSA-driven reformulation demand in Western Europe. |
| Direct-to-Manufacturer Digital Marketplace | Bypasses traditional distributor markups for mid-tier French and German bakery producers seeking rapid sample validation. |
| Retail Chain Formulation Partnership | Embedded technical service teams at Aldi and Lidl secure exclusive clean label supply arrangements. |
| Multi-Jurisdiction Certification Investment | Simultaneous USDA Organic and EU Organic audits reduce time-to-market for North American export formulations. |
Research Approach
The analysis maps sweetener substitution dynamics, preservative fermentation platforms, and enzymatic texturizer applications, each validated through procurement directors at major retail chains, food manufacturing R&D leads, and precision fermentation biotech executives. Primary interviews with German discounter sourcing teams, French dairy alternative formulators, and Iowa agricultural processors combined with secondary validation from EFSA additive restriction databases, USDA National Organic Program certification records, and customs trade flows. Bottom-up volume modeling across ingredient types triangulates against top-down expenditure estimates from food manufacturer procurement disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models ingredient type, application category, form factor, and end-user compliance burden intensity as segmentation dimensions. CAGRs derive from regression analysis of historical procurement volumes against regulatory milestone timing and retail chain commitment announcements. Industry-specific forecast inputs include ECHA substance restriction implementation schedules and German retail clean label commitment penetration curves.
Forecasts assume regulatory continuity in EU Green Deal Farm to Fork implementation and FDA guidance evolution on healthy label claims; material policy shifts would require re-modeling. Unmodeled risks include catastrophic weather events in certified organic growing regions and breakthrough synthetic biology platforms displacing plant-derived alternatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Lactoperoxidase Market