
 Argentina Food Acidulants Market | 2026-2036
Argentina Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Food Acidulants Market Outlook
Clean-label fermentation technology is rewriting how acidulants enter Argentine food formulations. Corbion leverages microbial fermentation expertise to supply biobased lactic acid with minimal chemical processing residues. Tate & Lyle PLC anchors the citric acid segment through its global supply network reaching Buenos Aires industrial corridors. Cargill competes with integrated sweetener-acidulant bundles that reduce procurement complexity for local beverage bottlers.
Food acidulants comprise organic acids—citric, lactic, malic, and tartaric—typically produced via fermentation or chemical synthesis, functioning to lower pH, enhance flavor profiles, inhibit microbial spoilage, and stabilize color in processed foods. Citric acid dominates volume flows given its versatility across beverages and dairy applications, while lactic acid captures margin premiums in clean-label positioning for bakery and snack segments. Powder and granule forms lead industrial procurement due to handling efficiency, though liquid formats gain traction in automated dosing systems at large beverage plants.
Argentina's national food safety regulator enforces CODEX-aligned additive maximum limits, while the Mercosur technical regulation harmonizes cross-border acidulant standards with Brazil and Paraguay. Compliance with these frameworks shapes import sourcing decisions and domestic manufacturing investments. Stakeholders must monitor evolving Mercosur labeling requirements and local biotechnology incentives that could redirect production economics toward fermentation-based domestic supply.
Market Dynamics
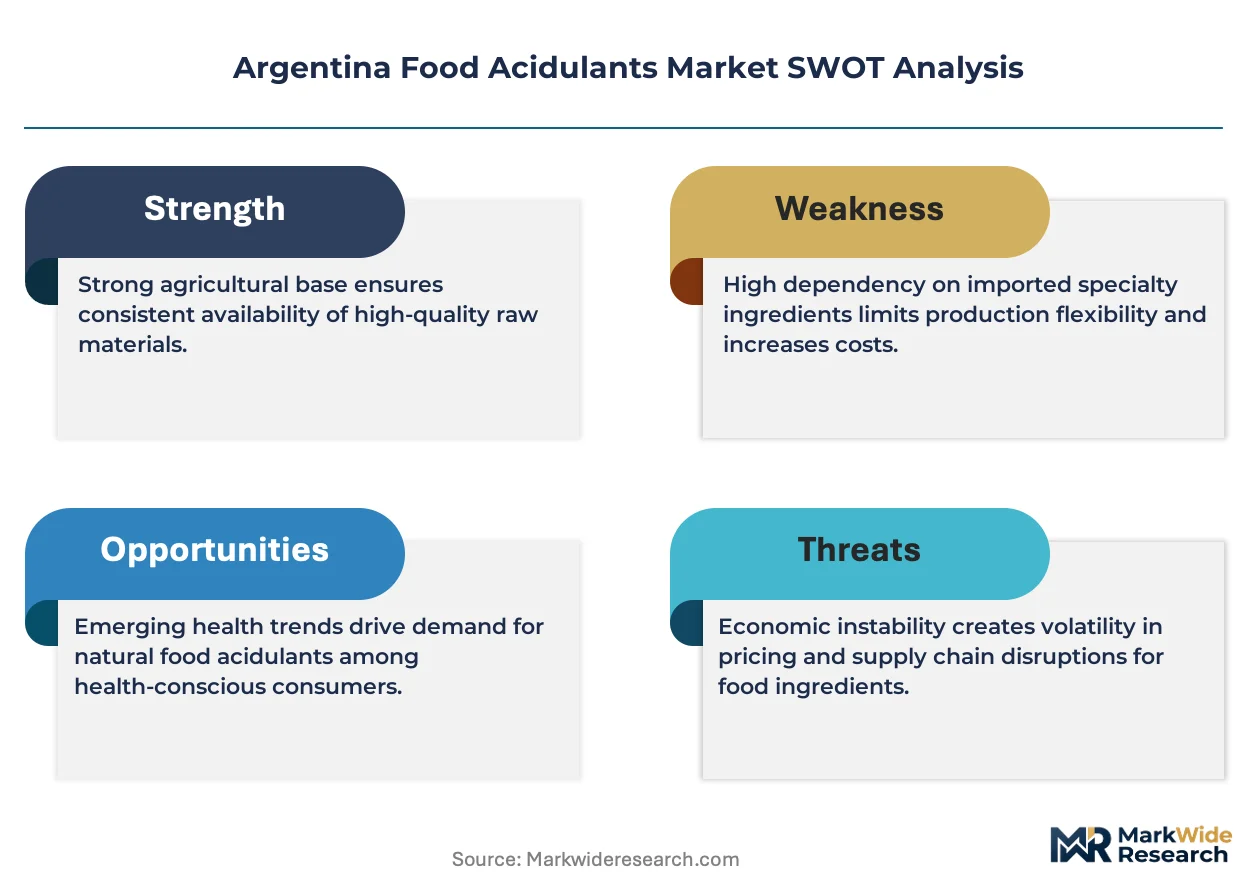
Clean-label fermentation technology is compressing chemical synthesis margins across Argentine food acidulant supply chains. Domestic beverage formulators now prioritize biobased acid streams that satisfy CODEX-aligned purity standards while reducing synthetic additive declarations on consumer labels.
Growth Catalysts
- Buenos Aires industrial corridor concentration:Proximity of acidulant consumers to Argentina's densest food processing cluster minimizes logistics friction and enables just-in-time fermentation feedstock delivery.
- Mercosur technical regulation harmonization:Aligned maximum additive limits with Brazil and Paraguay eliminate duplicate testing burdens for cross-border acidulant shipments.
- Fermentation biotechnology maturation:Advances in microbial strain engineering cut lactic acid production cycles while improving optical purity for clean-label bakery applications.
Market Restraints
- Molasses feedstock price volatility:Argentine sugar beet harvest fluctuations transmit directly to citric acid fermentation economics, compressing producer margins during drought cycles.
- Import dependency for specialty acids:Domestic capacity gaps in tartaric acid crystallization force Argentine wineries and confectioners to source from Chilean and Italian suppliers.
- CODEX maximum limit stringency:Tight additive caps in acidified dairy categories constrain formulation flexibility for regional cheese processors seeking extended shelf life.
Strategic Opportunities
- Córdoba province food processing expansion:Underdeveloped acidulant distribution infrastructure in Argentina's second-largest dairy region creates first-mover positioning for localized fermentation facilities.
- Biotechnology production incentives:Pending federal R&D tax credits for industrial biotechnology could redirect capital toward domestic lactic acid fermentation rather than imported citric acid.
- Automated liquid dosing systems:Large beverage plants in Greater Buenos Aires are retrofitting powder handling lines with continuous acid injection equipment, opening service-contract revenue streams.
Industry Challenges
- Microbial strain IP licensing complexity:Proprietary fermentation organisms for high-yield lactic acid remain controlled by European biotechnology holders, forcing Argentine producers into royalty-bearing technology transfer agreements.
- CODEX compliance certification timelines:New acidulant variants face extended approval windows at Argentina's national food safety regulator, delaying product launches against faster-imported alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Food Acidulants Market |
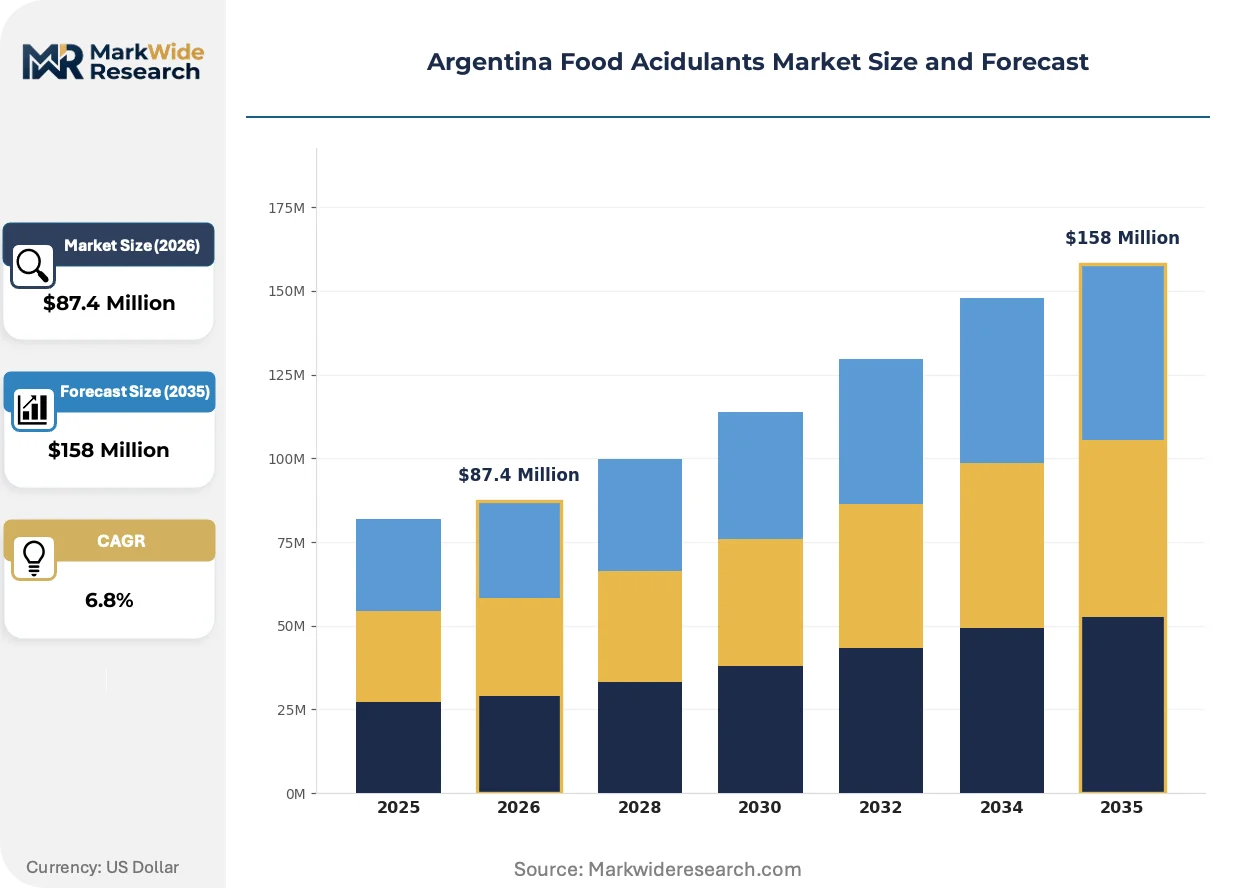
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Malic Acid, Tartaric Acid Application: Beverages, Bakery, Dairy Products, Snacks Form: Liquid, Powder, Granules, Crystals End User: Food Manufacturers, Beverage Companies, Restaurants, Bakeries |
| Companies Covered | Tate & Lyle PLC, Corbion, Helm AG, Eltee International, Brenntag AG, Biosystems S.A., ADM, Cargill, Jungbunzlauer Suisse AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Food Acidulants Market Strategic Shifts
Fermentation-derived acidulants are displacing petrochemical routes across Argentine food manufacturing. Three interconnected developments are compressing legacy supply structures while elevating biobased purity standards.
Precision fermentation using engineered yeast strains is rendering obsolete traditional Aspergillus niger citric acid production. Argentine beverage bottlers in Quilmes and Pilar industrial parks are trialing these biobased streams for reduced chemical residue labeling. The technology is compressing capital requirements for acidulant manufacturing while enabling smaller-batch production closer to formulation sites.
CODEX-aligned additive maximum limits enforced by Argentina's national food safety regulator are tightening purity documentation requirements. Acidulant importers now face expanded third-party testing obligations for heavy metal and solvent residue verification. Dairy processors in Santa Fe province are reformulating around these stricter caps, prioritizing fermentation-derived acids with cleaner analytical profiles.
Consolidated procurement by multinational beverage anchor buyers is fragmenting supplier relationships for mid-tier Argentine food processors. Large bottlers in Buenos Aires province now negotiate acidulant-sweetener bundles directly with integrated global suppliers. Smaller regional dairies and bakeries in Mendoza and San Juan are responding through cooperative purchasing arrangements to recover volume leverage.
Argentina Food Acidulants Market Segmentation
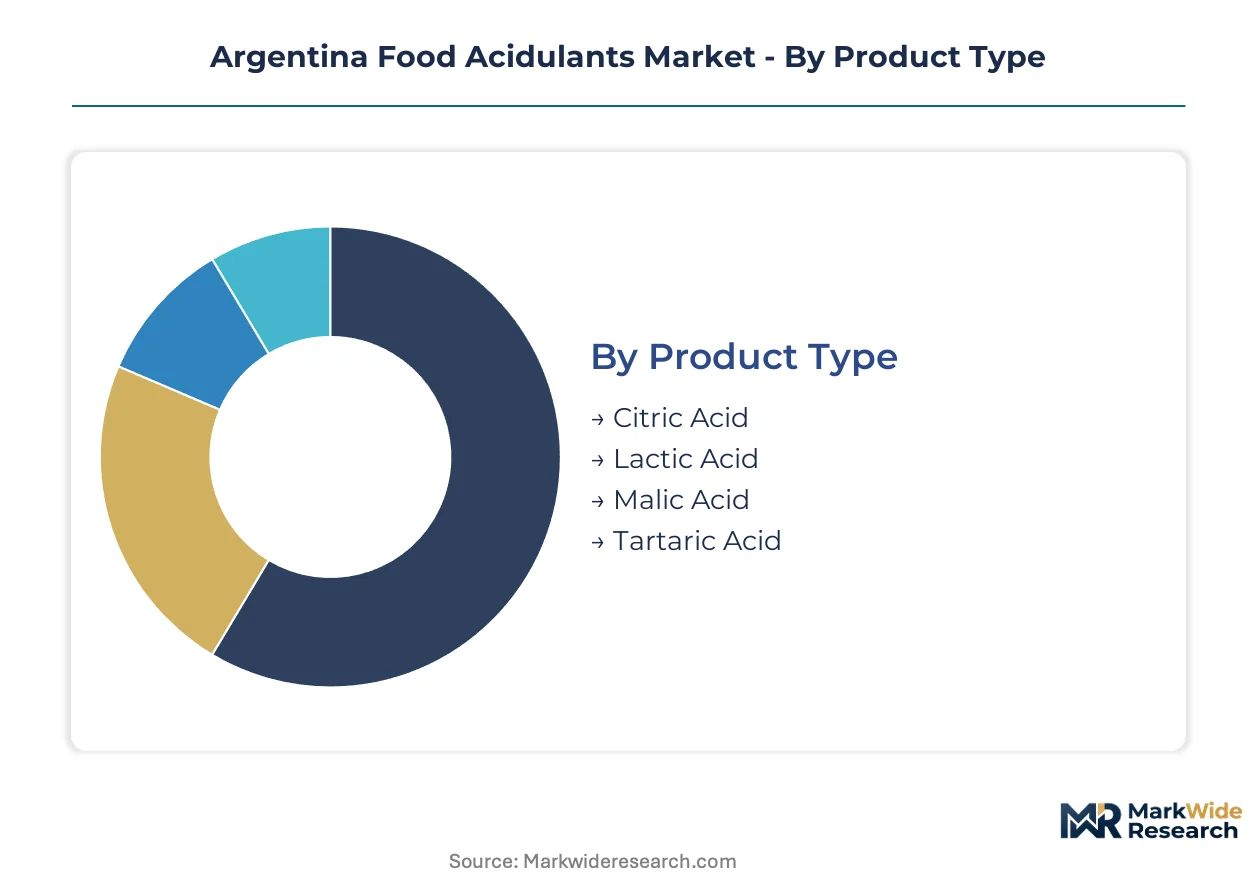
Acidulant procurement patterns across Argentina diverge sharply by processing scale and automation level. Buenos Aires beverage plants negotiate bulk liquid contracts with integrated service tiers, while Mendoza bakeries source powder formats through distributors with minimal technical support.
Product Type:
After-sales service intensity varies dramatically across acidulant chemistries, with fermentation-derived products demanding microbial strain troubleshooting and purity certification support that synthetic alternatives rarely require.
- Citric Acid:Produced primarily through Aspergillus niger fermentation of molasses or sucrose, this tricarboxylic acid delivers the sharpest pH reduction per unit cost. Demand concentrates in Greater Buenos Aires beverage corridors where Coca-Cola FEMSA and Arcor bottling facilities prioritize its compatibility with high-fructose syrup systems and established supply chain relationships with Tate & Lyle distributors.
- Lactic Acid:Microbial fermentation of corn or sugar beet sugars yields this alpha-hydroxy acid with superior clean-label positioning. Santa Fe dairy processors and Córdoba artisanal cheese makers drive adoption for pH-controlled curd formation, though optical purity specifications require dedicated technical service from Corbion's local fermentation specialists.
- Malic Acid:Chemical synthesis or fermentation routes produce this dicarboxylic acid with prolonged sourness perception. Confectioners in Rosario industrial parks favor its flavor stability in hard candies.
- Tartaric Acid:Natural crystallization from grape pomace or chemical synthesis yields this diprotic acid with distinctive optical activity. Mendoza wineries source through Chilean importers due to domestic crystallization capacity gaps.
Citric Acid holds the largest share; momentum sits with Lactic Acid.
Application:
Cost tier stratification separates commodity beverage acidification from premium bakery positioning, with dairy applications occupying a mid-tier technical complexity band.
- Beverages:Carbonated soft drinks, fruit juices, and functional drinks constitute the highest-volume acidulant consumption channel. Quilmes and Pilar industrial parks house automated dosing infrastructure that favors liquid citric acid delivered via tanker truck with integrated inventory management services.
- Bakery:Bread, cakes, and pastries utilize acidulants for dough conditioning and mold inhibition. Córdoba's expanding commercial baking sector purchases lactic acid through regional distributors offering formulation guidance for clean-label claims.
- Dairy Products:Yogurt, cheese, and acidified milk drinks require precise pH control for protein stability. Santa Fe processors face CODEX maximum limit constraints that favor fermentation-derived acids with documented purity profiles.
- Snacks:Flavored chips and extruded products employ acidulants for taste enhancement and shelf-life extension. Seasoning application equipment in Buenos Aires province plants handles powder and granule formats exclusively.
Beverages dominates volume; Bakery climbs the fastest on clean-label reformulation.
Form:
Volume economics favor bulk powder for mid-tier processors, while automated beverage lines drive liquid format penetration with associated equipment service dependencies.
- Powder:Spray-dried or crystallized acidulants in free-flowing particulate form enable flexible dosing across batch operations. Mendoza and San Juan regional bakeries rely on 25-kilogram bag distribution with minimal technical support requirements.
- Liquid:Aqueous solutions or concentrated suspensions facilitate continuous injection in high-speed production environments. Greater Buenos Aires beverage retrofits specify stainless steel tank systems with vendor-managed maintenance contracts.
- Granules:Agglomerated particles reduce dust generation during handling. Snack seasoning operations in Buenos Aires province specify this intermediate format for pneumatic conveying compatibility.
- Crystals:Purified solid forms with defined particle size distribution support precise weighing in artisanal applications. Specialty confectioners in Rosario source tartaric acid crystals for controlled dissolution rates.
Powder holds the largest share; Liquid gains share fastest on automation investment.
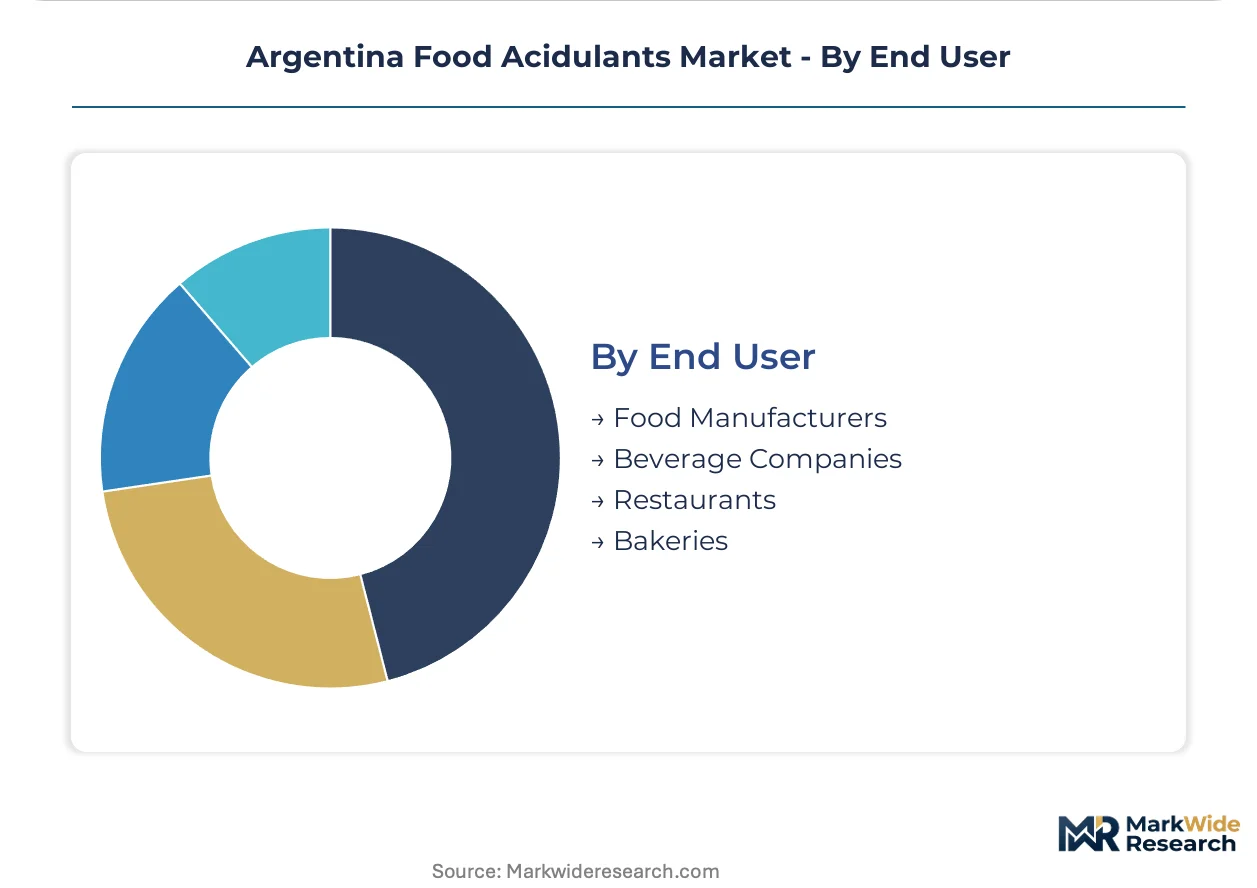
End User:
Customer type determines procurement sophistication, with multinational beverage anchors negotiating direct manufacturer relationships while fragmented food service channels rely on distributor intermediaries.
- Food Manufacturers:Industrial-scale processors of packaged goods operate integrated quality laboratories that validate acidulant certificates of analysis. Arcor and Molinos Río de la Plata maintain approved supplier lists with annual audit requirements.
- Beverage Companies:Bottling operations with continuous production lines demand just-in-time delivery and technical troubleshooting support. Coca-Cola FEMSA's Argentine facilities specify fermentation-derived acids with full traceability documentation.
- Restaurants:Commercial kitchens and catering operations purchase acidulants through food service distributors in small package formats. Buenos Aires metropolitan area concentration supports consolidated delivery routes.
- Bakeries:Artisanal and commercial bread producers vary in technical capability from bench-scale pH testing to no quality control infrastructure. Córdoba province growth attracts distributor expansion with basic formulation guidance.
Food Manufacturers holds the largest share; Beverage Companies show steepest expansion trajectory on foreign direct investment in production capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian acidulant exporters dominate Mercosur trade corridors, shipping fermentation-derived citric acid through Uruguay to Argentine beverage bottlers. Chilean tartaric acid crystallizers supply Mendoza wineries via Andean logistics routes.
Buenos Aires Province
Coca-Cola FEMSA and Arcor bottling facilities drive concentrated acidulant consumption across Quilmes and Pilar industrial parks. Argentina's national food safety regulator enforces CODEX-aligned additive maximum limits that elevate purity documentation requirements. Greater Buenos Aires hosts automated liquid dosing infrastructure that favors tanker-truck delivery of fermentation-derived acids with vendor-managed inventory services.
Córdoba Province
Expanding commercial bakeries and artisanal cheese operations generate rising lactic acid demand for clean-label pH control. Pending federal R&D tax credits for industrial biotechnology could redirect capital toward domestic fermentation facilities. The province's underdeveloped acidulant distribution infrastructure creates first-mover positioning opportunities for localized biobased production.
Santa Fe Province
Dairy processors face CODEX maximum limit stringency in acidified milk categories that constrains formulation flexibility for extended shelf-life products. The national food safety regulator's tight additive caps favor fermentation-derived acids with documented heavy metal and solvent residue profiles. Regional yogurt and cheese facilities prioritize Corbion's microbial fermentation supply for optical purity specifications.
Mendoza Province
Wineries and specialty confectioners source tartaric acid through Chilean importers due to domestic crystallization capacity gaps. Grape pomace availability supports potential natural extraction operations. The province's artisanal food sector purchases acidulant crystals through distributors offering minimal technical support for precise weighing applications.
Argentina Food Acidulants Market Competitive Environment
On the supply side, the industry is bifurcated between integrated multinational suppliers with fermentation biotechnology platforms and regional distributors serving fragmented mid-tier processors. Three archetypes dominate: global fermentation specialists with microbial strain IP, integrated sweetener-acidulant bundlers, and import-dependent commodity traders. Capacity expansion and strategic partnerships represent the primary competitive vectors as players secure molasses feedstock contracts and automated dosing service agreements.
Within the fermentation biotechnology tier, Corbion and Jungbunzlauer Suisse AG exemplify microbial expertise positioning, while Tate & Lyle PLC occupies a supply-chain anchor role through established Buenos Aires distribution corridors. Cargill represents integrated bundling strategy, combining sweetener and acidulant procurement to reduce complexity for beverage bottlers. These three companies sit within distinct competitive positions: biobased purity leadership, legacy supply network control, and procurement simplification through portfolio breadth.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Corbion |
| Helm AG |
| Eltee International |
| Brenntag AG |
| Biosystems S.A. |
| ADM |
| Cargill |
| Jungbunzlauer Suisse AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Argentine fermentation-based lactic acid production compresses supplier margins while elevating import parity pricing for clean-label formulations. CODEX-aligned purity documentation requirements add certification layers that widen the cost spread between biobased and synthetic acidulant streams.
Pricing Analysis
Fermentation-generation pricing gaps separate legacy citric acid from next-generation precision fermentation outputs. Three-tier pricing structure across premium, standard, and economy levels stratifies by optical purity certification and microbial strain documentation depth. Price differentiation centers on CODEX compliance grade and after-sales technical service bundling. Pricing pressure stems from molasses feedstock volatility in Tucumán sugar beet regions. Mid-tier dairy processors in Santa Fe province exhibit highest price sensitivity; multinational beverage bottlers in Buenos Aires show lowest sensitivity due to volume leverage.
Supply Chain Analysis
Export-control regimes on proprietary microbial strain IP limit technology transfer flows to Argentine fermentation facilities. Supply concentrates in Brazil, China, and the Netherlands for citric acid fermentation infrastructure. Raw material dependencies include Tucumán molasses, imported corn starch, and Chilean tartaric acid crystalline feedstock. Single-source vulnerability runs through Brazilian citric acid exporters dominating Mercosur trade corridors. Distribution runs through Buenos Aires industrial corridor tanker-truck networks for liquid formats and regional distributor warehouses for powder and granule packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across acidulant procurement tiers creates niche positioning opportunities as clean-label reformulation splits demand between multinational beverage anchors and mid-tier artisanal processors.
For Market Incumbents: Harden fermentation strain IP control through exclusive licensing with European biotechnology holders to block domestic competitor access. Expand captive molasses supply contracts in Tucumán province to neutralize feedstock price volatility threatening margin compression. Vertical integration into automated liquid dosing service contracts locks in Buenos Aires beverage plant relationships against distributor intermediaries. For New Entrants and Emerging Players: Córdoba province's underdeveloped acidulant distribution infrastructure and expanding commercial bakery sector represent the most penetrable entry point for localized fermentation facilities. Target Santa Fe dairy processors seeking CODEX-compliant lactic acid alternatives with documented optical purity profiles. Lead with technical service bundling including microbial strain troubleshooting to differentiate from commodity importers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation biotechnology as engineered yeast strains compress production cycle timelines. Long-term viability favors platforms with proprietary strain IP and integrated sweetener-acidulant bundling capabilities. Watch for federal R&D tax credit legislation as the signal indicating domestic production economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Tucumán province feedstock contracts neutralize drought-driven price volatility for citric acid fermentation. |
| Precision Fermentation Technology Licensing | Engineered yeast strain access enables Corbion and Jungbunzlauer to maintain biobased purity leadership positioning. |
| Automated Liquid Dosing Service Contracts | Greater Buenos Aires beverage plant retrofits create recurring revenue streams tied to tanker-truck delivery infrastructure. |
| Córdoba Province Distribution Expansion | First-mover positioning captures rising lactic acid demand from expanding commercial bakeries and artisanal cheese operations. |
| Codex Compliance Certification Investment | Argentina's national food safety regulator documentation capabilities accelerate approval timelines against import competitors. |
Study Parameters
A standing panel of fermentation plant managers, beverage procurement leads at Coca-Cola FEMSA and Arcor facilities, dairy technical directors in Santa Fe province, and Corbion regional sales engineers provided ongoing calibration across the study period. Primary interview findings triangulated against secondary validation from ANMAT regulatory filings, Mercosur technical regulation harmonization documents, SEC 10-K disclosures from Tate & Lyle and Cargill, and Argentine customs import data for tartaric acid crystalline feedstock. Bottom-up volume modeling across acidulant chemistries and top-down GDP-elasticity checks anchored forecast integrity.
Scenario-bracketing framed low-case and high-case demand trajectories across the projection horizon. Segmentation dimensions modeled include acidulant chemistry type, application category, physical form factor, and end-user procurement sophistication tier. CAGRs derived from historical volume elasticities against beverage production indices and dairy processing capacity expansion plans. Molasses feedstock price cycles and CODEX maximum limit revision timelines served as industry-specific forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in Argentine peso exchange rate stability and Mercosur tariff harmonization schedules would shift the trajectory. Forecasts reflect documented assumptions regarding fermentation biotechnology maturation rates and federal R&D incentive passage. Material shifts in ANMAT regulatory stringency or Brazilian exporter pricing power would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Food Grade Stearic Acid Market