
 Germany Food Emulsifiers Market | 2026-2036
Germany Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Emulsifiers Market Foresight
Germany is tilting toward expanded domestic emulsifier production capacity as food manufacturers seek shorter supply chains. BASF SE leverages its Ludwigshafen chemical complex to sustain integrated lecithin and specialty ester output for bakery and confectionery clients. Cargill, Incorporated anchors its European emulsifier distribution through Hamburg port logistics, while Kerry Group differentiates via tailored blends for meat substitute applications.
Food emulsifiers are surface-active agents with hydrophilic-lipophilic balance values typically ranging from 2 to 16, designed to stabilize heterogeneous mixtures of immiscible liquids such as oil and water in processed foods. These compounds reduce interfacial tension to prevent phase separation, extend shelf stability, and control texture in commercial food production. Mono- and diglycerides occupy the largest share of product type demand, reflecting their cost efficiency and broad regulatory acceptance across baked goods and dairy alternatives. Polysorbates represent the fastest-expanding product category, driven by plant-based beverage formulations requiring robust emulsion stability. Within applications, meat substitutes command emerging margin pools as German food manufacturers reformulate texture systems for consumer acceptance.
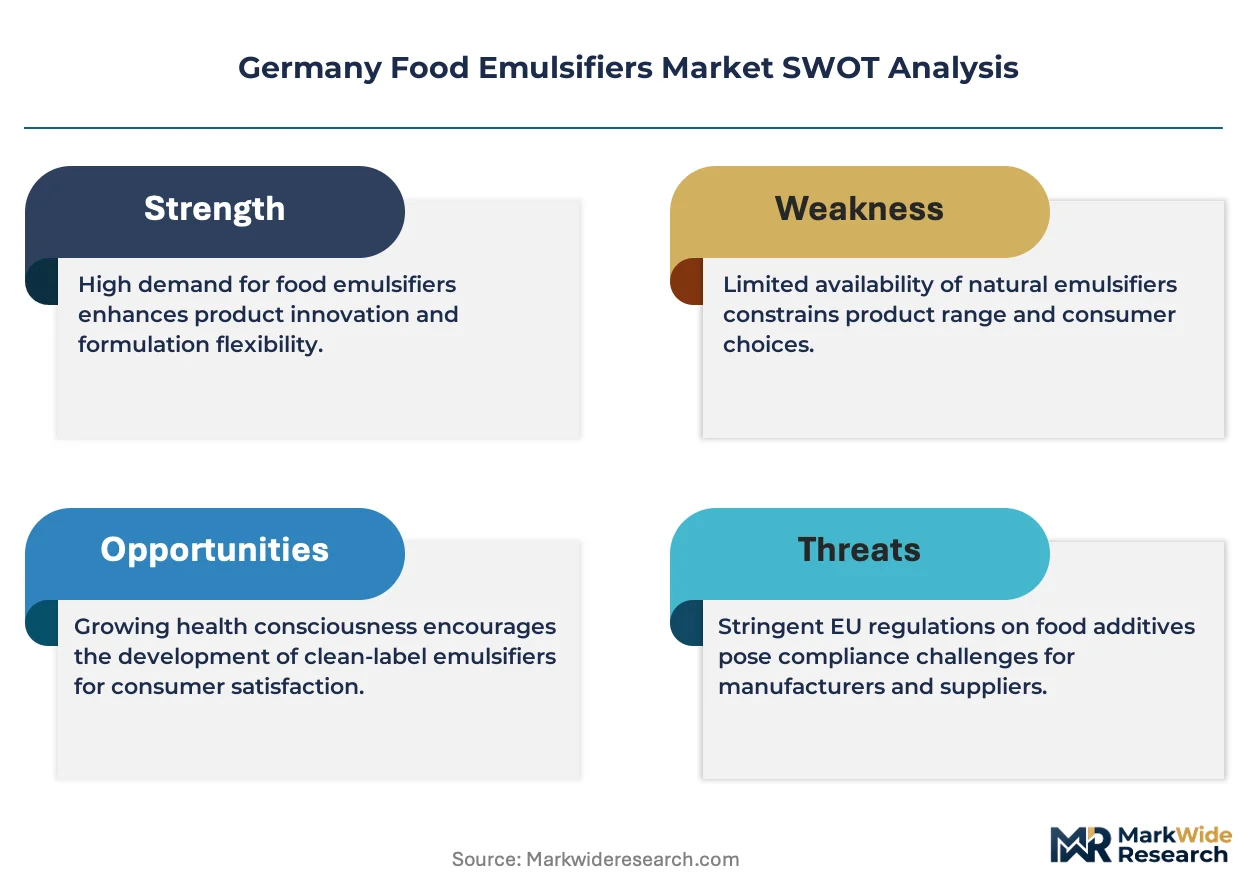
Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces additive purity standards under EU Regulation 1333/2008, while REACH compliance through ECHA governs chemical substance registration for imported emulsifier raw materials. KBA and state-level environmental agencies in Baden-Württemberg and Bavaria impose wastewater and emissions thresholds on production facilities, elevating capital requirements for new manufacturing entrants. Stakeholders must monitor evolving EU packaging sustainability rules and their downstream impact on bulk container specifications and logistics cost structures.
Market Dynamics
The EU Green Deal's sustainable sourcing mandates are compressing supplier qualification timelines across Bavaria's bakery clusters and Baden-Württemberg's plant-based dairy corridors, forcing manufacturers to revalidate emulsifier supply chains under stricter carbon-accounting protocols.
Growth Catalysts
- Clean-label reformulation mandates:Bakery operators in North Rhine-Westphalia are stripping synthetic additives from bread lines, pulling natural lecithin and mono-diglyceride demand upward.
- REACH compliance integration:ECHA registration requirements for imported raw materials are accelerating domestic production investments at Ludwigshafen chemical complexes.
- Plant-based beverage clustering:Stuttgart and Munich manufacturing corridors are concentrating oat and almond milk production, requiring polysorbate stabilization systems.
Market Restraints
- Sunflower lecithin supply concentration:Ukrainian and Russian seed oil disruptions have elevated input cost volatility for European emulsifier manufacturers.
- REACH registration timelines:ECHA's substance evaluation protocols extend raw material approval cycles to 18-24 months for novel emulsifier chemistries.
- Enzymatic emulsifier substitution:Lipase-modified phospholipids are displacing chemically processed alternatives in premium clean-label segments.
Strategic Opportunities
- Meat substitute texture systems:German food manufacturers are reformulating mycoprotein and pea-protein applications with tailored emulsifier blends for mouthfeel acceptance.
- EU packaging sustainability rules:Downcoming bulk container specifications favor regional logistics hubs over long-haul import routes.
- Enzyme-emulsifier convergence:Lipase-catalyzed esterification is enabling cold-process manufacturing with reduced energy intensity.
Industry Challenges
- Process chemist scarcity:Emulsifier synthesis expertise concentrates at legacy chemical engineering programs in Aachen and Karlsruhe, constraining new facility staffing.
- Legacy equipment retrofit costs:Batch reactor systems at older plants require capital-intensive upgrades to meet Baden-Württemberg emissions thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Emulsifiers Market |
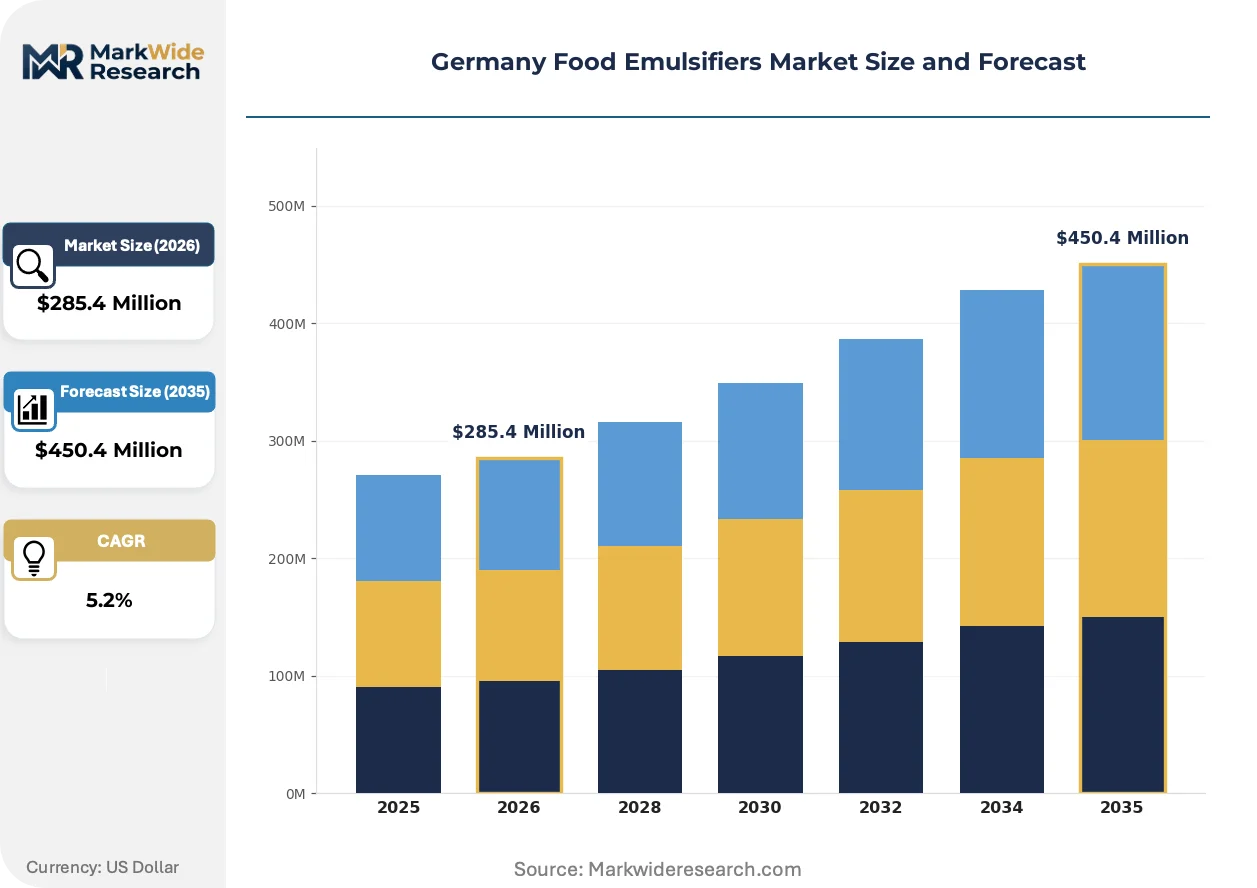
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- & Diglycerides, Polysorbates, Sorbitan Esters, Stearoyl Lactylates Application: Baked Goods, Dairy Alternatives, Confectionery, Dressings & Sauces, Meat Substitutes End User: Food Manufacturers, Ingredient Suppliers, Bakery Operators, Confectioners, Foodservice Providers Packaging Type: Bulk Containers, Paper Bags, Plastic Drums, Fiberboard Boxes, Intermediate Bulk Containers |
| Companies Covered | Cargill, Incorporated, BASF SE, The Archer Daniels Midland Company, Ingredion Incorporated, Lonza Group, DuPont de Nemours, Inc., Kerry Group, Corbion, Palsgaard A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Emulsifiers Market Shifts & Advancements
Clean-label emulsifier chemistry is migrating from synthetic esters toward enzymatically modified natural lipids, compressing formulation cycles across German food manufacturing.
Enzymatic interesterification is migrating from pilot-scale demonstration to commercial deployment at Stuttgart-area specialty lipid facilities. Bakery and confectionery manufacturers in southern Germany are adopting these processes at accelerated pace to meet retailer clean-label specifications. The technology is migrating from premium niche applications toward mass-market bread and pastry lines, eroding cost premiums for chemically processed alternatives.
EU Regulation 1333/2008 additive purity standards are tightening maximum residue limits for solvent-extracted lecithins. Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforcement actions have elevated testing costs for imported raw materials. Bakery segments sourcing from eastern European suppliers are most affected, accelerating qualification of domestic enzymatic processing alternatives.
Direct procurement relationships are displacing traditional distributor intermediaries among large-scale meat substitute manufacturers in Bavaria. Volume buyers are negotiating captive supply agreements with Ludwigshafen-based producers, compressing margins for Hamburg port logistics operators. This channel restructuring is most visible in plant-based dairy alternative verticals, where formulation confidentiality demands favor closed-loop supplier integration.
Germany Food Emulsifiers Market Segmentation
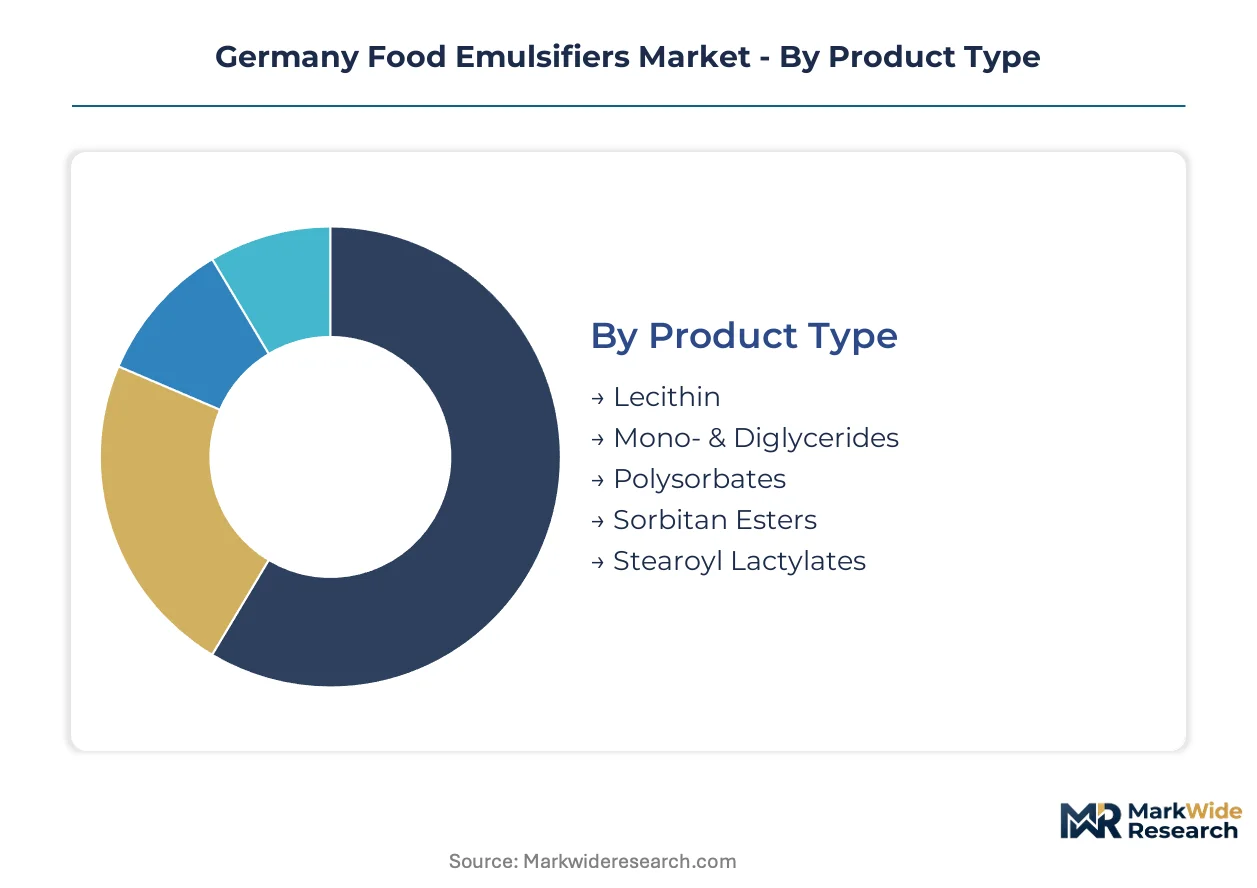
Emulsifier procurement patterns in Germany diverge sharply by product chemistry and end-use application, with bakery and plant-based dairy verticals driving divergent specification requirements. Understanding segment turnover velocity enables suppliers to align inventory positioning with demand cycles across Bavaria's manufacturing clusters and North Rhine-Westphalia's bakery networks.
Product Type:
Mono- and diglycerides turn inventory fastest through high-volume bakery channels, while specialty esters linger in longer qualification cycles for meat substitute applications.
- Lecithin:Phospholipid mixtures extracted from soybean or sunflower oils serve as the benchmark natural emulsifier for clean-label bakery reformulations. North Rhine-Westphalia bread manufacturers are stripping synthetic additives from product lines, pulling fluid and de-oiled lecithin grades upward.
- Mono- & Diglycerides:Glycerol esters of fatty acids dominate cost-sensitive applications through efficient interfacial tension reduction. Bavaria's industrial bakeries run these at high inclusion rates for extended shelf-life bread, though enzymatic alternatives are eroding share in premium positioning.
- Polysorbates:Ethoxylated sorbitan esters deliver superior emulsion stability for oat and almond milk formulations clustering around Stuttgart and Munich.
- Sorbitan Esters:Lipophilic surfactants stabilize water-in-oil systems for confectionery fat bloom control.
- Stearoyl Lactylates:Ionic emulsifiers strengthen gluten networks in yeast-raised baked goods.
Mono- and diglycerides dominate installed base. Polysorbates are where expansion concentrates.
Application:
Cost tiers separate commodity bakery applications from premium meat substitute texture engineering, with mid-tier dairy alternatives commanding blended margin profiles.
- Baked Goods:Industrial bread and pastry production consumes emulsifiers at highest volume intensity, with clean-label mandates accelerating natural lecithin substitution for synthetic esters across North Rhine-Westphalia operations.
- Dairy Alternatives:Plant-based beverage manufacturing around Stuttgart and Munich requires robust polysorbate systems for fat dispersion stability in extended shelf-life oat and almond milks.
- Confectionery:Chocolate and coating applications depend on lecithin for viscosity control and fat crystallization management.
- Dressings & Sauces:Mayonnaise and vinaigrette emulsions utilize mono-diglyceride and lecithin blends for freeze-thaw stability.
- Meat Substitutes:Mycoprotein and pea-protein reformulations in Bavaria deploy tailored emulsifier blends for mouthfeel acceptance and juiciness retention.
Baked goods anchor volume throughput. Meat substitutes capture the steepest expansion trajectory.
End User:
Customer scale determines specification control, with large food manufacturers dictating custom blends while bakery operators accept standard grades.
- Food Manufacturers:Integrated processors in Baden-Württemberg negotiate captive supply agreements for proprietary emulsifier systems, compressing distributor margins.
- Ingredient Suppliers:Regional distributors serve mid-tier accounts with stocked standard grades, facing margin pressure from direct procurement trends.
- Bakery Operators:North Rhine-Westphalia bread specialists are consolidating purchases around clean-label lecithin for retailer-compliant product lines.
- Confectioners:Chocolate processors specify de-oiled lecithin for viscosity-critical applications.
- Foodservice Providers:Institutional kitchens source pre-dispersed emulsifier systems for sauce and dressing preparation.
Food manufacturers dominate installed base. Bakery operators are where specification change concentrates.
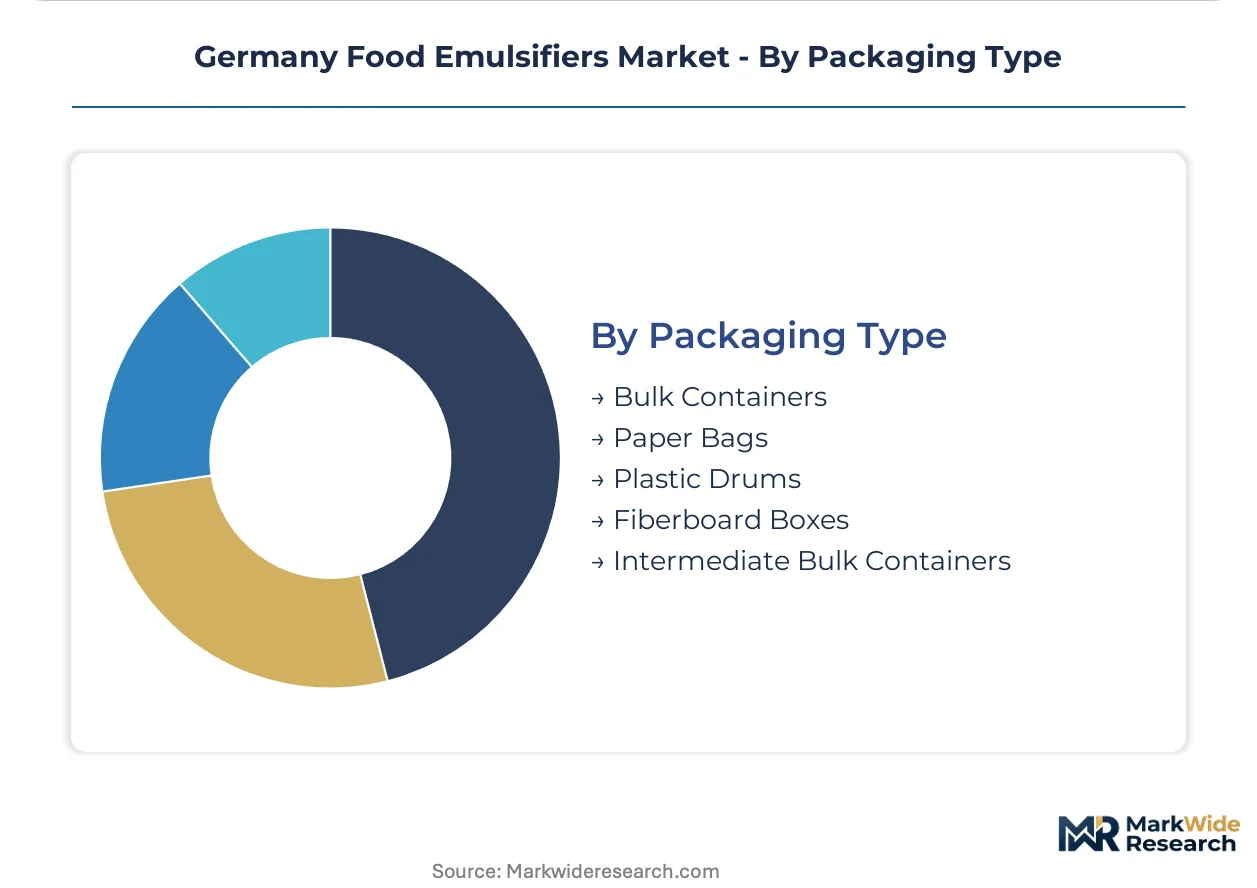
Packaging Type:
Sustainability mandates are reshaping container economics, with bulk formats gaining share against single-use packaging for high-volume accounts.
- Bulk Containers:Tank truck and railcar deliveries serve Ludwigshafen-area chemical complexes and large-scale food manufacturers with lowest unit logistics cost.
- Intermediate Bulk Containers:Reusable totes balance handling efficiency with reduced packaging waste for mid-volume dairy alternative processors.
- Paper Bags:Kraft multiwall constructions hold powder and granular lecithin for bakery ingredient distributors.
- Plastic Drums:Standard 200-liter formats serve small-batch confectionery and meat substitute manufacturers.
- Fiberboard Boxes:Corrugated containers with polyethylene liners protect moisture-sensitive specialty esters.
Bulk containers dominate installed base. Intermediate bulk containers are where sustainability-driven conversion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical manufacturing clusters in Ludwigshafen and Hamburg anchor domestic emulsifier supply, while Bavaria and Baden-Württemberg concentrate downstream food processing demand. Regional specialization splits between upstream synthesis corridors and downstream formulation hubs.
Bavaria
Meat substitute manufacturers in Munich and Ingolstadt drive specialty emulsifier procurement for mycoprotein and pea-protein texture systems. Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces additive purity standards under EU Regulation 1333/2008 across Bavarian food manufacturing. Nuremberg-area logistics hubs facilitate direct procurement relationships that bypass traditional distributor channels.
Baden-Württemberg
Plant-based beverage production around Stuttgart clusters oat and almond milk facilities requiring polysorbate stabilization. State-level environmental agencies impose wastewater and emissions thresholds on production facilities, elevating capital requirements for manufacturing entrants. Enzymatic interesterification facilities in the region migrate from pilot-scale to commercial deployment for clean-label bakery applications.
North Rhine-Westphalia
Industrial bakeries in Cologne and Düsseldorf strip synthetic additives from bread lines, accelerating natural lecithin substitution. KBA oversight intersects with EU Green Deal sustainable sourcing mandates, compressing supplier qualification timelines. The Ruhr Valley logistics network connects to Hamburg port infrastructure for imported raw material flows.
Lower Saxony
Confectionery processors in Hanover specify de-oiled lecithin for viscosity-critical chocolate applications. REACH compliance through ECHA governs chemical substance registration for imported emulsifier raw materials entering through Bremerhaven. Regional dairy alternative startups source intermediate bulk containers through sustainability-driven packaging conversions.
Hamburg
Port logistics operators face margin compression as volume buyers negotiate captive supply agreements with upstream producers. EU packaging sustainability rules reshape bulk container specifications for materials handling through the harbor complex. Cargill anchors European distribution networks through Hamburg's maritime infrastructure.
Germany Food Emulsifiers Market Competitive Landscape
Integrated chemical conglomerates and specialty ingredient formulators split the market between scale-driven synthesis and tailored application engineering. BASF SE leverages Ludwigshafen infrastructure for captive lecithin and ester output, while Kerry Group differentiates through meat substitute texture systems. Three archetypes dominate: petrochemical-integrated producers, food-specialist blenders, and regional distribution anchors. Capacity expansion and direct procurement relationships represent the dominant competitive vectors reshaping channel economics.
Among diversified chemical conglomerates, BASF SE occupies a position exemplifying petrochemical-integrated production architecture. Cargill, Incorporated anchors agricultural-originated supply chains through Hamburg port logistics infrastructure. Kerry Group represents the food-specialist formulator archetype with tailored blend capabilities. These three entities illustrate the strategic segmentation between upstream synthesis control, agricultural commodity flows, and downstream application engineering.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| The Archer Daniels Midland Company |
| Ingredion Incorporated |
| Lonza Group |
| DuPont de Nemours, Inc. |
| Kerry Group |
| Corbion |
| Palsgaard A/S |
| Others |
Supply & Pricing Matrix
Sunflower lecithin supply concentration in Ukrainian and Russian seed oil corridors determines both premium-to-economy pricing spreads and the geographic shape of German emulsifier procurement networks. This input dependency forces manufacturers to absorb volatility through tiered contract structures while repositioning logistics around Hamburg port alternatives.
Pricing Analysis
EU Regulation 1333/2008 dictates the pricing tier structure across enzymatic versus solvent-extracted lecithin grades. Three-tier pricing separates premium enzymatic grades for clean-label bakery from standard solvent-extracted alternatives and economy mono-diglyceride commodities. Price differentiation hinges on certification purity levels and volume scale commitments. Cost compression in standard grades is intensifying because sunflower oil supply disruptions have elevated input volatility. Small bakery operators in North Rhine-Westphalia exhibit highest price sensitivity, while integrated meat substitute manufacturers in Bavaria prioritize formulation performance over unit cost.
Supply Chain Analysis
Extended payment terms from Ludwigshafen-based producers are compressing distributor working capital cycles across Hamburg port intermediaries. Raw material sourcing draws from Ukrainian sunflower seed, Russian vegetable oil, and Brazilian soybean phospholipid corridors. Production rests on specialty ester chemical inputs and enzymatic catalyst supplies. Single-source vulnerability in Black Sea agricultural exports creates structural exposure to geopolitical disruption. Distribution runs through captive direct agreements with large food manufacturers, bypassing traditional wholesale channels for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Food Emulsifiers Market functions as a regulatory-moat arena where REACH compliance entrenchment and ECHA registration timelines create durable barriers against import competition.
For Market Incumbents: Entrench position through backward integration into enzymatic processing capacity at Baden-Württemberg facilities, neutralizing substitution threats from lipase-modified phospholipids. Deepen captive supply relationships with Bavarian meat substitute manufacturers to lock out distributor intermediaries. Prioritize certification investment for EU Green Deal carbon-accounting protocols ahead of supplier requalification waves. For New Entrants and Emerging Players: Build out enzymatic interesterification capabilities targeting mid-tier dairy alternative processors in Stuttgart corridors underserved by BASF and Cargill direct sales teams. White-space concentrates in clean-label polysorbate alternatives for oat milk applications requiring non-ethoxylated stabilization systems. Go-to-market should leverage sustainability credentials for EU packaging rules compliance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty formulators with captive R&D relationships. Long-term viability across the projection horizon hinges on enzymatic technology ownership rather than commodity ester assets. Target acquisition archetype: regional blenders with established Bundesamt für Verbraucherschutz und Lebensmittelsicherheit testing relationships. Signal to monitor: ECHA substance evaluation acceleration timelines for novel chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Baden-Württemberg facilities gain clean-label certification advantage under EU Regulation 1333/2008 tightening. |
| Backward Integration into Sunflower Lecithin | Domestic crushing capacity reduces Ukrainian supply disruption exposure for North Rhine-Westphalia bakeries. |
| Direct Procurement Channel Development | Bavarian meat substitute manufacturers bypass Hamburg distributors for formulation confidentiality protection. |
| REACH Registration Acceleration | ECHA compliance timelines compress competitive windows for imported raw material alternatives. |
| Sustainability Packaging Conversion | Intermediate bulk container adoption aligns with EU Green Deal logistics requirements for Stuttgart dairy alternatives. |
Research Methodology
Desk research of EU regulatory filings, Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforcement records, and ECHA substance registration databases preceded structured interviews with emulsifier plant managers, bakery procurement leads, meat substitute R&D directors, and Hamburg port logistics operators. Primary fieldwork combined with secondary validation from trade customs data and chemical industry association reports. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry segments.
Assumptions held fixed include REACH registration timeline stability and EU Green Deal implementation pace, while sunflower oil supply recovery trajectories and enzymatic technology cost curves were varied across scenarios. Segmentation dimensions encompassed product type chemistry, application vertical, end-user scale tier, and regional manufacturing cluster. CAGRs were derived from installation base expansion rates and substitution elasticity parameters. Forecast inputs incorporated clean-label reformulation mandates and polysorbate demand from plant-based beverage capacity buildouts.
Stress conditions across sunflower lecithin supply disruption severity, ECHA evaluation acceleration, and enzymatic process cost parity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and technology adoption curves. Macroeconomic contraction, trade policy disruption, or breakthrough enzymatic catalyst efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Egypt Food Preservatives Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
France Food Enzymes Market