
 Dairy Enzymes Market | 2026-2036
Dairy Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Enzymes Market Analysis
European enzyme producers is expanding fermentation capacity to capture premium dairy contract volumes. Novozymes A/S leverages its Copenhagen-based biotech infrastructure to supply protease and lactase formulations across Nordic dairy cooperatives. Chr. Hansen Holding A/S anchors its position through deep specialization in microbial rennet and coagulant cultures for artisan and industrial cheese makers.
Dairy enzymes are protein-based biocatalysts, typically operating at temperatures between 30°C and 55°C and pH ranges of 4.5 to 7.0, that accelerate specific biochemical reactions in milk processing such as protein hydrolysis, lactose conversion, and fat modification. Their primary commercial purpose centers on yield optimization, flavor development, and texture control across fermented and fresh dairy products. Proteases command the largest share of product-type revenue due to their indispensable role in cheese curd formation and whey protein hydrolysis. Lactases represent the fastest-expanding category as lactose-free milk and yogurt applications multiply across European and North American retail channels.
EMA food enzyme safety evaluations, REACH chemical registration requirements, and EU Green Deal carbon-intensity benchmarks collectively shape formulation standards and facility investment timelines for enzyme suppliers serving European dairy processors. FDA Generally Recognized as Safe determinations and USDA organic processing rules govern market access for imports into the United States. Stakeholders must monitor evolving regulatory convergence between microbial strain approval pathways and clean-label positioning requirements.
Market Dynamics
Precision fermentation scale-up is compressing enzyme production costs while EU carbon-intensity mandates force dairy processors to retrofit facilities for energy-efficient biocatalysis, creating a dual squeeze on supplier margins and processor capex cycles simultaneously.
Growth Catalysts
- Specialty cheese volumes:Artisan and premium cheese categories across Germany, France, and Italy are pulling higher-specification protease and lipase formulations from fermentation suppliers.
- REACH chemical registration:Streamlined microbial strain approval pathways under ECHA guidance are shortening time-to-market for novel enzyme formulations serving European dairy networks.
- Lactose-free dairy retail:Supermarket chains in Scandinavia and the Netherlands are expanding shelf space for hydrolyzed milk products, directly lifting lactase demand.
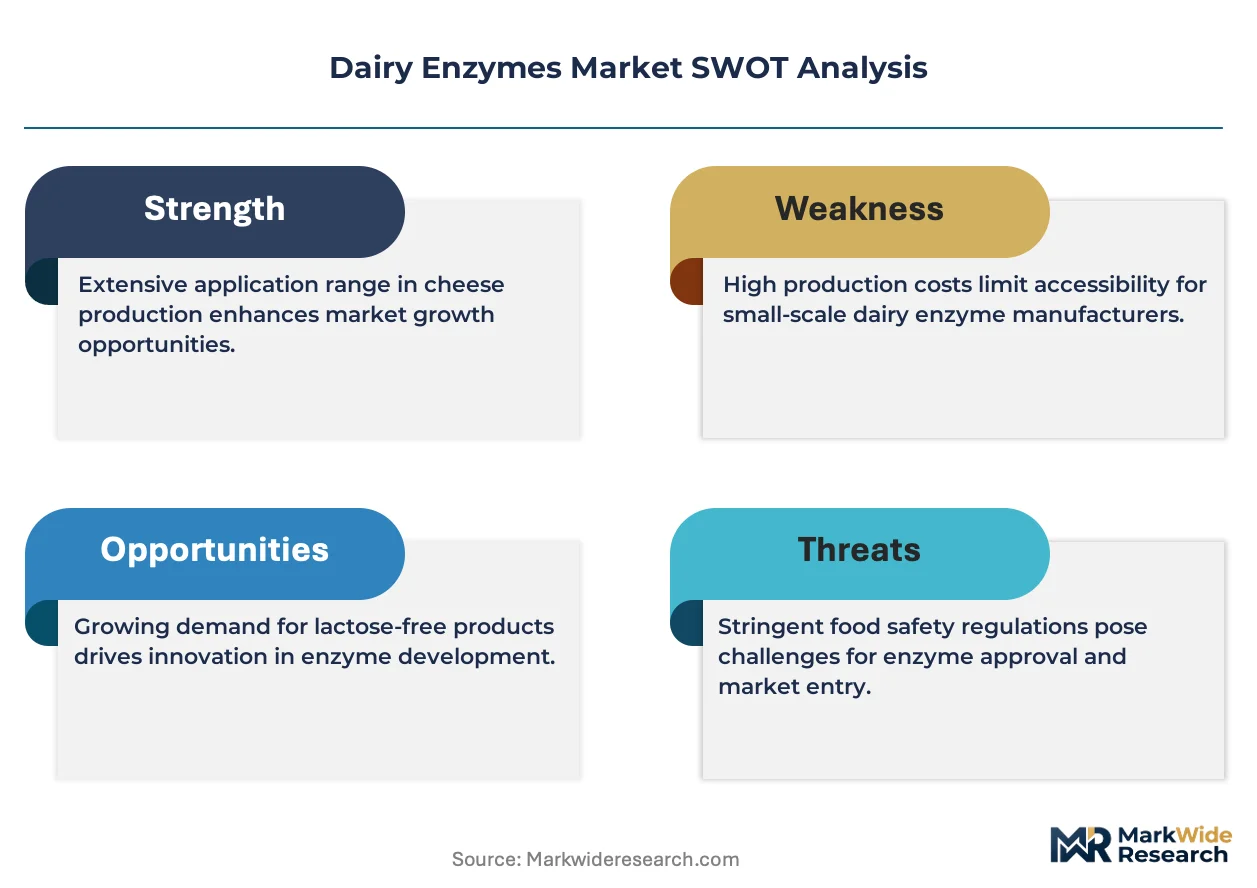
Market Restraints
- Fermentation feedstock volatility:Corn-derived glucose and yeast extract prices swing with agricultural commodity cycles, compressing gross margins for bulk enzyme manufacturers.
- Danish biotech cluster concentration:Copenhagen-based production facilities control disproportionate volumes of microbial rennet supply, creating geographic single-point vulnerability.
- Thermal stability limits:Existing protease formulations degrade above 55°C, restricting application in high-temperature whey processing lines without costly cooling infrastructure.
Strategic Opportunities
- Polish dairy processing expansion:Central European cooperatives are modernizing cheese facilities, opening contract volumes for enzyme suppliers with regional distribution footprints.
- EU Green Deal retrofit incentives:Carbon-intensity benchmarking grants for processor energy upgrades create bundled enzyme-system sales opportunities.
- Plant-based cheese analogues:Precision fermentation-derived enzymes are crossing into oat and almond protein texturization, opening non-dairy revenue streams.
Industry Challenges
- Microbial strain IP thickets:Patent landscaping around CRISPR-edited production organisms is lengthening freedom-to-operate assessments for new market entrants.
- EMA food enzyme dossier complexity:Toxicological study requirements for novel microbial sources are extending regulatory approval timelines beyond typical product development cycles.
- Legacy dairy equipment integration:Retrofitting continuous stirred-tank reactors for immobilized enzyme systems requires process engineering expertise scarce outside established supplier technical service teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Enzymes Market |
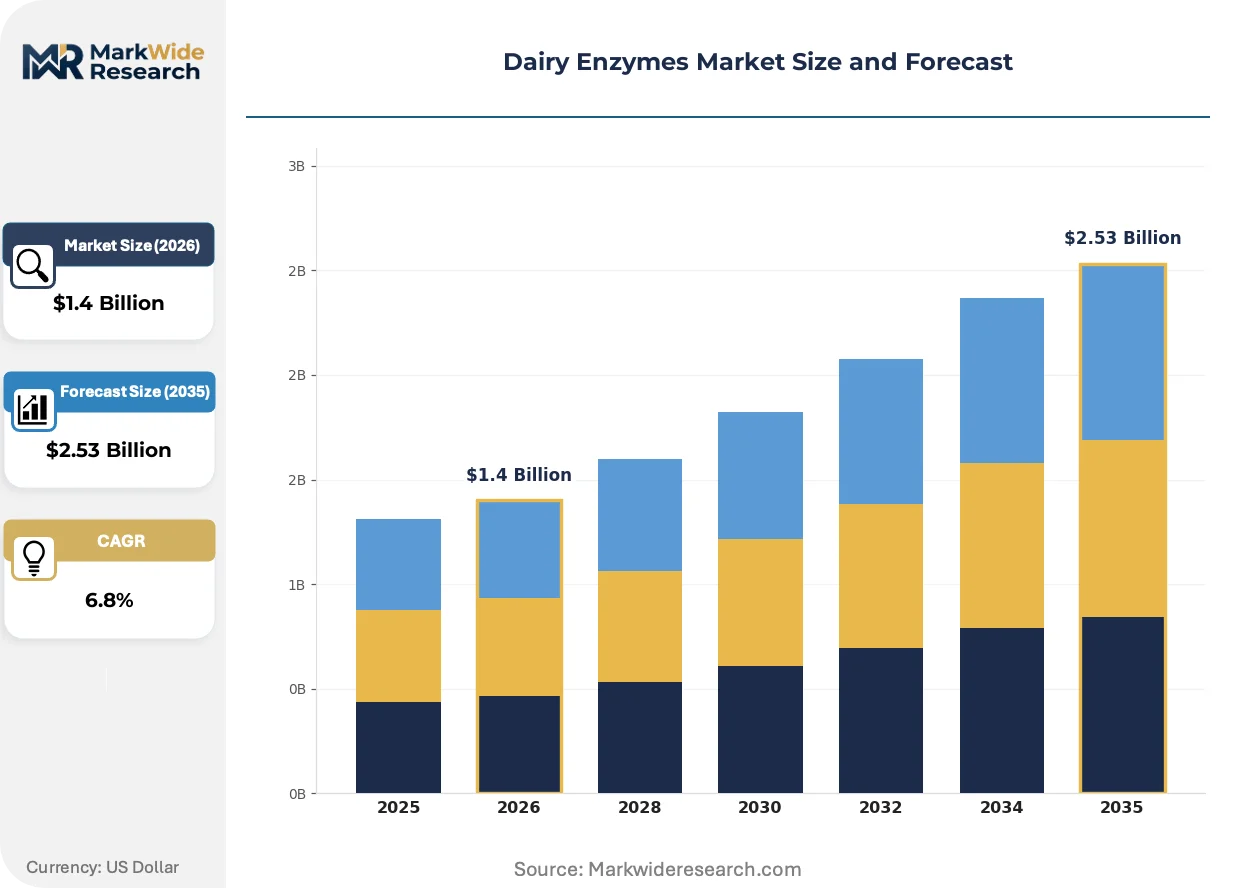
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Lactases, Lipases, Rennet Application: Cream Cheese, Yogurt, Ice Cream, Milk End User: Food Manufacturers, Retailers, Food Service Operators, Dairy Processors Delivery Mode: Liquid, Powder, Granulate, Tablet |
| Companies Covered | Novozymes A/S, Chr. Hansen Holding A/S, DSM, Kerry Group plc, Amano Enzyme Inc., Advanced Enzyme Technologies Ltd., DuPont de Nemours Inc, International Flavors & Fragrances Inc., Biocatalysts Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Enzymes Market Emerging Trajectories
Bioprocess intensification is reshaping how enzyme suppliers compete on cost and performance, with three converging developments altering investment priorities across fermentation infrastructure and customer technical service models.
Cell-free enzyme production is consolidating manufacturing economics by eliminating biomass separation steps and reducing downstream processing energy. Mid-scale dairy enzyme suppliers are adopting this platform to challenge bulk incumbents on lead times for custom protease blends. The technology is consolidating competitive position around fermentation yield rather than tank volume alone.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent enzyme storage facilities toward alternative cooling chemistries or ambient-stable formulation development. Dairy processors in Germany and the Netherlands face compressed retrofit timelines for cold-chain compliance. Smaller enzyme distributors without capital reserves are exiting temperature-sensitive product lines.
Direct procurement contracts between dairy cooperatives and fermentation specialists are displacing traditional distributor intermediaries in enzyme supply. Large Nordic dairy groups now negotiate multi-year protease and lactase supply agreements with technical service riders. This pattern concentrates most visibly in Denmark and Sweden where cooperative consolidation has reduced buyer fragmentation.
Dairy Enzymes Market Segmentation
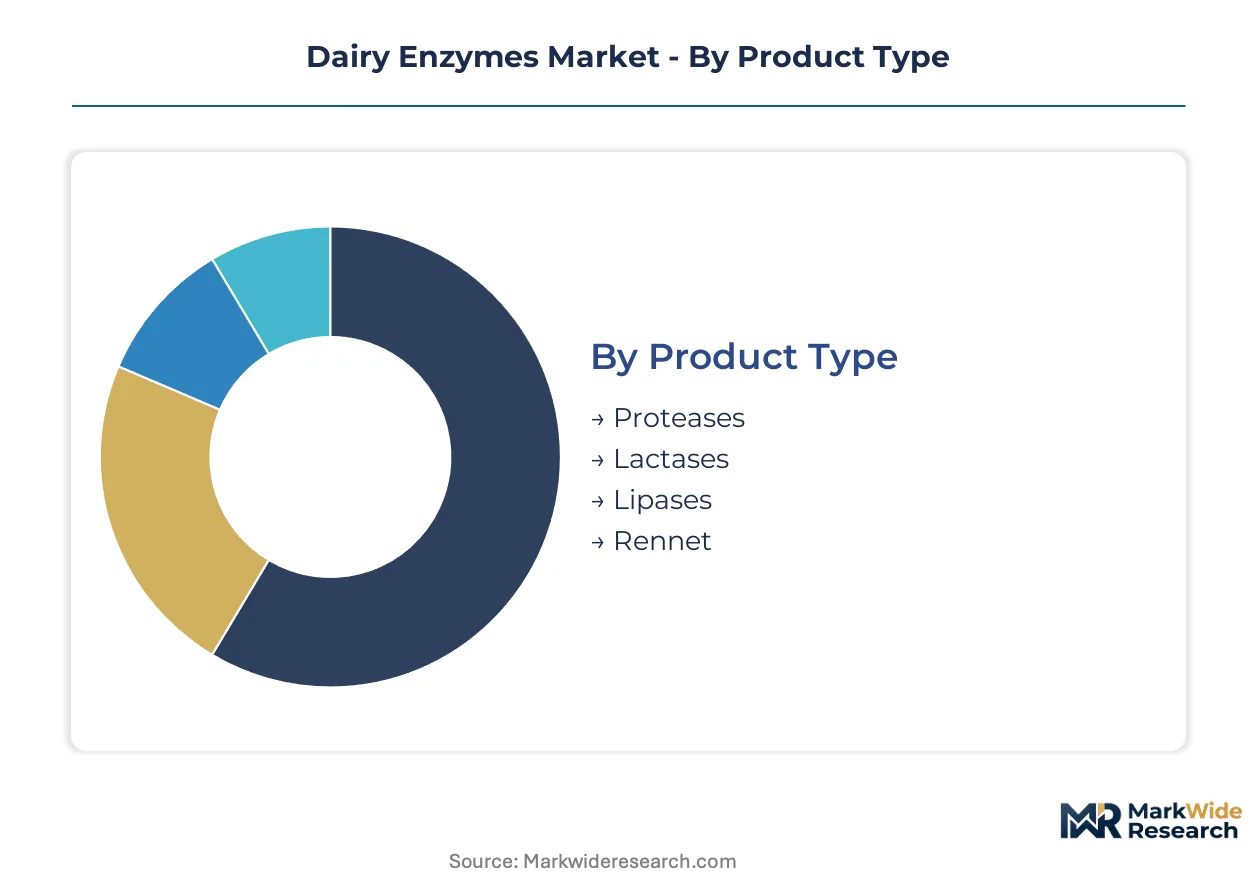
Dairy enzyme procurement patterns diverge sharply across product chemistry, application heat-load, and customer technical sophistication. Supply-side specialization and customer formulation requirements create natural segmentation boundaries that determine pricing power and contract stickiness for fermentation suppliers.
Product Type:
Supply concentration clusters around protease manufacturing, where Copenhagen-based fermentation infrastructure and Danish biotech IP portfolios create geographic lock-in for industrial-scale production.
- Proteases:These protein-hydrolyzing biocatalysts operate optimally between 35°C and 50°C with pH tolerance from 5.0 to 7.0. Specialty cheese production across Germany, France, and Italy pulls higher-specification formulations, with artisan makers demanding precise curd-setting kinetics that commodity suppliers cannot match.
- Lactases:Beta-galactosidase enzymes hydrolyze lactose into glucose and galactose for reduced-sugar dairy applications. Scandinavian and Dutch supermarket chains expanding hydrolyzed milk shelf space are concentrating demand, directly lifting fermentation capacity allocation toward lactase-dedicated bioreactors.
- Lipases:Fat-modifying enzymes catalyze triglyceride hydrolysis for flavor development in aged cheeses. Italian pecorino and French Roquefort makers specify lipase blends for controlled free fatty acid release.
- Rennet:Chymosin-based coagulants from microbial fermentation now dominate industrial cheese production, displacing traditional calf-sourced extraction.
Proteases absorb the bulk of installed capacity; lactases are expanding most quickly.
Application:
Cost tier differentiation separates commodity fluid milk processing from premium fermented applications requiring precise enzyme dosing and technical service support.
- Cream Cheese:High-fat, low-moisture formulations demand lipase-protease blends for texture stabilization. German dairy cooperatives operating continuous stirred-tank reactors specify immobilized enzyme systems to reduce downstream processing costs.
- Yogurt:Lactase pre-treatment enables reduced-lactose positioning for Scandinavian retail chains. Culture-enzyme synergy requirements create formulation complexity that favors suppliers with dairy culture portfolios.
- Ice Cream:Lipase-modified milk fats improve melt resistance and mouthfeel. Industrial producers in the Netherlands optimize overrun through controlled fat crystallization.
- Milk:Standard lactose hydrolysis for fluid milk represents volume-driven, price-sensitive procurement with minimal technical service attachment.
Cream cheese and yogurt applications command premium pricing; fluid milk processing operates at compressed margins with high volume throughput.
End User:
Customer type determines contract structure, with direct procurement displacing distributor intermediaries among large-scale buyers with in-house formulation expertise.
- Food Manufacturers:Multi-product dairy processors negotiate multi-year enzyme supply agreements with technical service riders, consolidating procurement around fewer fermentation specialists. Danish and Swedish cooperative consolidation has accelerated this pattern.
- Dairy Processors:Specialized cheese and ingredient facilities require custom protease blends with precise activity specifications. Polish cooperatives modernizing Central European facilities represent emerging contract volume.
- Food Service Operators:Institutional and QSR channels purchase pre-hydrolyzed dairy ingredients rather than direct enzyme procurement, placing them downstream of manufacturer processing decisions.
- Retailers:Private-label lactose-free milk programs drive indirect enzyme demand through contract manufacturer specifications rather than direct supplier relationships.
Food manufacturers and dairy processors dominate direct procurement; food service and retail channels participate through indirect demand.
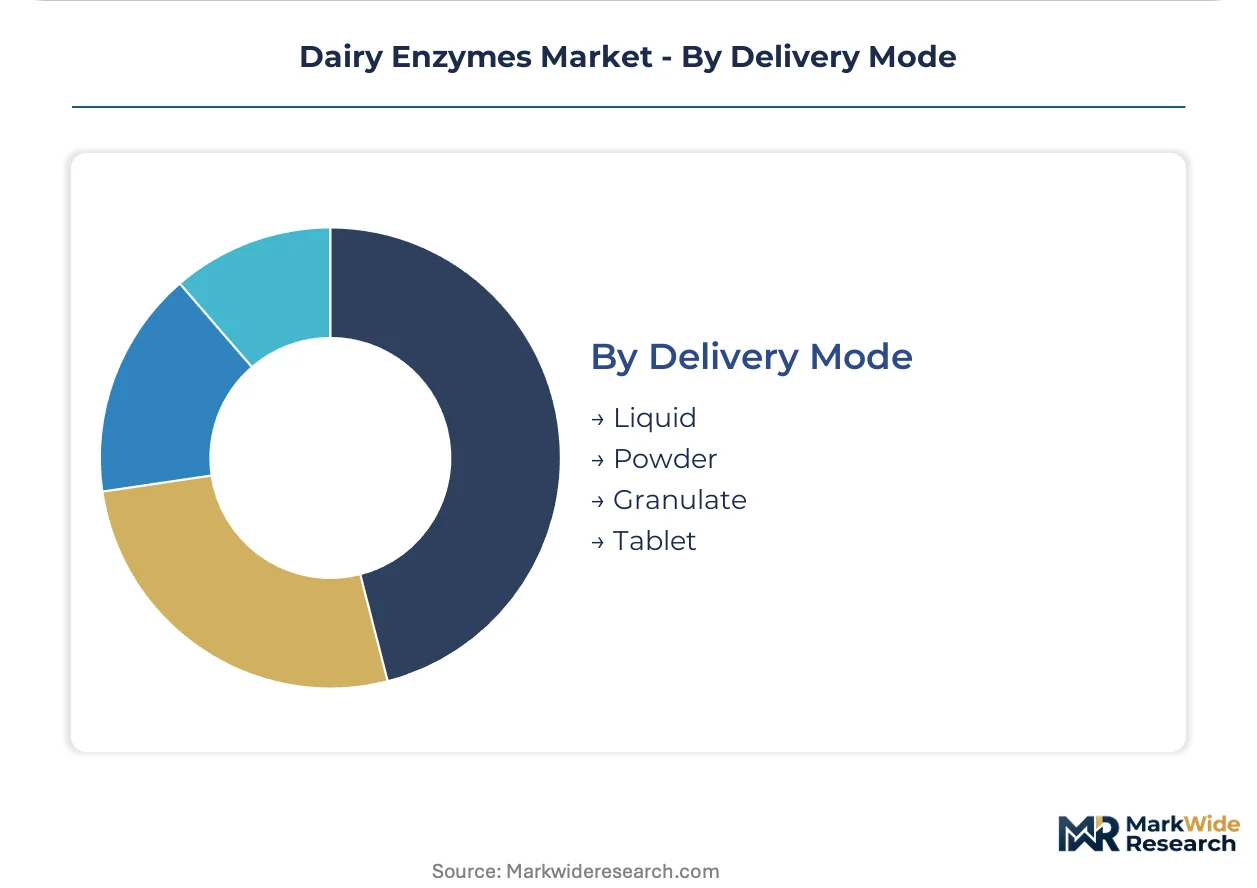
Delivery Mode:
Volume and margin profiles vary across physical form factors, with liquid formulations capturing continuous processing applications and dry forms serving distributed or seasonal operations.
- Liquid:Pumpable enzyme concentrates suit automated dosing in large-scale continuous processing. German precision fermentation clusters supply bulk liquid protease and lactase to automated dairy lines across Central Europe.
- Powder:Spray-dried formulations enable ambient-stable distribution to smaller processors lacking cold-chain infrastructure. Extended shelf life reduces inventory risk for seasonal cheese production.
- Granulate:Dust-free handling characteristics improve worker safety and dosing precision in open-system cheese vats. Artisan producers in France and Italy favor granulate for manual addition control.
- Tablet:Pre-measured unit doses simplify small-batch operations and educational dairy processing facilities where precise weighing infrastructure is absent.
Liquid delivery absorbs the majority of industrial volume; powder and granulate forms serve geographic and scale niches outside continuous processing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn-derived glucose and yeast extract feedstock networks anchor enzyme production geography across North America and Europe, with fermentation capacity clustering near agricultural processing corridors and dairy manufacturing belts.
Germany
Precision fermentation clusters in Bavaria and North Rhine-Westphalia supply protease and lactase formulations to Central European dairy networks. The EU F-Gas Regulation compresses retrofit timelines for cold-chain-dependent enzyme storage facilities. Munich-based biotech infrastructure serves automated dairy lines across the Rhine-Ruhr industrial corridor.
United States
FDA Generally Recognized as Safe determinations govern enzyme import pathways for lactose-free milk applications expanding through Midwest dairy cooperatives. USDA organic processing rules shape formulation standards for premium cheese manufacturers. Wisconsin and California dairy belts concentrate demand for industrial-scale protease contracts.
Denmark
Copenhagen-based microbial rennet production controls disproportionate supply volumes for Nordic and Baltic dairy cooperatives. EMA food enzyme safety evaluations streamline approval pathways for novel fermentation-derived formulations. The Øresund biotech cluster anchors technical service capabilities for artisan and industrial cheese makers.
Netherlands
Rotterdam-Antwerp logistics corridors enable bulk liquid enzyme distribution to continuous processing facilities across the Benelux dairy sector. REACH chemical registration requirements shape facility investment timelines for fermentation suppliers. Friesland and Gelderland cheese manufacturing zones pull higher-specification lipase blends for aged product categories.
France
Artisan cheese producers in Auvergne-Rhône-Alpes and Normandy specify precise curd-setting kinetics that commodity enzyme suppliers cannot match. EU Green Deal carbon-intensity benchmarks drive processor energy upgrade grants bundled with enzyme-system sales. Roquefort and Comté appellation zones concentrate demand for controlled free fatty acid release formulations.
Dairy Enzymes Market Vendor Landscape
Global majors compete with regional champions across fermentation scale and technical service depth, producing a tiered structure where Copenhagen-based biotech infrastructure commands industrial protease supply while mid-scale specialists challenge on custom blend lead times. Three archetypes dominate: bulk fermentation incumbents with tank-volume advantages, precision fermentation scale-ups leveraging cell-free production economics, and application-focused formulators bundling enzyme-culture synergies. Consolidation concentrates around multi-year supply agreements with technical service riders, while capacity expansion targets Central European dairy modernization cycles.
Among Danish biotech specialists, Novozymes A/S and Chr. Hansen Holding A/S exemplify the fermentation-infrastructure archetype, with corporate structures reflecting long-established public company governance. DSM and Kerry Group plc represent diversified nutrition-ingredient conglomerates competing through portfolio breadth rather than single-category dominance. These four entities anchor competitive positioning across industrial-scale supply contracts, though their specific strategic postures fall outside this analysis scope.
| Leading Market Players |
|---|
| Novozymes A/S |
| Chr. Hansen Holding A/S |
| DSM |
| Kerry Group plc |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies Ltd. |
| DuPont de Nemours Inc |
| International Flavors & Fragrances Inc. |
| Biocatalysts Ltd. |
| Others |
Supply Flow & Price Mechanics
Technical service bundling separates contract-locked protease supply from spot-market lactase procurement, with Danish fermentation clusters commanding premium pricing for multi-year agreements while commodity distributors compete on glucose feedstock pass-through costs. This bifurcation concentrates margin capture with Copenhagen-based incumbents and compresses intermediaries lacking cold-chain infrastructure or EMA dossier expertise.
Pricing Analysis
Service-bundling intensity defines competitive positioning, with multi-year protease contracts incorporating on-site technical support and culture-enzyme synergy consulting commanding substantial premiums over unbundled lactase spot purchases. Price differentiation rests on EMA food enzyme certification tier and fermentation yield guarantees, with artisan cheese makers in France and Italy showing lowest price sensitivity for precise curd-setting kinetics. Cost compression in bulk lactase supply is intensifying because precision fermentation scale-ups are eroding legacy tank-volume advantages. Fluid milk processors represent the most price-sensitive segment, procuring standardized hydrolysis enzymes through distributor channels with minimal formulation support.
Supply Chain Analysis
Refrigerated freight costs for liquid enzyme concentrates constrain distribution radius, favoring regional fermentation hubs over centralized global supply. Production gravity centers on Denmark, Germany, and the Netherlands, with Copenhagen-based facilities controlling microbial rennet volumes and Bavarian clusters serving Central European dairy networks. Raw material dependencies draw from corn-derived glucose, yeast extract, and specialized nitrogen sources anchored in agricultural processing corridors. Single-source vulnerability concentrates around Danish biotech infrastructure for industrial-scale protease supply. Distribution runs through direct procurement contracts between dairy cooperatives and fermentation specialists, displacing traditional distributor intermediaries in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA food enzyme safety evaluations and REACH chemical registration requirements construct a cost-of-compliance barrier that entrenches incumbent positions and extends regulatory approval timelines beyond typical product development cycles for unprepared entrants.
For Market Incumbents: To counter precision fermentation scale-ups eroding bulk enzyme margins, deepen captive supply of CRISPR-edited production organisms through backward integration into strain development capabilities, and expand technical service teams in Poland to capture Central European cooperative modernization contracts. For New Entrants and Emerging Players: Enter via cell-free enzyme production platforms targeting mid-scale custom protease blend demand from artisan cheese makers in Auvergne-Rhône-Alpes and Normandy, where specification complexity exceeds commodity supplier capabilities and direct technical relationships remain underdeveloped. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation scale-ups leveraging cell-free production economics given EU Green Deal retrofit incentives bundling enzyme-system sales with processor energy upgrades. Long-term viability favors acquisition targets with EMA-approved microbial strain portfolios and established technical service density in Germany or Denmark. The signal to watch is accelerating direct procurement contract signings between Nordic dairy cooperatives and fermentation specialists as an inflection indicator for distributor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive CRISPR-edited organism supply reduces licensing costs and accelerates novel formulation timelines. |
| Cell-Free Production Platform Deployment | Eliminates biomass separation steps, compressing lead times for custom protease blends serving artisan cheese makers. |
| Technical Service Expansion in Poland | Positions enzyme suppliers to capture contract volumes from modernizing Central European dairy cooperatives. |
| EU Green Deal Retrofit Bundling | Combines enzyme-system sales with carbon-intensity benchmarking grants, locking in multi-year processor relationships. |
| Direct Procurement Contract Negotiation | Displaces distributor intermediaries in Nordic markets, concentrating margin capture with fermentation specialists. |
Methodological Framework
Multi-period observation of fermentation capacity utilization, EMA food enzyme approval timelines, and dairy cooperative procurement patterns anchored the trend analysis, supplemented by interviews with fermentation plant managers, dairy processor procurement leads, enzyme distributor technical sales directors, and regulatory affairs specialists at EMA and ECHA. Secondary validation drew from REACH chemical registration databases, EU F-Gas Regulation implementation reports, SEC filings of listed biotech firms, and customs data on enzyme concentrate trade flows. Bottom-up triangulation across individual facility capacity announcements and top-down reconciliation against dairy processing volume forecasts ensured analytical consistency.
Input-output matrices modeled enzyme demand as a function of specialty cheese production volumes, lactose-free dairy retail shelf expansion, and EU carbon-intensity retrofit cycles across the projection horizon. Segmentation dimensions included product chemistry tier, application heat-load requirements, end-user technical sophistication, and delivery mode cold-chain dependency. CAGRs were derived from regression analysis of historical fermentation capacity expansion against dairy output growth, incorporating precision fermentation yield improvement curves and regulatory approval pipeline visibility. Industry-specific inputs encompassed glucose feedstock price volatility indices and F-Gas Regulation phase-down schedules affecting storage infrastructure investment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained agricultural commodity inflation or accelerated EMA toxicological study requirements for novel microbial sources. Forecasts reflect documented assumptions regarding precision fermentation scale-up rates and dairy cooperative consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Non-GMO Citric Acid Market