
 Brazil Feed Additives Market | 2026-2036
Brazil Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Feed Additives Market Outlook
Market Context with Strategic Players
Precision fermentation and enzyme engineering is rewriting formulation economics for Brazilian compound feed manufacturers. Cargill leverages its integrated grain-handling network to secure cost-advantaged substrate flows for additive production in the interior. Kemin Industries anchors its position through captive antioxidant manufacturing near São Paulo state poultry corridors. DSM-Firmenich specializes in methionine and vitamin premix combinations tailored to tropical heat-stress conditions.
Technical Definition and Structural Segments
Brazil feed additives comprise biologically active compounds—including crystalline amino acids, fat-soluble and water-soluble vitamin complexes, synthetic and natural antioxidant molecules, and exogenous enzyme preparations—that are incorporated into compound feeds at inclusion rates typically below one percent to modify nutritional availability, metabolic efficiency, or preservation stability. These inputs serve the primary commercial purpose of converting grain and oilseed meals into standardized animal protein outputs with predictable feed conversion ratios and controlled production cycle durations. Amino acids command the deepest margin pools among product types due to volume concentration in poultry and swine rations, while enzymes represent the fastest-expanding category as Brazilian producers adopt phytase and NSP-degrading formulations to reduce inorganic phosphate costs. Among end users, poultry producers sustain the largest absolute additive offtake, though aquaculture channels are gaining share as tilapia and shrimp intensification spreads across the Northeast.
Regulatory Framework and Forward Outlook
ANVISA and MAPA jointly govern feed additive safety assessments, with ANVISA evaluating novel ingredient toxicology and MAPA administering manufacturing facility inspections and product registration renewals under Normative Instruction regulations. These frameworks shape demand by determining which enzyme classes and probiotic strains achieve commercial clearance, directly constraining formulation options available to domestic premixers. Stakeholders must monitor pending revisions to antibiotic growth promoter restrictions, as regulatory shifts toward zinc oxide and copper sulfate limitations will force reformulation decisions across southern Brazil's integrated pork and poultry systems.
Market Dynamics
Precision fermentation and enzyme engineering is compressing formulation costs for Brazilian compound feed manufacturers, forcing incumbent suppliers to defend margin positions through captive manufacturing investments and geographic clustering near substrate sources.
Growth Catalysts
- MAPA Registration Acceleration:Compressed approval timelines for novel enzymes under updated Normative Instruction protocols are clearing commercial pathways for phytase and NSP-degrading formulations. Large-scale swine operations in Santa Catarina and Rio Grande do Sul are expanding enzyme adoption programs.
- Amino Acid Volume Concentration:Crystalline amino acids command the deepest margin pools due to volume concentration in poultry and swine rations. Commercial feedlots serving poultry integrators in Mato Grosso and Paraná are expanding supplementation programs.
- Aquaculture Intensification:Tilapia and shrimp farming spreads across Brazil's Northeast, creating new additive demand channels distinct from traditional poultry and swine concentrations.
Market Restraints
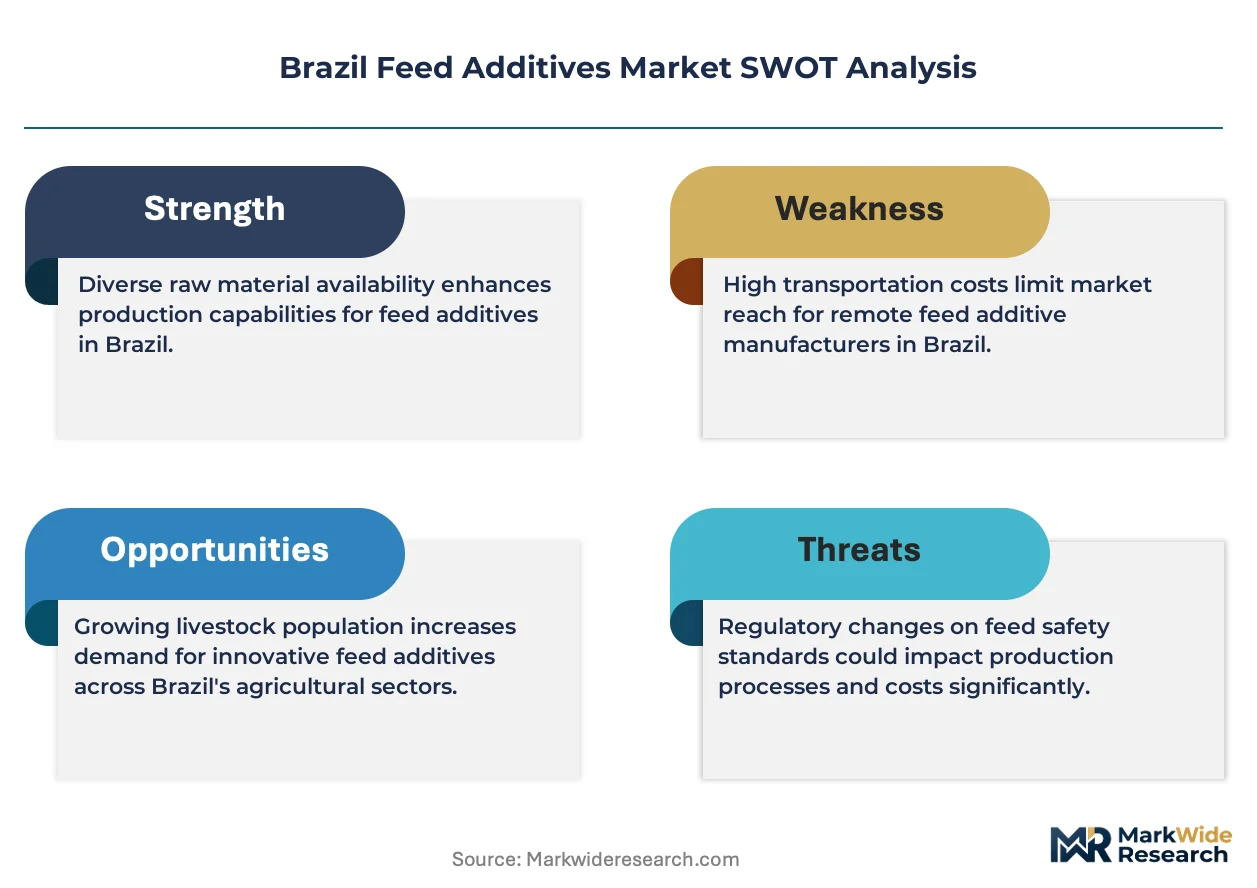
- Substrate Cost Volatility:Corn and soybean meal price swings directly compress additive inclusion economics for Brazilian compounders, forcing reformulation frequency that strains technical service relationships.
- ANVISA Toxicology Review Bottlenecks:Novel ingredient safety assessments create extended clearance timelines that delay commercial launch windows for probiotic strains and next-generation enzymes.
- Inorganic Phosphate Substitution Ceiling:Phytase adoption faces diminishing returns in certain diet formulations, limiting the cost-reduction runway for enzyme suppliers targeting layer and broiler operations.
Strategic Opportunities
- Northeast Aquaculture Corridors:Underpenetrated tilapia and shrimp production zones offer additive suppliers first-mover positioning before formulation standards crystallize.
- Antibiotic Growth Promoter Phase-Out:Pending MAPA restrictions on zinc oxide and copper sulfate will force integrated pork and poultry systems toward alternative gut health solutions.
- Precision Fermentation Convergence:Combining cell-culture platforms with traditional chemical synthesis is enabling novel antioxidant molecules with superior heat-stability profiles for tropical conditions.
Industry Challenges
- Enzyme Formulation Talent Scarcity:Brazilian universities produce insufficient graduates with dual competencies in microbiology and animal nutrition, forcing premixers to import technical staff or invest in extended training cycles.
- Legacy System Integration Friction:Digital feed formulation platforms require retrofitting into existing mill control systems, creating implementation delays and data interoperability failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Feed Additives Market |
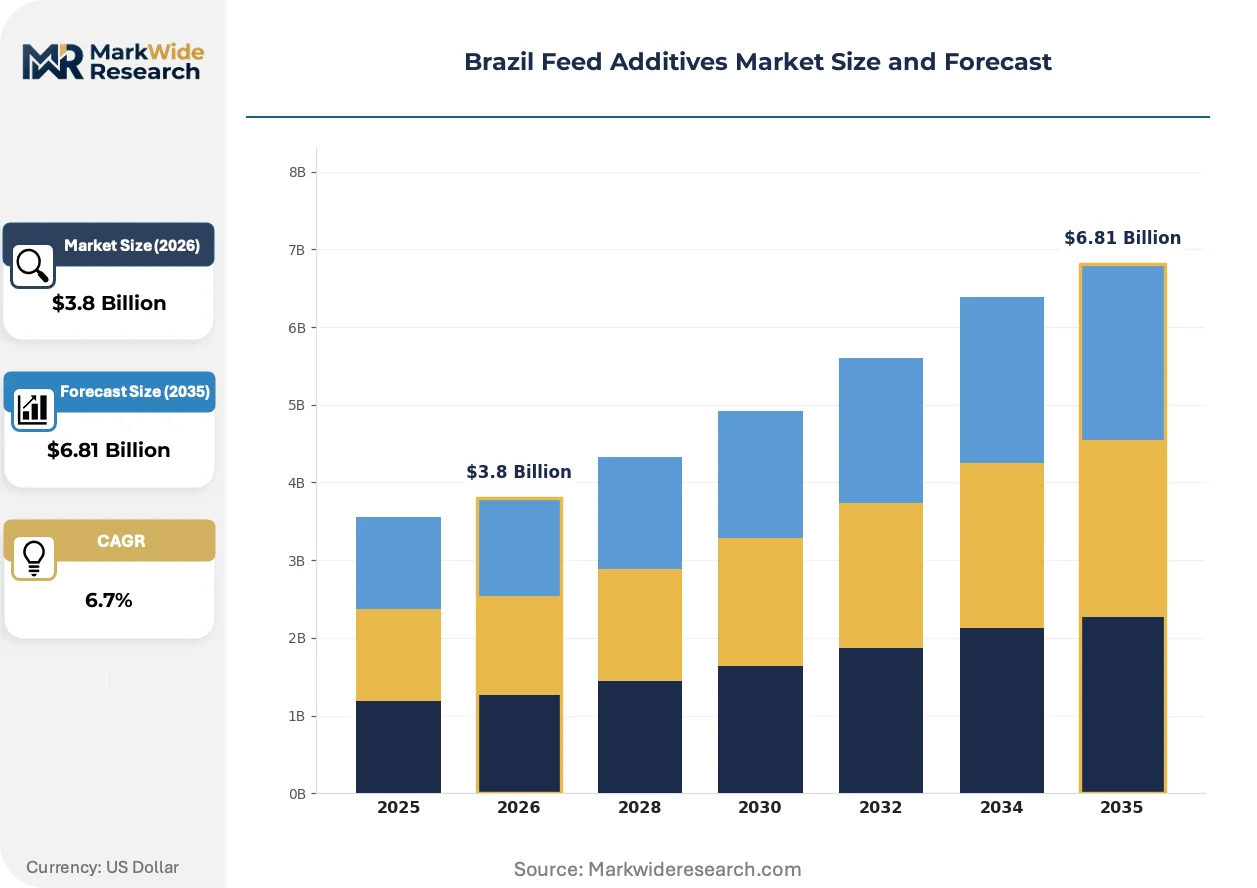
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Antioxidants, Enzymes End User: Poultry Producers, Swine Farmers, Aquaculture, Ruminant Feedlots Functionality: Nutrition Enhancement, Gut Health Improvement, Growth Promotion, Performance Optimization Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Adisseo, Nutreco, Cargill, Evonik Industries, BASF, Archer Daniels Midland, DSM-Firmenich, Kemin Industries, Alltech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Feed Additives Market Strategic Shifts
Biotechnology convergence and regulatory pressure on antibiotic alternatives are actively reshaping how Brazilian feed additive suppliers develop, register, and commercialize functional ingredients for protein production systems.
Precision fermentation is hybridizing traditional chemical synthesis routes for amino acid and antioxidant production. Poultry integrators in São Paulo state corridors are adopting these biologically derived inputs at accelerating rates. The technology is compressing capital requirements for domestic manufacturing while enabling substrate flexibility that insulates against grain price volatility.
ANVISA and MAPA joint oversight frameworks are tightening toxicology documentation requirements for novel probiotic strains entering commercial feed channels. Manufacturing facility inspections now emphasize contamination control protocols that exceed prior standards. Southern Brazil's integrated pork systems are responding by consolidating supplier relationships toward vertically integrated additive producers with established compliance infrastructures.
Buyer concentration among large-scale integrators is compressing switching cycles for premix and additive procurement. Traditional distributor networks serving independent feed mills are losing volume to direct manufacturer relationships. This pattern is most visible in the South-Central cluster, where Santa Catarina and Rio Grande do Sul operations are consolidating additive spend among three to four core suppliers with captive technical service teams.
Brazil Feed Additives Market Segmentation
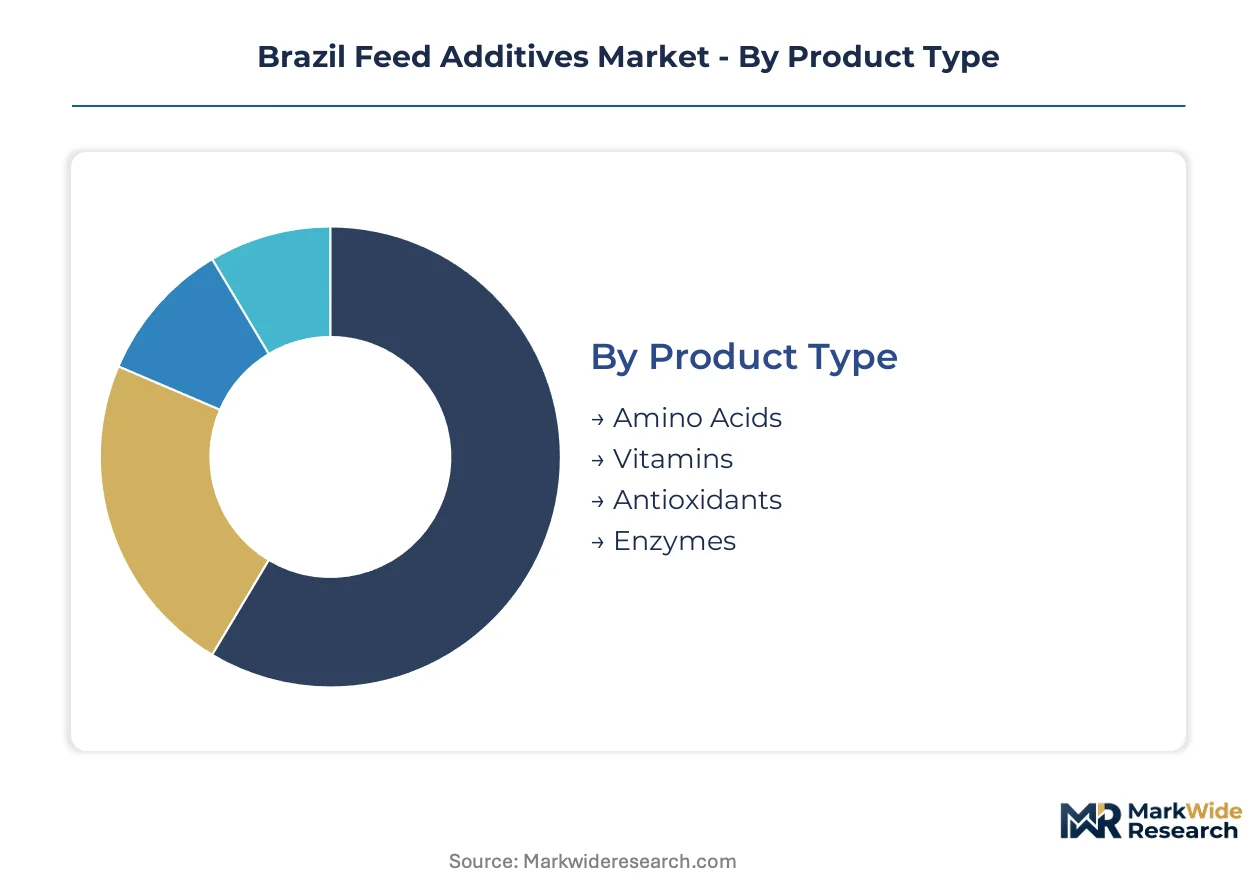
Segmentation reveals how Brazilian feed additive demand fragments across production systems with distinct formulation requirements and procurement behaviors. Understanding these divisions exposes where margin pools concentrate and which channels are capturing volume rotation.
Product Type:
Cost tier positioning separates commodity amino acids from premium enzyme formulations with divergent margin structures and technical service intensity.
- Amino Acids:Crystalline lysine, methionine, and threonine formulations dominate inclusion volumes in poultry and swine rations. Demand concentrates among commercial feedlots serving Mato Grosso and Paraná poultry integrators, where supplementation programs are expanding to optimize feed conversion ratios under tropical heat stress.
- Enzymes:Phytase and NSP-degrading preparations represent the fastest-expanding category as Brazilian producers seek to reduce inorganic phosphate costs. Large-scale swine operations in Santa Catarina and Rio Grande do Sul are accelerating adoption under MAPA's compressed approval timelines for novel enzyme registrations.
- Vitamins:Fat-soluble and water-soluble complexes stabilize nutritional availability across extended feed storage periods in humid climates.
- Antioxidants:Synthetic and natural molecules preserve feed integrity during high-temperature storage and transport through interior logistics corridors.
Amino Acids holds installed capacity. Enzymes is rotating up the share rankings.
End User:
Application focus determines formulation complexity, with integrated operations demanding customized premix services versus independent producers purchasing standard blends.
- Poultry Producers:Integrated broiler and layer systems sustain the largest absolute additive offtake through high-volume, low-margin procurement contracts. São Paulo state poultry corridors anchor antioxidant demand from Kemin Industries' captive manufacturing position.
- Swine Farmers:South-Central cluster operations spanning Santa Catarina and Rio Grande do Sul concentrate demand for amino acid and enzyme combinations. Zinc oxide and copper sulfate restriction pressures are forcing these systems toward alternative gut health solutions.
- Aquaculture:Tilapia and shrimp intensification across Brazil's Northeast creates distinct additive demand channels with formulation standards still crystallizing.
- Ruminant Feedlots:Beef cattle finishing operations in Center-West states utilize lower inclusion rate additives focused on ionophores and rumen modifiers.
Poultry Producers commands volume leadership. Aquaculture is climbing the fastest among end-use channels.
Functionality:
Customer type segmentation separates nutritional baseline inputs from performance-enhancing additives with differentiated regulatory scrutiny and pricing power.
- Nutrition Enhancement:Amino acid and vitamin premixes close dietary gap deficiencies in corn-soybean meal base rations. Precision fermentation is compressing production economics for these inputs across Brazilian compound feed manufacturers.
- Gut Health Improvement:Probiotic strains and organic acid blends address antibiotic growth promoter phase-out requirements. ANVISA toxicology review bottlenecks constrain commercial clearance timelines for novel microbial ingredients.
- Growth Promotion:Traditional performance enhancers face pending MAPA restrictions on mineral-based alternatives, forcing reformulation decisions.
- Performance Optimization:Enzyme-driven digestibility improvements and metabolic efficiency modifiers target feed conversion ratio compression in high-density production systems.
Nutrition Enhancement holds installed capacity. Gut Health Improvement is rotating up the share rankings.
Distribution Channel:
Supply concentration patterns reveal how buyer consolidation among large-scale integrators is restructuring channel economics and technical service delivery models.
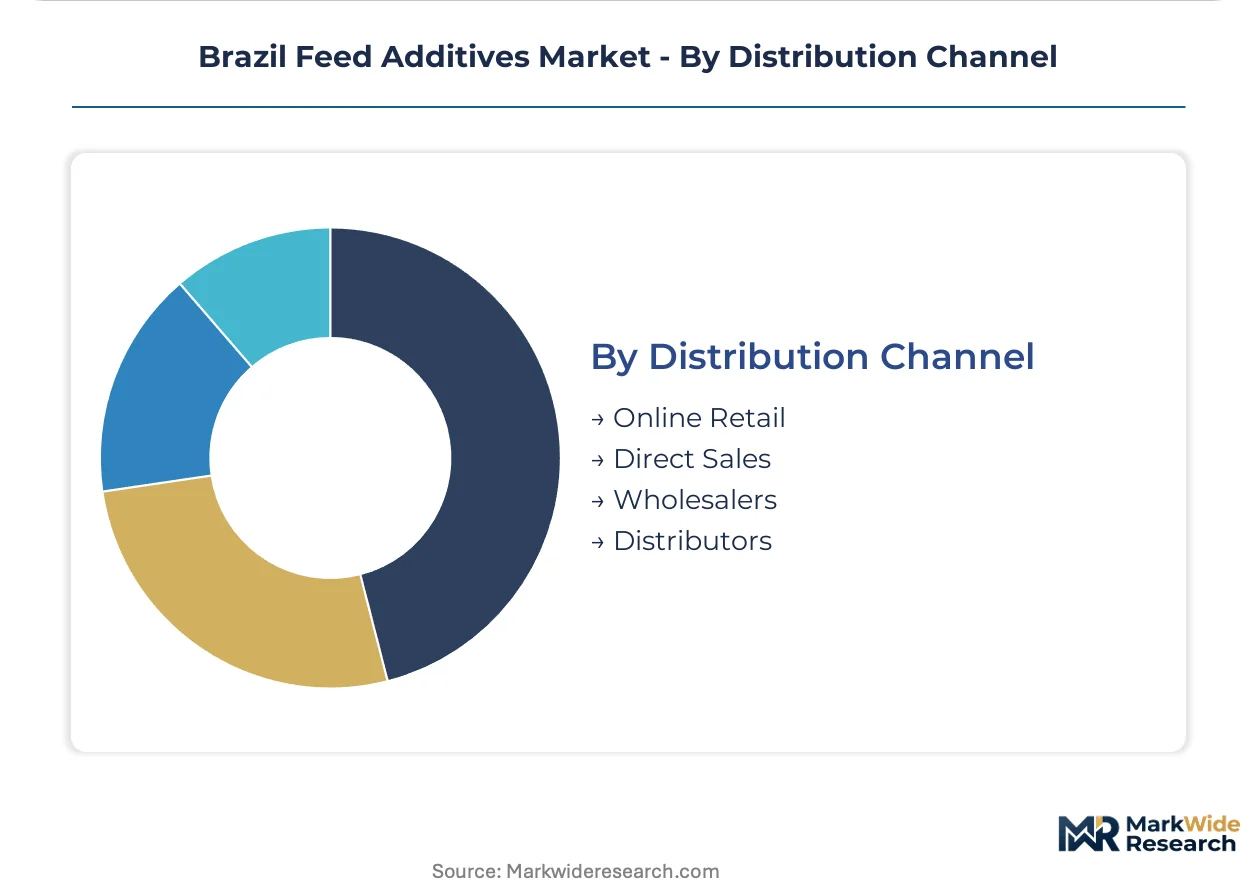
- Direct Sales:Manufacturer-integrator relationships are displacing traditional distributor networks as Santa Catarina and Rio Grande do Sul operations consolidate additive spend among core suppliers with captive technical service teams.
- Distributors:Regional premixers and independent feed mills in interior states maintain reliance on established distribution infrastructure for smaller volume procurement.
- Wholesalers:Bulk commodity amino acids flow through agricultural supply cooperatives serving independent livestock producers.
- Online Retail:Digital procurement platforms are gaining traction among mid-scale operations seeking price transparency and reduced order cycle times.
Direct Sales holds installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale integrators in Brazil's South-Central cluster command the deepest additive procurement volumes, while emerging aquaculture zones in the Northeast attract first-mover positioning from premix suppliers.
São Paulo
Poultry integrators along São Paulo state corridors drive antioxidant demand through high-density broiler and layer operations. ANVISA toxicology documentation requirements shape which novel probiotic strains achieve commercial clearance. Kemin Industries anchors its position through captive manufacturing near these poultry production zones.
Santa Catarina
Large-scale swine operations concentrate amino acid and enzyme demand as producers seek feed conversion optimization. MAPA's compressed approval timelines for novel enzyme registrations accelerate phytase adoption programs. Zinc oxide and copper sulfate restriction pressures force these systems toward alternative gut health solutions.
Rio Grande do Sul
Integrated pork systems sustain deep additive offtake through direct manufacturer relationships displacing traditional distributor networks. ANVISA and MAPA joint facility inspections emphasize contamination control protocols exceeding prior standards. Buyer consolidation compresses switching cycles among three to four core suppliers with captive technical service teams.
Paraná
Commercial feedlots serving poultry integrators expand crystalline amino acid supplementation programs to optimize tropical heat-stress performance. MAPA updated feed ingredient registration protocols compress approval timelines for domestic premixers. Mato Grosso-Paraná logistics corridors enable cost-advantaged substrate flows for additive production.
Bahia
Tilapia and shrimp intensification creates distinct additive demand channels with formulation standards still crystallizing. Northeast aquaculture corridors offer underpenetrated positioning before technical specifications harden. Digital procurement platforms gain traction among mid-scale operations seeking price transparency.
Brazil Feed Additives Market Competitive Environment
Channel-controlling players compete with product-specialist players across Brazil's feed additive landscape. The market structure tilts toward consolidation among vertically integrated grain handlers and captive premix manufacturers, while enzyme and probiotic niches retain specialist fragmentation. Two archetypes dominate: substrate-integrated multinationals leveraging grain-handling networks, and technology-focused specialists concentrating precision fermentation capabilities. Competitive moves center on backward integration into substrate sourcing and geographic clustering near poultry and swine production corridors.
Within the substrate-integrated tier, Cargill and Archer Daniels Midland exemplify channel-control strategies through grain-handling infrastructure. DSM-Firmenich occupies a position representing technology-specialist archetypes with methionine and vitamin premix combinations. These three companies anchor distinct competitive vectors—one through upstream agricultural asset control, another through biochemical synthesis capabilities—while MAPA registration protocols and ANVISA safety assessments constrain which formulation innovations achieve commercial scale.
| Leading Market Players |
|---|
| Adisseo |
| Nutreco |
| Cargill |
| Evonik Industries |
| BASF |
| Archer Daniels Midland |
| DSM-Firmenich |
| Kemin Industries |
| Alltech |
| Others |
Value Chain & Pricing Dynamics
Mato Grosso-Paraná logistics corridors transmit freight cost volatility directly into additive pricing power, concentrating margin capture among substrate-integrated multinationals while forcing independent premixers toward price differentiation through technical service bundling.
Pricing Analysis
Cost-plus contracts indexed to CBOT corn and soybean meal futures dominate amino acid procurement between integrated poultry operators and compound feed manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates DSM-Firmenich's heat-stability-certified methionine formulations from commodity lysine and unbranded antioxidant blends. Pricing pressure stems from MAPA's compressed enzyme approval timelines accelerating phytase commoditization. Independent feed mills in interior states exhibit highest price sensitivity, while Santa Catarina swine integrators prioritize feed conversion performance over unit cost.
Supply Chain Analysis
Upstream fermentation feedstocks draw from Argentina's corn surplus, Iowa's dextrose streams, and domestic Brazilian molasses corridors for yeast-derived additives. Crystalline amino acid production hinges on natural gas derivatives and corn steep liquor, while enzyme manufacturing rests on fungal and bacterial strain libraries held by technology-specialist firms. Single-source vulnerability concentrates in phytase active ingredient supply from Danish and Chinese biotech platforms. Distribution runs through Cargill's captive grain-handling network for bulk amino acids, with direct manufacturer relationships displacing regional distributors for enzyme premixes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's feed additive market functions as a service-attach opportunity where technical formulation consulting and on-farm feed conversion optimization expand faster than commodity ingredient volumes.
For Market Incumbents: Build regulatory compliance moats through preemptive ANVISA toxicology documentation investments ahead of probiotic strain commercialization waves. Defensive consolidation should prioritize backward integration into São Paulo-state antioxidant manufacturing and captive technical service team deployment across Santa Catarina swine corridors. Substitute technology threats from precision fermentation platforms demand accelerated enzyme engineering R&D partnerships. For New Entrants and Emerging Players: Bahia's tilapia and shrimp aquaculture zones offer formulation standardization gaps before incumbent technical specifications crystallize. White-space targets include Northeast digital procurement platforms for mid-scale operations and heat-stability-optimized vitamin premixes for tropical storage conditions. Go-to-market positioning should leverage direct online channels with transparent pricing to bypass distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational grain traders seeking to monetize captive additive divisions lacking biochemical synthesis depth. Long-term viability centers on precision fermentation convergence capabilities and MAPA registration expertise. The inflection signal to monitor is antibiotic growth promoter restriction implementation accelerating gut health additive demand.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Cell-culture platforms enable novel antioxidant molecules with superior tropical heat-stability profiles. |
| MAPA Registration Acceleration | Compressed approval timelines for phytase and NSP-degrading enzymes clear commercial pathways ahead of competitors. |
| Northeast Aquaculture Technical Service Deployment | Early formulation standardization in Bahia tilapia corridors captures volume before specifications harden. |
| Direct Manufacturer-Integrator Relationships | Bypassing distributor networks in Rio Grande do Sul consolidates additive spend among core suppliers. |
| Antibiotic Alternative Gut Health Portfolio | Pending zinc oxide and copper sulfate restrictions force integrated pork systems toward probiotic and organic acid solutions. |
Study Parameters
Initial hypotheses were tested against primary input from compound feed plant managers, poultry integration nutritionists, MAPA regulatory affairs officers, and enzyme platform R&D directors and refined through secondary validation against ANVISA registration databases, MAPA Normative Instruction filings, customs trade flow records, and SEC disclosures from listed grain traders. Bottom-up volume modeling across amino acid, enzyme, vitamin, and antioxidant product categories triangulated with top-down market sizing from feed production statistics.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user species concentration, functionality category, and distribution channel structure. CAGRs were derived from regression analysis of historical feed additive inclusion rate trends and forward projection of MAPA regulatory approval velocity. Industry-specific inputs incorporated phytase adoption curves in Santa Catarina swine operations and aquaculture intensification rates across Northeast coastal zones.
Practitioners should monitor MAPA antibiotic restriction implementation schedules and ANVISA probiotic toxicology review bottlenecks for early signals of demand inflection. Forecasts reflect assumptions regarding continued precision fermentation cost compression and sustained grain price volatility. Quarterly review of enzyme registration approval timelines and integrated poultry operator capital expenditure disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market