
 Food Grade Glycerin Market | 2026-2036
Food Grade Glycerin Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Glycerin Market Analysis
Beverage formulation is expanding as the fastest-rising end-use vertical for food grade glycerin, displacing traditional sweetener and preservative systems in functional drinks. Cargill Incorporated leverages its agricultural supply chain to secure cost-advantaged vegetable oil feedstocks for glycerin extraction. Wilmar International Ltd anchors Asia-Pacific production capacity through integrated palm oil refining complexes. Emery Oleochemicals specializes in oleochemical-derived glycerin with certified kosher and halal standards for global food access.
Food grade glycerin is a purified polyol compound, typically containing minimum 99.5% glycerol content by weight, manufactured through hydrolysis or transesterification of vegetable oils or animal fats, functioning primarily as a humectant, solvent, and sweetening agent in edible formulations. Refined glycerin commands premium positioning due to stringent impurity thresholds required by pharmaceutical-overlapping food safety protocols. Organic glycerin captures expanding shelf space as clean-label bakery and dairy processors reject petrochemical-derived alternatives. The beverage application segment is accelerating fastest, driven by low-glycemic-index positioning in sports and functional drink formulations.
The FDA maintains purity specifications under 21 CFR for direct food additives, while the EPA monitors glycerin manufacturing effluent under Clean Water Act provisions for oleochemical plants. EFSA and REACH collectively enforce contaminant limits and registration transparency for glycerin imported into European food supply chains. Stakeholders must monitor evolving bio-based content certification schemes and feedstock traceability mandates that will determine supplier qualification and procurement channel selection.
Market Dynamics
Beverage manufacturers are forcing glycerin procurement into pharmaceutical-grade purity tiers as clean-label positioning collides with humectant functionality requirements. This structural pressure is compressing the acceptable supplier base while elevating formulation-grade premiums.
Growth Catalysts
- EU Green Deal purity mandates:The EU Green Deal and F-Gas Regulation are tightening contaminant thresholds for bio-based glycerin, disqualifying marginal producers and concentrating procurement among certified refiners.
- Bakery moisture retention specifications:Confectionery and bread manufacturers are expanding glycerin volumes for texture stabilization in reduced-fat formulations.
- Germany ingredient cluster concentration:Food-grade glycerin demand is concentrating around Düsseldorf and Hamburg bio-chemical R&D hubs where formulation-grade buyers co-locate.
Market Restraints
- Vegetable oil feedstock volatility:Palm and soybean oil price swings transmit directly into glycerin production economics, compressing refiner margins during commodity spikes.
- Supply concentration in Southeast Asian oleochemical complexes:Integrated palm oil refiners control disproportionate global food-grade glycerin capacity, creating single-source vulnerability for European and North American buyers.
- Propylene glycol substitution in beverage systems:Synthetic humectants retain cost advantages in price-sensitive drink categories, capping glycerin penetration in mainstream soft drinks.
Strategic Opportunities
- Organic certification white space:Clean-label dairy and artisan bakery processors are rejecting petrochemical-derived glycerin, opening premium positioning for certified organic vegetable oil feedstocks.
- Sports drink formulation expansion:Low-glycemic-index positioning in functional beverages is displacing traditional sweetener systems with glycerin-based alternatives.
- REACH registration transparency as competitive moat:ECHA documentation requirements are raising barriers for unregistered Asian exporters, advantaging compliant European and North American refiners.
Industry Challenges
- Kosher and halal certification complexity:Multi-standard compliance for global food access requires parallel audit streams and extended qualification timelines for new production facilities.
- Hydrolysis-to-transesterification process switching:Refiners face capital intensity in upgrading from legacy batch systems to continuous processing for pharmaceutical-overlapping purity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Glycerin Market |
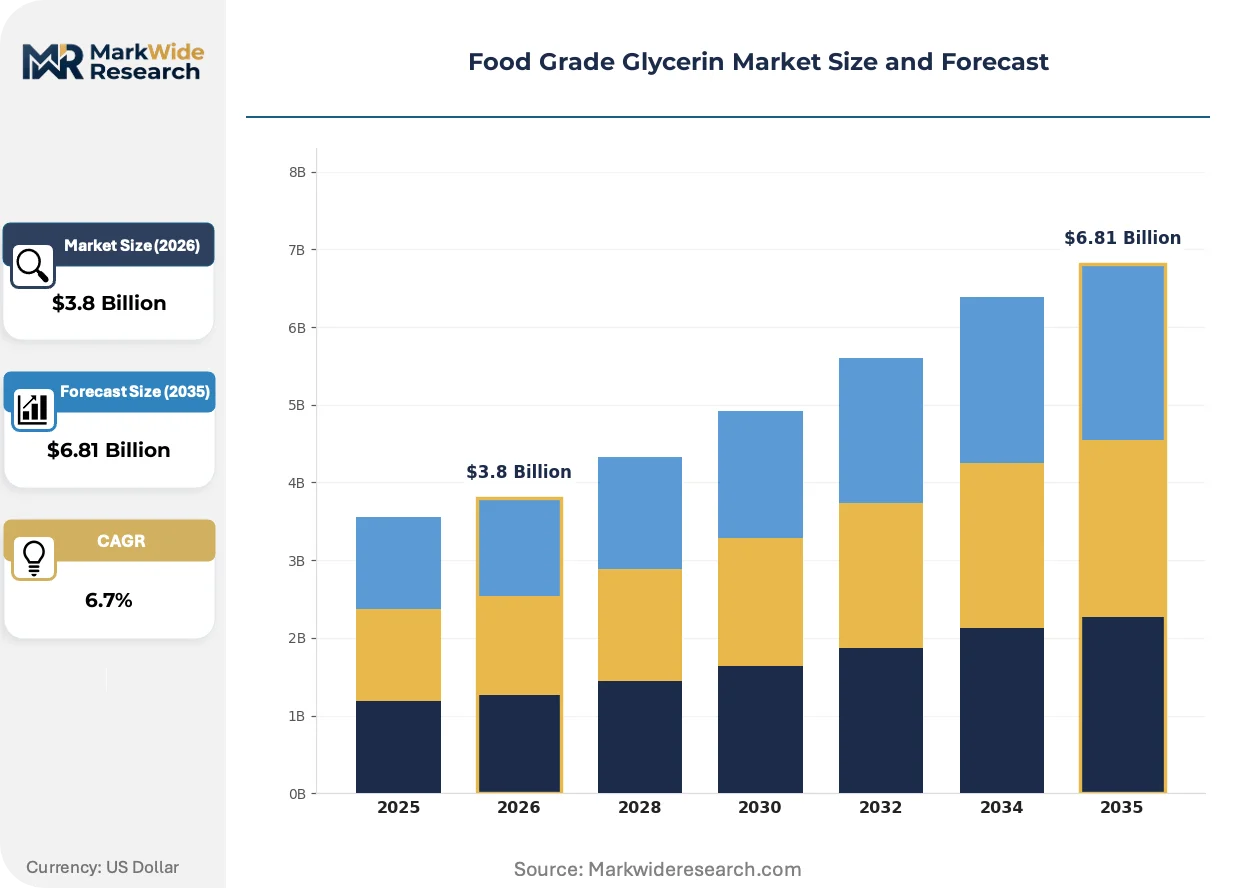
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-GMO, Organic, Crude, Refined Application: Bakery, Confectionery, Beverages, Dairy End User: Food Manufacturers, Beverage Producers, Bakeries, Catering Companies Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Wilmar International Ltd, Cargill Incorporated, Emery Oleochemicals, IOI Corporation Berhad, Kao Corporation, Godrej Industries Limited, Croda International Plc, P&G Chemicals, KLK OLEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Glycerin Market Emerging Trajectories
Membrane filtration and molecular distillation advances are collapsing the cost gap between technical and food-grade glycerin purification. These process innovations are enabling new feedstock flexibility while compressing traditional quality-tier pricing spreads.
Supercritical CO2 extraction is rewriting glycerin recovery economics from biodiesel waste streams. German chemical engineers are deploying this technology at commercial scale. The process is enabling food-grade certification for previously non-compliant feedstocks, expanding the addressable supplier base beyond virgin vegetable oils.
EFSA contaminant limits under REACH are forcing reformulation of imported glycerin supply chains. The regulation is mandating batch-level traceability documentation for oleochemical derivatives. European beverage manufacturers are responding by consolidating procurement around REACH-registered refiners with verified feedstock chain-of-custody systems.
Direct refiner-to-formulator contracting is displacing traditional oleochemical distributor networks. Large bakery and dairy processors are negotiating multi-year glycerin supply agreements with guaranteed purity specifications. This pattern is most visible in Germany and the Netherlands where food ingredient clusters enable face-to-face technical collaboration between refiners and formulation scientists.
Food Grade Glycerin Market Segmentation
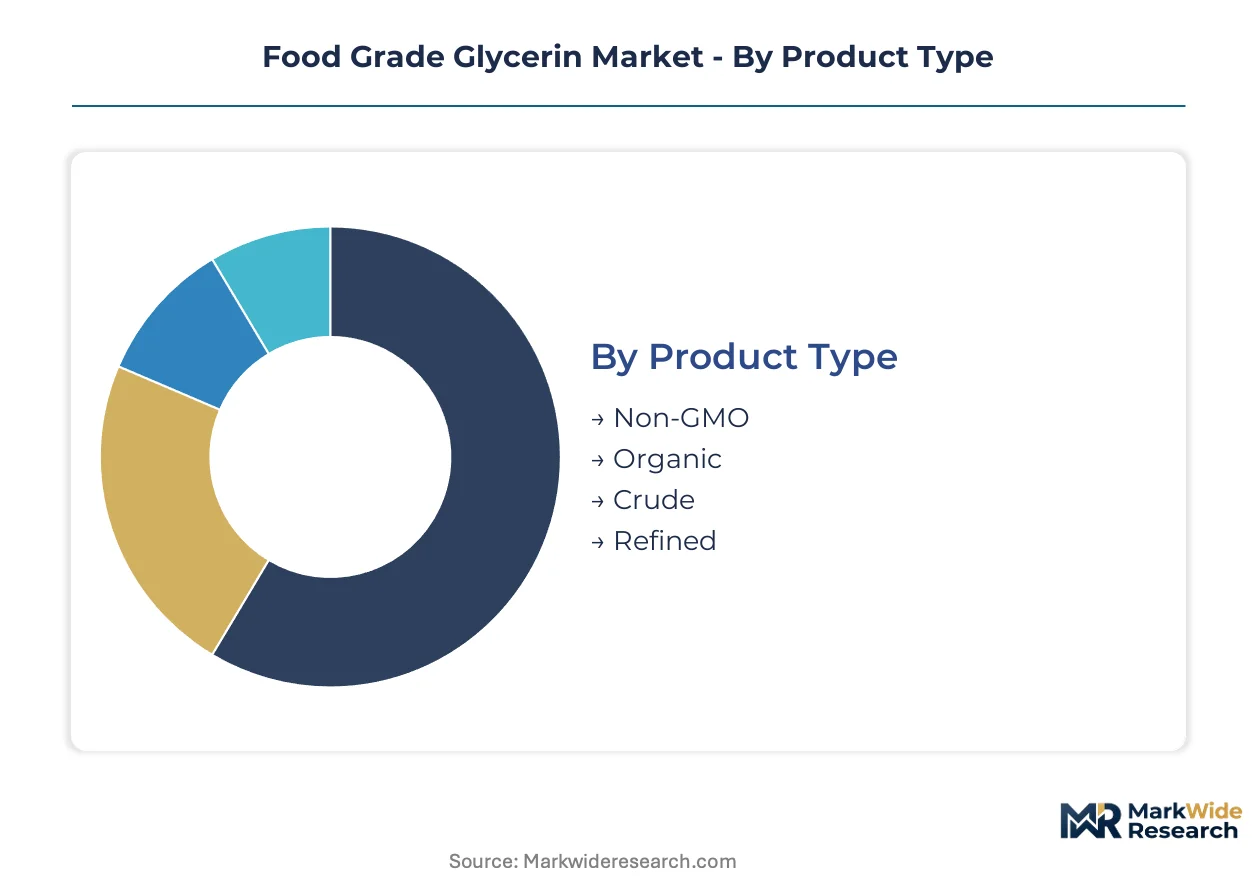
Food grade glycerin procurement patterns diverge sharply across purity grades and application specifications. Refiners structure production portfolios around these fault lines to capture formulation-grade premiums while managing feedstock volatility.
Product Type:
Supply concentration among integrated palm oil refiners in Malaysia and Indonesia shapes product tier availability and certification reach.
- Refined:Minimum 99.5% glycerol content meets pharmaceutical-overlapping food safety protocols. German beverage manufacturers and Dutch dairy processors dominate procurement for clean-label positioning. EFSA contaminant limits under REACH documentation requirements compress the acceptable supplier base.
- Organic:Certified vegetable oil feedstocks command shelf space in artisan bakery and clean-label dairy segments. Clean-label processors reject petrochemical-derived alternatives, opening premium positioning for certified organic supply chains.
- Non-GMO:Identity-preserved soybean and rapeseed feedstocks satisfy North American processor verification requirements.
- Crude:Pre-purification intermediate streams serve technical applications outside food-grade specifications.
Today's leader: Refined. Tomorrow's challenger: Organic.
Application:
Formulation-grade premiums concentrate where humectant functionality intersects with clean-label marketing requirements.
- Beverages:Low-glycemic-index positioning displaces traditional sweetener systems in sports and functional drink formulations. German chemical engineers deploy supercritical CO2 extraction to enable food-grade certification for expanded feedstock flexibility.
- Bakery:Moisture retention specifications expand glycerin volumes in reduced-fat bread and confectionery formulations. Texture stabilization requirements drive direct refiner-to-formulator contracting.
- Confectionery:Humectant properties prevent sugar crystallization in chocolate and candy production.
- Dairy:Ice cream and yogurt processors leverage glycerin for freeze-thaw stability and mouthfeel enhancement.
Volume concentrates in bakery. Steepest expansion trajectory emerges in beverages.
End User:
Procurement scale and technical collaboration intensity separate tier-one buyers from price-sensitive segments.
- Food Manufacturers:Multi-year supply agreements with guaranteed purity specifications dominate procurement patterns. Large bakery and dairy processors negotiate directly with REACH-registered refiners.
- Beverage Producers:Pharmaceutical-grade purity tiers compress acceptable supplier bases while elevating formulation premiums.
- Bakeries:Artisan and industrial segments split between organic certification requirements and cost-optimized refined grades.
- Catering Companies:Smaller volume procurement flows through distributor networks with less stringent documentation requirements.
Contracting power clusters with food manufacturers. Beverage producers gain negotiating leverage fastest.
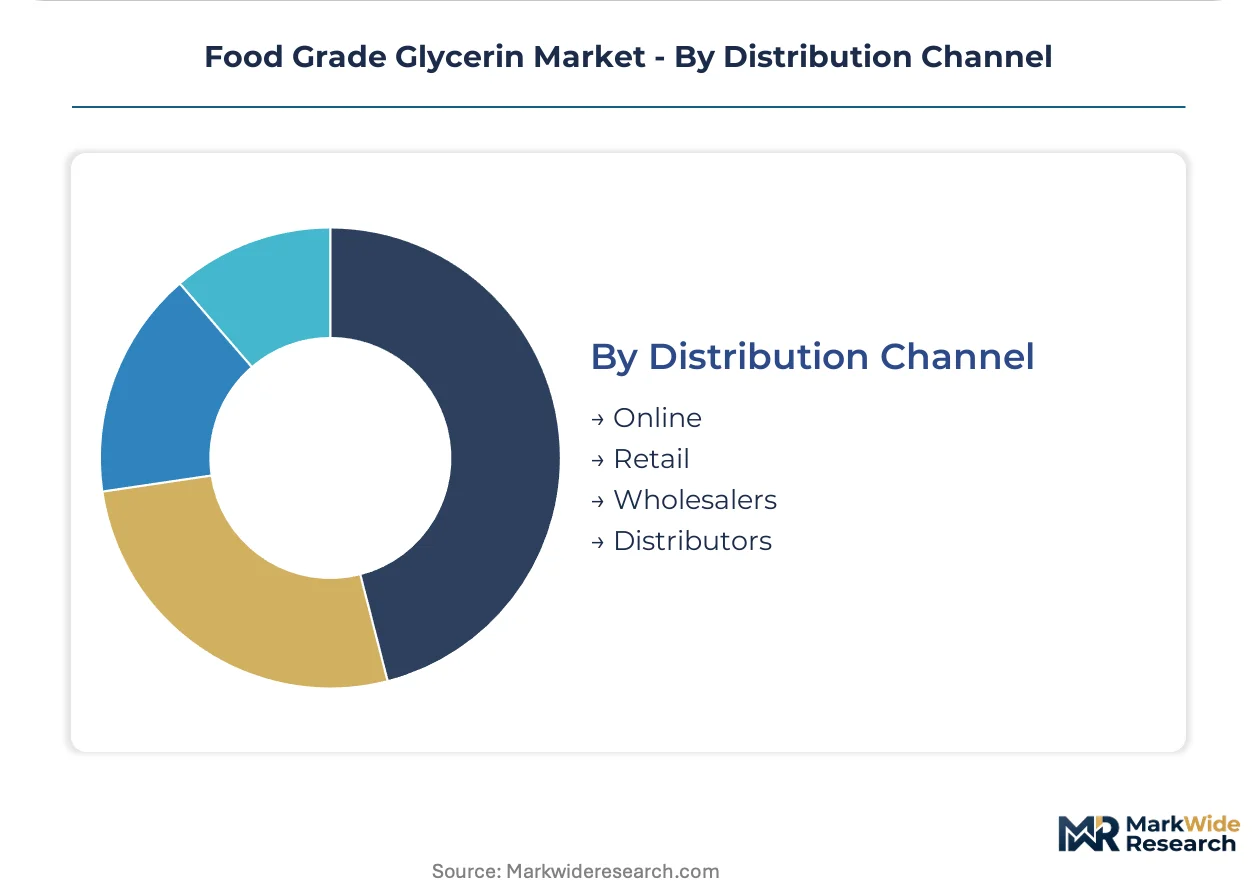
Distribution Channel:
Channel selection reflects buyer scale, certification documentation needs, and geographic proximity to refining capacity.
- Distributors:Traditional oleochemical distributor networks face displacement as large processors consolidate procurement around direct refiner relationships.
- Wholesalers:Volume aggregation serves mid-tier food manufacturers without dedicated procurement teams.
- Online:Digital platforms capture smaller bakeries and specialty food producers seeking organic-certified grades.
- Retail:Packaged glycerin for artisan and home-use applications represents minimal commercial volume.
Direct channels capture share from distributors. Online platforms expand fastest in organic-certified segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf and Hamburg bio-chemical R&D hubs concentrate formulation-grade glycerin procurement as beverage manufacturers and dairy processors negotiate direct supply agreements with REACH-registered refiners.
Germany
Clean-label bakery processors and sports drink formulators drive pharmaceutical-grade glycerin demand. The EU Green Deal and F-Gas Regulation tighten contaminant thresholds for bio-based glycerin imports. Düsseldorf's food ingredient cluster enables face-to-face technical collaboration between refiners and formulation scientists.
United States
Non-GMO verification requirements from identity-preserved soybean processors expand procurement specifications. The FDA maintains purity standards under 21 CFR for direct food additives. Chicago and Minneapolis dairy processors leverage glycerin for freeze-thaw stability in reduced-fat ice cream formulations.
Malaysia
Integrated palm oil refining complexes control disproportionate global food-grade glycerin capacity. The country's national standards body enforces feedstock traceability for oleochemical exports. Port Klang and Pasir Gudang industrial zones anchor Southeast Asian glycerin production gravity.
China
Beverage manufacturers adopt low-glycemic-index positioning in functional drink formulations. GB standards and SAMR oversight govern food additive purity and labeling requirements. Yangtze River Delta chemical parks concentrate hydrolysis and transesterification capacity for domestic glycerin supply.
Netherlands
Dairy and confectionery processors expand glycerin volumes for texture stabilization in reduced-fat formulations. ECHA documentation requirements under REACH raise barriers for unregistered exporters. Rotterdam's port infrastructure and Amsterdam food ingredient clusters facilitate European glycerin distribution.
Food Grade Glycerin Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated palm oil refiners scale continuous processing systems to capture pharmaceutical-overlapping purity premiums. The vendor base stratifies between agricultural conglomerates with captive vegetable oil supplies and independent oleochemical specialists. Three archetypes define competitive positioning: integrated agribusinesses, standalone oleochemical refiners, and certified organic specialists. M&A activity and backward integration into vegetable oil feedstocks represent the dominant competitive moves as participants defend margin positions against commodity volatility.
Among Asia-Pacific-based integrated producers, Wilmar International Ltd and IOI Corporation Berhad exemplify the agribusiness archetype with captive palm oil refining capacity. Emery Oleochemicals occupies a position within the specialist tier, representing kosher and halal-certified oleochemical glycerin production for global food access. These three companies anchor the competitive structure while smaller regional participants compete on organic certification and REACH registration compliance.
| Leading Market Players |
|---|
| Wilmar International Ltd |
| Cargill Incorporated |
| Emery Oleochemicals |
| IOI Corporation Berhad |
| Kao Corporation |
| Godrej Industries Limited |
| Croda International Plc |
| P&G Chemicals |
| KLK OLEO |
| Others |
Supply Flow & Price Mechanics
Malaysian palm oil futures and Indonesian crude palm oil benchmarks cascade directly into food grade glycerin pricing tiers, with integrated refiners in Southeast Asia capturing margin premiums while European buyers absorb volatility through long-term offtake contracts.
Pricing Analysis
Input-cost pass-through from vegetable oil feedstocks governs pricing dynamics across the value chain. Contract-based long-term offtake agreements dominate procurement between large bakery processors and REACH-registered refiners, with price differentiation driven by certification grade and volume scale. Pricing pressure intensifies in standard refined tiers as biodiesel-derived glycerin floods technical-grade markets. Mid-sized beverage producers exhibit highest price sensitivity due to reformulation flexibility, while pharmaceutical-grade buyers accept premiums for contaminant documentation.
Supply Chain Analysis
EU Green Deal local-content mandates and feedstock traceability requirements are reshaping sourcing patterns for European food manufacturers. Supply concentrates in Malaysia, Indonesia, and Germany, with hydrolysis and transesterification capacity drawing from palm oil, soybean oil, and rapeseed feedstocks. Single-source vulnerability persists around Port Klang and Pasir Gudang refining complexes. Distribution runs through direct refiner-to-formulator channels for large processors, while smaller bakeries rely on distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
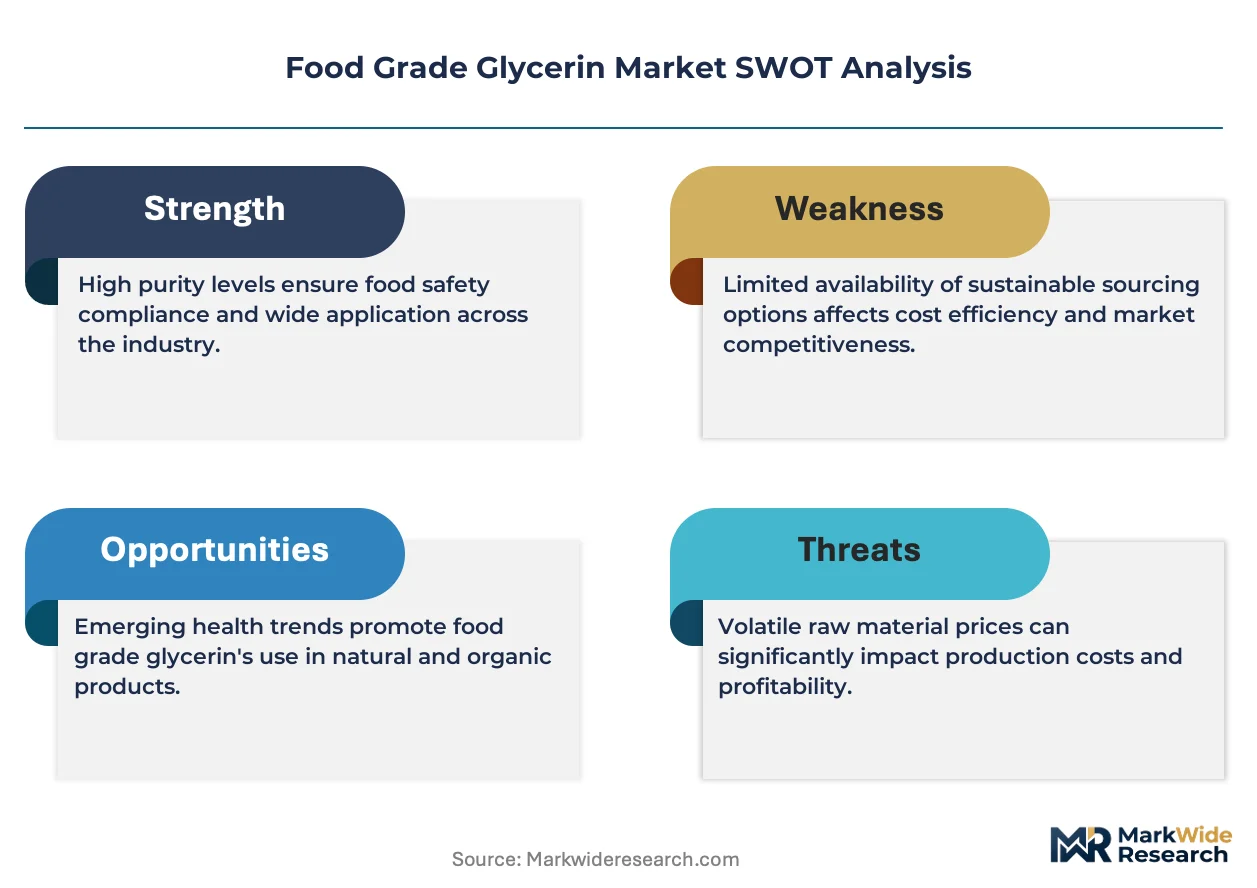
The food grade glycerin market functions as a stable compounder anchored by irreversible clean-label substitution trends across beverage and bakery formulations.
For Market Incumbents: Anticipate margin compression from organic certification demands by securing backward integration into certified vegetable oil estates in Southeast Asia. Expand continuous processing capacity in Germany to meet pharmaceutical-overlapping purity specifications. Kosher and halal audit stream consolidation represents the critical defensive lever against emerging specialist refiners.
For New Entrants and Emerging Players: Capture white space in organic-certified glycerin for artisan dairy and clean-label confectionery segments. The most penetrable entry point sits with online distribution platforms serving smaller European bakeries seeking identity-preserved feedstock documentation. A go-to-market angle anchored in supercritical CO2 extraction technology enables food-grade certification from non-virgin feedstocks.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale oleochemical refiners possessing REACH registration and established kosher/halal certification infrastructure. The five-to-ten year viability window favors assets with verified feedstock chain-of-custody systems. Watch for EFSA contaminant limit enforcement as the inflection signal consolidating procurement around compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feedstocks | Captures margin from organic glycerin premiums while satisfying EU Green Deal traceability mandates. |
| Continuous Processing Capacity Expansion | Enables pharmaceutical-grade purity output for beverage manufacturers demanding contaminant thresholds. |
| REACH Registration Compliance Investment | Creates competitive moat against unregistered Asian exporters facing ECHA documentation barriers. |
| Direct Refiner-to-Formulator Contracting | Bypasses distributor networks to capture formulation-grade premiums from large bakery processors. |
| Supercritical CO2 Extraction Deployment | Expands addressable feedstock base beyond virgin vegetable oils for German beverage manufacturers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with glycerin refinery plant managers, procurement leads at bakery and dairy OEMs, distribution channel partners, and beverage formulation scientists with secondary validation against customs trade data, oleochemical industry association reports, FDA 21 CFR filings, and EFSA contaminant limit documentation. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Comparable historical periods anchored the forecast window across the analysis window, with segmentation modeling across purity grade tiers, application verticals, end-user scale categories, and regional production hubs. CAGRs derived from feedstock price elasticity coefficients and substitution rate assumptions for propylene glycol displacement. Biodiesel policy mandates and clean-label penetration curves served as industry-specific forecast inputs.
Vegetable oil commodity volatility, regulatory enforcement intensity around REACH documentation, and propylene glycol substitution acceleration are the dominant revision risks to modeled outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Protein Films Market