
 South America Feed Additives Market | 2026-2036
South America Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Additives Market Analytics
Phytogenic extracts are hardening as the preferred alternative to antibiotic growth promoters in poultry and swine formulations. DSM-Firmenich leverages its Swiss-Brazilian R&D hub to develop region-specific essential oil blends for tropical stress conditions. Cargill, Incorporated anchors its position through backward integration into Brazilian soybean processing, securing captive supply of lecithin and oilseed derivatives for emulsifier production. BASF SE differentiates via its Natuphos phytase portfolio, competing on thermostability metrics critical to pelleting operations in high-temperature climates.
Feed additives encompass biologically active substances incorporated into animal diets at inclusion rates typically below one percent to enhance nutrient utilization, gut health, or growth performance. Enzyme formulations, particularly xylanase and phytase variants, function by degrading anti-nutritional factors in corn-soybean meal matrices dominant across South American feed mills. Vitamins and minerals constitute the mature revenue base with stable offtake from integrated poultry operations, while enzymes represent the fastest-expanding margin pool as producers seek feed cost reduction amid volatile grain prices. Powder formulations retain volume leadership for micro-premix applications, though liquid enzyme delivery systems are gaining traction in automated dosing infrastructure at large-scale feed manufacturers.
Brazil's MAPA enforces progressive restrictions on antibiotic growth promoters, compelling reformulation investments across feed manufacturers serving export-oriented protein processors. ANVISA's residue monitoring protocols for the EU and China export markets shape product registration pathways and efficacy documentation requirements. Argentina's SENASA implements parallel veterinary drug regulations that influence cross-border formulation standardization. Stakeholders must monitor regulatory divergence between Mercosur harmonization ambitions and individual national registration timelines when allocating product development resources.
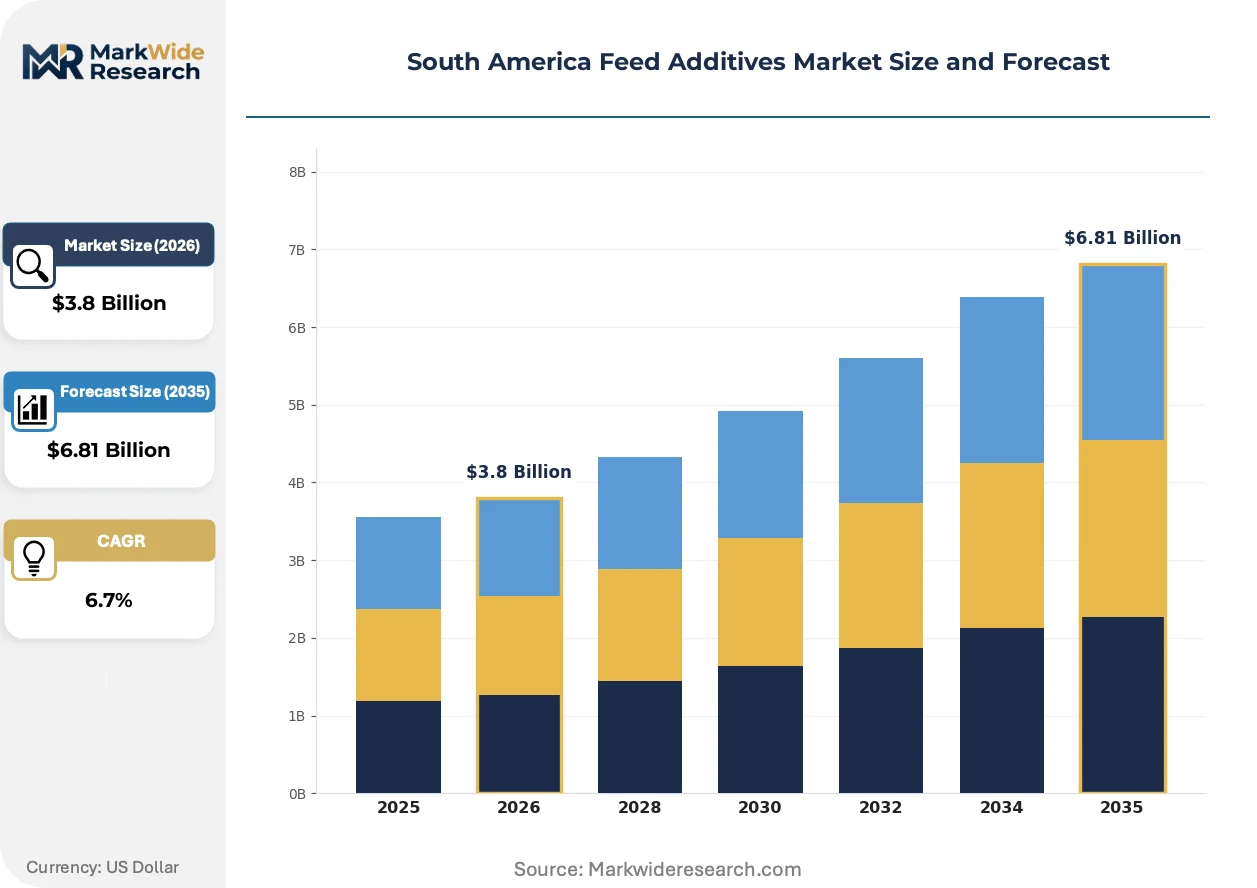
Market Dynamics
Brazil's MAPA antibiotic growth promoter restrictions are forcing feed manufacturers across the southern livestock corridor to rebuild formulation portfolios around phytogenic and probiotic alternatives, compressing reformulation cycles from years to months.
Growth Catalysts
- Enzyme adoption:Poultry integrators in Paraná and Santa Catarina are deploying xylanase-phytase cocktails to degrade anti-nutritional factors in corn-soybean meal matrices, improving feed conversion ratios by measurable margins.
- ANVISA export protocols:Residue monitoring requirements for EU and China protein markets are compelling investments in documentation-heavy organic acid and essential oil registrations.
- Southern corridor concentration:Demand gravity centers on Rio Grande do Sul's vertically integrated pork and poultry complexes, creating captive offtake pools for premix suppliers.
Market Restraints
- Soybean input volatility:Lecithin and oilseed derivative costs fluctuate with Brazilian crush margins, compressing emulsifier producer margins unpredictably.
- Cross-border regulatory friction:Divergent SENASA and MAPA veterinary drug registration timelines fragment product standardization across Mercosur trade flows.
- Thermostability limitations:Conventional enzyme formulations degrade under high-temperature pelleting conditions prevalent in tropical feed mills, restricting application ranges.
Strategic Opportunities
- Argentina's lagging transition:SENASA enforcement gaps create a 24-36 month window for phytogenic-first entrants to establish formulation standards before antibiotic restrictions tighten.
- Liquid dosing infrastructure:Automated enzyme delivery systems at large-scale Brazilian feed manufacturers enable precision inclusion rate adjustments and service contract bundling.
- Essential oil convergence:Blending region-specific botanical extracts with organic acids addresses tropical heat stress in poultry, opening premium positioning in export-oriented operations.
Industry Challenges
- Registration timeline compression:ANVISA efficacy documentation requirements for novel probiotic strains extend product launch cycles beyond 18 months, straining R&D amortization.
- Feed mill integration complexity:Legacy powder premix infrastructure at mid-tier Brazilian manufacturers requires capital-intensive retrofitting to accommodate liquid enzyme systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Additives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Enzymes, Vitamins, Minerals Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granulated, Pelleted End User: Feed Manufacturers, Livestock Farmers, Aquafarmers, Pet Food Producers |
| Companies Covered | Cargill, Incorporated, DSM-Firmenich, BASF SE, Archer Daniels Midland Company, Adisseo, Evonik Industries AG, Alltech, Kemin Industries, Novus International, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Additives Market Evolving Landscape
Formulation science is pivoting from cost-driven inclusion to performance-verified active ingredients, with thermostability and gut microbiome targeting replacing commodity purchasing logic across South American feed operations.
Phytase enzyme engineering is overtaking standard fungal-derived formulations in Brazilian high-temperature pelleting environments. DSM-Firmenich and BASF SE are deploying bacterial-origin variants with 85°C+ stability thresholds. Poultry integrators in Santa Catarina are adopting these heat-resistant grades at accelerated procurement cycles, compressing supplier qualification timelines from 24 months to 12.
MAPA's progressive antibiotic growth promoter restrictions are restructuring product registration priorities across feed additive portfolios. Manufacturers must now front-load phytogenic and organic acid efficacy trials to maintain market access. Export-oriented protein processors in Paraná are driving this shift, pressuring premix suppliers to abandon legacy antimicrobial formulations regardless of domestic enforcement timing.
Integrated poultry operations are consolidating procurement authority at the holding-company level, displacing decentralized mill-level purchasing. BRF and JBS protein divisions now mandate centralized enzyme and vitamin sourcing across their southern Brazil feed manufacturing networks. This concentration is most visible in Rio Grande do Sul, where three integrators control 60% of regional premix volume, forcing suppliers into direct partnership negotiations rather than distributor-mediated sales.
South America Feed Additives Market Segmentation
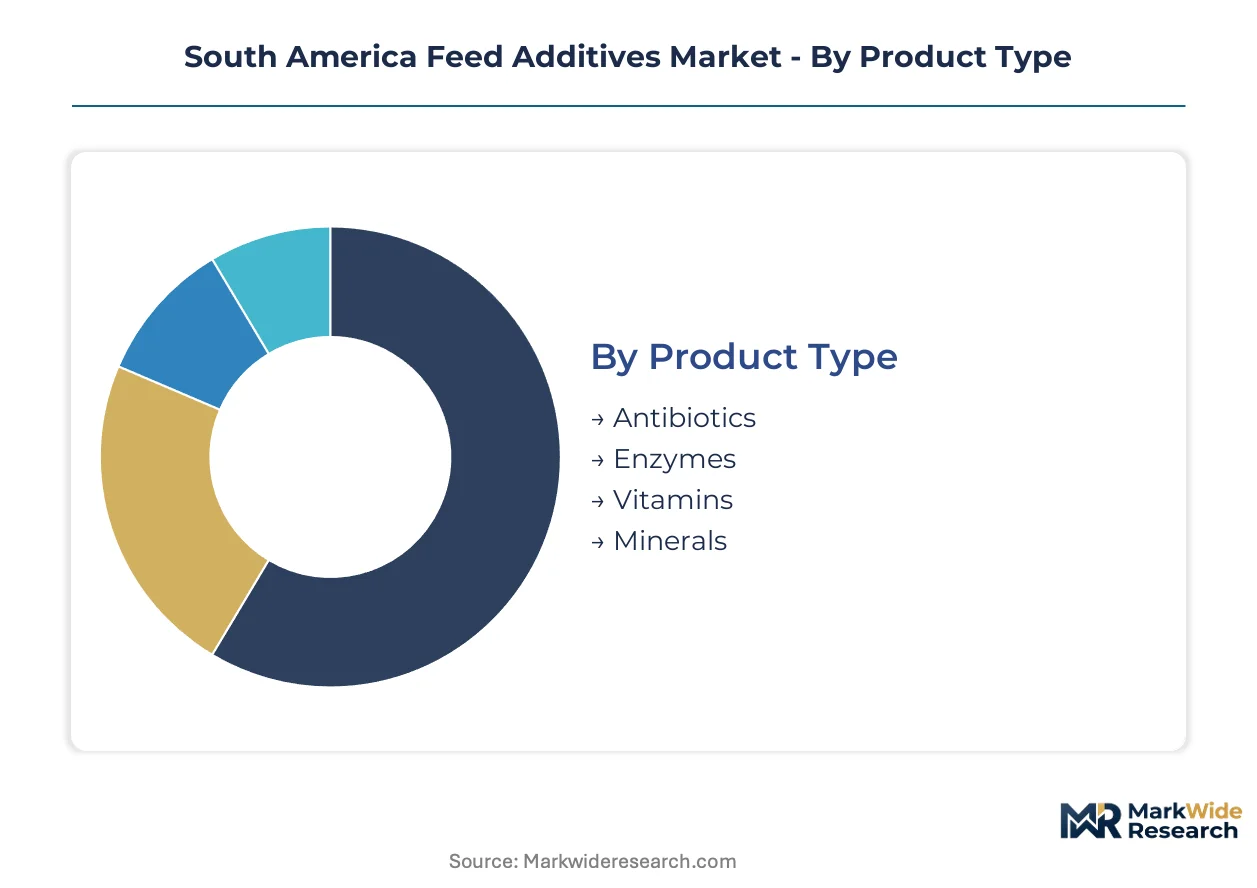
Feed additive purchasing patterns diverge sharply across South American livestock operations based on species-specific nutritional requirements and processing infrastructure maturity. Understanding these segment boundaries enables suppliers to align formulation investments with the highest-conversion customer profiles.
Product Type:
Thermostability specifications and inclusion rate economics separate mature commodity segments from emerging performance categories.
- Enzymes:Xylanase and phytase variants degrade anti-nutritional factors in corn-soybean meal matrices. Poultry integrators in Paraná and Santa Catarina deploy bacterial-origin phytase with 85°C+ stability thresholds for high-temperature pelleting, compressing supplier qualification timelines from 24 months to 12.
- Vitamins:Fat-soluble and water-soluble micronutrient premixes constitute the established revenue base with stable offtake from integrated operations. Demand concentrates in Rio Grande do Sul's vertically integrated pork and poultry complexes, where three integrators control 60% of regional premix volume.
- Antibiotics:Growth promoter formulations face progressive MAPA restrictions, forcing reformulation investments across export-oriented feed manufacturers.
- Minerals:Macro and trace element supplementation addresses regional soil deficiency patterns in Brazilian pasture systems.
Mature deployment sits with Vitamins. Newer deployment is concentrated in Enzymes.
Application:
Species-specific digestive physiology dictates additive selection, with monogastric operations driving precision nutrition adoption faster than ruminant systems.
- Poultry:Broiler and layer operations require exacting feed conversion optimization. Brazil's southern livestock corridor spanning Paraná, Santa Catarina, and Rio Grande do Sul generates the most intense demand concentration for enzyme and probiotic formulations.
- Swine:Finishing phase diets incorporate phytogenic extracts as antibiotic alternatives. SENASA enforcement gaps in Argentina create a 24-36 month window for phytogenic-first entrants to establish formulation standards.
- Ruminants:Beef and dairy operations utilize ionophores and buffer compounds for rumen efficiency.
- Aquaculture:Shrimp and tilapia producers in coastal Brazil require specialized immunostimulant and pigment additive protocols.
Volume leadership belongs to Poultry. Steepest expansion trajectory is occurring in Aquaculture.
Form:
Physical delivery systems determine manufacturing compatibility and dosing precision across feed mill infrastructure tiers.
- Powder:Micro-premix applications retain volume leadership due to legacy infrastructure prevalence. Mid-tier Brazilian manufacturers face capital-intensive retrofitting requirements to accommodate alternative delivery systems.
- Liquid:Automated enzyme dosing infrastructure enables precision inclusion rate adjustments at large-scale feed manufacturers. Service contract bundling opportunities emerge as procurement consolidates at holding-company level.
- Granulated:Flowability-enhanced formats reduce dust exposure and improve handling characteristics.
- Pelleted:Coated formulations protect heat-sensitive actives through pelleting thermal stress.
Established infrastructure favors Powder. Technology migration is accelerating toward Liquid.
End User:
Customer scale and integration depth create distinct purchasing authority patterns across the value chain.
- Feed Manufacturers:Integrated poultry operations now mandate centralized enzyme and vitamin sourcing across southern Brazil networks. BRF and JBS protein divisions displace decentralized mill-level purchasing with direct partnership negotiations.
- Livestock Farmers:Independent producers rely on distributor-mediated sales for smaller-volume premix requirements.
- Aquafarmers:Coastal shrimp operations require specialized technical support for water quality-integrated nutrition protocols.
- Pet Food Producers:Premium companion animal formulations drive palatability and digestibility additive demand.
Procurement consolidation centers on Feed Manufacturers. Emerging specification development is occurring among Aquafarmers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's southern livestock corridor, where vertically integrated poultry and pork operations drive premix procurement consolidation. Argentina's regulatory lag creates a 24-36 month window for phytogenic entrants before SENASA enforcement tightens.
Brazil
MAPA's antibiotic growth promoter restrictions are forcing feed manufacturers to rebuild formulation portfolios around phytogenic and probiotic alternatives. ANVISA's residue monitoring protocols for EU and China export markets shape product registration pathways. The southern corridor spanning Paraná, Santa Catarina, and Rio Grande do Sul generates the most intense demand concentration for enzyme and organic acid formulations.
Argentina
Poultry and swine producers are expanding enzyme usage to improve feed conversion ratios amid volatile grain prices. SENASA implements parallel veterinary drug regulations that influence cross-border formulation standardization with Brazil. Buenos Aires province and Santa Fe host the densest concentration of feed manufacturing capacity serving export-oriented protein processors.
Chile
Salmon aquaculture operations drive specialized demand for immunostimulant and pigment additive protocols. The country's national pharmaceutical regulator enforces strict residue limits for export compliance with US and EU markets. Puerto Montt and the Los Lagos region anchor the highest concentration of aquafeed production infrastructure.
Colombia
Poultry integrators are deploying xylanase-phytase cocktails to degrade anti-nutritional factors in corn-soybean meal matrices. The national agricultural authority oversees feed safety standards aligned with regional Mercosur harmonization ambitions. The Cundinamarca-Boyacá corridor concentrates the largest feed mill capacity serving Bogotá's protein demand.
Peru
Coastal shrimp producers require specialized technical support for water quality-integrated nutrition protocols. The country's fisheries and aquaculture regulator monitors additive safety for export market access. Piura and Tumbes regions host expanding aquafeed manufacturing serving Asian market export contracts.
South America Feed Additives Market Competitive Landscape
Backward integration into Brazilian soybean processing dominates the current landscape as suppliers secure captive supply of lecithin and oilseed derivatives. The market structure consolidates around multinational chemical conglomerates with regional R&D hubs, regional premix specialists, and integrated protein processors with captive feed operations. Three archetypes prevail: thermostability-focused enzyme engineers, phytogenic blend developers, and emulsifier producers with oilseed crushing assets. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms build automated liquid dosing infrastructure.
Within the multinational tier, DSM-Firmenich and BASF SE exemplify divergent approaches to tropical market adaptation. Cargill, Incorporated anchors the integrated supply chain archetype through its Brazilian processing footprint. These three firms occupy positions that reflect distinct strategic bets on regulatory timing, formulation science, and raw material security across the southern livestock corridor.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DSM-Firmenich |
| BASF SE |
| Archer Daniels Midland Company |
| Adisseo |
| Evonik Industries AG |
| Alltech |
| Kemin Industries |
| Novus International |
| Others |
Value Network & Pricing Analysis
Specialized enzyme formulation chemists concentrated in Brazil's southern livestock corridor command wage premiums that compress pricing-tier spreads between premium thermostable grades and standard fungal-derived alternatives. Labor-cost differentials between Swiss-Brazilian R&D hubs and local technical service teams feed directly into how suppliers structure service-bundled versus commodity enzyme offerings.
Pricing Analysis
Volume leadership sits with vitamins and minerals, while margin expansion concentrates in enzymes and phytogenic extracts. Three-tier pricing structure across premium thermostable phytase, standard fungal enzymes, and economy-grade mineral premixes separates formulation tiers. Pricing pressure stems from soybean lecithin input volatility crushing emulsifier producer margins. Independent livestock farmers in Brazil's interior exhibit highest price sensitivity, whereas export-oriented poultry integrators prioritize performance metrics over unit cost.
Supply Chain Analysis
ANVISA efficacy documentation and MAPA registration protocols gate supplier qualification timelines, extending from 12 months for established players to 18+ months for novel probiotic strains. Raw material sourcing draws from Brazilian soybean crushing assets for lecithin and oilseed derivatives, Swiss-European R&D inputs for essential oil blends, and Chinese-manufactured vitamin premix concentrates. Single-source vulnerability concentrates in thermostable phytase engineering capabilities held by limited bacterial-origin enzyme producers. Distribution runs through direct partnership negotiations with consolidated feed manufacturers rather than distributor-mediated sales to fragmented mill operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America feed additives market sits in a technology-transition phase as bacterial-origin thermostable enzymes displace conventional fungal formulations in high-temperature pelleting environments.
For Market Incumbents: Deepen backward integration into Brazilian soybean processing to secure captive supply of lecithin and oilseed derivatives against crush margin volatility. Expand automated liquid enzyme dosing infrastructure partnerships with BRF and JBS protein divisions to lock in centralized procurement relationships before mid-tier manufacturers complete capital-intensive retrofitting cycles. For New Entrants and Emerging Players: Phytogenic-first formulation platforms offer the most penetrable wedge into Argentina's lagging regulatory transition before SENASA enforcement tightens. Target Buenos Aires province and Santa Fe feed manufacturing clusters with region-specific essential oil blends for tropical heat stress, leveraging 24-36 month enforcement gaps to establish formulation standards ahead of antibiotic restriction alignment with Brazil. For Investors and Strategic Acquirers: Re-rating potential sits with thermostability-focused enzyme engineering specialists given MAPA's progressive antibiotic growth promoter restrictions accelerating enzyme adoption curves. Long-term viability centers on firms with bacterial-origin phytase portfolios and established ANVISA registration pathways. Watch for SENASA regulatory harmonization announcements as the inflection indicator for Argentina market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Processing | Cargill secures captive lecithin supply for emulsifier production against Brazilian crush margin swings. |
| Thermostable Enzyme Engineering Investment | BASF SE's bacterial-origin Natuphos variants withstand 85°C+ pelleting thresholds in tropical feed mills. |
| Region-Specific Phytogenic R&D Hub | DSM-Firmenich's Swiss-Brazilian facility develops essential oil blends calibrated for southern corridor heat stress. |
| Automated Liquid Dosing Infrastructure | Large-scale Brazilian feed manufacturers enable precision enzyme inclusion and service contract bundling. |
| Cross-Border Registration Harmonization | Parallel MAPA-SENASA veterinary drug pathways reduce fragmentation across Mercosur trade flows. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with feed mill procurement directors, poultry integrator nutritionists, premix supplier technical service managers, and MAPA registration consultants combined with secondary validation from ANVISA residue monitoring protocols, SENASA veterinary drug regulations, and Brazilian customs export statistics. Bottom-up volume modeling across enzyme, vitamin, and phytogenic segments triangulated against top-down market sizing from regional feed production data.
Granularity-level modeling deployed product-type splits at the enzyme-variant level, application-level disaggregation across poultry, swine, ruminant, and aquaculture species, and form-factor differentiation between powder and liquid delivery systems. CAGRs derived from regression analysis of historical feed additive intensity ratios against projected livestock production volumes across the analysis window. Forecast inputs incorporated MAPA regulatory phase-out timelines for antibiotic growth promoters and ANVISA export protocol stringency indices for EU and China market access.
Several conditions sit outside the modeled scope, including unforeseen SENASA enforcement acceleration, Mercosur regulatory divergence beyond current harmonization ambitions, and catastrophic Brazilian soybean crop failures. Forecasts reflect assumptions about continued export market access for Brazilian protein processors and stable grain price volatility patterns. A model refresh is warranted upon material change in MAPA antibiotic restriction phase-out schedules or ANVISA efficacy documentation requirements for novel probiotic strains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Natural Food Color Additives Market