
 United Kingdom Anti Caking Market | 2026-2036
United Kingdom Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Anti Caking Market Analytics
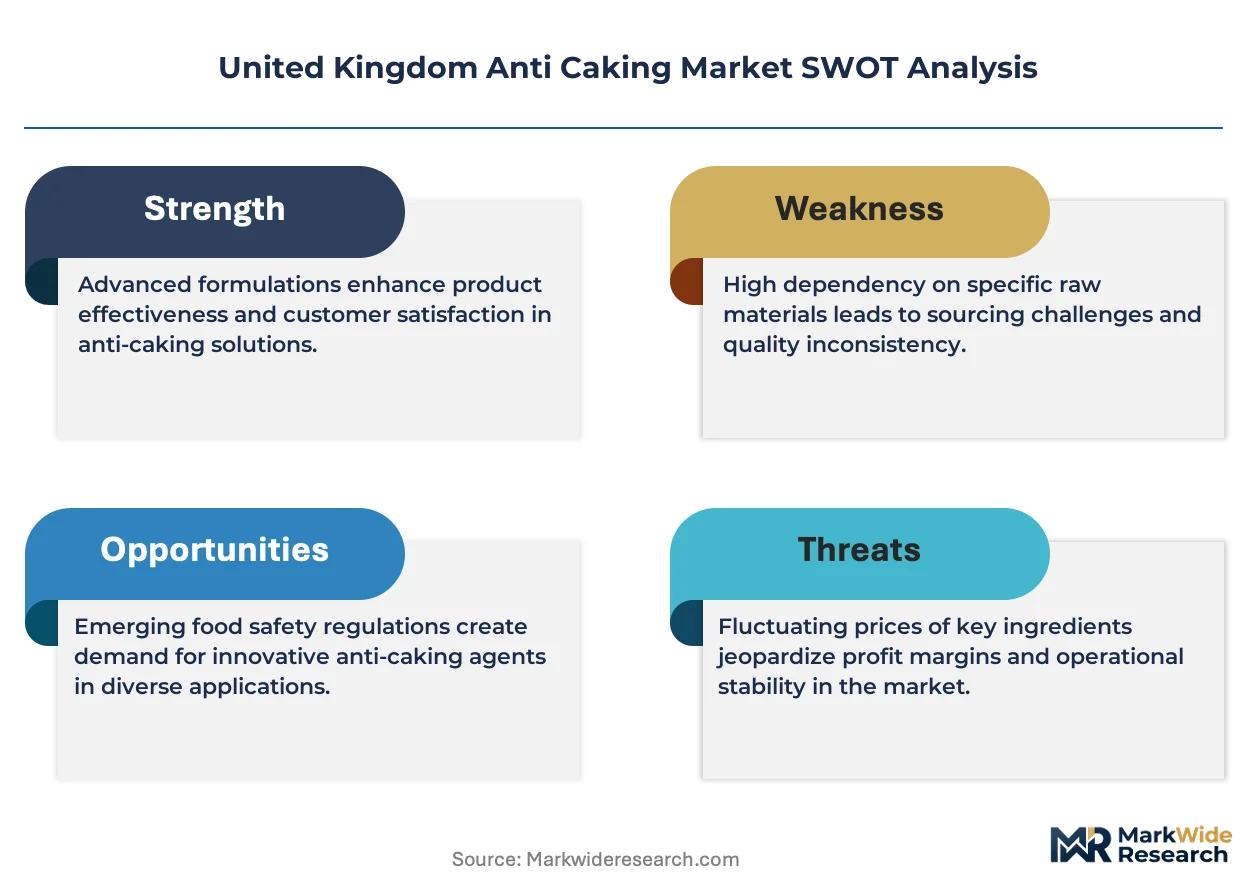
Asset-light leasing arrangements for specialty chemical processing equipment is reconfiguring competitive entry barriers for mid-sized suppliers in the United Kingdom Anti Caking Market. BASF SE leverages its integrated silicate chemistry platform to sustain cost advantages across sodium silicoaluminate production. Norkem anchors its position through specialized distribution networks serving food manufacturers throughout England and Scotland. Evonik Industries AG differentiates via precipitated silica technologies that extend its reach into pharmaceutical-grade applications.
Anti-caking agents are powdered or granular additives, typically comprising silicates, stearates, or carbonates, that absorb moisture and reduce interparticle cohesion to maintain free-flow properties in bulk solids. These materials prevent caking in hygroscopic powders during storage and transport, preserving processing efficiency in automated filling and dosing equipment. Sodium silicoaluminate dominates the product type landscape due to its cost-performance ratio in mass-market food applications, while calcium stearate commands premium positioning in pharmaceutical tablet formulations where lubricity requirements are stringent. The food industry application segment leads by volume, though pharmaceutical end users generate higher margin pools per kilogram given certification and purity overheads.
The Food Standards Agency enforces retained EU regulations on food additive purity and maximum usage levels, compelling reformulation where legacy compositions exceed codified thresholds. REACH compliance administered by the Health and Safety Executive governs chemical registration and hazard communication for non-food industrial applications, raising documentation burdens for imported raw materials. BSI standards for food contact materials provide an additional conformance layer that shapes supplier qualification protocols. Stakeholders must monitor evolving divergence between UK and EU regulatory frameworks to anticipate compliance cost trajectories and sourcing strategy adjustments.
Market Dynamics
Retained EU food additive regulations under UK law are fragmenting formulation standards from continental Europe, forcing manufacturers to maintain dual compliance pathways and reshaping sourcing strategies across England's food processing belt.
Growth Catalysts
- Instant beverage mix expansion:Powdered drink manufacturers in Yorkshire and the East Midlands are scaling production lines that require sodium silicoaluminate to maintain flow properties during automated packaging.
- REACH documentation convergence:Health and Safety Executive chemical registration protocols are streamlining hazard communication for imported silicates, reducing administrative friction for specialty chemical distributors.
- Pharmaceutical tablet lubricity standards:Calcium stearate demand from contract manufacturers serving NHS supply chains is rising as purity specifications tighten for generic drug production.
Market Restraints
- Silicate raw material concentration:Sodium silicate feedstock supply concentrates in northwest England industrial corridors, creating geographic vulnerability to regional logistics disruptions.
- Regulatory divergence friction:UK Food Standards Agency maximum usage levels for certain silicates now differ from EFSA thresholds, complicating cross-border formulation standardization for multinational food brands.
- Natural anti-caking substitution:Rice hull ash and other plant-derived flow agents are capturing niche positioning in premium organic seasoning segments, pressuring synthetic silicate volumes.
Strategic Opportunities
- Scottish pharmaceutical corridor:Underpenetrated tablet manufacturing capacity near Glasgow presents whitespace for precipitated silica suppliers targeting high-margin excipient applications.
- Clean label convergence:Combining modified starch technologies with mineral carriers creates hybrid anti-caking systems that satisfy both processing performance and simplified ingredient declarations.
- Asset-light equipment leasing:Specialty chemical processors in the Midlands are adopting short-term reactor leases rather than capital purchases, lowering entry barriers for mid-sized formulation specialists.
Industry Challenges
- Dual regulatory qualification timelines:Manufacturers must simultaneously satisfy retained EU purity standards and emerging UK-specific BSI food contact material protocols, extending product approval cycles.
- Silicate chemistry talent scarcity:Formulation chemists with expertise in precipitated silica particle engineering are concentrated among a small cohort of legacy suppliers, constraining R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Anti Caking Market |
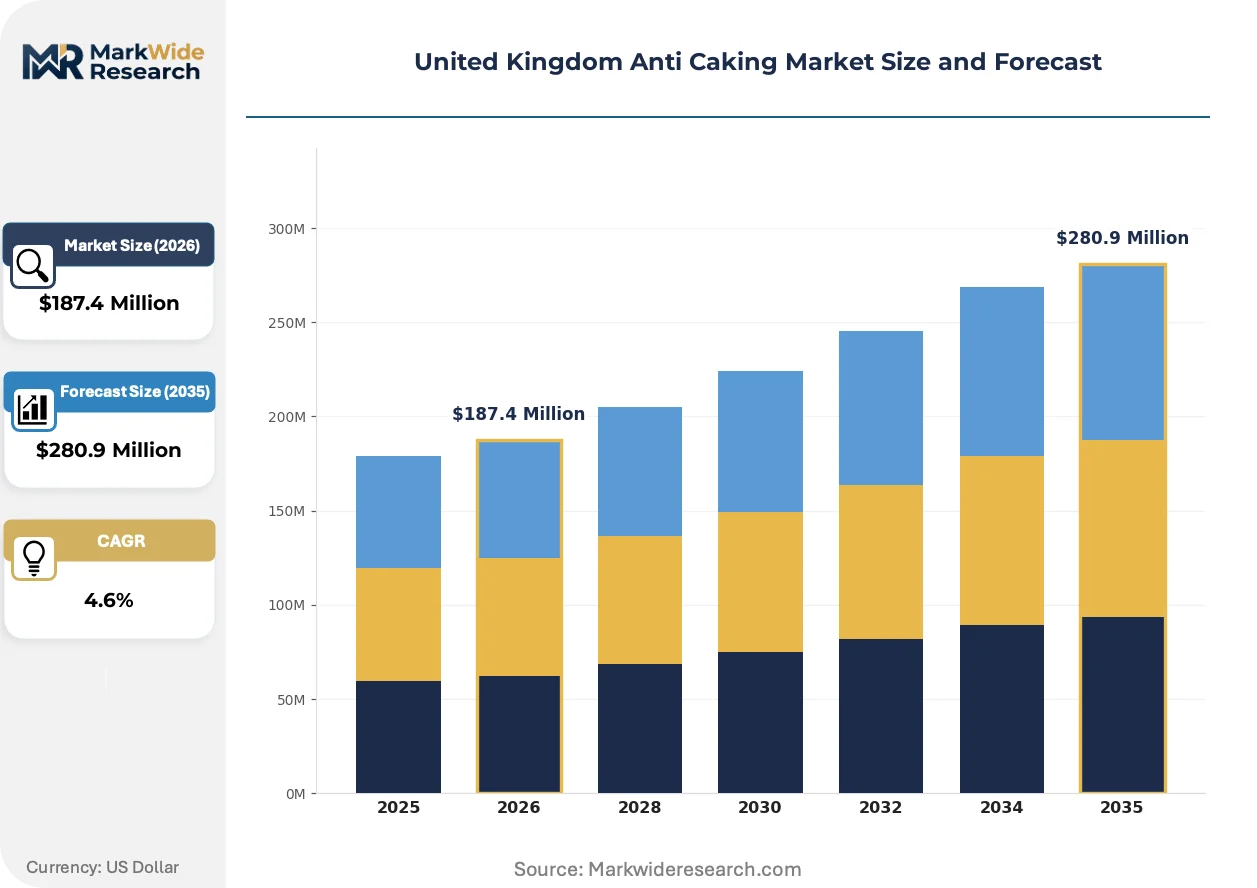
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicoaluminate, Talc, Magnesium Carbonate, Calcium Stearate Application: Food Industry, Chemical Processing, Pharmaceutical, Agriculture Form: Powder, Granular, Liquid, Tablet End User: Food Manufacturers, Chemical Producers, Pharmaceutical Companies, Agricultural Suppliers |
| Companies Covered | BASF SE, Norkem, PQ Corporation, Bacarel and Company Limited, H Plus Limited, Spectrum Chemical Manufacturing Corp, Evonik Industries AG, PPG Industries, Huber Engineered Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Anti Caking Market Evolving Landscape
Digital formulation platforms and precision particle engineering are compressing development cycles for anti-caking systems, while regulatory divergence between UK and EU frameworks is forcing adaptive compliance architectures.
Computational modeling of particle-particle interactions is virtualizing traditional empirical testing protocols for anti-caking efficacy. Food manufacturers in England's East Midlands are adopting these simulation tools to reduce physical prototyping iterations from months to weeks. This technology is virtualizing the historical reliance on pilot-scale silo storage trials, collapsing time-to-market for new seasoning formulations.
The UK's retained EU regulations framework under the Food Standards Agency is diverging from EFSA maximum usage levels for certain silicate additives. This policy friction is compelling multinational food brands to maintain separate UK-specific formulations rather than unified European recipes. Powdered soup and sauce manufacturers serving both markets are absorbing the highest compliance burden, with some consolidating production in England to avoid cross-border regulatory complexity.
Buyer concentration among large contract manufacturers is compressing supplier qualification timelines and unbundling technical service from material supply. Mid-sized seasoning blenders in Yorkshire are shifting from relationship-based procurement to specification-driven tendering, with anti-caking performance guarantees replacing historical brand loyalty. This behavioral shift is most visible in the East Midlands food processing cluster, where procurement teams now mandate third-party flowability certification prior to contract award.
United Kingdom Anti Caking Market Segmentation
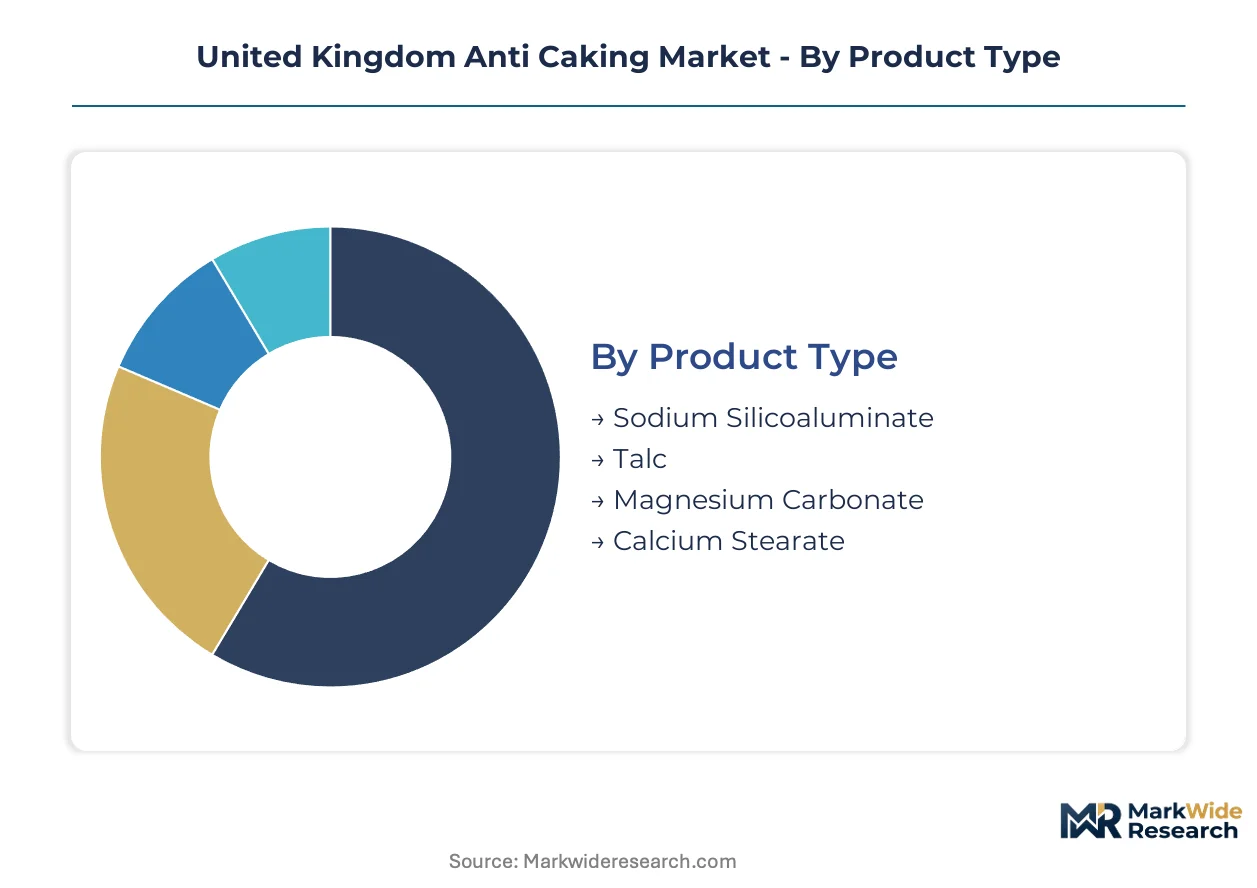
Anti-caking agent procurement in the United Kingdom follows distinct technical and commercial logics across product chemistry, application requirements, and end-user scale. Segmentation clarity enables suppliers to align formulation investments with margin concentration points in England's food processing belt and emerging pharmaceutical corridors.
Product Type:
Cost tier differentiation separates commodity silicates from premium stearates and specialty carbonates in procurement negotiations.
- Sodium Silicoaluminate:Synthetic aluminum silicate complex delivers superior moisture absorption at low inclusion rates. Yorkshire instant beverage manufacturers specify this chemistry for automated packaging lines handling hygroscopic drink powders under FSA purity protocols.
- Calcium Stearate:Metallic soap derivative provides dual functionality as anti-caking agent and tablet lubricant. NHS contract manufacturers in the East Midlands favor this grade for generic drug production where pharmacopeial compliance commands price premiums.
- Talc:Hydrated magnesium silicate serves niche food and industrial applications requiring inert carrier properties.
- Magnesium Carbonate:Lightweight alkaline compound finds use in specialty seasoning blends and sports nutrition powders.
Sodium silicoaluminate holds installed capacity. Calcium stearate is rotating up the share rankings.
Application:
Application segmentation tracks divergent purity standards and performance specifications across regulated industries.
- Food Industry:Powdered seasonings, soup mixes, and instant beverages dominate volume consumption. East Midlands processing clusters source sodium silicoaluminate under retained EU additive regulations enforced by the Food Standards Agency.
- Pharmaceutical:Tablet and capsule formulations require excipient-grade flow agents with full pharmacopeial documentation. Scottish manufacturing corridors near Glasgow represent underpenetrated whitespace for precipitated silica suppliers.
- Chemical Processing:Bulk solids handling in industrial catalysts and pigments drives demand for cost-optimized silicate grades.
- Agriculture:Fertilizer coating and feed additive applications consume mineral carriers with lower purity thresholds than food or drug grades.
Food industry applications hold installed capacity. Pharmaceutical is rotating up the share rankings.
Form:
Physical form selection determines dosing precision, dust exposure, and compatibility with downstream processing equipment.
- Powder:Fine particulate morphology maximizes surface area for moisture adsorption in seasoning blends. Automated dosing systems in Yorkshire manufacturing plants require consistent particle size distribution to prevent bridging in hoppers.
- Granular:Agglomerated structure reduces dust generation during handling. Food manufacturers with open-air mixing operations specify this form to comply with HSE workplace exposure limits.
- Liquid:Dispersed or dissolved anti-caking systems serve specialized coating applications.
- Tablet:Compressed excipient formats enable precise unit-dose addition in pharmaceutical compounding.
Powder forms hold installed capacity. Granular is rotating up the share rankings.
End User:
Customer type segmentation reveals divergent procurement behaviors between specification-driven pharmaceutical buyers and cost-sensitive agricultural suppliers.
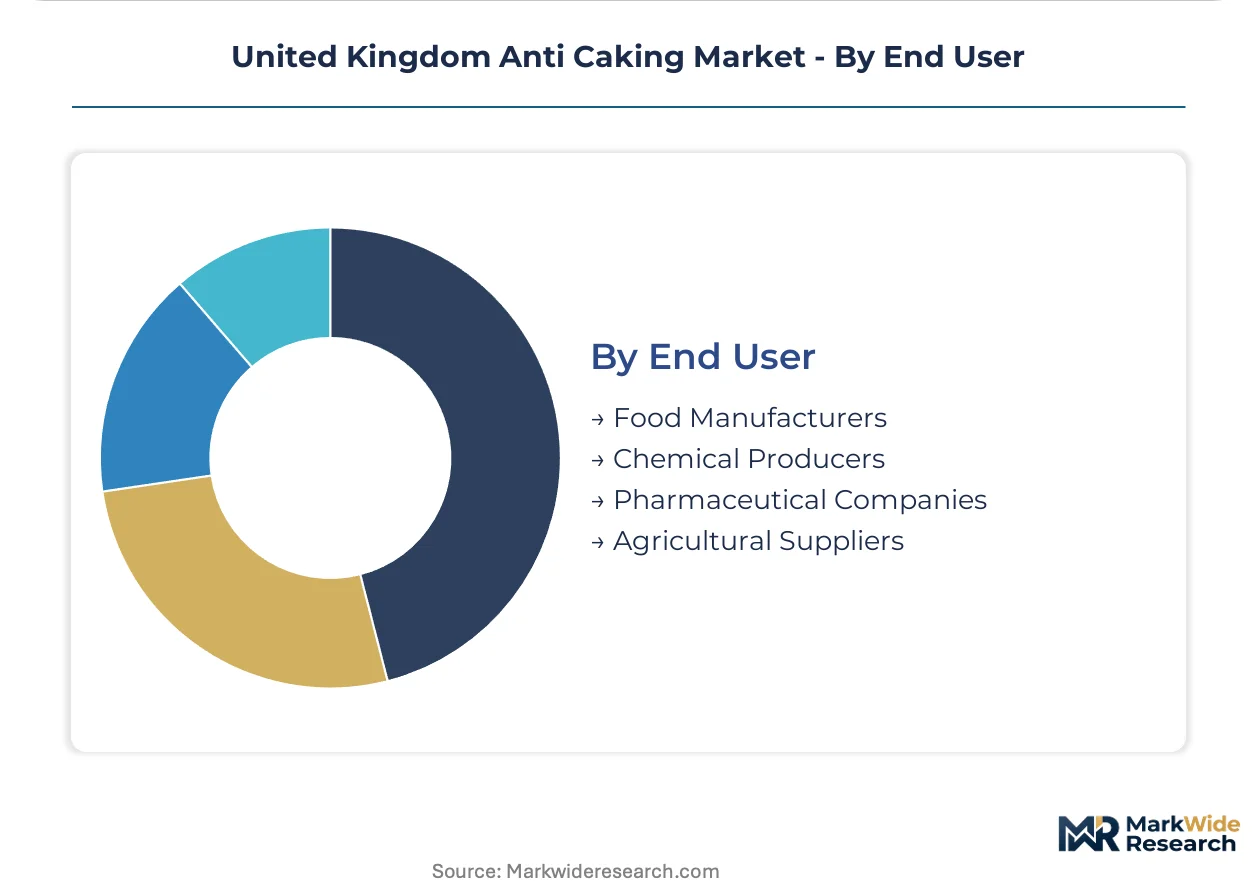
- Food Manufacturers:Large contract manufacturers in England's East Midlands drive consolidation in supplier qualification. Procurement teams now mandate third-party flowability certification prior to contract award.
- Pharmaceutical Companies:NHS supply chain contractors absorb the highest compliance burden for dual UK-EU regulatory pathways. Purity documentation requirements extend approval cycles but protect margin pools.
- Chemical Producers:Industrial buyers prioritize volume pricing and logistics reliability over technical service.
- Agricultural Suppliers:Feed and fertilizer blenders represent price-sensitive demand with minimal formulation support requirements.
Food manufacturers hold installed capacity. Pharmaceutical companies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retained EU food additive regulations enforced by the Food Standards Agency are fragmenting compliance pathways across the United Kingdom's devolved administrations, compelling suppliers to navigate distinct qualification protocols in England, Scotland, Wales, and Northern Ireland.
England
Instant beverage manufacturers in Yorkshire and the East Midlands are scaling sodium silicoaluminate procurement for automated packaging lines. The Food Standards Agency enforces maximum usage levels under retained EU regulations that now diverge from EFSA thresholds. Birmingham and Leicester processing clusters absorb the highest compliance burden as multinational brands consolidate UK-specific formulations.
Scotland
Pharmaceutical contract manufacturers near Glasgow are expanding precipitated silica demand for tablet excipient applications. The country's national pharmaceutical regulator aligns with MHRA guidelines for excipient-grade purity documentation. Scottish tablet manufacturing corridors remain underpenetrated relative to English pharmaceutical volumes, presenting whitespace for specialty chemical distributors.
Wales
Food seasoning blenders in South Wales are adopting granular anti-caking forms to comply with Health and Safety Executive workplace exposure limits. Welsh manufacturing operations benefit from proximity to northwest England sodium silicate feedstock corridors. Cardiff and Newport processing facilities serve as secondary sourcing nodes for English retail brand supply chains.
Northern Ireland
Cross-border food manufacturers face dual UK-EU regulatory qualification as the Windsor Framework shapes additive compliance protocols. Belfast-area processors must maintain separate formulation inventories for Great Britain and Republic of Ireland markets. The region's seasoning and soup mix producers absorb disproportionate administrative costs from divergent maximum usage levels.
Northwest England
Sodium silicate feedstock concentration in Manchester and Liverpool industrial corridors creates geographic vulnerability for national supply chains. REACH documentation administered by the Health and Safety Executive streamlines hazard communication for imported raw materials. Merseyside chemical processing infrastructure anchors domestic silicate derivative production for food and pharmaceutical applications.
United Kingdom Anti Caking Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with captive silicate chemistry platforms, regional distributors with specialized logistics networks, and precipitated silica specialists targeting pharmaceutical-grade margins. Competitive moves concentrate on portfolio diversification into adjacent excipient categories and geographic expansion through distribution partnerships rather than asset-heavy manufacturing investments.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes differentiated by chemistry platform breadth versus specialty silica depth. Norkem occupies a position among regional distributors with England and Scotland coverage networks. PQ Corporation and PPG Industries sit within the industrial silicate producer category, while Huber Engineered Materials represents the engineered minerals specialist archetype. Spectrum Chemical Manufacturing Corp and Bacarel and Company Limited anchor mid-scale supply positions, with H Plus Limited exemplifying the focused UK-based distributor model.
| Leading Market Players |
|---|
| BASF SE |
| Norkem |
| PQ Corporation |
| Bacarel and Company Limited |
| H Plus Limited |
| Spectrum Chemical Manufacturing Corp |
| Evonik Industries AG |
| PPG Industries |
| Huber Engineered Materials |
| Others |
Value Network & Pricing Analysis
Northwest England's sodium silicate corridor concentrates feedstock capacity that feeds downstream pricing power into specialty anti-caking derivative markets. Yorkshire and East Midlands food manufacturers absorb transport cost premiums when sourcing from Manchester-Liverpool production clusters, compressing margins on commodity sodium silicoaluminate grades while pharmaceutical buyers in the East Midlands accept pharmacopeial certification premiums for calcium stearate.
Pricing Analysis
Pharmacopeial certification grade creates the primary spread between pharmaceutical excipient and food-grade anti-caking agents. Three-tier pricing structure across pharmacopeial-certified, food-grade, and industrial mineral tiers reflects purity documentation burdens and dual UK-EU regulatory qualification costs. Cost compression in commodity silicate tiers intensifies because buyer consolidation among East Midlands contract manufacturers shifts procurement toward specification-driven tendering. Agricultural suppliers exhibit highest price sensitivity, while NHS pharmaceutical contractors absorb premium pricing for excipient-grade flow agents with full MHRA documentation trails.
Supply Chain Analysis
Contract manufacturing concentration among East Midlands and Yorkshire food processors shapes national demand aggregation for anti-caking procurement. Domestic supply draws from northwest England silicate chemistry infrastructure, with supplemental sodium silicate feedstock sourced from continental European producers. Raw material dependencies center on sodium silicate, metallic stearate precursors, and precipitated silica intermediates. Single-source vulnerability concentrates in northwest England logistics corridors where regional disruption would cascade through national seasoning and beverage manufacturing. Distribution runs through specialty chemical distributors with England-Scotland coverage networks serving qualified supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between UK Food Standards Agency and EFSA maximum usage levels is disrupting formulation standardization and forcing adaptive compliance investments across England's food processing belt.
For Market Incumbents: Harden dual-formulation capabilities to serve split UK-EU regulatory pathways without cross-border product consolidation. Deepen captive sodium silicate production in northwest England corridors to defend margin position against imported feedstock price volatility. Invest in precipitated silica particle engineering talent pools concentrated among legacy suppliers to protect R&D expansion capacity.
For New Entrants and Emerging Players: Pursue underpenetrated pharmaceutical tablet manufacturing corridors near Glasgow where precipitated silica demand for excipient applications outpaces specialty chemical distributor coverage. Target hybrid clean-label anti-caking systems combining modified starch with mineral carriers to capture premium organic seasoning segments pressuring synthetic silicate volumes. Lead with third-party flowability certification capabilities to displace relationship-based procurement at Yorkshire seasoning blenders.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty silica specialists with pharmacopeial documentation capabilities over commodity silicate producers facing buyer consolidation pressure. Long-term viability rests on regulatory arbitrage skills navigating divergent UK-EU additive frameworks. Acquisition targets should demonstrate precipitated silica formulation expertise and Scottish pharmaceutical corridor access. Watch for Food Standards Agency maximum usage level revisions as signal for compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate Feedstock | Captive supply from Manchester-Liverpool corridors insulates margin from import logistics volatility. |
| Pharmacopeial Certification Investment | MHRA documentation capabilities unlock NHS pharmaceutical contract manufacturer procurement channels. |
| Scottish Distribution Network Expansion | Glasgow pharmaceutical corridor penetration captures whitespace in tablet excipient applications. |
| Clean-Label Hybrid Formulation Development | Modified starch-mineral carrier combinations satisfy East Midlands organic seasoning processor specifications. |
| Asset-Light Reactor Leasing Adoption | Short-term specialty chemical processing equipment access lowers entry barriers for mid-sized formulation specialists. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, procurement leads at East Midlands contract manufacturers, and distribution channel partners anchors the qualitative findings in operational reality. Secondary validation draws from Food Standards Agency additive regulations, Health and Safety Executive REACH documentation, BSI food contact material standards, and trade flow data through UK customs records. Bottom-up demand modeling across Yorkshire and East Midlands processing clusters triangulates against top-down market sizing from supplier capacity disclosures.
Calibration against historical volume trajectories in instant beverage and seasoning segments shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application purity requirements, physical form specifications, and end-user procurement scale. CAGRs derive from trend extrapolation adjusted for regulatory divergence friction and buyer consolidation dynamics. Forecast inputs incorporate sodium silicate feedstock capacity utilization in northwest England corridors and pharmaceutical tablet production expansion near Glasgow.
Sensitivities concentrate around Food Standards Agency maximum usage level revisions, EFSA regulatory divergence acceleration, and natural anti-caking substitution rates in premium organic segments. Forecasts reflect documented assumptions on buyer procurement behavior shifts and dual compliance pathway maintenance costs. Quarterly review of FSA additive regulation updates, NHS pharmaceutical contract awards, and clean-label ingredient adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
North America Food Stabilizers Market