
 Cream of Tartar Market | 2026-2036
Cream of Tartar Market Size, Share, and Industry Trends Forecast 2026-2036
Cream of Tartar Market Outlook
ISO 22000 food safety management certification is reorganizing competitive access in the cream of tartar sector, filtering out smaller processors lacking hazard-controlled supply chains. McCormick & Company leverages its retail brand strength and North American distribution density to dominate consumer-facing channels. Tártaros Gonzalo Castello anchors European supply through its Spanish wine-derivative operations, sustaining cost advantages in tartaric acid sourcing. ATP Group specializes in industrial-grade refinement, competing on volume contracts with chemical manufacturers seeking consistent acidity regulators.
Cream of tartar, the potassium acid salt of tartaric acid (KC₄H₅O₆, minimum 99% purity for food grade), crystallizes from grape must fermentation sediments and functions primarily as a leavening stabilizer, pH buffer, and metal ion chelator in food and pharmaceutical systems. Food-grade product commands the largest value pool due to clean-label bakery demand, while pharmaceutical-grade extraction is accelerating fastest as oral drug formulation standards tighten. Industrial-grade applications in electroplating and construction chemicals represent a mature, price-sensitive segment where margin pools have compressed.
FDA food additive regulations under 21 CFR 184.1077, coupled with REACH chemical registration requirements in Europe and FSSAI purity mandates in India, collectively elevate compliance costs while restricting unqualified market entry. These frameworks push producers toward documented supply chain traceability from wine sediment to final crystallization. Stakeholders must monitor evolving pharmaceutical excipient monographs and regional wine production volumes, as tartaric acid feedstock availability directly constrains capacity expansion decisions.
Market Dynamics
ISO 22000 certification requirements are filtering out smaller cream of tartar processors lacking hazard-controlled supply chains, concentrating production among vertically integrated wine-derivative refiners capable of documented traceability from grape sediment to crystallization.
Growth Catalysts
- FDA Food Safety Modernization Act:Tightening purity standards for food-grade additives push manufacturers toward pharmaceutical-grade processing investments, expanding the addressable premium segment.
- Clean-label bakery demand:Artisanal bread producers and commercial bakeries expand meringue stabilization applications, sustaining food-grade volume pools.
- Craft winemaking clusters:Premium wine regions generate concentrated tartaric acid feedstock, anchoring cost-competitive extraction capacity.
Market Restraints
- Grape must supply concentration:Wine production volatility in key sourcing regions constrains tartaric acid availability, creating feedstock bottlenecks for crystallization capacity.
- REACH registration costs:European chemical compliance burdens elevate entry barriers for industrial-grade producers seeking cross-border market access.
- Baking powder substitution:Sodium acid pyrophosphate and monocalcium phosphate blends displace cream of tartar in cost-sensitive commercial bakery applications.
Strategic Opportunities
- Pharmaceutical excipient expansion:Tightening oral drug formulation standards create pull for USP-grade potassium bitartrate in tablet binders and effervescent systems.
- Indian FSSAI compliance:Purity mandate enforcement opens premium positioning for certified exporters targeting processed food manufacturing growth.
- Electroplating chemical demand:Metal finishing applications in precision electronics manufacturing require consistent acidity regulators, favoring industrial-grade volume contracts.
Industry Challenges
- ISO 22000 certification timelines:Hazard analysis and critical control point documentation requirements extend facility qualification periods, delaying commercial shipments.
- Wine sediment supply integration:Captive sourcing agreements with vineyard cooperatives demand working capital intensity and quality variability management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cream of Tartar Market |
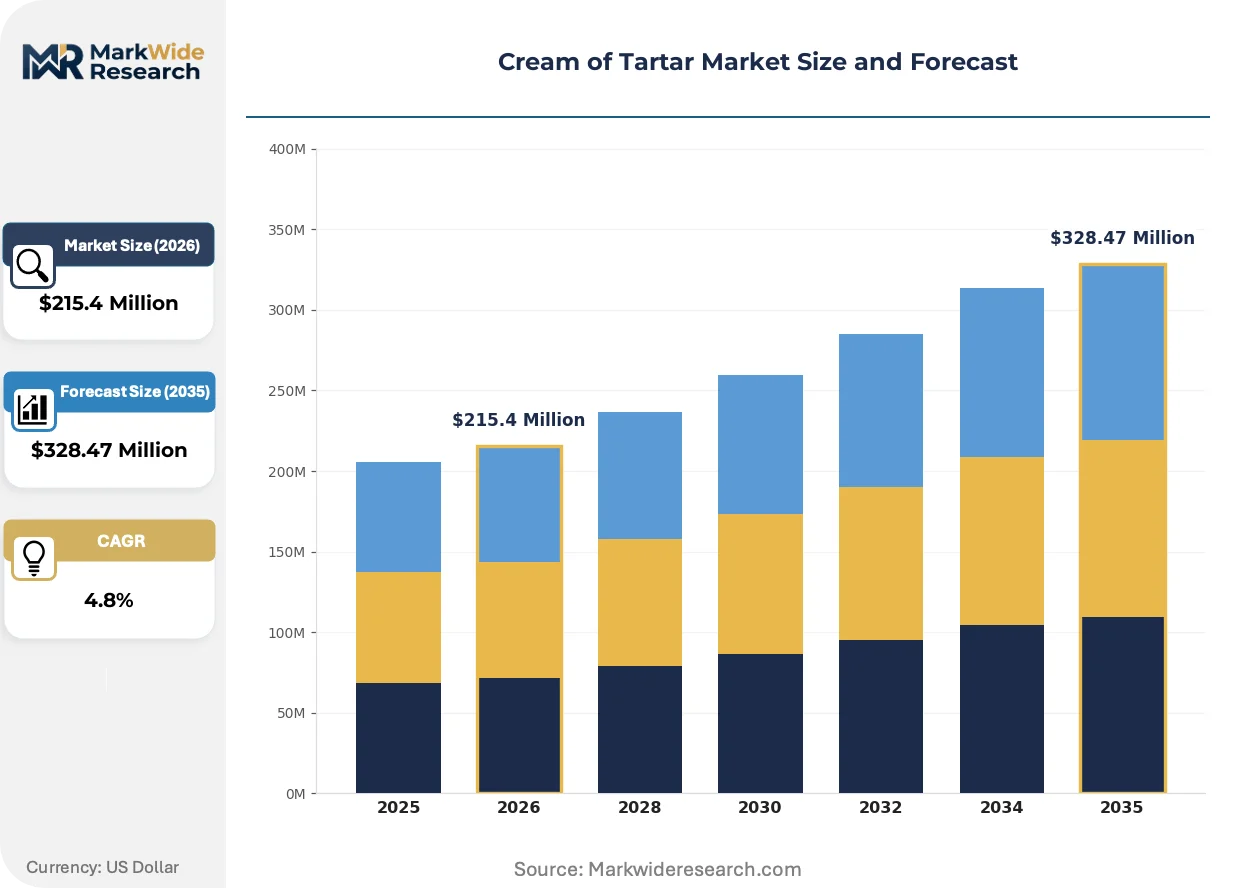
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $328.47 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Laboratory Grade Application: Baking, Food Preservation, Winemaking, Cosmetics End User: Food Producers, Bakeries, Pharmaceutical Companies, Chemical Manufacturers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | McCormick & Company Inc., Tártaros Gonzalo Castello, Newseed Chemical, ATP Group, Foodchem International, Shanghai AiBo Additive, SIP Chemical Industries, GC Chemicals, Alvinesa Natural Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream of Tartar Market Strategic Shifts
Processing technology and certification standards are actively restructuring competitive access in cream of tartar manufacturing, separating pharmaceutical-grade refiners from commodity food-grade processors.
Membrane filtration and continuous crystallization systems are bifurcating the competitive landscape. Pharmaceutical manufacturers adopt these technologies to meet USP monograph standards for excipient purity. This capability divide compresses margins for batch-processors locked in food-grade commodity competition while enabling premium pricing for certified refiners.
REACH chemical registration requirements in Europe are elevating compliance documentation burdens for industrial-grade exporters. Manufacturers must demonstrate supply chain traceability from wine sediment through final crystallization. Food-grade segments face the steepest cost increases as they lack the margin buffers of pharmaceutical-grade producers.
Direct procurement contracts between tartaric acid refiners and pharmaceutical formulators are displacing traditional distributor channels. Large oral drug manufacturers now require excipient lot traceability and certificate of analysis documentation that intermediaries cannot provide. This pattern concentrates most visibly in United States and German pharmaceutical manufacturing clusters.
Cream of Tartar Market Segmentation
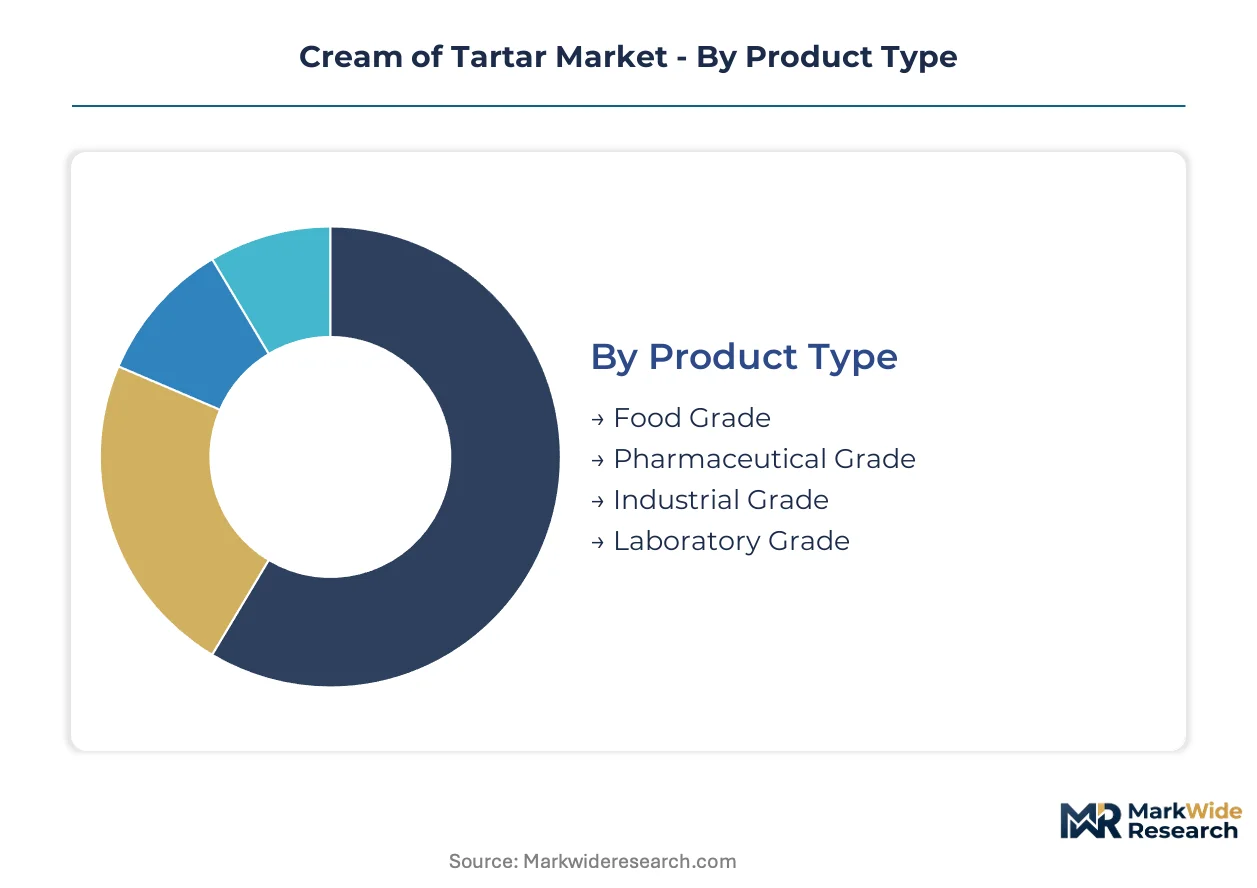
Cream of tartar demand fragments sharply across purity grades and end-use specifications, with substitution economics varying dramatically by application. Pharmaceutical and food-grade segments face divergent competitive pressures from synthetic acidity regulators and alternative stabilizers.
Product Type:
Food-grade and industrial-grade segments confront the most intense substitution pressure from sodium acid pyrophosphate and monocalcium phosphate blends in cost-sensitive applications.
- Food Grade:Minimum 99% purity potassium bitartrate crystallized from wine sediment, functioning as a leavening stabilizer and pH buffer. Clean-label bakery demand in the United States sustains premium positioning despite higher cost relative to synthetic alternatives.
- Pharmaceutical Grade:USP-monograph compliant potassium bitartrate refined through membrane filtration and continuous crystallization. Oral drug manufacturers in German pharmaceutical clusters now require direct procurement contracts with documented lot traceability.
- Industrial Grade:Lower-purity material serving electroplating and construction chemical applications. Metal finishing operations in precision electronics manufacturing demand consistent acidity regulation at compressed margin levels.
- Laboratory Grade:High-purity analytical reagent for research and quality control applications. Academic and industrial R&D facilities require certified reference materials with full certificate of analysis documentation.
Food Grade anchors the volume base while Pharmaceutical Grade gains share at the steepest rate.
Application:
Cost tier differentiation separates artisanal applications commanding premium pricing from commodity food manufacturing where synthetic substitutes dominate.
- Baking:Meringue stabilization and angel food cake leavening in artisanal and commercial bakeries. McCormick retail distribution density in North American consumer channels sustains household penetration despite baking powder competition.
- Food Preservation:pH buffering and metal ion chelation in processed foods. FSSAI purity mandate enforcement in India creates compliance-driven demand for certified exporters.
- Winemaking:Cold stabilization agent for tartrate crystal prevention in premium wine production. Spanish and Italian wine-derivative operations generate captive tartaric acid feedstock for integrated refiners.
- Cosmetics:pH adjustment and emulsion stabilization in personal care formulations. Clean-label beauty trends in French and German cosmetic manufacturing clusters drive specification tightening.
Baking commands the largest absolute volume while Cosmetics exhibits the most rapid specification escalation.
End User:
Customer type determines procurement pattern complexity, with pharmaceutical formulators demanding supply chain documentation that intermediaries cannot provide.
- Food Producers:Processed food manufacturers integrating cream of tartar as a pH buffer and stabilizer. Large-scale operations face persistent sodium acid pyrophosphate substitution pressure in margin-constrained categories.
- Bakeries:Artisanal bread producers and commercial meringue manufacturers prioritizing clean-label positioning. United States craft baking clusters sustain premium-grade consumption despite higher ingredient costs.
- Pharmaceutical Companies:Oral drug formulators requiring USP-grade excipients with certificate of analysis documentation. Direct procurement contracts now displace traditional distributor channels in United States and German manufacturing clusters.
- Chemical Manufacturers:Industrial consumers seeking consistent acidity regulators for electroplating and specialty chemical synthesis. Volume contracts favor refiners with continuous crystallization capacity and documented feedstock traceability.
Food Producers generate the highest shipment volumes while Pharmaceutical Companies drive the steepest margin expansion.
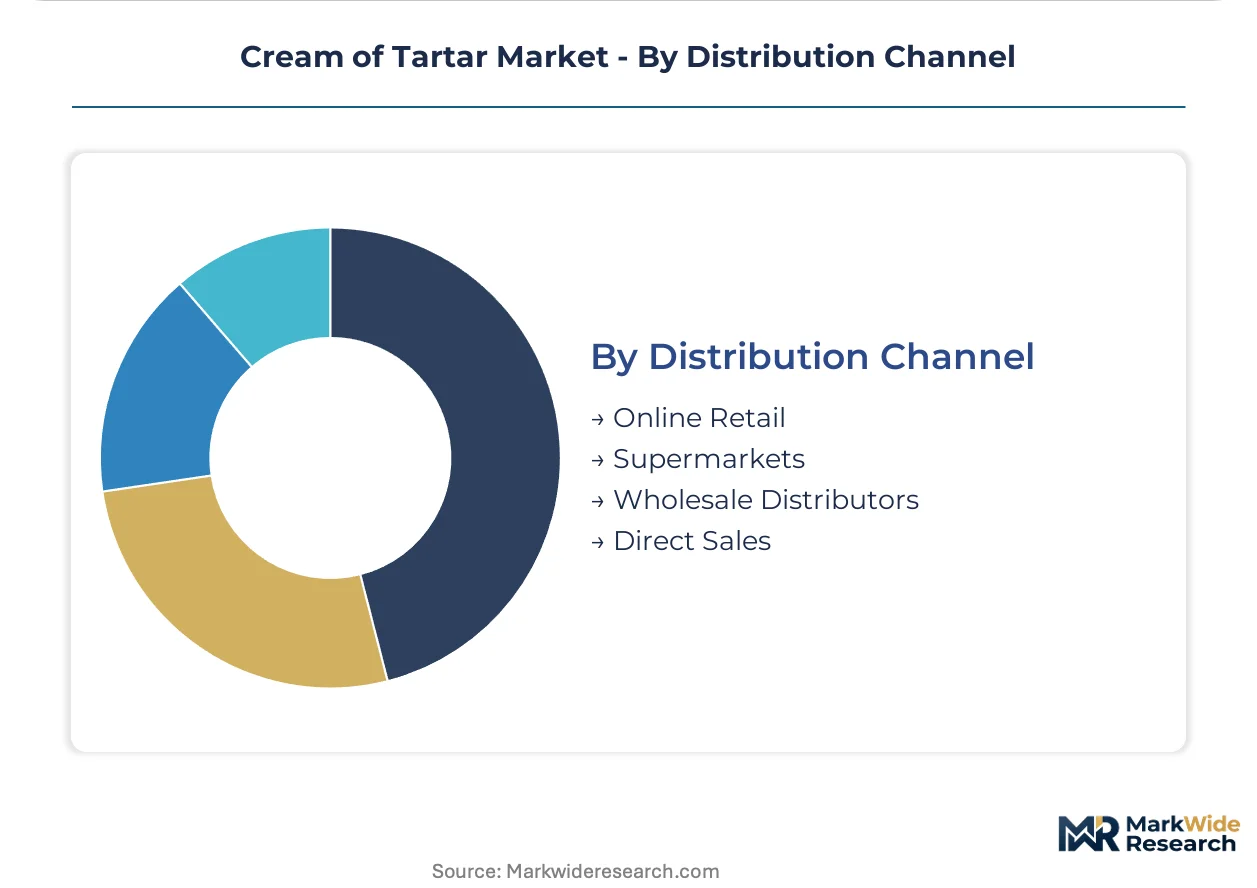
Distribution Channel:
Supply concentration in wine-producing regions dictates channel efficiency, with direct sales gaining ground where lot traceability requirements exclude intermediaries.
- Online Retail:E-commerce platforms serving household bakers and small-scale food producers. North American retail brand strength enables consumer-facing penetration despite shipping cost disadvantages for low-unit-value products.
- Supermarkets:Mass-market retail placement for consumer baking applications. Shelf space competition from private-label baking powder blends constrains premium positioning.
- Wholesale Distributors:Traditional intermediaries serving food manufacturers and industrial users. Pharmaceutical-grade segments bypass this channel as formulators mandate direct refiner relationships.
- Direct Sales:Refiner-to-manufacturer contracts with full documentation and certificate of analysis provision. REACH registration requirements in Europe accelerate this shift for compliance-intensive applications.
Wholesale Distributors retain the broadest reach while Direct Sales climbs fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bakeries and pharmaceutical formulators cluster in distinct geographies, with wine-producing regions anchoring supply-side infrastructure and mature economies driving premium-grade consumption.
United States
Clean-label artisanal bakeries in Brooklyn and San Francisco sustain food-grade demand despite synthetic substitute pressure. FDA Food Safety Modernization Act enforcement tightens purity documentation requirements for imported additives. McCormick's retail distribution density dominates consumer-facing channels, while New Jersey pharmaceutical clusters pull USP-grade material for oral drug formulations.
Spain
Tártaros Gonzalo Castello anchors European supply through wine-derivative operations in La Rioja and Catalonia. REACH chemical registration requirements elevate compliance burdens for industrial-grade exporters seeking cross-border access. Barcelona-area refiners leverage captive tartaric acid feedstock from premium wine regions to sustain cost advantages in crystallization capacity.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and North Rhine-Westphalia now mandate direct procurement contracts with documented lot traceability. EMA excipient monograph standards tighten oral drug formulation specifications, displacing traditional distributor channels. Stuttgart-area chemical refiners invest in membrane filtration systems to meet USP-grade certification thresholds.
India
FSSAI purity mandate enforcement creates compliance-driven demand for certified exporters targeting processed food manufacturing growth in Maharashtra and Gujarat. Mumbai-area bakeries expand meringue stabilization applications amid clean-label trend adoption. Domestic wine production in Nashik generates nascent tartaric acid feedstock for captive refining investments.
China
Shanghai AiBo Additive and regional chemical processors serve electroplating demand from precision electronics manufacturers in the Yangtze River Delta. GB standards for food-grade additives tighten documentation requirements for crystallization facilities. Zhejiang and Jiangsu provinces concentrate industrial-grade capacity serving metal finishing and construction chemical applications.
Cream of Tartar Market Competitive Environment
Player mix skews toward wine-derivative refiners with backward integration into vineyard sediment sourcing. The competitive structure concentrates among three strategic archetypes: retail-branded consumer goods conglomerates, European wine-integrated processors, and Asian industrial chemical specialists. Dominant competitive moves include ISO 22000 certification investments and direct procurement contract displacement of distributor channels.
Among North American consumer-facing players, McCormick & Company represents the retail-brand archetype with established supermarket penetration. Tártaros Gonzalo Castello exemplifies European wine-integrated supply control, anchoring cost-competitive feedstock access. ATP Group occupies a position within industrial-grade refinement, serving volume contracts for electroplating and chemical manufacturing applications.
| Leading Market Players |
|---|
| McCormick & Company Inc. |
| Tártaros Gonzalo Castello |
| Newseed Chemical |
| ATP Group |
| Foodchem International |
| Shanghai AiBo Additive |
| SIP Chemical Industries |
| GC Chemicals |
| Alvinesa Natural Ingredients |
| Others |
Value Chain & Pricing Dynamics
Sodium acid pyrophosphate displacement in cost-sensitive commercial baking simultaneously redraws procurement geography toward synthetic acidifier hubs and compresses margin pools for wine-derivative refiners locked in food-grade commodity competition.
Pricing Analysis
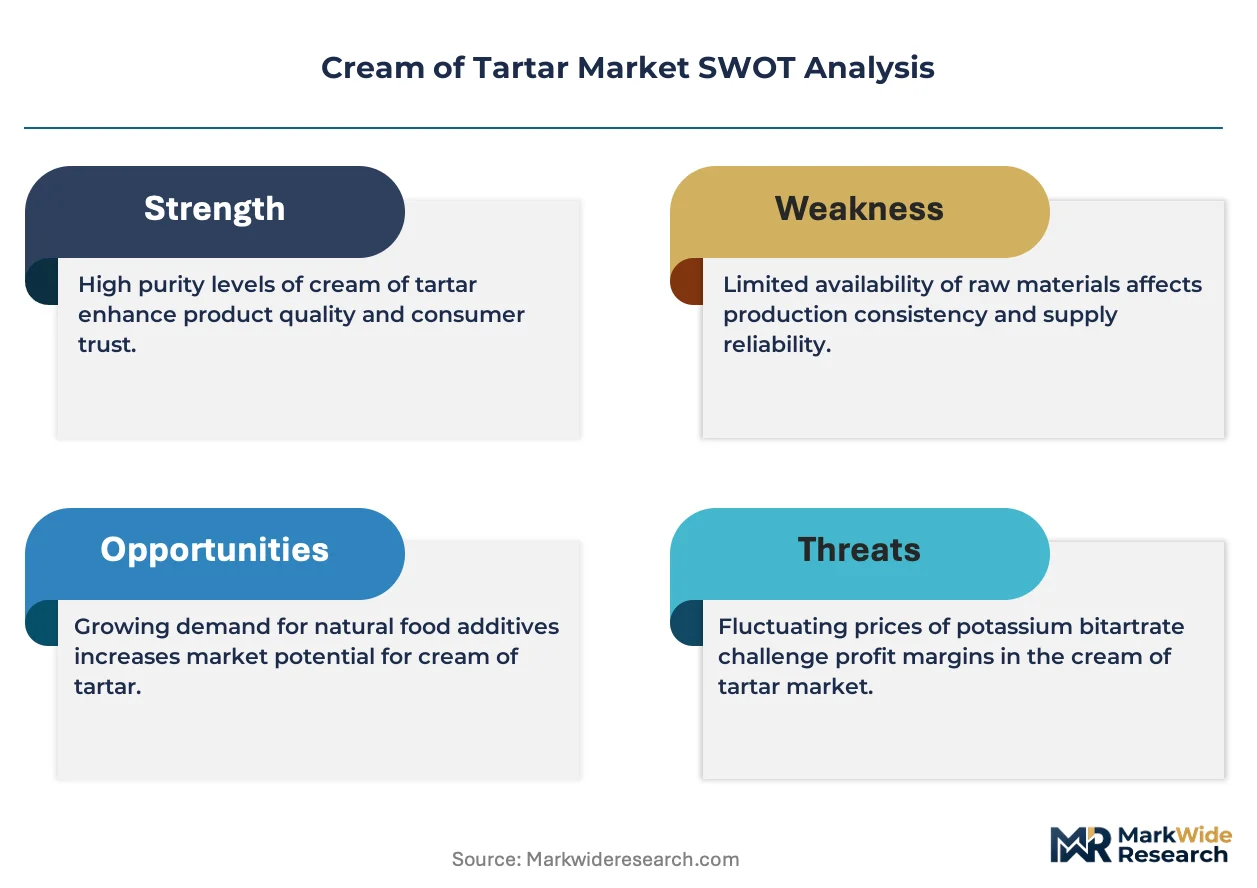
Cost-plus contracts with tartaric acid feedstock indexation dominate industrial-grade volume agreements, while pharmaceutical-grade material commands fixed-price premiums tied to USP certification tiers. Price differentiation rests on ISO 22000 documentation depth and membrane filtration capability, separating certified refiners from batch processors. Pricing pressure stems from baking powder substitution in mass-market bakery applications, where sodium acid pyrophosphate blends undercut potassium bitartrate on unit economics. Food producers exhibit highest price sensitivity due to thin margin structures, whereas pharmaceutical formulators absorb premiums for documented lot traceability.
Supply Chain Analysis
Strategic stockpiling of wine sediment concentrates in La Rioja and Catalonia coexists with just-in-time crystallization scheduling for pharmaceutical-grade contracts. Geographic supply concentrates in Spain, Italy, and the United States, drawing from premium wine region sediment deposits. Raw material dependencies include grape must availability, tartaric acid extraction yield, and crystallization energy inputs. Single-source vulnerability runs through vineyard cooperative agreements in concentrated wine belts. Distribution runs through direct refiner-to-manufacturer contracts for pharmaceutical segments, with wholesale distributors retaining food-grade channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical formulators and certified food manufacturers as procurement consolidation eliminates distributor intermediaries demanding documented supply chain traceability.
For Market Incumbents: Consolidate backward control over vineyard sediment sourcing through captive cooperative agreements in La Rioja and Catalonia to defend against tartaric acid feedstock volatility. Expand membrane filtration capacity to capture USP-grade premium pools as FDA and EMA excipient standards tighten. Channel control through direct procurement contracts with German and United States pharmaceutical clusters anchors margin defense against commodity food-grade erosion. For New Entrants and Emerging Players: Documentation-as-a-service gaps in certificate-of-analysis provision for mid-tier food manufacturers present white-space entry points. Target Indian FSSAI compliance-driven demand in Maharashtra and Gujarat processed food corridors, where certified exporter shortages create procurement bottlenecks. Go-to-market leverage rests on ISO 22000 certification investment ahead of facility qualification timelines that delay incumbent expansion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European wine-integrated refiners holding captive sediment sourcing but lacking pharmaceutical-grade filtration infrastructure. Long-term viability over a multi-year horizon favors targets with documented vineyard cooperative agreements and USP-monograph compliance pathways. The signal to watch is EMA excipient monograph revision timing, which would accelerate direct procurement contract displacement and concentrate value in certified refining capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vineyard Sediment Sourcing | Captive supply agreements in La Rioja and Catalonia insulate against tartaric acid feedstock volatility. |
| Membrane Filtration Capacity Expansion | USP-grade certification thresholds in German pharmaceutical clusters demand continuous crystallization systems. |
| ISO 22000 Certification Investment | FDA Food Safety Modernization Act enforcement filters out hazard-uncontrolled processors from food-grade supply. |
| Direct Procurement Contract Displacement | Pharmaceutical formulators in New Jersey and Baden-Württemberb now mandate refiner relationships bypassing distributors. |
| Indian FSSAI Compliance Positioning | Purity mandate enforcement in Maharashtra and Gujarat opens premium positioning for certified exporters. |
Study Parameters
Desk research of wine industry production databases, tartaric acid trade flows, and pharmaceutical excipient monograph filings preceded structured interviews with plant managers at wine-derivative refiners, procurement leads at commercial bakeries, regulatory affairs specialists at FDA-registered facilities, and technical R&D directors at electroplating chemical manufacturers. Secondary validation drew from customs records, REACH registration databases, and FSSAI compliance disclosures. Bottom-up crystallization capacity modeling and top-down end-use demand estimation were triangulated against cross-referenced primary intelligence.
Variance decomposition across grade tier, end-use application, and regional production hub shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectory modeling and value-per-unit escalation patterns. Wine production volatility in key sourcing regions and pharmaceutical excipient standard revision timing served as industry-specific forecast inputs throughout the modeling period.
Underlying assumptions cover sustained tartaric acid feedstock availability from premium wine regions, with deviation risk concentrated in climate-induced harvest variability and regulatory acceleration of purity documentation requirements. Revision becomes warranted when grape must supply disruption crosses thresholds that trigger crystallization capacity idling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Nutraceutical Excipients Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Japan Food Enzymes Market