
 Sugar Reduction Technology Market | 2026-2036
Sugar Reduction Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Reduction Technology Market Analytics
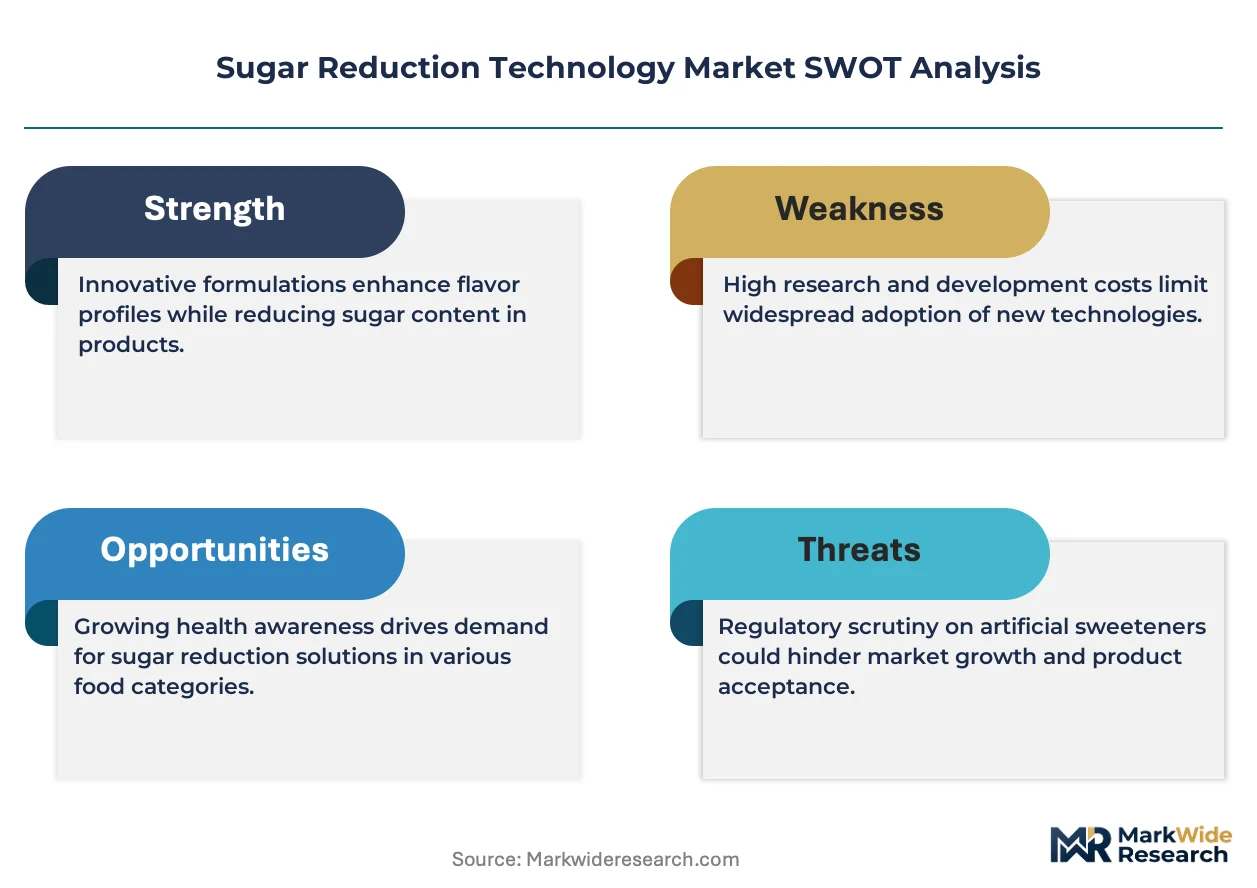
ISO 22000 certification is reorganizing competitive access for ingredient suppliers seeking entry into multinational food and beverage supply chains. Cargill Incorporated leverages its integrated agricultural supply chain to sustain cost advantages in natural sweetener sourcing. Tate & Lyle PLC anchors its position through specialized fermentation-derived solutions for beverage applications. Ingredion Incorporated differentiates via enzymatic processing capabilities that deliver clean-label sugar reduction across dairy and bakery segments.
Sugar reduction technology encompasses physical, chemical, and biological processes that modify or replace sucrose and other caloric sweeteners in formulated foods, including enzymatic conversion parameters, fermentation-derived molecule purity thresholds, and filtration-based taste modulation systems. Its primary commercial purpose is enabling manufacturers to achieve target sweetness profiles while meeting nutritional claims and regulatory thresholds for added sugars. Natural sweeteners occupy the largest current revenue pool due to clean-label positioning, though novel sweeteners represent the fastest-expanding category as precision fermentation yields improve. Beverage applications lead volume demand given high reformulation frequency, while confectionery presents concentrated margin opportunities due to technical complexity in texture preservation.
The FDA enforces added-sugar disclosure and nutrient content claims that directly shape product development priorities for domestic manufacturers. EFSA and the EU Green Deal framework impose parallel requirements across European markets, creating dual compliance burdens for exporters. Food manufacturers and beverage companies must monitor evolving WHO sugar intake guidelines and anticipate how municipal tax regimes in countries including Mexico and the United Kingdom will expand to additional product categories.
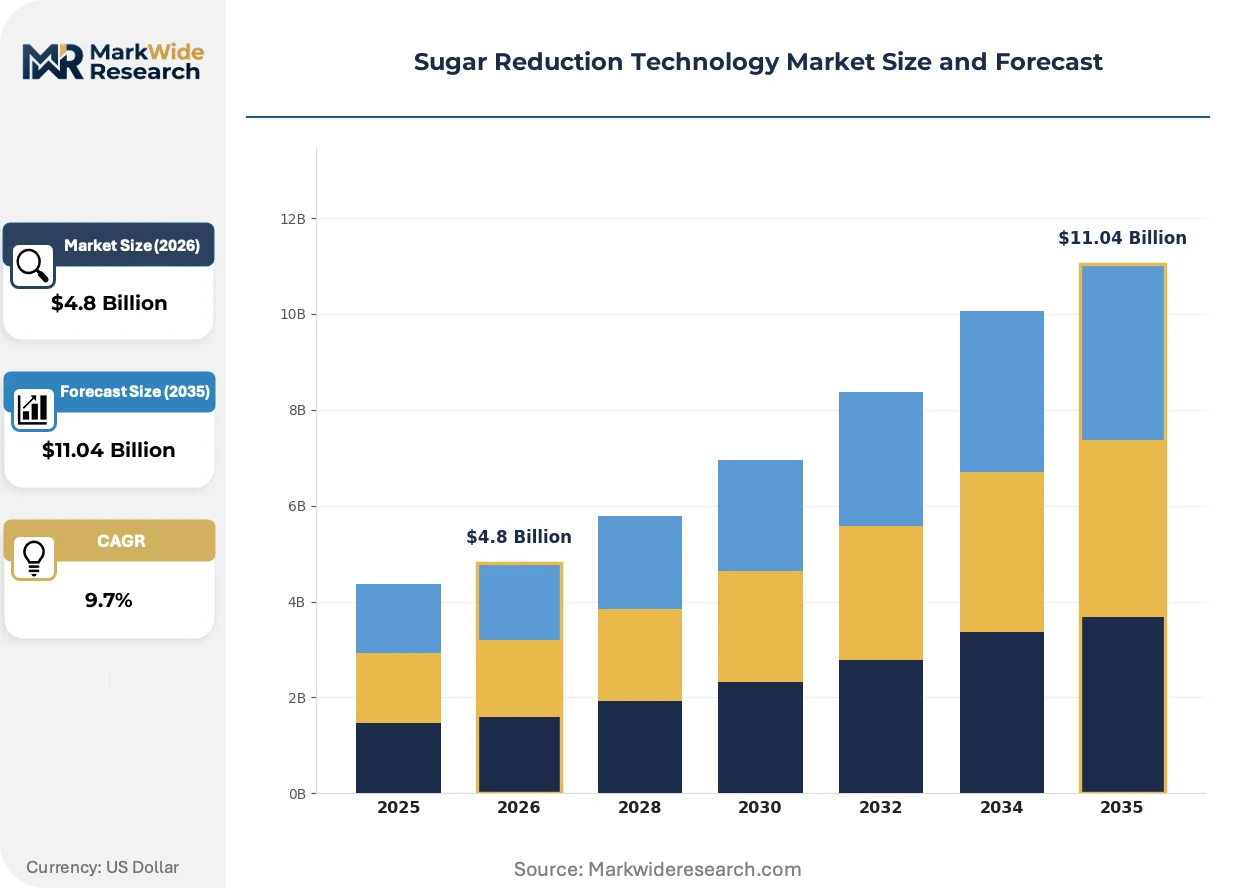
Market Dynamics
FDA's added-sugar disclosure mandates and municipal sugar tax proliferation are compressing reformulation timelines, forcing beverage and confectionery manufacturers to accelerate adoption of enzymatic conversion and fermentation-derived alternatives.
Growth Catalysts
- Clean-Label Consumer Preference:Shoppers scrutinize ingredient panels, prioritizing recognizable natural sweeteners over synthetic alternatives in carbonated beverages and functional drinks.
- Municipal Sugar Tax Expansion:Philadelphia, Seattle, and Boulder impose per-ounce levies on sugar-sweetened beverages, compelling manufacturers to reduce caloric content.
- Precision Fermentation Yield Improvements:Novel sweetener production costs decline as microbial strain optimization and bioreactor efficiency advance.
Market Restraints
- Stevia Supply Concentration:Raw leaf sourcing clusters in China, exposing processors to climate volatility and trade friction.
- Texture Preservation Complexity:Bulk sugar replacement disrupts crystallization and mouthfeel in chocolate and hard candy applications.
- Dual Compliance Burden:EFSA novel food authorization timelines conflict with FDA GRAS self-determination, delaying cross-Atlantic product launches.
Strategic Opportunities
- Dairy Segment Underpenetration:Flavored milk and yogurt applications lag beverages in reformulation intensity, offering first-mover advantages.
- EU Green Deal Procurement Incentives:Public sector foodservice contracts increasingly specify reduced-sugar nutritional profiles.
- Enzymatic-Blending Convergence:Combining enzymatic conversion with fiber-based bulking agents enables deeper sugar reduction without sensory trade-offs.
Industry Challenges
- ISO 22000 Certification Timelines:Ingredient suppliers face 12-18 month audit cycles to access multinational food and beverage supply chains.
- Flavor Masking Expertise Scarcity:Off-notes from high-intensity sweeteners require specialized sensory scientists and formulation chemists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Reduction Technology Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sweeteners, Artificial Sweeteners, Sugar Alcohols, Novel Sweeteners Application: Beverages, Dairy Products, Bakery Items, Confectionery Technology: Fermentation Technology, Enzymatic Processing, Filtration, Chemical Synthesis End User: Food Manufacturers, Beverage Companies, Restaurants, Retailers |
| Companies Covered | Cargill Incorporated, Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères, ADM, Kerry Group PLC, DouxMatok, Givaudan, Südzucker AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Reduction Technology Market Evolving Landscape
Reformulation science is advancing along three distinct vectors: precision biotechnology, regulatory arbitrage, and procurement model transformation. Each vector reshapes competitive positioning differently.
Precision fermentation platforms for rare sugar production are bifurcating the ingredient supply base. Large beverage manufacturers integrate captive bioreactor capacity for allulose and tagatose, while mid-tier formulators rely on toll manufacturers. This technology is bifurcating price structures between integrated producers and merchant market dependents.
EFSA's 2023 updated guidance on novel food safety assessments compresses evaluation windows for fermentation-derived sweeteners. Manufacturers pre-submit dossiers to secure Union-wide authorization ahead of national implementations. Confectionery exporters to Germany and France accelerate dossier preparation to maintain shelf presence.
Direct ingredient sourcing from biotechnology developers is displacing traditional distributor relationships in North American beverage procurement. Large reformulators negotiate multi-year offtake agreements with precision fermentation startups, bypassing conventional ingredient houses. This pattern concentrates in California and Texas, where clean-label beverage startups cluster near biotech R&D hubs.
Sugar Reduction Technology Market Segmentation
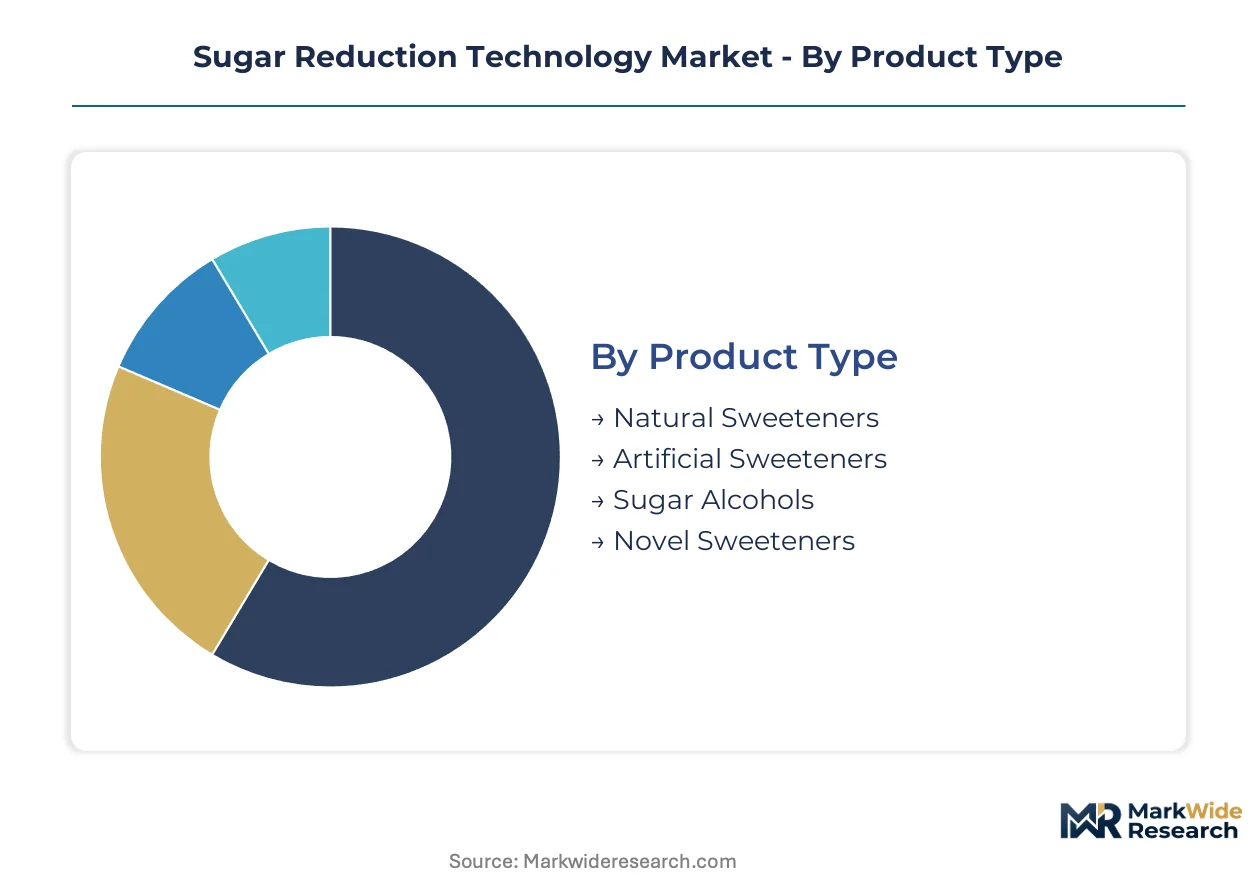
Sugar reduction technology segments reflect divergent supply chain configurations and regulatory exposure profiles. Product type and technology choices determine whether suppliers serve domestic reformulation demand or navigate export authorization complexity. Application focus shapes margin structures and customer concentration risk.
Product Type:
Domestic U.S. demand concentrates in naturally positioned ingredients, while export-led growth depends on novel sweetener approvals across EFSA jurisdictions.
- Natural Sweeteners:Stevia, monk fruit, and allulose extracted from botanical sources dominate clean-label positioning. Beverage manufacturers in the United States absorb the majority of supply as municipal sugar taxes compress reformulation timelines. Supply concentration in Chinese leaf sourcing creates vulnerability to climate volatility and tariff friction.
- Novel Sweeteners:Precision fermentation-derived molecules including tagatose and rare sugars achieve deeper caloric reduction without sensory trade-offs. European authorization timelines under EFSA novel food procedures currently constrain export volumes, though dossier pre-submission is accelerating. Yield improvements in microbial strain optimization are compressing production costs fastest in this category.
- Artificial Sweeteners:Sucralose, aspartame, and acesulfame potassium maintain cost advantages in price-sensitive applications.
- Sugar Alcohols:Erythritol, xylitol, and maltitol serve bulk replacement needs in confectionery texture preservation.
Natural sweeteners command the established base. The steepest expansion runs through novel sweeteners.
Application:
Volume concentration and margin profiles diverge sharply across end-use categories, with reformulation frequency determining technology adoption intensity.
- Beverages:Carbonated drinks, functional waters, and ready-to-drink teas require the highest reformulation frequency due to direct consumer taste evaluation and sugar tax exposure. Philadelphia, Seattle, and Boulder municipal levies force continuous formulation iteration. Enzymatic conversion and fermentation-derived solutions scale most efficiently in liquid processing environments.
- Confectionery:Chocolate, hard candy, and chewing gum present concentrated margin opportunities offset by technical complexity in crystallization control and mouthfeel preservation. European exporters to Germany and France prioritize texture-preserving bulk replacements to maintain shelf presence under EU Green Deal procurement specifications.
- Dairy Products:Flavored milk and yogurt applications lag beverages in reformulation intensity, creating first-mover positioning potential.
- Bakery Items:Bread, cakes, and pastries balance sugar reduction with Maillard reaction requirements and shelf-life extension.
Beverages anchor volume demand. Confectionery captures premium margin expansion.
Technology:
Capital intensity and regulatory pathway length separate integrated producers from toll-dependent formulators across processing methods.
- Fermentation Technology:Precision bioreactor platforms produce rare sugars and novel molecules with high purity thresholds. Large beverage manufacturers are integrating captive capacity in California and Texas near biotech R&D clusters, while mid-tier formulators rely on toll manufacturers with ISO 22000 certification.
- Enzymatic Processing:Enzyme-catalyzed conversion of starch substrates enables clean-label sugar reduction with fiber-based bulking agent compatibility. Dairy and bakery segments favor this approach for its processing efficiency and sensory neutrality.
- Filtration:Membrane-based taste modulation systems remove bitter compounds from high-intensity sweetener blends.
- Chemical Synthesis:Traditional catalytic routes persist in artificial sweetener production for cost-sensitive applications.
Fermentation technology attracts the deepest capital commitment. Enzymatic processing expands most quickly across dairy and bakery penetration.
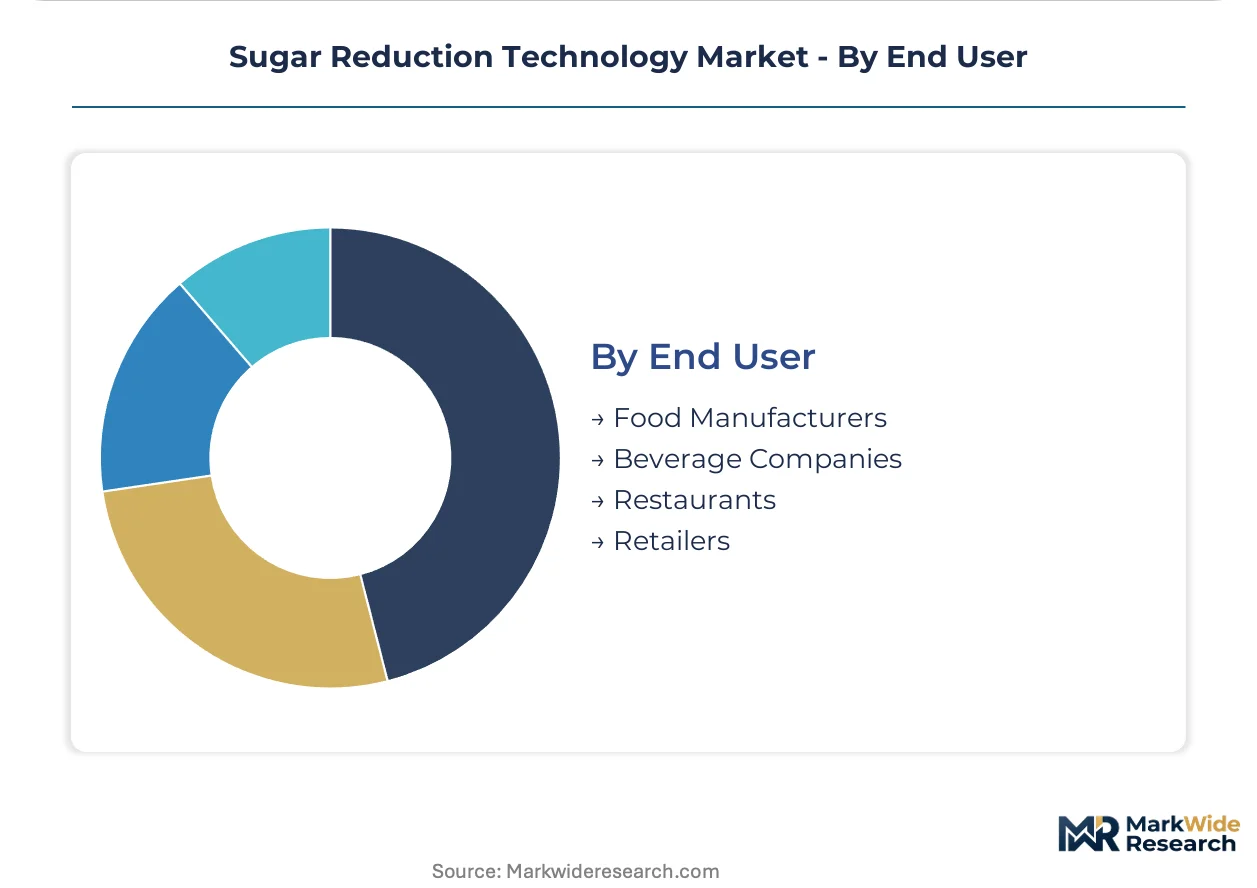
End User:
Procurement sophistication and supply chain access requirements stratify customers across four distinct organizational types.
- Food Manufacturers:Multinational packaged goods companies with direct biotechnology developer relationships and multi-year offtake agreements. These buyers bypass conventional ingredient distributors, concentrating procurement leverage in North America.
- Beverage Companies:Carbonated and functional drink specialists with the most compressed reformulation timelines due to FDA added-sugar disclosure mandates and municipal tax exposure.
- Restaurants:Foodservice operators responding to EU Green Deal public sector contract specifications for reduced-sugar nutritional profiles.
- Retailers:Private-label product developers with price-sensitive positioning and distributor-dependent supply access.
Food manufacturers and beverage companies dominate technology adoption. Restaurant procurement is gaining share fastest under sustainability-linked contract requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal sugar taxes and FDA disclosure mandates compress reformulation timelines across multiple jurisdictions. Beverage manufacturers navigate divergent regulatory pathways while seeking clean-label positioning advantages. Geographic concentration reflects proximity to biotechnology R&D clusters and precision fermentation infrastructure.
United States
Philadelphia, Seattle, and Boulder impose per-ounce levies on sugar-sweetened beverages, forcing continuous formulation iteration. FDA added-sugar disclosure requirements on updated Nutrition Facts labels directly shape product development priorities. California and Texas biotech R&D clusters host captive bioreactor capacity for allulose and tagatose production.
Germany
Confectionery exporters prioritize texture-preserving bulk replacements to maintain shelf presence under EU Green Deal procurement specifications. EFSA novel food authorization timelines compress evaluation windows for fermentation-derived sweeteners. Industrial concentration in North Rhine-Westphalia supports enzymatic processing scale-up for dairy and bakery applications.
United Kingdom
The Soft Drinks Industry Levy drives reformulation across carbonated and functional beverage categories. WHO sugar intake guidelines inform domestic public health procurement standards. Greater London hosts direct sourcing negotiations between large reformulators and precision fermentation startups.
France
ANSM and DGCCRF enforcement of EU nutrition claims shapes clean-label positioning strategies. Public sector foodservice contracts increasingly specify reduced-sugar nutritional profiles under national sustainability frameworks. Paris-region headquarters of major ingredient houses anchor European distribution networks.
China
Stevia leaf sourcing concentration exposes processors to climate volatility and trade friction. SAMR implementation of GB standards for food additives creates compliance complexity for imported novel sweeteners. Zhejiang and Shandong provinces host extraction and processing infrastructure for natural sweetener supply.
Sugar Reduction Technology Market Competitive Landscape
Player mix skews toward integrated agricultural processors and specialized fermentation houses. The supplier base organizes around three archetypes: captive bioreactor operators, toll-dependent enzyme processors, and botanical extraction specialists. Scale advantages concentrate with backward-integrated agricultural networks. Competitive moves center on multi-year offtake agreements and ISO 22000 certification acceleration.
Among North American integrated processors, Cargill Incorporated and Ingredion Incorporated exemplify cost-advantaged sourcing positions through upstream agricultural control. Tate & Lyle PLC represents the specialized fermentation archetype with European regulatory dossier expertise. These three anchors demonstrate how supply chain configuration determines access to multinational beverage and confectionery procurement channels.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Roquette Frères |
| ADM |
| Kerry Group PLC |
| DouxMatok |
| Givaudan |
| Südzucker AG |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates supply qualification and price differentiation simultaneously, creating tiered access where certified fermentation houses command premiums over uncertified botanical processors while municipal sugar taxes compress buyer willingness to absorb cost increases.
Pricing Analysis
Certification level creates the primary spread, with ISO 22000-accredited suppliers capturing premium positioning over uncertified competitors in beverage procurement channels. Three-tier pricing structure across premium fermentation-derived, standard enzymatic-conversion, and economy-grade artificial sweetener tiers reflects purity thresholds and regulatory dossier completeness. Pricing pressure stems from yield improvements in precision fermentation compressing novel sweetener production costs fastest. Beverage companies show highest price sensitivity due to municipal tax exposure, while confectionery manufacturers absorb premiums for texture-preserving bulk replacements.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for Chinese stevia leaf shipments, exposing processors to working capital pressure. Supply concentrates in China for botanical extraction, the United States for precision fermentation infrastructure, and Germany for enzymatic processing scale-up. Raw material dependencies include stevia leaf, corn starch substrates, and microbial strains for bioreactor cultivation. Single-source vulnerability runs through Chinese stevia sourcing given climate volatility and tariff exposure. Distribution runs through direct multi-year offtake agreements between large reformulators and biotechnology developers, displacing traditional ingredient distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor masking services and sensory formulation consulting attach to hardware ingredient sales at margins expanding faster than commodity sweetener supply, as off-note management becomes the critical bottleneck in high-intensity sweetener adoption.
For Market Incumbents: Secure captive bioreactor capacity in California and Texas biotech clusters before precision fermentation yield improvements commoditize merchant market supply. Accelerate ISO 22000 certification timelines to 12-month cycles to defend distributor bypassing by large beverage manufacturers. Backward integration into microbial strain development protects margin compression from toll-dependent positioning. For New Entrants and Emerging Players: FDA GRAS self-determination fast-track offers entry velocity unmatched by EFSA novel food authorization timelines, enabling US market proof points before European dossier submission. Dairy applications present the most penetrable white space, with flavored milk and yogurt reformulation intensity lagging beverages by several adoption cycles. Direct sourcing partnerships with clean-label beverage startups near biotech R&D hubs provide the strongest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation sub-segments as bioreactor efficiency advances and strain optimization matures. Long-term viability favors acquisition targets with captive capacity and direct reformulator relationships over distributor-dependent merchant models. The signal to watch is municipal sugar tax expansion into confectionery categories, which would re-rate texture-preserving technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Offtake Agreement | Bypasses traditional distributors and locks in precision fermentation supply for beverage reformulators. |
| ISO 22000 Certification Acceleration | Opens multinational food and beverage supply chains previously blocked to uncertified ingredient suppliers. |
| EFSA Novel Food Dossier Pre-Submission | Secures Union-wide authorization ahead of national implementations for European confectionery exporters. |
| Enzymatic-Fiber Blending Convergence | Enables deeper sugar reduction in dairy and bakery without sensory trade-offs for clean-label positioning. |
| Captive Bioreactor Capacity Buildout | Concentrates production gravity near California and Texas biotechnology R&D clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with beverage formulation chemists, sensory scientists, regulatory affairs directors, and precision fermentation operations leads; and secondary validation through FDA GRAS notices, EFSA novel food registers, municipal sugar tax ordinance databases, and trade flow records. Bottom-up triangulation across ingredient procurement volumes and top-down cross-checks against reformulation frequency in taxed jurisdictions anchored the quantitative framework.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, application category, processing technology, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of precision fermentation yield curves, enzymatic conversion efficiency improvements, and regulatory timeline compression effects. Industry-specific forecast inputs included municipal sugar tax expansion trajectories and EFSA evaluation window updates.
Decision-makers should treat outputs as directional under assumptions of continued FDA disclosure enforcement and stable Chinese stevia leaf supply; material deviation would warrant model refresh. Specific risk factors include trade friction disrupting botanical sourcing and EFSA authorization delays constraining novel sweetener export volumes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Chocolate Wax Market