
 Europe Plastic Packaging Market | 2026-2036
Europe Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plastic Packaging Market Analysis
Poland is narrowing the cost gap with Western European converters through automated extrusion lines and proximity to German brand owners. Amcor PLC leverages its multi-layer film technology to sustain pharmaceutical barrier contracts across the continent. Berry Global anchors rigid container supply for dairy and prepared-meal segments through its Central European molding network.
Europe plastic packaging encompasses thermoformed, extruded, and molded polymer structures—typically ranging from 10 microns in flexible films to 2 millimeters in rigid containers—engineered to protect, preserve, and present consumer and industrial goods. Bottles and containers dominate value capture in beverage and pharmaceutical channels where oxygen transmission rates below 0.5 cc/m²/day determine shelf-life performance. Flexible packaging in food service and e-commerce applications leads volume expansion as mono-polyethylene laminates replace multi-material formats to satisfy EU recyclability mandates.
EMA pharmaceutical packaging guidelines, the EU Packaging and Packaging Waste Regulation, and REACH chemical compliance frameworks collectively mandate recyclability thresholds and substance restrictions that reshape material selection across converters. ECHA substance evaluations and national extended producer responsibility schemes in Germany and France are forcing reformulation of polyvinyl chloride and polystyrene grades. Stakeholders must decide whether to prioritize mechanical recycling compatibility or invest in chemical recycling infrastructure before the next regulatory enforcement phase tightens market access.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a wholesale restructuring of material specifications across European converters, collapsing demand for multi-layer laminates while accelerating investment in mono-material extrusion lines and chemical recycling infrastructure.
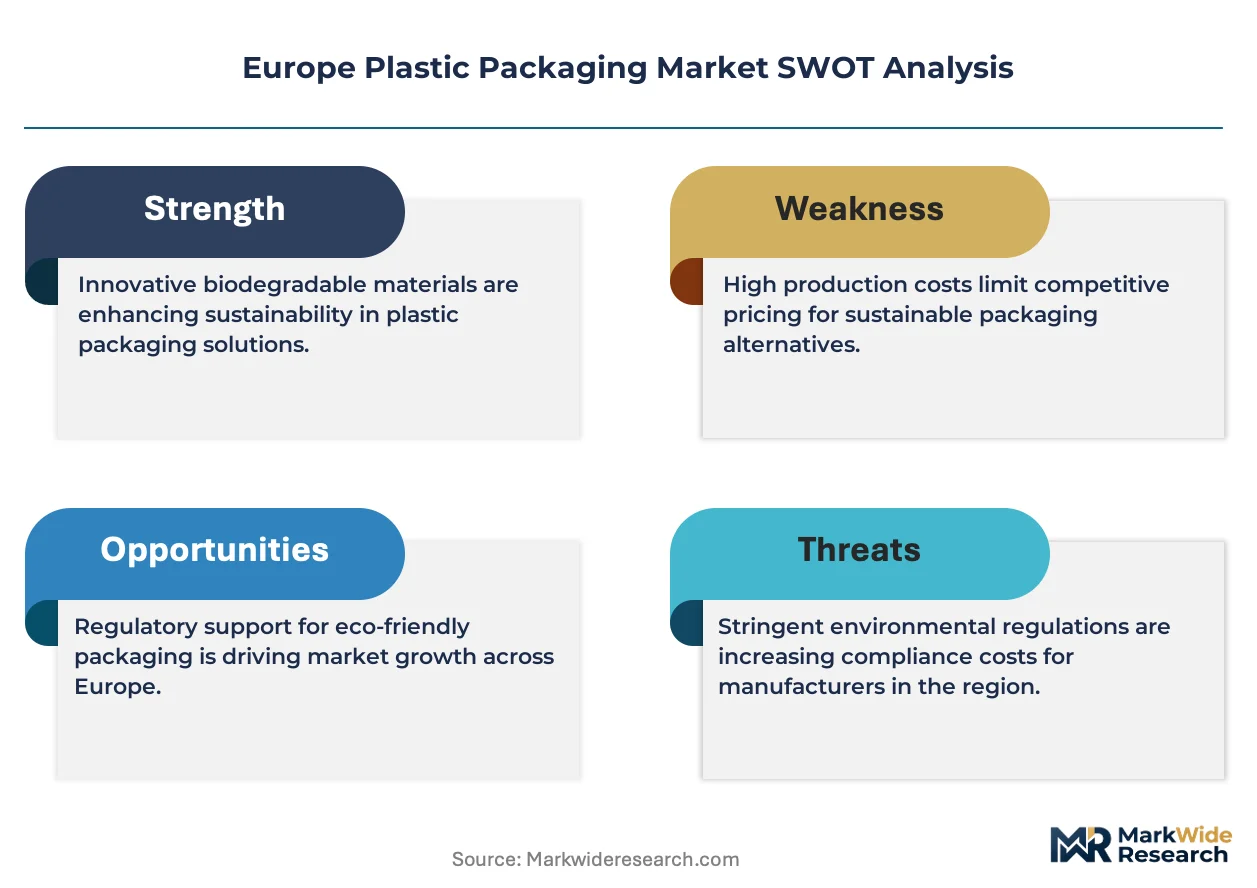
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds are redirecting R&D budgets toward mono-polyethylene and mono-polypropylene structures that qualify for mechanical recycling streams.
- Fresh-produce retail modernization:French and Italian supermarket chains are specifying modified-atmosphere barrier films with sub-1 cc/m²/day oxygen transmission rates to extend shelf life.
- Pharmaceutical serialization mandates:EMA guidelines on track-and-trace compliance are expanding demand for high-barrier blister packs and vial containment systems across the continent.
Market Restraints
- Feedstock cost volatility:European naphtha crackers remain exposed to natural gas price swings that compress converter margins on commodity polyethylene grades.
- Technical recycling limitations:Current mechanical recycling infrastructure cannot process printed or metallized flexible films, creating stranded volumes of otherwise recoverable material.
- ECHA substance restrictions:Evaluations of phthalate plasticizers and certain flame retardants are forcing reformulation of PVC and polystyrene grades used in medical and food-contact applications.
Strategic Opportunities
- Central European production clusters:Poland and the Czech Republic offer automated extrusion capacity at cost structures 15-20% below Western European equivalents, with rail links to German brand owners.
- Chemical recycling scale-up:Pyrolysis and depolymerization investments in the Netherlands and Belgium will unlock processing of contaminated flexible films currently rejected by mechanical recyclers.
- E-commerce protective formats:Expansion of insulated pouch and air-cushion demand for temperature-sensitive pharmaceutical delivery creates new specification opportunities for foam-in-place and bubble laminates.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with expertise in barrier layer design and compatibilizer systems are concentrated among a handful of Western European research institutes.
- Legacy equipment retrofit costs:Converters operating decade-old co-extrusion lines face capital intensity of €2-4 million per line to achieve mono-material output specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plastic Packaging Market |
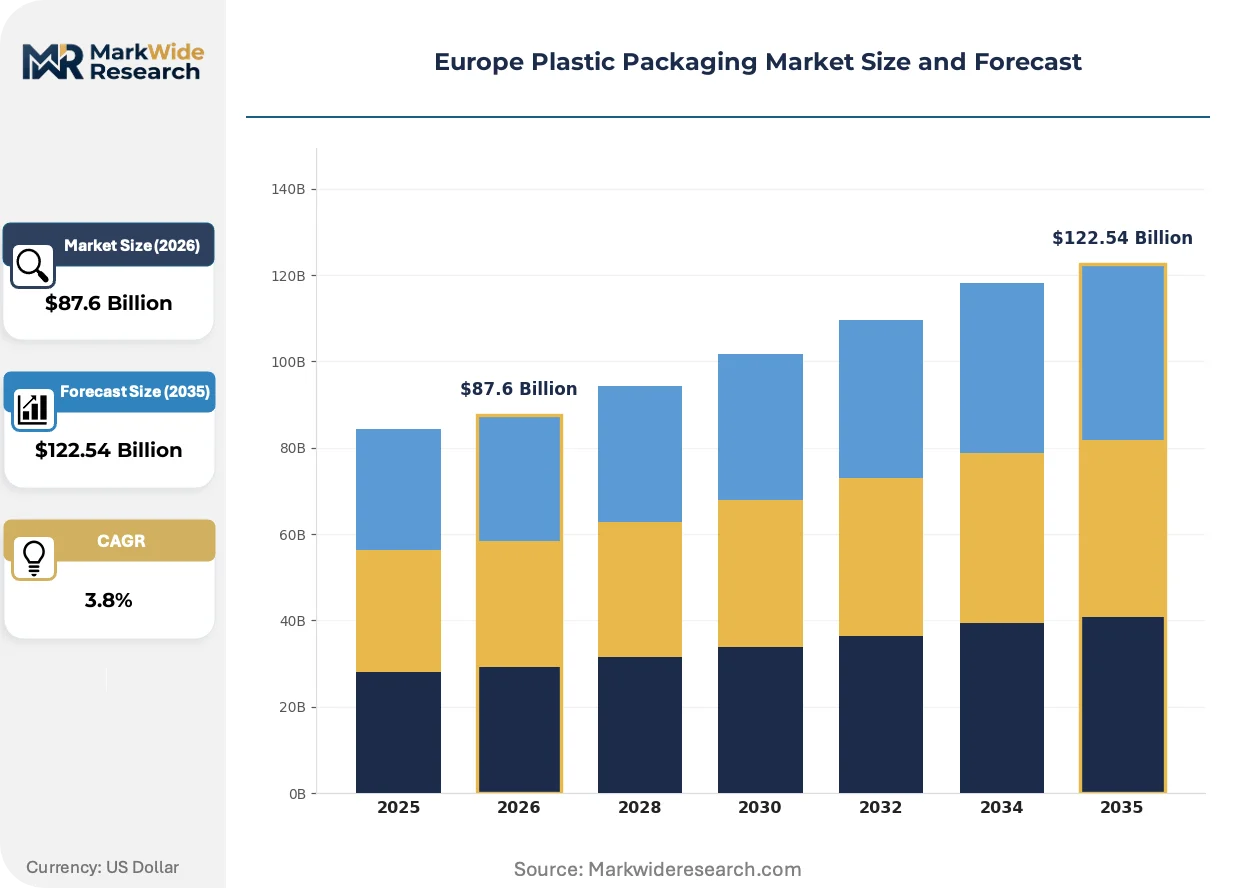
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $122.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Bags, Containers, Wraps End User: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Goods Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Flexible Packaging, Rigid Packaging, Food Service, E-Commerce |
| Companies Covered | Amcor PLC, Berry Global Inc., Sealed Air Corporation, Constantia Flexibles GmbH, Mondi Group, ALPLA Werke GmbH, Huhtamaki Oyj, Sonoco Products Company, Coveris Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plastic Packaging Market Emerging Trajectories
Digital printing and smart packaging integration are collapsing minimum order quantities while enabling batch-level traceability, fundamentally altering how converters compete for pharmaceutical and premium food contracts.
Digital flexographic and inkjet systems with sub-5% ink waste rates are rendering obsolete traditional rotogravure cylinders that require €15,000+ setup costs and 10-day lead times. Pharmaceutical contract packagers in Germany and Switzerland are adopting these systems for serialization-compliant short runs. The shift is compressing converter economics toward make-to-order models and away from volume-driven commodity production.
REACH chemical compliance frameworks are mandating substance-by-substance registration for all polymer additives above 0.1% concentration, forcing converters to audit entire supply chains for SVHC candidates. The industrial consequence is a phased withdrawal of certain colorants and slip agents from food-contact applications. Flexible packaging producers in Italy and Spain are most affected, accelerating substitution toward mineral-based alternatives with established safety dossiers.
Retailer private-label consolidation is concentrating procurement decisions among fewer buyers with dedicated sustainability scorecards. Discounters in Germany and France are unbundling packaging specification from finished-goods supply, appointing direct converter relationships that bypass traditional brand-owner intermediaries. The Netherlands and Scandinavia show the most advanced adoption, where supermarket chains now mandate mass-balance certification for all flexible formats.
Europe Plastic Packaging Market Segmentation
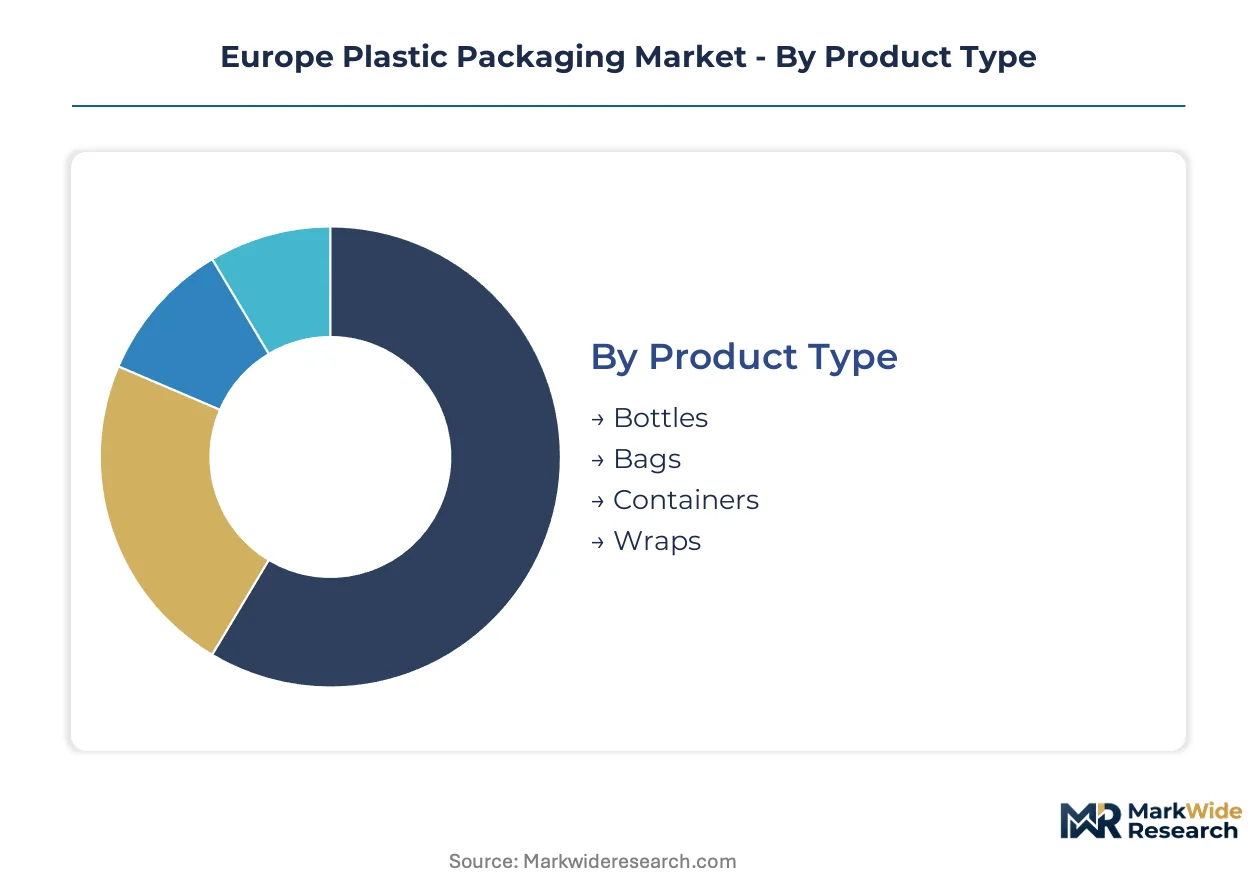
Segmentation in European plastic packaging reveals how regulatory pressure and end-use performance requirements split procurement decisions across incompatible material specifications. Converters must align extrusion capabilities with distinct compliance frameworks governing food contact, pharmaceutical barrier, and e-commerce protective applications.
Product Type:
After-sales service intensity varies sharply across formats, with pharmaceutical bottles requiring serialization validation support and flexible wraps demanding rapid specification adjustments for retail private-label programs.
- Bottles:Blow-molded PET and HDPE structures ranging from 50ml to 5L dominate beverage and pharmaceutical channels. German pharmaceutical contract packagers are specifying child-resistant closures with integrated desiccant chambers to meet EMA stability guidelines.
- Bags:Mono-polyethylene and multi-layer coextruded formats span 10-150 micron thicknesses for retail carryout and industrial bulk applications. French supermarket chains are mandating minimum 30% recycled content thresholds that only post-consumer PE streams can satisfy.
- Containers:Injection-molded PP and thermoformed PET structures serve prepared-meal and dairy segments across Central European dairy processors.
- Wraps:Stretch and shrink films secure palletized loads for German automotive component suppliers and Italian fresh-produce exporters.
Bottles holds the largest share; momentum sits with Bags as retailers accelerate recycled-content mandates.
End User:
Cost tier differentiation separates premium pharmaceutical specifications from commodity food-service procurement, with personal care occupying an intermediate position on barrier performance and decoration complexity.
- Food & Beverage:Modified-atmosphere barrier films and aseptic bottle formats protect shelf-stable and chilled categories. Italian pasta and sauce producers are adopting high-barrier EVOH coextrusions to replace metal cans.
- Pharmaceuticals:Blister packs, vials, and prefilled syringes demand oxygen transmission rates below 0.5 cc/m²/day and full batch traceability. Swiss and German contract packagers are integrating RFID-enabled labels to satisfy EMA serialization deadlines.
- Personal Care:Airless pumps and dual-chamber bottles combine aesthetic differentiation with formula protection for premium skincare lines.
- Consumer Goods:Detergent pods and battery blister packs prioritize child-resistant features and shelf impact over barrier performance.
Food & Beverage commands volume leadership; Pharmaceuticals is climbing the fastest on unit value expansion.
Material:
Volume concentration favors polyethylene across flexible formats, while rigid pharmaceutical and dairy applications sustain polypropylene demand despite higher conversion costs.
- Polyethylene:LDPE, LLDPE, and HDPE grades span 0.91-0.96 g/cm³ density ranges for film, bottle, and injection-molding applications. The EU Packaging and Packaging Waste Regulation is accelerating mono-PE laminate development to qualify for mechanical recycling streams.
- Polypropylene:Homopolymer and random copolymer grades deliver thermal resistance for hot-fill and retort applications. Polish converters are expanding biaxially oriented PP capacity for snack food lidding.
- Polyvinyl Chloride:Medical blister packs and blood bags face ECHA plasticizer evaluations that are forcing migration to TPO alternatives.
- Polystyrene:Expandable and crystal grades serve protective packaging and dairy cups where recycling infrastructure remains underdeveloped.
Polyethylene holds the largest share; momentum sits with Polypropylene as dairy and prepared-meal segments expand retort-capable formats.
Application:
Customer type splits between brand-owner direct procurement for rigid containers and converter-mediated sourcing for flexible films, with e-commerce protective formats emerging as a distinct specification channel.
- Flexible Packaging:Rollstock, premade pouches, and lidding films dominate food and pharmaceutical barrier applications. Netherlands-based converters are piloting chemical recycling feedstocks for mass-balance certified laminates.
- Rigid Packaging:Bottles, jars, and thermoformed trays deliver dimensional stability for liquid and semi-solid contents. Berry Global's Central European molding network anchors dairy supply for German discounters.
- Food Service:Disposable cutlery, clamshells, and portion cups face bans on expanded polystyrene across France and Italy.
- E-Commerce:Insulated pouches, air cushions, and mailer bags protect temperature-sensitive pharmaceutical deliveries and electronics.
Flexible Packaging holds the largest share; E-Commerce is gaining share fastest on cold-chain pharmaceutical expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's freight rail network and Rotterdam-Antwerp port complex anchor Europe's polymer distribution, channeling feedstock from North Sea crackers to converters across the continent.
Germany
Modified-atmosphere barrier films for fresh produce and pharmaceutical serialization mandates drive specification intensity. ECHA substance evaluations under REACH force reformulation of PVC medical grades. The Baden-Württemberg and North Rhine-Westphalia clusters host coextrusion lines supplying dairy and prepared-meal segments.
France
Supermarket private-label consolidation and recycled-content mandates reshape flexible film procurement. ANSM pharmaceutical packaging guidelines align with EMA track-and-trace requirements. The Île-de-France and Hauts-de-France regions concentrate blow-molding capacity for beverage and personal care bottles.
Italy
Fresh-produce export modernization and pasta sauce producers adopting high-barrier EVOH coextrusions displace metal can formats. EFSA food-contact compliance frameworks govern additive selection. Emilia-Romagna and Lombardy anchor thermoforming operations for chilled ready-meal trays.
Netherlands
Chemical recycling infrastructure investments and mass-balance certification pilots unlock processing of contaminated flexible films. The EU Packaging and Packaging Waste Regulation accelerates mono-material development. Rotterdam's port-linked industrial zone hosts pyrolysis scale-up projects for circular feedstock supply.
Poland
Automated extrusion lines narrow the cost gap with Western European converters while rail links serve German brand owners. Extended producer responsibility schemes under EU waste directives tighten compliance requirements. The Łódź and Warsaw industrial corridors expand biaxially oriented PP capacity for snack food lidding.
Europe Plastic Packaging Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on material science and barrier engineering. The European plastic packaging market structures around three tiers: multinational converters with continental extrusion networks, mid-cap specialists in mono-material or pharmaceutical formats, and regional molders serving single-country dairy and beverage accounts. Two strategic archetypes dominate: technology licensors with patented barrier layer systems, and scale operators leveraging Central European cost structures. Consolidation through bolt-on acquisitions and chemical recycling joint ventures represent the primary competitive vectors.
Among the integrated converters, Amcor PLC and Berry Global anchor the multinational tier, representing the platform-integrator archetype with cross-border supply networks. Sealed Air Corporation occupies a position within the protective and flexible packaging specialization. These three exemplify divergent strategic postures: technology-led barrier film development, scale-driven rigid container molding, and systems-based protective format integration.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Inc. |
| Sealed Air Corporation |
| Constantia Flexibles GmbH |
| Mondi Group |
| ALPLA Werke GmbH |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Coveris Holdings |
| Others |
Supply Flow & Price Mechanics
North Sea naphtha crackers in the Netherlands and Belgium anchor feedstock supply for European converters, concentrating margin capture upstream while downstream packaging tiers fragment across mechanical recycling compatibility grades and chemical recycling certification premiums.
Pricing Analysis
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across the European plastic packaging landscape. Three-tier pricing structure across premium, standard, and economy levels separates mass-balance certified mono-material formats from conventional multi-layer laminates and commodity spot-grade alternatives. Price differentiation rests on certification level—specifically EFSA food-contact compliance and REACH substance dossier completeness—and volume scale for converter offtake agreements. Pricing pressure stems from natural gas cost volatility at European crackers, compressing margins on commodity polyethylene grades. Food-service procurement teams exhibit highest price sensitivity, while pharmaceutical contract packagers prioritize barrier performance over unit cost.
Supply Chain Analysis
Central European contract manufacturers in Poland and the Czech Republic hold expanding extrusion capacity, with automated lines narrowing cost gaps against Western European equivalents. Geographic supply concentration centers on Germany, France, and Italy for pharmaceutical and dairy rigid formats, while flexible film production gravitates toward the Netherlands and Belgium for chemical recycling feedstock integration. Raw material dependencies draw from North Sea naphtha crackers, Saudi ethane-based import grades, and post-consumer recycled PE streams. Supply chain risk hinges on single-source vulnerability for EVOH barrier resins and certain compatibilizer additives. Distribution runs through Rotterdam-Antwerp port complexes and Rhine-Alpine rail corridors to converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation creates a high-growth disruption as mandatory recyclability thresholds force €2-4 million line retrofits and open acquisition opportunities for mono-material technology holders.
For Market Incumbents: Insulate pharmaceutical barrier contracts through patented multi-layer film investments while accelerating backward integration into chemical recycling feedstock supply. Amcor PLC and Berry Global should prioritize mono-polypropylene retort capacity additions in Poland to defend against Central European cost competitors. ECHA substance evaluations threaten PVC medical grades, demanding reformulation R&D to protect existing device packaging relationships. For New Entrants and Emerging Players: Establish a beachhead in e-commerce protective formats for temperature-sensitive pharmaceutical delivery, where insulated pouch specifications remain underdeveloped and buyer consolidation has not yet occurred. Target Netherlands-based mass-balance certification pilots as a go-to-market anchor, leveraging chemical recycling infrastructure investments to differentiate from mechanical recycling-limited incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap mono-material specialists in Italy and Spain, where REACH compliance costs and retailer recycled-content mandates are forcing consolidation. Five-to-ten year viability favors converters with in-house extrusion capabilities and established EFSA dossiers. Monitor EMA serialization deadline enforcement as the signal indicating pharmaceutical packaging contract renewal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Scale-Up | Qualifies laminates for mechanical recycling streams under EU Packaging and Packaging Waste Regulation thresholds. |
| Chemical Recycling Joint Venture | Unlocks processing of contaminated flexible films currently rejected by Netherlands and Belgium mechanical recyclers. |
| Pharmaceutical Barrier Patent Licensing | Captures EMA serialization-compliant blister pack contracts from German and Swiss contract packagers. |
| Central European Capacity Expansion | Exploits Poland's 15-20% cost advantage versus Western European converters for German discounter supply. |
| Digital Printing Integration | Collapses pharmaceutical short-run minimum order quantities through sub-5% ink waste flexographic systems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across converter procurement teams, brand-owner packaging engineers, and EMA regulatory affairs specialists. Secondary validation drew from ECHA substance evaluation databases, EU Packaging and Packaging Waste Regulation impact assessments, and extended producer responsibility scheme filings in Germany and France. Bottom-up extrusion capacity modeling triangulated against top-down polymer consumption data from North Sea cracker operators.
Calibration anchored volume projections to historical mono-material adoption curves and regulatory enforcement phase transitions. Segmentation dimensions spanned product type, end-user industry, material grade, and application format across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating EFSA compliance cost pass-through and retailer private-label consolidation patterns. Feedstock price volatility bands and chemical recycling capacity buildout schedules served as key forecast inputs.
Stress conditions across natural gas price spikes, EMA serialization deadline delays, and mechanical recycling contamination thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement timing and brand-owner specification adoption curves. Quarterly review of ECHA substance restriction proposals and supermarket sustainability scorecard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market