
 Plastic-Free Packs Market | 2026-2036
Plastic-Free Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic-Free Packs Market Analytics
Food-grade barrier performance is collapsing the historical trade-off between shelf stability and plastic elimination. Mondi leverages its integrated kraft paper and coating operations to supply high-barrier paper solutions for fresh protein applications. DS Smith anchors European corrugated alternatives through proprietary moisture-resistant flute designs. Smurfit Kappa competes with recycled-content paper bags engineered for dry grocery distribution.
Plastic-free packs denote primary and secondary packaging formats engineered without petroleum-derived polymers, typically incorporating cellulose fibers with bio-based coatings, glass, or thin-gauge aluminum to achieve specified oxygen and moisture vapor transmission rates. These constructions serve to contain, protect, and present goods while meeting compostability or recyclability criteria under EN 13432 and comparable frameworks. Cartons lead volume given established aseptic filling infrastructure, while glass containers capture premium margin pools in cosmetics and specialty food segments where inert contact surfaces command price premiums. Biodegradable paper formats represent the fastest-expanding material category as coating chemistry advances permit broader migration from polyethylene-laminated structures.
The EU Green Deal and REACH frameworks restrict persistent polymer additives, while EFSA evaluates novel contact substances for food-grade paper barriers. Germany's national packaging ordinance implements extended producer responsibility fees that penalize non-recyclable formats. Stakeholders must monitor coating innovation pipelines and regulator pre-approval timelines to secure first-mover positioning as barrier specifications tighten.
Market Dynamics
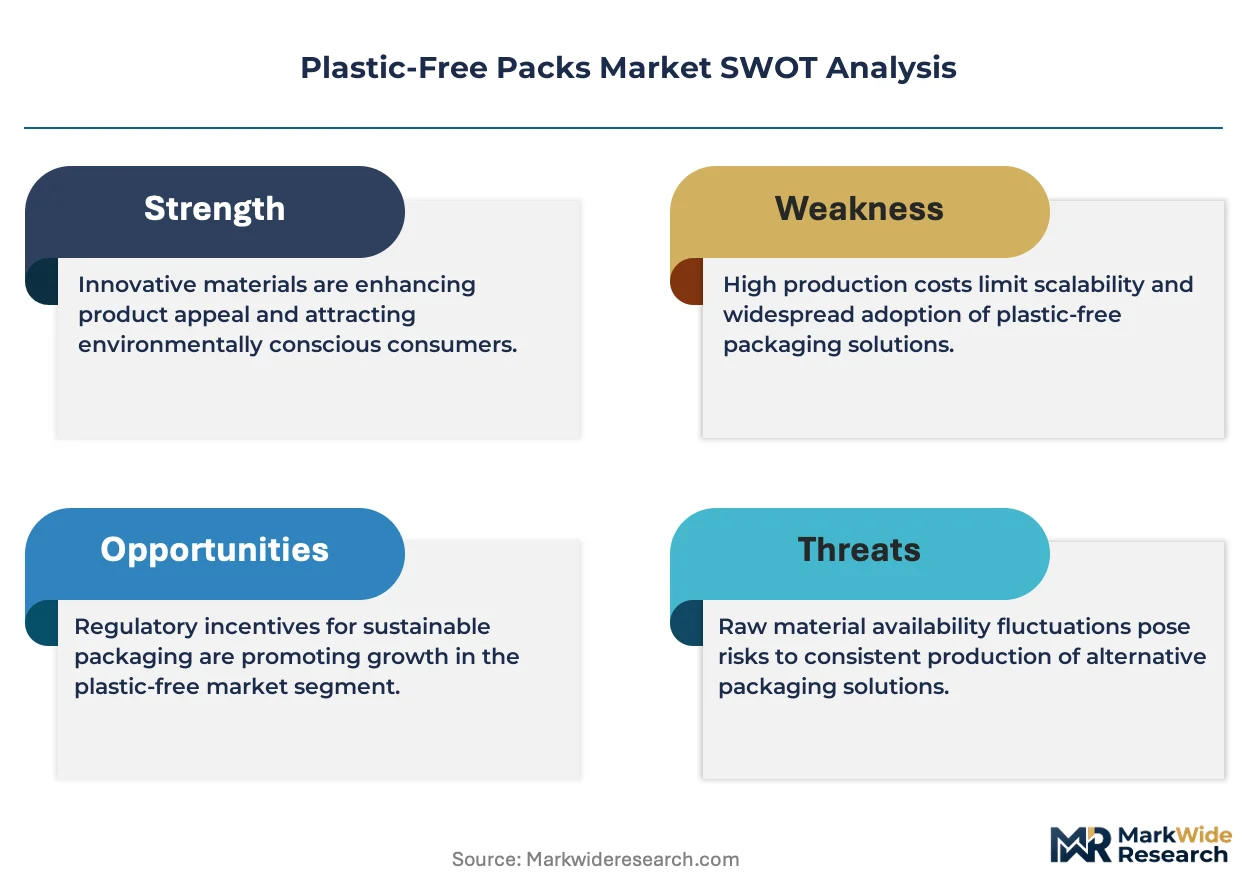
The EU Green Deal's Packaging and Packaging Waste Regulation is forcing food manufacturers to eliminate polyethylene laminates from primary packaging by 2030, collapsing the historical trade-off between shelf stability and plastic elimination through accelerated coating chemistry development.
Growth Catalysts
- Extended Producer Responsibility Fees:Germany's national packaging ordinance penalizes non-recyclable formats, redirecting capital toward cellulose fiber barrier development.
- Aseptic Filling Infrastructure:Established carton filling lines enable rapid format conversion without greenfield equipment investment.
- Retailer Sustainability Mandates:French and British supermarket chains now require plastic-free primary packaging for private-label dry grocery lines.
Market Restraints
- Coating Raw Material Concentration:Bio-based barrier chemistries depend on concentrated supply of polylactic acid and alginate derivatives from Southeast Asian processors.
- Moisture Vapor Transmission Limits:Current cellulose barriers cannot achieve the sub-0.1 g/m²/day rates required for frozen protein distribution.
- REACH Pre-Approval Timelines:ECHA's evaluation of novel contact substances creates 18-24 month commercialization delays for food-grade paper barriers.
Strategic Opportunities
- Cosmetics Premium Segment:Glass container adoption for skincare serums commands price premiums where inert contact surfaces justify unit cost increases.
- Compostable Wet Wipes:EN 13432-certified cellulose formats are displacing spunlace polyester in European personal care applications.
- Aluminum-Paper Hybrid Pouches:Thin-gauge foil laminates with fiber-based substrates satisfy pharmaceutical blister requirements while meeting recyclability criteria.
Industry Challenges
- Barrier Chemist Talent Scarcity:Formulation expertise spanning polymer science and paper engineering remains concentrated among legacy coating suppliers.
- Legacy Filling Line Retrofit Costs:Converting heat-seal polyethylene equipment to ultrasonic or cold-seal fiber formats demands substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic-Free Packs Market |
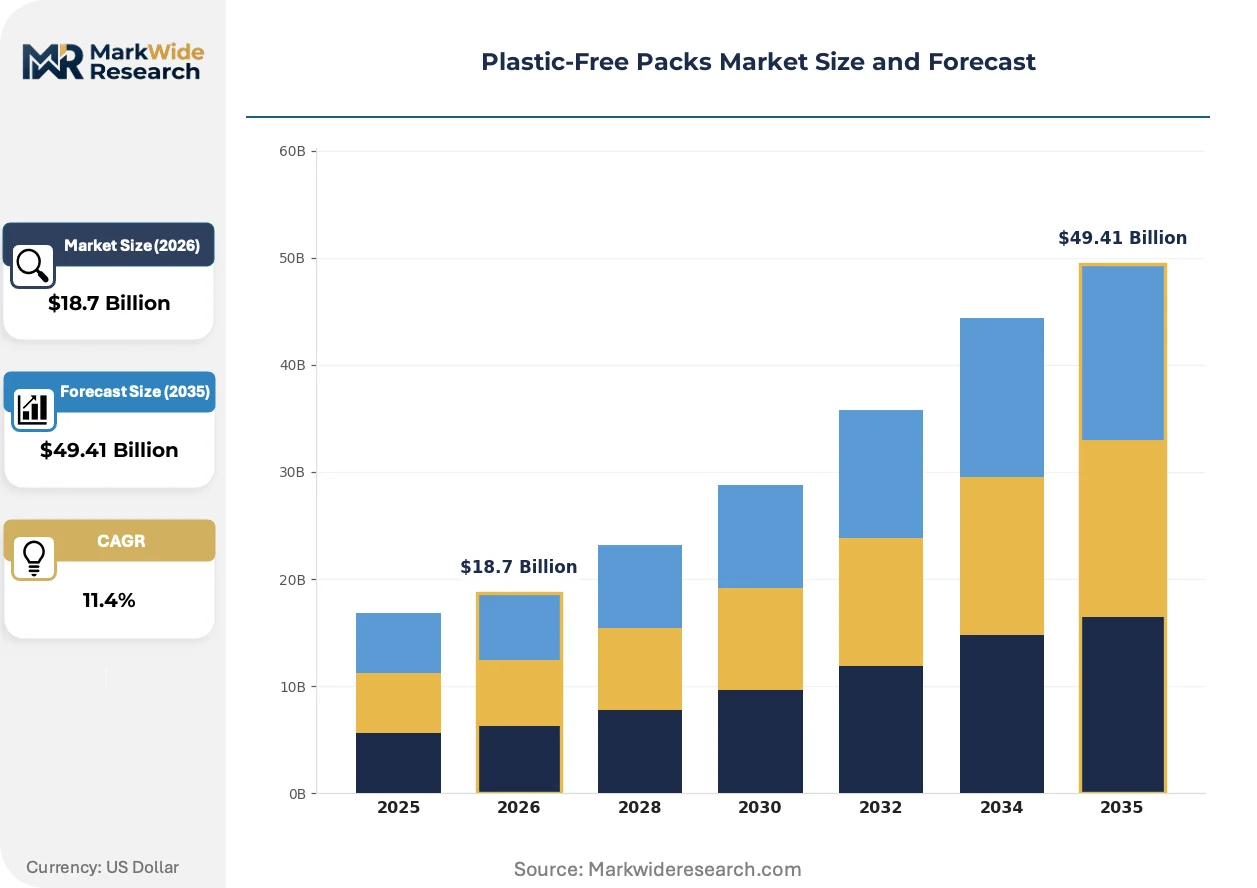
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cartons, Paper Bags, Glass Containers, Metal Containers Material: Biodegradable Paper, Bamboo, Metal, Glass End User: Food Industry, Cosmetics, Household Products, Healthcare Distribution Channel: Retail Stores, E-Commerce, Direct Sales, Wholesale |
| Companies Covered | Mondi, Amcor PLC, DS Smith, Smurfit Kappa, WestRock Company, Stora Enso, Huhtamaki OYJ, Tetra Pak International S.A., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic-Free Packs Market Evolving Landscape
Coating chemistry breakthroughs are collapsing performance gaps between cellulose barriers and petroleum-derived laminates, while regulatory pre-approval pipelines and retailer procurement mandates reshape competitive positioning across European supply chains.
Water-based acrylic coatings with graphene oxide additives are decomposing the oxygen transmission rate differential between kraft paper and metallized polyester. Fresh protein processors in the Netherlands and Denmark are piloting these constructions for modified atmosphere retail packs. The technology is decomposing incumbent supplier relationships as paper mills integrate barrier formulation in-house rather than outsourcing to polymer converters.
REACH restrictions on per- and polyfluoroalkyl substances eliminate oil-repellent fluorochemical coatings from food contact applications by 2025. Paperboard producers are accelerating paraffin-free alternatives and bio-wax formulations to maintain grease resistance in bakery and fast-food packaging. German converters face the steepest compliance curve given their concentration of quick-service restaurant supply contracts.
Buyers now specify compostability certification ahead of unit cost in tender evaluations for private-label dry grocery lines. French retail procurement teams prioritize EN 13432-validated formats over conventional paper-polyethylene laminates even at 15-20 percent price premiums. This preference rotation concentrates volume among integrated producers with captive composting verification capabilities rather than merchant converters.
Plastic-Free Packs Market Segmentation
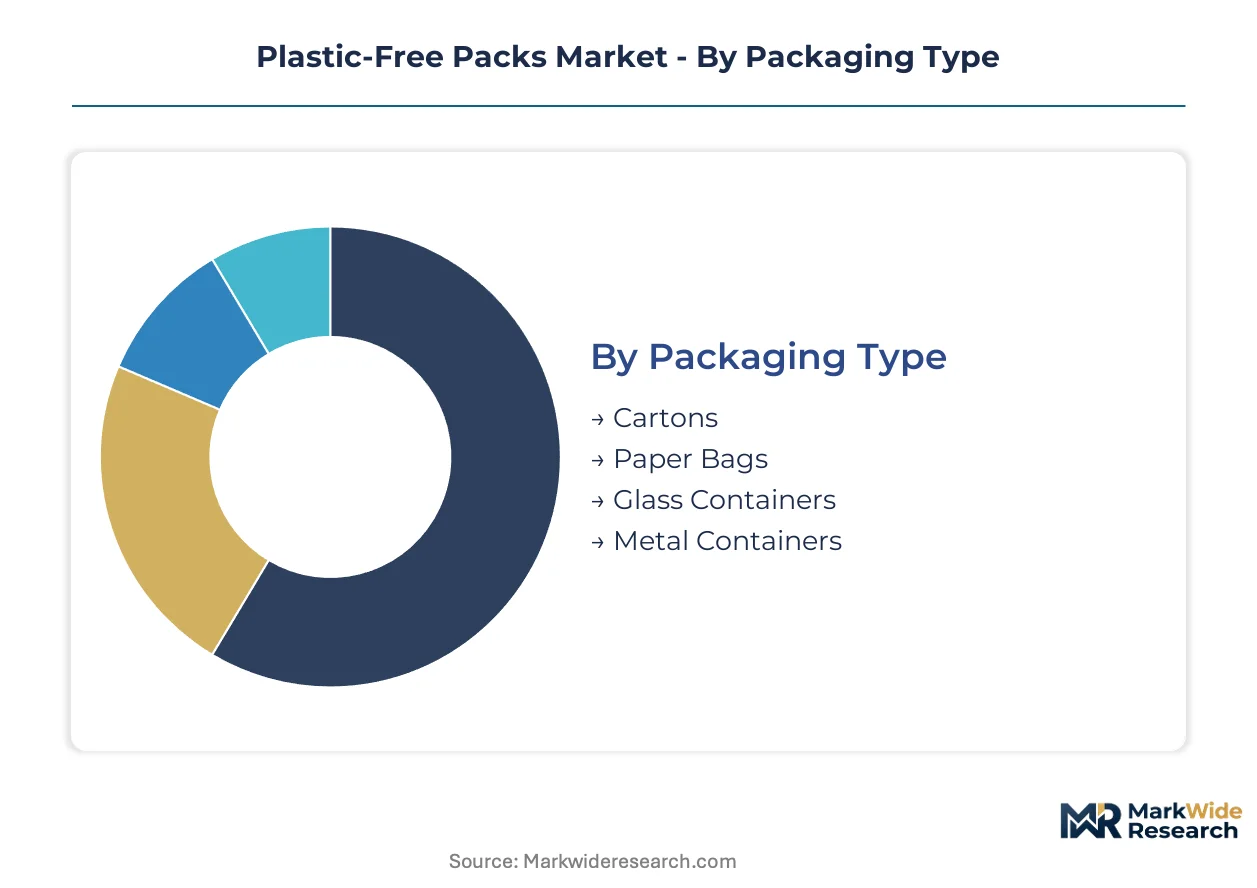
Segmentation in plastic-free packaging reveals divergent growth mechanics across material science maturity and regulatory exposure. Each category isolates distinct buyer priorities—shelf performance, compostability certification, or premium aesthetics—that reshape supplier capability requirements.
Packaging Type:
Carton demand clusters in domestic European markets with established aseptic infrastructure, while glass and metal formats serve export-led premium segments.
- Cartons:Aseptic brick and gable-top formats leverage existing filling lines across Germany and France. Dairy and plant-based beverage processors in the Netherlands and Denmark are converting volume fastest as retailer mandates eliminate polyethylene-laminated alternatives.
- Paper Bags:Multi-ply kraft constructions with bio-based moisture barriers capture dry grocery distribution. French supermarket private-label procurement teams now specify EN 13432-certified formats even at 15-20 percent price premiums over conventional laminates.
- Glass Containers:Inert contact surfaces command skincare serum and specialty food premiums. German and Italian cosmetics brands anchor European demand.
- Metal Containers:Tinplate and aluminum formats preserve shelf-stable proteins and prepared meals. British retail ready-meal lines are piloting fiber-based alternatives, pressuring metal share.
Cartons hold the largest share; momentum sits with paper bags as coating chemistry advances.
Material:
Cost tier stratification separates commodity cellulose from premium inorganic options, with bio-based intermediates capturing mid-market conversion.
- Biodegradable Paper:Coated kraft and molded fiber formats dominate volume. ECHA pre-approval timelines for novel barrier chemistries create 18-24 month commercialization delays that concentrate supply among integrated mills with captive R&D.
- Bamboo:Rapid-renewable fiber substitutes for hardwood pulp in Asian-sourced raw material supply. Limited European processing infrastructure constrains adoption to niche premium applications.
- Metal:Thin-gauge aluminum and tinplate satisfy pharmaceutical blister and shelf-stable food requirements. Recyclability via established municipal streams sustains relevance despite weight penalties.
- Glass:Soda-lime and borosilicate formats serve inert-contact premium segments. Italian and Portuguese container glass production clusters supply cosmetics and specialty food brands.
Biodegradable paper commands volume leadership; bamboo is expanding most quickly as coating compatibility improves.
End User:
Application-driven performance specifications fragment demand—oxygen barriers for proteins, grease resistance for bakery, inert surfaces for serums.
- Food Industry:Fresh protein, dairy, and dry grocery lines drive barrier innovation. Modified atmosphere packs for Dutch retail meat cases are piloting graphene oxide-enhanced cellulose coatings.
- Cosmetics:Skincare serums and premium fragrances favor glass and aluminum for inert contact. French and British indie beauty brands are accelerating format conversion ahead of packaging waste regulations.
- Household Products:Compostable wet wipes displace spunlace polyester in European personal care. EN 13432-certified cellulose formats are capturing shelf space in German drugstore chains.
- Healthcare:Pharmaceutical blisters and medical device packaging balance barrier performance with sterilization compatibility. Aluminum-paper hybrid pouches are gaining trial for unit-dose applications.
Food industry applications hold the largest share; cosmetics is gaining share fastest on premium pricing power.
Distribution Channel:
Channel concentration reflects buyer scale and specification complexity—retail mandates drive standardization, direct sales enable customization.
- Retail Stores:Supermarket and hypermarket procurement teams impose sustainability specifications across private-label portfolios. French and British chains now require plastic-free primary packaging for dry grocery lines.
- E-Commerce:Direct-to-consumer shipment formats prioritize lightweight and damage resistance. German online grocers are testing paper-based insulated liners for chilled delivery.
- Direct Sales:Brand-owned channels for premium cosmetics and specialty foods enable bespoke format development. Italian glass container producers maintain direct relationships with fragrance houses.
- Wholesale:Foodservice and institutional buyers specify cost-optimized cellulose formats for bulk dry goods. German and Polish distribution centers are consolidating pallet configurations.
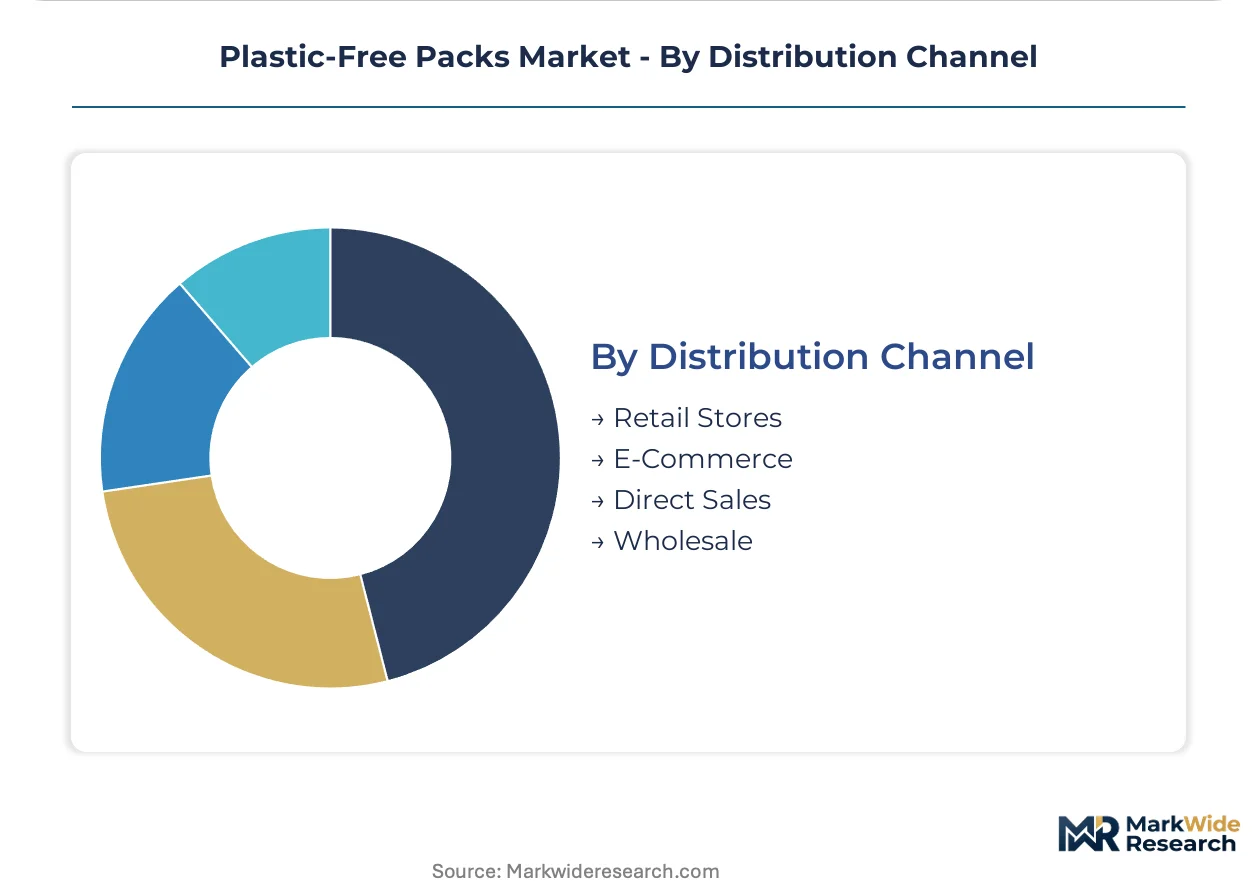
Retail stores hold the largest share; e-commerce is climbing the fastest as last-mile packaging regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European import demand for cellulose barrier substrates outpaces domestic coating capacity, drawing supply from Nordic pulp mills and Southeast Asian biopolymer processors. Export flows concentrate in German-engineered filling equipment and Italian glass container specialties.
Germany
Retailer sustainability mandates from Rewe and Edeka propel carton and paper bag conversion in dry grocery lines. The national packaging ordinance imposes extended producer responsibility fees that penalize non-recyclable formats. Bavarian and North Rhine-Westphalian converters dominate aseptic brick supply for dairy and plant-based beverages.
France
Supermarket private-label procurement teams now require EN 13432-certified formats for dry grocery, accepting 15-20 percent price premiums over conventional laminates. ECHA's REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorochemical coatings from food contact by 2025. The Île-de-France region anchors cosmetics glass demand for skincare serums and premium fragrances.
United Kingdom
Tesco and Sainsbury's plastic-free mandates for private-label lines accelerate paper bag adoption in dry grocery distribution. The UK Environment Act 2021 establishes packaging waste reduction targets aligned with EU Green Deal trajectories. West Midlands corrugated converters supply moisture-resistant flute designs for fresh produce distribution.
Netherlands
Fresh protein processors pilot graphene oxide-enhanced cellulose coatings for modified atmosphere retail packs. EFSA evaluation of novel contact substances creates pre-approval bottlenecks for food-grade barriers. Rotterdam-area logistics hubs consolidate import flows of Southeast Asian polylactic acid and alginate derivatives.
Italy
Cosmetics brands anchor European glass container demand for inert-contact premium applications. The EU Green Deal's Packaging and Packaging Waste Regulation tightens compliance timelines for export-oriented personal care manufacturers. Lombard and Piedmont container glass clusters supply fragrance houses and specialty food brands across Mediterranean markets.
Plastic-Free Packs Market Competitive Landscape
Concentration sits with integrated paper and packaging conglomerates that control captive pulp supply and coating formulation capabilities. The vendor base spans multinational converters with aseptic filling partnerships, regional specialists in barrier chemistry, and legacy glass producers serving premium segments. Two archetypes dominate: integrated fiber-based packaging suppliers with in-house kraft and coating operations, and diversified materials companies balancing petroleum-derived and cellulose portfolios. Competitive moves center on backward integration into biopolymer supply and strategic partnerships with aseptic equipment manufacturers.
Among European-based integrated suppliers, Mondi, DS Smith, and Smurfit Kappa occupy positions spanning the fiber-based barrier value chain. Mondi exemplifies the captive pulp-to-coating model through its kraft paper and integrated barrier operations. DS Smith represents corrugated alternatives with proprietary moisture-resistant engineering. Smurfit Kappa sits within the recycled-content paper bag segment for dry grocery distribution. These three anchor distinct competitive vectors without overlapping specialization.
| Leading Market Players |
|---|
| Mondi |
| Amcor PLC |
| DS Smith |
| Smurfit Kappa |
| WestRock Company |
| Stora Enso |
| Huhtamaki OYJ |
| Tetra Pak International S.A. |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Mill-scale coating operations at Nordic kraft paper producers generate 30-40 percent unit cost advantages over merchant converters, compressing price floors for EN 13432-certified barriers while concentrating supply leverage among integrated pulp-to-coating suppliers. German and French retailer sustainability mandates now absorb these premiums without volume elasticity, embedding cost-plus contract structures into private-label procurement.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the European plastic-free packs sector. Price differentiation stratifies across certification grade, with ECHA pre-approved barrier coatings commanding 15-20 percent premiums over standard cellulose formats, and volume scale tiering separating multinational dairy processors from regional bakery distributors. Cost compression in mid-tier paper bags is intensifying because Southeast Asian polylactic acid supply bottlenecks are feeding input volatility. Private-label supermarket procurement teams show highest price sensitivity, while cosmetics glass container buyers demonstrate lowest elasticity given inert-surface specifications.
Supply Chain Analysis
Inventory cycles for bio-based barrier chemistries stretch 8-12 weeks due to Southeast Asian polylactic acid and alginate derivative lead times. Geographic supply concentration centers on Sweden, Finland, and Germany for kraft pulp and coating capacity, with Italy and Portugal anchoring specialty glass container production. Raw material dependencies rest on Nordic softwood pulp, bio-wax formulations, and thin-gauge aluminum foil. Single-source vulnerability pervades novel barrier chemistry supply, where ECHA pre-approval timelines tether commercialization to captive R&D pipelines. Distribution runs through retail procurement consolidation in France, Germany, and the United Kingdom, with direct sales channels serving Italian cosmetics and fragrance houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic-free packs market sits in early-cycle expansion driven by EU Green Deal compliance deadlines, with coating chemistry breakthroughs compressing substitution economics ahead of regulatory enforcement.
For Market Incumbents: Fortify backward integration into captive biopolymer supply and accelerate ECHA pre-submission pipelines for novel barrier chemistries. Coating formulation expertise concentration among legacy suppliers presents acquisition vulnerability; integrated mills should lock in exclusive alginate derivative offtake from Southeast Asian processors before capacity constraints bite. Capacity addition in Bavaria and North Rhine-Westphalia secures aseptic brick supply positioning for dairy conversion waves. For New Entrants and Emerging Players: Anchor in compostable wet wipes and pharmaceutical aluminum-paper hybrid pouches, where EN 13432 certification gaps and sterilization compatibility requirements create defendable white space. Cosmetics glass container supply to French and British indie beauty brands offers the most penetrable segment given premium pricing tolerance and direct sales channel access. A go-to-market angle targeting EFSA fast-track consultation pathways accelerates food-grade barrier commercialization against incumbent timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated fiber-based packaging suppliers with captive pulp and in-house coating R&D capabilities over diversified materials conglomerates balancing petroleum-derived portfolios. Long-term viability across the analysis window hinges on coating chemistry patent estates and retailer mandate compliance timelines. Watch EFSA novel contact substance approval velocity as the critical inflection signal for food-grade paper barrier volume conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Supply | Captive alginate and polylactic acid sourcing insulates coating operations from Southeast Asian supply bottlenecks. |
| ECHA Pre-Approval Pipeline Investment | Early novel contact substance submissions compress 18-24 month commercialization delays for food-grade barriers. |
| Aseptic Filling Equipment Partnership | Equipment manufacturer alliances secure conversion priority as dairy and beverage processors retrofit polyethylene-laminated lines. |
| Compostability Certification Captive Capability | In-house EN 13432 validation concentrates private-label volume among integrated producers versus merchant converters. |
| Pharmaceutical Hybrid Pouch Development | Aluminum-paper laminates with fiber substrates capture unit-dose pharmaceutical trials ahead of recyclability mandate tightening. |
Research Methodology
The analysis maps cellulose barrier substrates, glass container specialties, and bio-based coating chemistries, each validated through procurement directors at French and German supermarket chains, technical R&D leads at Nordic paper mills, and regulatory affairs managers navigating ECHA pre-approval pathways. Primary interviews with sustainability officers at dairy and cosmetics processors combined with secondary validation against EU Green Deal regulatory filings, EFSA novel food contact evaluations, and EN 13432 certification databases. Bottom-up volume triangulation across coating chemistry pipelines and top-down demand modeling from retailer mandate timelines cross-validated segment outputs.
Consistency checks against external benchmarks anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include packaging type, material science maturity tier, end-use application performance specifications, and distribution channel concentration. CAGRs derived from coating chemistry adoption curves and regulatory compliance deadline clustering, with inputs from aseptic filling line conversion rates and private-label procurement specification shifts.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and ECHA pre-approval timeline stability; material deviation in regulatory velocity or bio-based raw material supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
HDPE Jug Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Global Plastic Straps Market