
 Plastic Crates Market | 2026-2036
Plastic Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Crates Market Analysis
Modular crate configurations is shifting buyer preference toward collapsible and nestable designs that reduce return-trip volume. ORBIS Corporation leverages its North American manufacturing footprint to supply automotive and food-grade modular systems. Schoeller Allibert competes through European pooling networks that sustain high asset-turn ratios across retail chains. Brambles Limited anchors global scale through IFCO's reusable produce container platform, which dominates supermarket fresh-produce logistics.
Plastic crates are rigid containers molded from high-density polyethylene, polypropylene, or recycled polymers, typically featuring vented walls, reinforced bases, and standardized footprints compatible with pallet dimensions and automated conveyor systems. They protect perishables during multi-leg distribution while enabling stack stability and hygiene certification for food contact. Collapsible crates capture growing share among third-party logistics providers seeking empty-haul efficiency, while high-density polyethylene grades retain volume leadership due to impact resistance and washdown durability. Agricultural use applications represent the fastest-expanding demand pool as farm-to-retail traceability requirements tighten across major economies.
The EU Green Deal and REACH chemical compliance frameworks in Europe, alongside FDA food-contact regulations in the United States, shape material specifications and recyclability mandates for crate manufacturers. India's BIS standards for food-grade plastics and the country's PLI scheme for packaging infrastructure create dual pressure on imported and domestic supply. China's GB standards and dual carbon goals restrict virgin polymer intensity, pushing converters toward post-consumer recycled content. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance fragmentation in multi-national pooling networks.
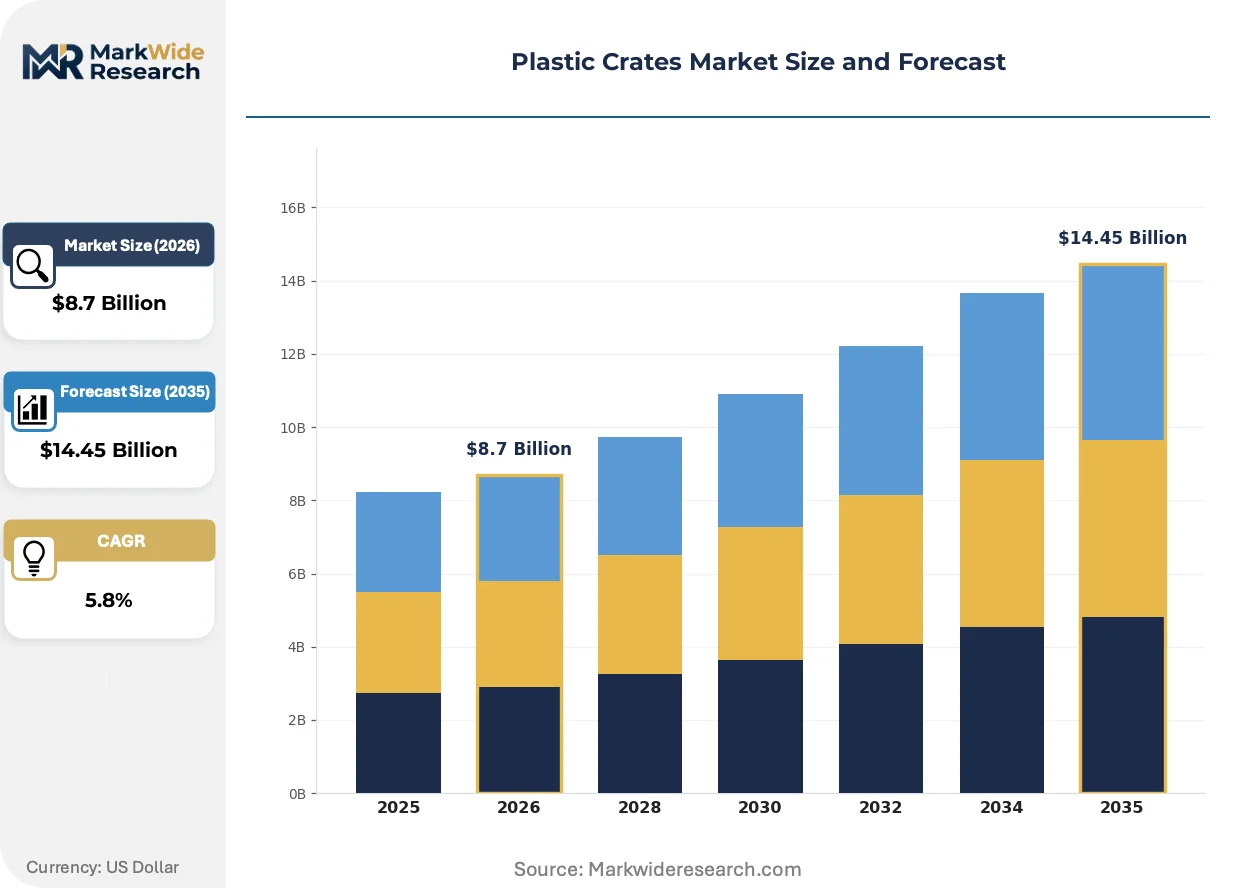
Market Dynamics
The EU Green Deal's packaging waste directives are forcing fresh produce supply chains to abandon single-use cardboard for reusable plastic crate pooling systems, compressing payback periods and rewiring logistics economics across European retail networks.
Growth Catalysts
- EU Green Deal packaging mandates:The directive's waste reduction targets compel supermarket chains to convert produce aisles to standardized reusable containers, accelerating asset deployment across pooling networks.
- Agricultural cold chain expansion:India's logistics infrastructure investments under its PLI scheme for packaging are driving nestable crate adoption among third-party cold storage operators serving farm-to-retail corridors.
- HDPE material performance:High-density polyethylene grades deliver washdown durability and impact resistance that satisfies FDA food-contact regulations, cementing polymer preference in automated distribution environments.
Market Restraints
- Virgin polymer cost volatility:Crude-linked HDPE and polypropylene feedstock prices expose converters to margin compression during petrochemical supply disruptions.
- Chinese supply concentration:Post-consumer recycled content mandates under dual carbon goals restrict domestic virgin polymer availability, creating import dependency for European and Asian pooling operators.
- Cardboard substitution persistence:Single-use corrugated remains entrenched in low-turnover produce categories where return logistics costs exceed reusable container depreciation benefits.
Strategic Opportunities
- Indian agricultural modernization:BIS standards for food-grade plastics and cold chain subsidies create entry pathways for certified HDPE container suppliers in underserved farm logistics corridors.
- Collapsible-nestable hybrid designs:Third-party logistics providers seeking empty-haul efficiency present demand for modular crates combining volume reduction with structural integrity.
- REACH recyclability certification:ECHA chemical compliance frameworks reward converters demonstrating closed-loop material recovery, differentiating premium pooling assets in European retail tenders.
Industry Challenges
- Multi-jurisdiction compliance fragmentation:Divergent FDA, REACH, and BIS food-contact specifications force pooling networks to maintain separate container fleets or absorb recertification costs.
- Legacy warehouse automation retrofitting:Existing conveyor and racking systems designed for cardboard dimensions require capital-intensive reconfiguration to accommodate standardized plastic crate footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Crates Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Crates, Nestable Crates, Collapsible Crates, Open Crates Application: Food Transportation, Agricultural Use, Retail Display, Storage Solutions End User: Agriculture Sector, Retail Chains, Logistics Providers, Manufacturing Units Material Grade: High-Density Polyethylene, Low-Density Polyethylene, Polypropylene, Recycled Plastic |
| Companies Covered | ORBIS Corporation, DS Smith Plastics, IFCO Systems, Myers Industries, Tosca, Rehrig Pacific Company, Craemer Group, Brambles Limited, Schoeller Allibert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Crates Market Emerging Trajectories
Material science breakthroughs and regulatory tightening are converging to transform crate economics, with automation compatibility and circularity certification emerging as decisive competitive differentiators.
Post-consumer recycled HDPE blending is electrifying sustainable container production without sacrificing impact resistance. Major European pooling operators are mandating minimum recycled content thresholds in supplier tenders. This material transition is compressing virgin polymer dependence while satisfying ESG disclosure requirements under CSRD.
REACH chemical compliance frameworks are tightening traceability mandates for food-contact plastics. Manufacturers must document polymer origin and additive composition across batch records. German automotive and Dutch retail pooling networks are responding by integrating blockchain-based material passports into container asset management systems.
Supermarket procurement departments are unbundling crate supply from logistics service contracts, creating direct supplier relationships with certified container manufacturers. This disintermediation is visible across German and Netherlands retail chains where produce category managers now specify HDPE grade and washdown protocol independently of 3PL arrangements.
Plastic Crates Market Segmentation
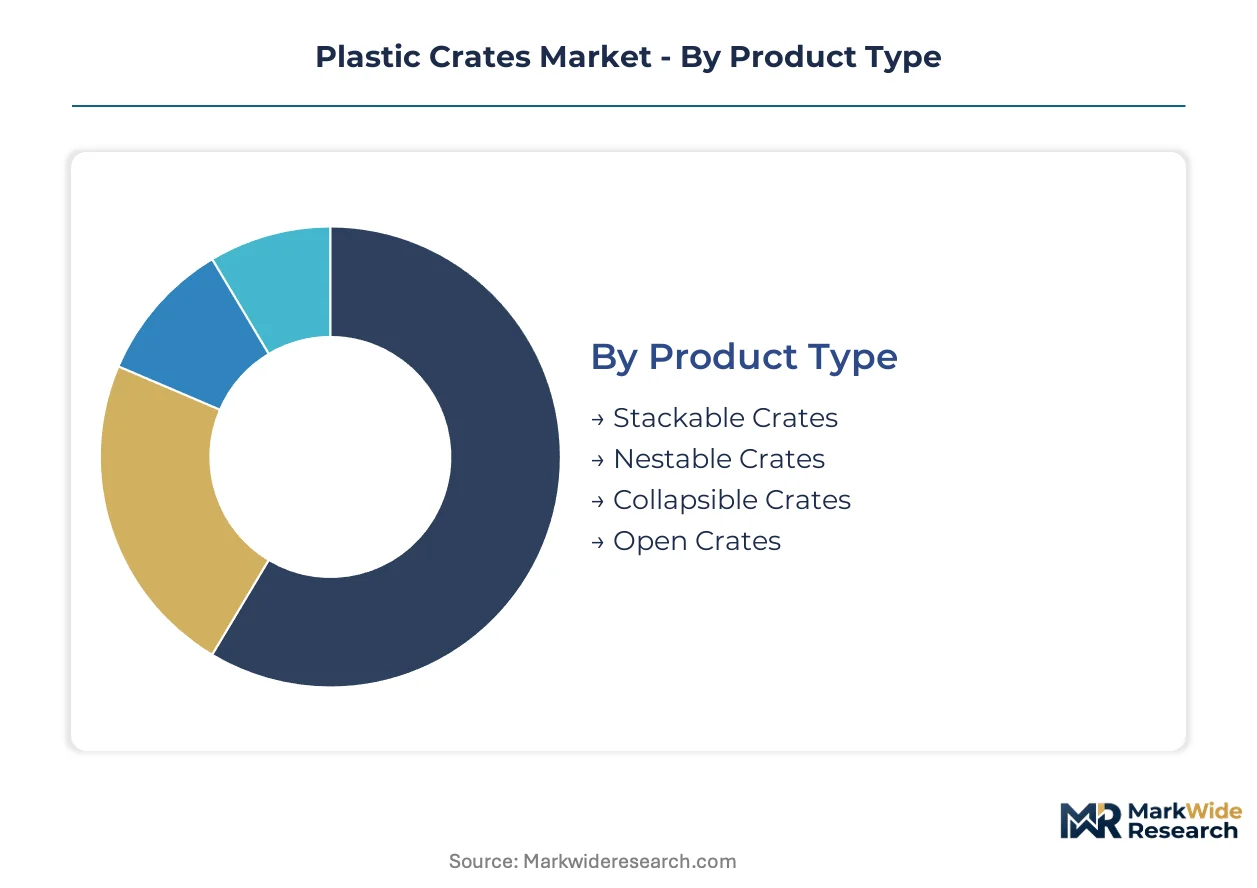
Plastic crate purchasing decisions hinge on return-trip economics, washdown protocols, and automation compatibility. Procurement managers weigh volume reduction against structural integrity across divergent supply chain configurations.
Product Type:
Buyers prioritize empty-haul efficiency when selecting crate configurations for multi-leg distribution networks.
- Stackable Crates:Rigid sidewalls and interlocking corners enable vertical stacking without nesting. European supermarket pooling networks favor these for high-turn produce aisles where structural integrity outweighs return volume concerns.
- Nestable Crates:Tapered sidewalls allow 70-80% volume reduction when empty. India's agricultural cold chain operators adopt these for farm-to-retail corridors where backhaul capacity remains constrained.
- Collapsible Crates:Hinged sidewalls fold flat for maximum transport efficiency. Third-party logistics providers specify these for seasonal produce flows with irregular return patterns.
- Open Crates:Vented designs without solid walls suit bulk agricultural handling where airflow trumps protection.
Stackable designs lead on scale; nestable configurations lead on momentum.
Application:
End-use environment dictates material specification and hygiene certification requirements.
- Food Transportation:FDA-compliant HDPE containers with sealed bases prevent liquid migration. Automated distribution centers in Germany and the Netherlands mandate standardized footprints for conveyor compatibility.
- Agricultural Use:UV-stabilized polypropylene withstands field exposure and harvest mechanization. Indian farm logistics under PLI scheme subsidies are expanding certified container deployment across state-level cold chains.
- Retail Display:Color-coded crates with branding surfaces serve dual logistics and merchandising functions.
- Storage Solutions:Heavy-duty bases support static warehouse stacking without pallet infrastructure.
Food transportation dominates current procurement volumes; agricultural use is climbing the fastest.
End User:
Asset ownership models separate pooling network operators from direct-purchase customers.
- Agriculture Sector:Smallholder cooperatives and commercial farms source nestable crates through subsidized distribution channels. India's BIS certification requirements filter supplier eligibility for food-grade plastics.
- Retail Chains:Supermarket operators drive standardization through tender specifications that mandate washdown protocols and RFID traceability. German and Dutch chains unbundle container procurement from 3PL contracts.
- Logistics Providers:Third-party operators seek collapsible-nestable hybrids to maximize fleet utilization across incompatible client requirements.
- Manufacturing Units:Automotive and electronics assemblers specify ESD-safe polypropylene for component handling.
Retail chains anchor volume demand; logistics providers are gaining share fastest.
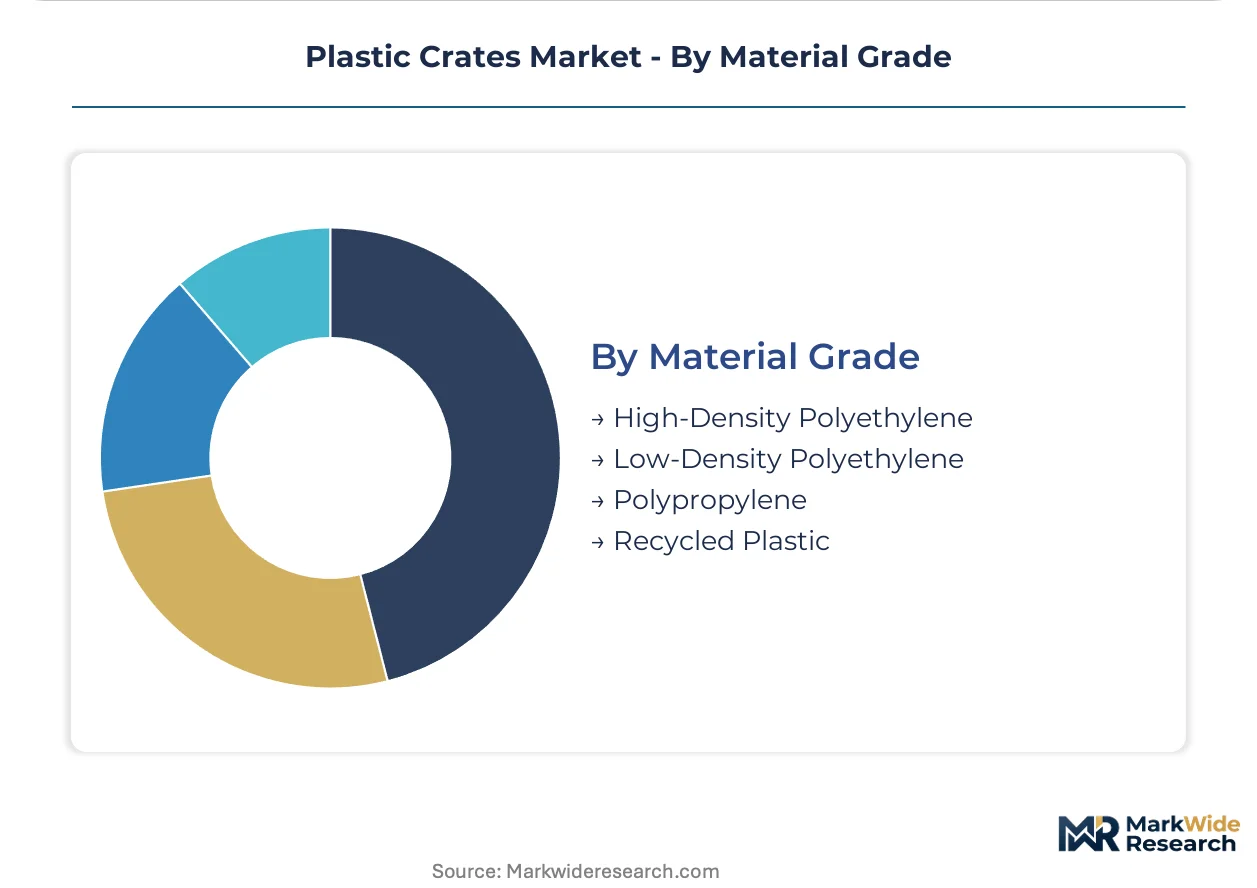
Material Grade:
Regulatory compliance and circularity mandates reshape polymer selection across jurisdictions.
- High-Density Polyethylene:Superior impact resistance and chemical stability dominate food-contact applications. REACH recyclability certification under ECHA frameworks rewards HDPE converters demonstrating closed-loop recovery.
- Recycled Plastic:Post-consumer HDPE blending satisfies CSRD disclosure requirements without sacrificing performance. European pooling operators now mandate minimum recycled content thresholds in supplier tenders.
- Polypropylene:Lighter weight and broader temperature tolerance suit agricultural field use and hot-fill applications.
- Low-Density Polyethylene:Flexibility and lower cost position this grade for non-structural storage and light-duty handling.
Virgin HDPE retains volume leadership; recycled content grades show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plastic crate industry traces its modern pooling infrastructure roots to post-war European retail consolidation, where Dutch and German supermarket cooperatives pioneered standardized reusable container systems to reduce produce spoilage and packaging waste across integrated supply chains.
Germany
Automotive and food-grade HDPE container demand concentrates in Bavaria and Baden-Württemberg, where precision manufacturing clusters require ESD-safe handling systems. The EU Green Deal's packaging waste directives accelerate conversion from single-use cardboard in retail produce aisles. Frankfurt and Hamburg anchor pooling network operations serving pan-European supermarket chains.
Netherlands
Rotterdam's port logistics and Amsterdam's distribution corridors drive certified food-grade container standardization across EU retail networks. REACH chemical compliance frameworks under ECHA mandate traceability documentation for polymer origin and additive composition. Eindhoven-based pooling operators integrate blockchain material passports into asset management systems.
United States
Automotive assembly plants in Michigan and Ohio specify modular crate systems for just-in-time component delivery, while California's agricultural valleys deploy vented containers for fresh produce distribution. FDA food-contact regulations shape HDPE material specifications for automated distribution centers. Chicago and Dallas-Fort Worth anchor third-party logistics fleets serving seasonal produce flows.
India
Maharashtra and Gujarat's agricultural processing zones adopt nestable crates under PLI scheme subsidies for cold chain infrastructure expansion. BIS standards for food-grade plastics filter supplier eligibility in farm-to-retail corridors. Bangalore and Hyderabad's logistics providers scale certified container deployment across state-level distribution networks.
China
Yangtze River Delta manufacturing clusters face virgin polymer constraints under dual carbon goals and GB standards restricting post-consumer recycled content mandates. Shanghai and Shenzhen converters supply collapsible crate designs to Asian pooling operators seeking empty-haul efficiency. MIIT industrial policy pushes domestic converters toward circular material recovery systems.
Plastic Crates Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with REACH-compliant and FDA-certified containers commanding pricing separation from uncertified alternatives. The vendor base stratifies into three archetypes: global pooling network operators owning asset fleets, regional converters supplying certified containers to tender specifications, and specialized fabricators serving automotive or agricultural niches. Dominant competitive moves include vertical integration into polymer recycling streams and strategic partnerships with supermarket procurement departments unbundling container supply from logistics contracts.
Within the pooling network operator tier, Brambles Limited and ORBIS Corporation exemplify asset-heavy models spanning multiple continents, while Schoeller Allibert occupies a position as a European-centric specialist with dense retail network penetration. Among North American fabricators, Myers Industries and Rehrig Pacific Company represent regional scale players serving automotive and agricultural end-use segments respectively. Craemer Group and Tosca anchor mid-market positioning through material-grade specialization and washdown protocol certification.
| Leading Market Players |
|---|
| ORBIS Corporation |
| DS Smith Plastics |
| IFCO Systems |
| Myers Industries |
| Tosca |
| Rehrig Pacific Company |
| Craemer Group |
| Brambles Limited |
| Schoeller Allibert |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between REACH-compliant pooling assets and uncertified commodity containers manifests in both procurement premiums and supply chain gatekeeping across European retail networks. Price spreads widen where FDA food-contact documentation or ECHA recyclability certification filters supplier eligibility, compressing margins for converters lacking backward integration into polymer recovery streams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs container procurement, with REACH-certified HDPE grades commanding separation from uncertified alternatives. Price differentiation rests on washdown protocol documentation and RFID traceability bundling. Cost compression in virgin polymer feedstocks is intensifying because crude-linked HDPE exposes converters to petrochemical volatility. Smallholder cooperatives in India exhibit highest price sensitivity, while German supermarket chains prioritize certification over unit cost.
Supply Chain Analysis
REACH and FDA qualification gating restricts supplier pools to converters maintaining batch-level polymer traceability and additive documentation. Manufacturing concentrates in China, Germany, and the Netherlands, with Yangtze River Delta converters facing virgin polymer constraints under dual carbon goals. Raw material dependencies center on high-density polyethylene resin, polypropylene granules, and post-consumer recycled feedstocks. Single-source vulnerability runs through Chinese PCR supply under GB standards. Distribution runs through pooling network operators owning captive asset fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic crates market compounds returns through regulatory layering, with the EU Green Deal's packaging waste directives mandating reusable container conversion across supermarket produce aisles.
For Market Incumbents: Extend certification moats by deepening ECHA recyclability documentation and blockchain material passport integration before competitor catch-up. Anchor pooling network density in Rotterdam-Amsterdam corridors where retail standardization tightens. Threaten margin compression from virgin polymer volatility demands captive supply of post-consumer HDPE. For New Entrants and Emerging Players: Begin with BIS-certified nestable crate supply to Indian cold chain operators under PLI scheme subsidies, where farm-to-retail corridor penetration remains below European benchmarks. Agricultural logistics in Maharashtra and Gujarat presents the most penetrable white space. Pursue direct procurement relationships with supermarket category managers unbundling container supply from 3PL contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale converters lack REACH certification bandwidth to serve pan-European retail tenders. Long-term viability favors asset-heavy pooling operators with dense return-logistics infrastructure over pure manufacturing plays. Signal to watch: supermarket tender specifications mandating minimum recycled content thresholds that filter uncertified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Recovery | ECHA recyclability certification demands closed-loop material documentation from converters. |
| Blockchain Material Passport Deployment | Dutch pooling operators integrate traceability systems to satisfy REACH additive disclosure mandates. |
| Direct Retail Procurement Relationships | German supermarket chains unbundle container specifications from logistics service contracts. |
| Collapsible-Nestable Hybrid R&D | Third-party logistics providers seek volume reduction without sacrificing structural integrity. |
| Indian Cold Chain Infrastructure Partnerships | PLI scheme subsidies accelerate certified HDPE deployment across state-level distribution networks. |
Methodological Framework
Multiple input streams — procurement manager interviews, converter production data, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary discussions engaged pooling network operators, food-grade HDPE converters, supermarket category managers, and third-party logistics fleet directors. Secondary validation drew from ECHA REACH registrations, FDA food-contact substance inventories, EU Green Deal implementation reports, and Indian BIS certification databases. Bottom-up unit economics and top-down sectoral spending patterns were cross-referenced for triangulation.
Historical shipment volumes were cross-referenced against panel input from industry participants to anchor growth trajectory assumptions across the analysis window. Segmentation modeling captured product type, application environment, end-user ownership model, and material grade tiers. CAGRs were derived from regression analysis against macro drivers including cold chain infrastructure investment, retail consolidation patterns, and polymer price indices. Forecast inputs included EU packaging waste directive compliance timelines and Indian PLI scheme disbursement schedules.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on polymer feedstocks and abrupt shifts in supermarket private-label sourcing strategies. Forecasts reflect assumptions about regulatory enforcement consistency and pooling network asset utilization rates. Deviation in virgin HDPE price volatility or REACH certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Plastic Aerosol Packaging Market