
 Middle East and Africa Plastic Bottles Market | 2026-2036
Middle East and Africa Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plastic Bottles Market Insights
Modular lightweighting is rebalancing procurement criteria across the Middle East and Africa Plastic Bottles Market as brand owners trade gram weight for transport efficiency. SABIC anchors regional resin supply through its petrochemical base in Jubail Industrial City. Amcor plc leverages pan-African distribution infrastructure to serve multinational beverage accounts. Mpact Group specializes in post-consumer recycled content for South African retail chains.
Plastic bottles are hollow containers blow-molded from thermoplastic resins, typically PET for carbonated beverages and HDPE for dairy or household chemicals, with wall thickness calibrated to internal pressure and stacking load requirements. PET commands the largest volume share in the Middle East and Africa Plastic Bottles Market due to its clarity, barrier performance, and established collection infrastructure in Cairo and Johannesburg. Flip-top closures are gaining traction in personal care applications across the Gulf states as dispensing convenience becomes a shelf-differentiation parameter. The food and beverage end-user segment occupies the dominant margin pool, though pharmaceutical-grade blow-fill-seal bottles attract premium pricing from CDSCO-aligned manufacturers in India-exporting facilities.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization (SASO) and South Africa's National Regulator for Compulsory Specifications (NRCS) enforce migration limits and recyclability labeling that shape formulation choices across the value chain. Egypt's Egyptian Organization for Standardization and Quality (EOS) alignment with Gulf technical regulations is easing cross-border bottle trade into the Common Market for Eastern and Southern Africa. Stakeholders must monitor how extended producer responsibility frameworks migrate from European templates into national legislation across the region.
Market Dynamics
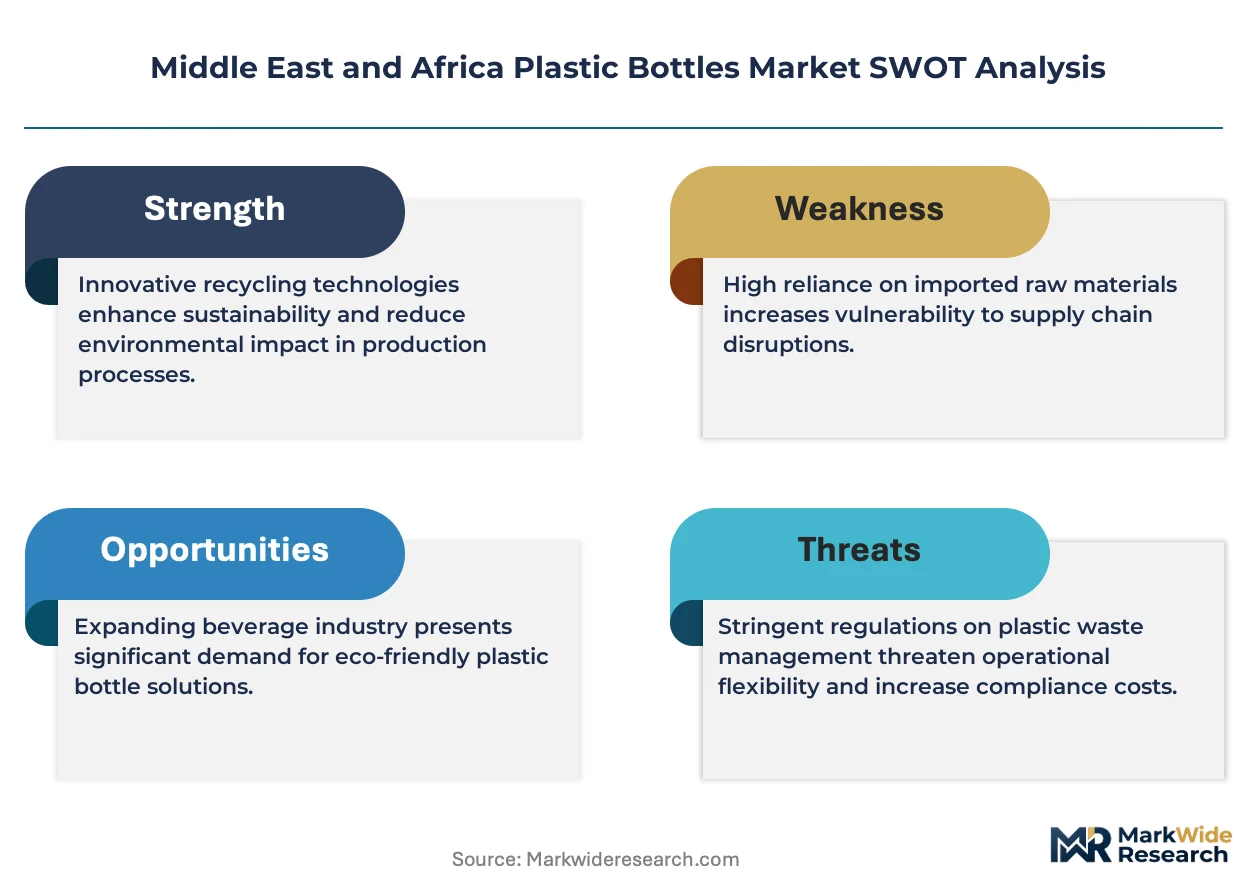
The Gulf Cooperation Council's single-use plastic bans are forcing resin suppliers and converters to reconfigure feedstock strategies around recycled PET and bio-based alternatives, compressing margins for virgin material producers while opening formulation gaps for circular-economy entrants.
Growth Catalysts
- Bottled Water Consumption:Nigeria and South Africa are anchoring volume expansion through rising per-capita consumption of packaged hydration products in urban centers.
- SASO Recyclability Mandates:Saudi Arabia's labeling and migration-limit rules are accelerating investment in closed-loop collection infrastructure across the Arabian Peninsula.
- Lightweighting Technology:Gram-weight reduction in PET preform design is cutting transport costs for beverage distributors operating across Egypt's Nile Delta corridor.
Market Restraints
- Feedstock Price Volatility:Ethylene and propylene input costs tied to regional crude benchmarks create margin instability for blow-molders in Jubail Industrial City.
- Collection Infrastructure Gaps:Post-consumer PET recovery rates in sub-Saharan markets outside South Africa remain structurally insufficient for rPET scale-up.
- Regulatory Fragmentation:Divergent technical standards between Egypt's EOS and Gulf SASO frameworks complicate cross-border bottle trade into COMESA territories.
Strategic Opportunities
- Kenya's Underpenetrated Dairy Sector:HDPE bottle adoption for pasteurized milk distribution remains below saturation in East African retail modernization.
- Extended Producer Responsibility:South Africa's pending packaging waste regulations will create mandated demand for post-consumer recycled content integration.
- Flip-Top Dispensing Convergence:Personal care brands in UAE and Qatar are merging convenience packaging with premium shelf differentiation.
Industry Challenges
- Blow-Mold Technician Scarcity:Skilled operators for high-speed stretch-blow equipment are concentrated in Saudi Arabia and South Africa, leaving other markets talent-constrained.
- Pharmaceutical Certification Timelines:CDSCO-aligned blow-fill-seal validation for Indian-exporting facilities creates extended approval cycles for sterile bottle applications.
- Legacy Equipment Integration:Retrofitting existing extrusion lines for bio-based resin processing requires capital outlays that mid-scale converters in North Africa struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plastic Bottles Market |
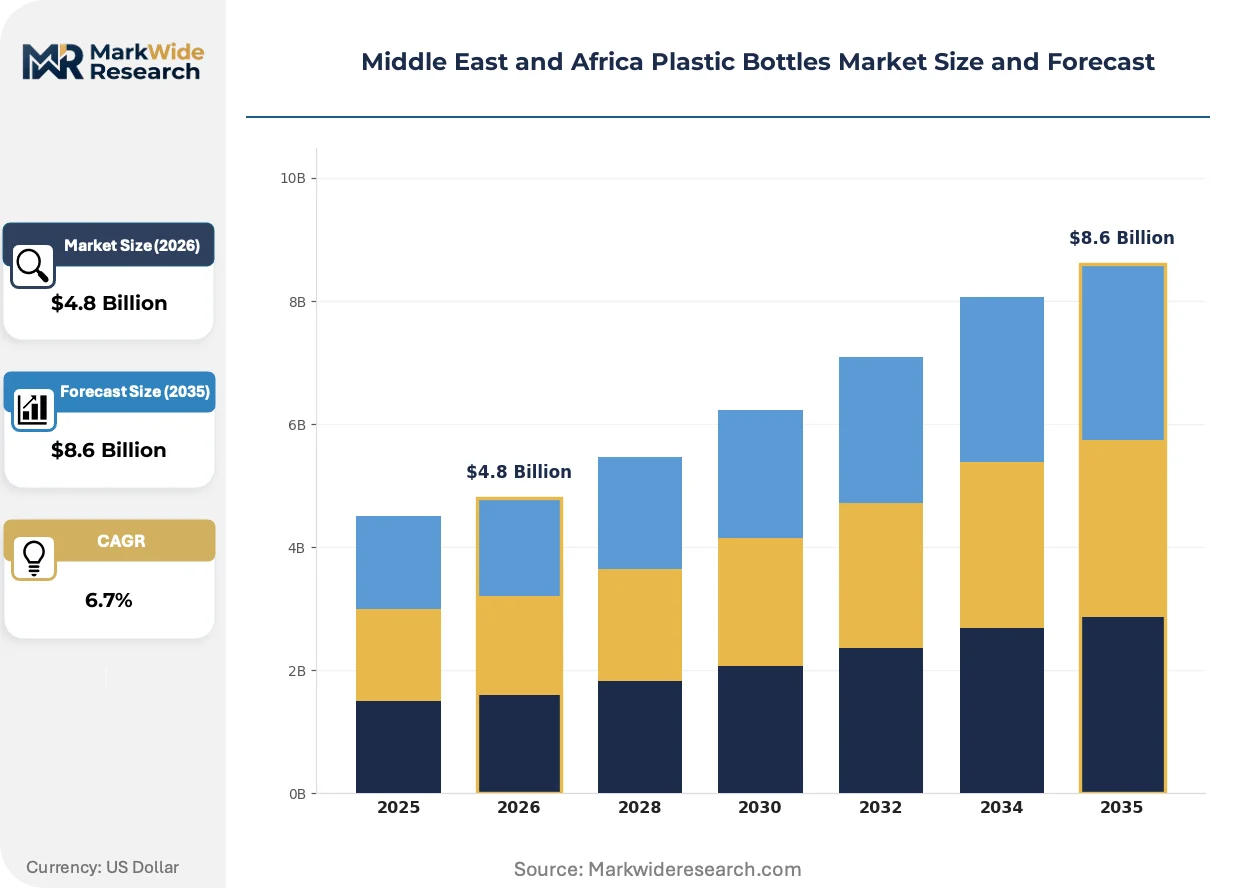
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PET, HDPE, LDPE, PP Closure Type: Screw Caps, Flip Top, Snap On, Pump Dispensers End User: Food & Beverage, Personal Care, Household, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Distributors |
| Companies Covered | Alpla Packaging SA, Plastics For Africa, Nampak Bevcan, SABIC, Amcor plc, Mpact Group, Savola Plastics Company, Zamil Plastic, Polyoak Packaging Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plastic Bottles Market Trends and Innovations
Material science advances and regulatory pressure are converging to reshape competitive positioning across the Middle East and Africa Plastic Bottles Market, with sustainability credentials becoming a procurement filter rather than a premium add-on.
rPET flake-to-preform processing is consolidating supply relationships between beverage brand owners and specialized recyclers in Johannesburg and Cairo. Major bottlers in Nigeria are now specifying minimum recycled content thresholds in resin supply agreements. This technology compression is eliminating spot-market virgin PET purchases for contracted volumes.
SASO's technical regulations for plastic packaging are mandating recyclability labeling and migration testing that exceeds previous Gulf voluntary standards. converters in Saudi Arabia's Eastern Province are requalifying resin formulations to maintain market access. The pharmaceutical and food-contact segments are absorbing the highest compliance costs through dedicated production line segregation.
Retail chains in South Africa are unbundling after-sales packaging services from primary product supply, forcing bottle converters to assume extended producer responsibility costs directly. This channel restructuring is visible in Cape Town's supermarket consolidation, where centralized procurement teams now negotiate packaging-as-a-service terms rather than per-unit bottle pricing.
Middle East and Africa Plastic Bottles Market Segmentation
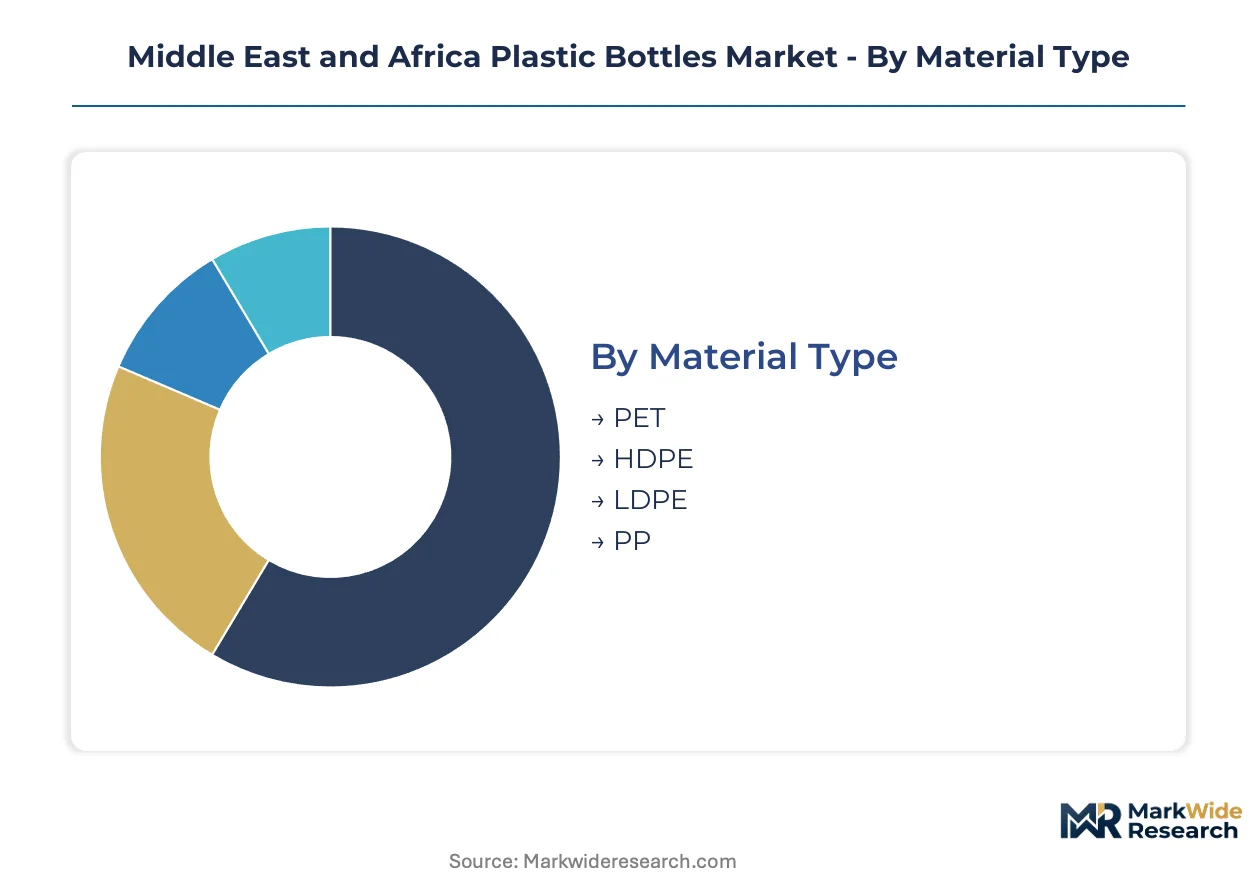
Material selection and closure mechanics in the Middle East and Africa Plastic Bottles Market are diverging sharply between mass-market beverage applications and premium personal care positioning. Procurement patterns now track regulatory pressure on recyclability alongside shelf-differentiation requirements in Gulf retail chains.
Material Type:
PET dominates volume flows while bio-based alternatives capture premium contract negotiations.
- PET:Blow-molded polyethylene terephthalate delivers clarity and carbonation barrier performance essential for Nigeria's bottled water expansion and South Africa's soft drink manufacturing belt. Cairo and Johannesburg collection infrastructure sustains rPET feedstock availability for closed-loop contracts.
- HDPE:High-density polyethylene serves dairy distribution in Kenya's pasteurized milk sector and household chemical applications across North Africa. SASO migration-limit testing adds compliance overhead for food-contact HDPE converters in Saudi Arabia's Eastern Province.
- LDPE:Low-density formulations accommodate squeeze dispensing in personal care travel sizes distributed through UAE duty-free retail.
- PP:Polypropylene withstands hot-fill sterilization requirements for pharmaceutical blow-fill-seal applications exporting from Indian-aligned facilities.
Today's leader: PET. Tomorrow's challenger: rPET flake-to-preform integration.
Closure Type:
Dispensing convenience is reclassifying closure selection from cost-minimization to shelf-differentiation investment.
- Screw Caps:Standard threaded closures retain cost dominance across beverage volume contracts in Egypt's Nile Delta corridor and Nigeria's Lagos manufacturing zone. Lightweighting preform designs are reducing cap gram weight in tandem with bottle wall thickness.
- Flip Top:Hinged dispensing closures are penetrating UAE and Qatar personal care segments where single-hand operation commands premium placement in pharmacy chains.
- Snap On:Press-fit closures serve single-serve dairy and juice portions in South African supermarket private-label programs.
- Pump Dispensers:Actuated dispensing systems concentrate in premium handwash and lotion applications across Gulf Cooperation Council retail modernization.
Screw caps anchor current procurement volumes. Flip-top mechanisms are climbing the fastest in contract value terms.
End User:
Food-contact compliance costs are concentrating converter specialization while pharmaceutical margins attract new entrant investment.
- Food & Beverage:Carbonated soft drink and bottled water applications absorb the largest resin tonnage across Saudi Arabia's packaging conversion cluster. SASO recyclability labeling mandates are forcing reformulation timelines for existing supply agreements.
- Pharmaceuticals:Blow-fill-seal sterile bottles for Indian export markets carry CDSCO-aligned validation requirements that extend approval cycles. Premium pricing compensates for dedicated production line segregation.
- Personal Care:Shampoo and conditioner bottles in UAE retail chains are specifying minimum recycled content thresholds in procurement tenders.
- Household:Cleaning product containers in North Africa remain price-sensitive, with converters prioritizing virgin resin cost stability over sustainability credentials.
Food and beverage commands current volume leadership. Pharmaceutical-grade applications are gaining share fastest on margin expansion.
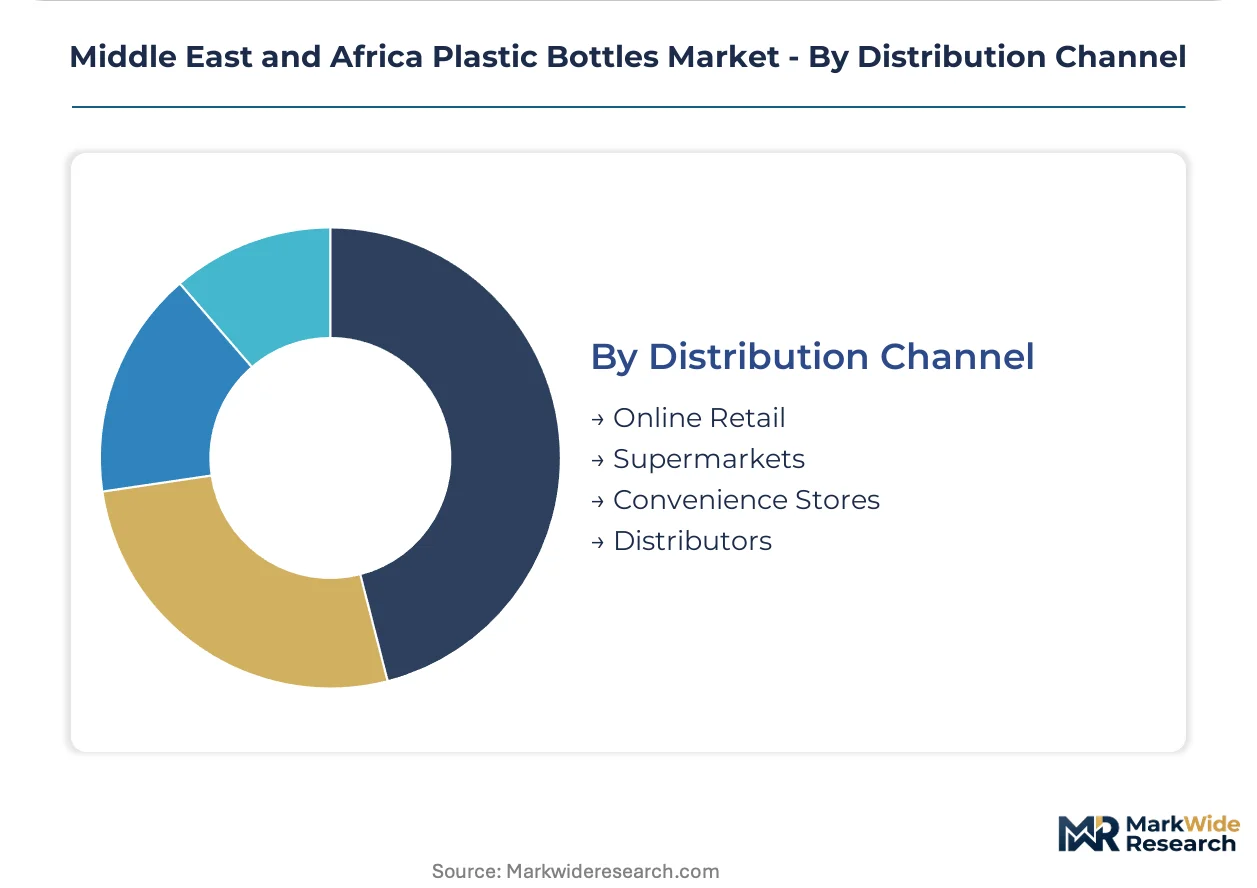
Distribution Channel:
Channel restructuring is unbundling packaging procurement from finished goods supply across South African retail consolidation.
- Supermarkets:Centralized procurement teams in Cape Town and Johannesburg are negotiating packaging-as-a-service terms rather than per-unit bottle pricing. Extended producer responsibility costs are shifting to converters.
- Distributors:Wholesale beverage distribution across Egypt's Nile Delta and Nigeria's northern states relies on bulk palletized bottle supply with gram-weight optimization for transport efficiency.
- Convenience Stores:Fragmented small-format retail in sub-Saharan markets outside South Africa limits standardized bottle specification adoption.
- Online Retail:E-commerce personal care sales in UAE and Saudi Arabia are driving demand for leak-proof closure validation and secondary protective packaging.
Supermarket consolidation defines today's procurement leverage. Online retail infrastructure is expanding most quickly as a channel-specific specification driver.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plastic bottle manufacturing in the Middle East and Africa traces its modern scale to Saudi Arabia's petrochemical build-out during the 1970s oil boom, which established the region's first integrated resin-to-conversion corridor. Today, demand clusters reflect divergent regulatory pressures and consumption patterns across the Arabian Peninsula, North Africa, and sub-Saharan markets.
Saudi Arabia
Bottled water and carbonated beverage demand from Saudi Arabia's young, urbanizing population sustains the region's largest packaging conversion cluster. SASO recyclability mandates and migration-limit testing are accelerating closed-loop collection infrastructure investment. Jubail Industrial City anchors resin supply through SABIC's petrochemical base, with converters requalifying formulations to maintain market access.
South Africa
Cape Town and Johannesburg host the continent's most sophisticated post-consumer PET recovery ecosystem, supporting rPET flake-to-preform integration for beverage contracts. Pending extended producer responsibility regulations will mandate recycled content thresholds, shifting procurement toward packaging-as-a-service models. Supermarket consolidation is centralizing bottle specification power among retail procurement teams.
Egypt
Nile Delta beverage distributors are driving gram-weight optimization in PET preform design to cut transport costs across dense urban corridors. EOS alignment with Gulf technical regulations is easing cross-border bottle trade into COMESA territories. Cairo's collection infrastructure sustains rPET feedstock availability for regional closed-loop contracts.
Nigeria
Lagos manufacturing zones anchor volume expansion through rising per-capita consumption of packaged hydration products in West African urban centers. Major bottlers are specifying minimum recycled content thresholds in resin supply agreements, eliminating spot-market virgin PET purchases for contracted volumes. Collection infrastructure gaps outside Lagos limit rPET scale-up.
United Arab Emirates
UAE retail modernization is driving flip-top closure adoption in personal care segments where single-hand dispensing commands premium pharmacy placement. Dubai and Abu Dhabi distribution hubs serve Gulf Cooperation Council markets with leak-proof closure validation for e-commerce personal care sales. Duty-free retail channels demand squeeze-dispensing LDPE formats for travel-size applications.
Middle East and Africa Plastic Bottles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and closure complexity tiers, with pharmaceutical-grade and food-contact segments absorbing the highest compliance costs. The vendor base spans multinational resin suppliers, regional packaging converters, and specialized recyclers. Three archetypes dominate: petrochemical-integrated resin producers, pan-regional packaging conglomerates with African distribution infrastructure, and post-consumer recycled content specialists serving retail chain mandates. Competitive moves concentrate on backward integration into rPET flake processing and strategic partnerships with beverage brand owners for closed-loop supply agreements.
Within the petrochemical-integrated tier, SABIC anchors regional resin supply from its Jubail Industrial City base. Among packaging specialists with African distribution reach, Amcor plc and Mpact Group occupy positions serving multinational beverage accounts and South African retail chains respectively. These three exemplify the divergent strategic paths—upstream resin control versus downstream recycling integration versus pan-regional logistics scale—that define competitive positioning across the Middle East and Africa Plastic Bottles Market.
| Leading Market Players |
|---|
| Alpla Packaging SA |
| Plastics For Africa |
| Nampak Bevcan |
| SABIC |
| Amcor plc |
| Mpact Group |
| Savola Plastics Company |
| Zamil Plastic |
| Polyoak Packaging Group |
| Others |
Pricing and Supply Chain Analysis
Ethylene feedstock costs originating from Saudi Aramco's Jubail petrochemical complex cascade through virgin PET pricing tiers, with rPET flake commanding contract premiums that compress virgin resin margins across beverage supply agreements in Lagos and Johannesburg.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and commodity utility levels segments the Middle East and Africa Plastic Bottles Market. Price differentiation hinges on SASO migration-limit compliance and rPET content thresholds specified by South African retail procurement teams. Cost compression in commodity beverage bottles intensifies because Nigerian bottlers are eliminating spot-market virgin PET purchases. Household chemical distributors in North Africa exhibit highest price sensitivity; pharmaceutical exporters to India-aligned markets absorb premium pricing with least negotiation leverage.
Supply Chain Analysis
Post-consumer bottle return flows from Cairo and Johannesburg collection hubs feed rPET flake-to-preform processing lines, creating reverse-logistics value capture that virgin resin suppliers cannot replicate. Raw material supply concentrates in Saudi Arabia's Eastern Province, Egypt's Nile Delta corridor, and South Africa's Cape Town-Johannesburg belt. Feedstock dependencies span ethylene from SABIC's Jubail base, PTA imports through Suez Canal logistics, and imported rPET flake for Nigerian converters. Single-source vulnerability to Gulf Cooperation Council regulatory shifts threatens margin stability. Distribution runs through supermarket centralized procurement in South Africa and wholesale beverage distributors across Egypt and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Plastic Bottles Market functions as a geographic-arbitrage corridor where South Africa's pending extended producer responsibility mandates create compliance cost differentials against Egypt's EOS-Gulf regulatory alignment that nimble converters can exploit.
For Market Incumbents: Anchor closed-loop rPET supply relationships with Johannesburg and Cairo recyclers to defend against circular-economy entrants capturing beverage brand owner contracts. Deepen backward integration into flake processing capacity before South Africa's packaging waste regulations mandate recycled content thresholds. Channel control through packaging-as-a-service terms with Cape Town supermarket procurement teams locks out mid-scale competitors. For New Entrants and Emerging Players: E-commerce personal care channels in UAE and Saudi Arabia offer lowest barrier-to-entry routes for leak-proof flip-top closure specialists. Kenya's pasteurized milk HDPE bottle segment remains below saturation with limited incumbent rPET capability. Direct supplier relationships with Dubai duty-free retail chains bypass established distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where post-consumer collection infrastructure gaps outside South Africa and Lagos strand mid-scale converters without rPET feedstock security. Long-term viability favors specialists with flake-to-preform integration or pharmaceutical-grade blow-fill-seal certification. Watch for SASO enforcement actions against non-compliant converters as inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Flake-to-Preform Integration | Captures closed-loop contracts with Nigerian and South African beverage bottlers specifying minimum recycled content. |
| SASO Recyclability Compliance Investment | Maintains market access for Saudi Arabia's Eastern Province converters facing mandatory migration-limit testing. |
| Packaging-as-a-Service Model | Shifts extended producer responsibility costs from Cape Town supermarket chains to converter balance sheets. |
| Flip-Top Closure Capability Addition | Penetrates UAE pharmacy chain premium placement for personal care dispensing convenience. |
| Pharmaceutical Blow-Fill-Seal Certification | Unlocks CDSCO-aligned export contracts from Indian-manufacturing facilities with extended approval timelines. |
Research Methodology
Direct dialogue with blow-mold plant managers, resin procurement leads at beverage bottlers, retail category buyers in Johannesburg and Cape Town, and SASO compliance officers grounded qualitative findings. Secondary validation drew from Egyptian Organization for Standardization technical regulations, Saudi Standards and Metrology Organization filings, South African National Regulator for Compulsory Specifications documentation, and customs trade data through COMESA territories. Bottom-up volume modeling triangulated against top-down petrochemical capacity assessments.
Segment-level projections across material type, closure mechanism, end-use application, and distribution channel fed aggregate market sizing across the projection horizon. CAGRs derived from weighted average of historical resin demand elasticity, regulatory implementation timelines, and per-capita bottled water consumption trajectories in Nigerian and South African urban centers. Feedstock price volatility assumptions and collection infrastructure build-out rates served as key sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for bio-based resin processing at scale would alter the outlook for petrochemical-integrated incumbents. Forecasts reflect assumptions about SASO enforcement consistency, South African extended producer responsibility implementation pace, and Nile Delta logistics cost stability. Practitioners should monitor Gulf Cooperation Council single-use plastic ban expansion, rPET flake import tariff movements, and pharmaceutical CDSCO alignment shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Egypt Plastic Packaging Market