
 GCC PET Packaging Market | 2026-2036
GCC PET Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC PET Packaging Market Intelligence
Preform-to-bottle conversion margins is reconfiguring value capture across the GCC PET packaging chain. SABIC leverages its upstream petrochemical integration to supply virgin PET resin at scale across the Arabian Peninsula. OCTAL anchors the regional market through its integrated PET sheet and resin operations in Oman, sustaining cost advantages in downstream conversion. Amcor plc competes on global formulation expertise, extending its technical service reach into Gulf beverage bottling operations.
GCC PET packaging comprises polyethylene terephthalate containers manufactured through injection-stretch blow molding or extrusion-thermoforming, with intrinsic viscosity typically ranging from 0.72 to 0.82 dL/g for carbonated beverage grades. The material delivers barrier performance against carbon dioxide and oxygen, preserving shelf stability in arid Gulf climates. Bottles dominate product type volumes, absorbing the majority of resin throughput from regional soft drink and bottled water producers. Injection molding technology leads capital deployment, though blow molding lines are expanding fastest as converters retrofit for lighter-weight designs. Food and beverage end users command the largest share of offtake, while pharmaceutical-grade demand is building on stricter SASO and Gulf Health Council compliance requirements.
SASO mandates food-contact material certifications that govern resin purity and migration limits for PET packaging sold in Saudi Arabia. The UAE's Ministry of Climate Change and Environment coordinates with Emirates Authority for Standardization and Metrology on extended producer responsibility frameworks that reshape collection and recycling infrastructure obligations. Gulf Cooperation Council customs union harmonization continues to simplify cross-border resin and preform movements among member states. Stakeholders must track how Saudi Arabia's local content requirements and the UAE's circular economy mandates interact to determine optimal plant location and recycling partnership strategies.
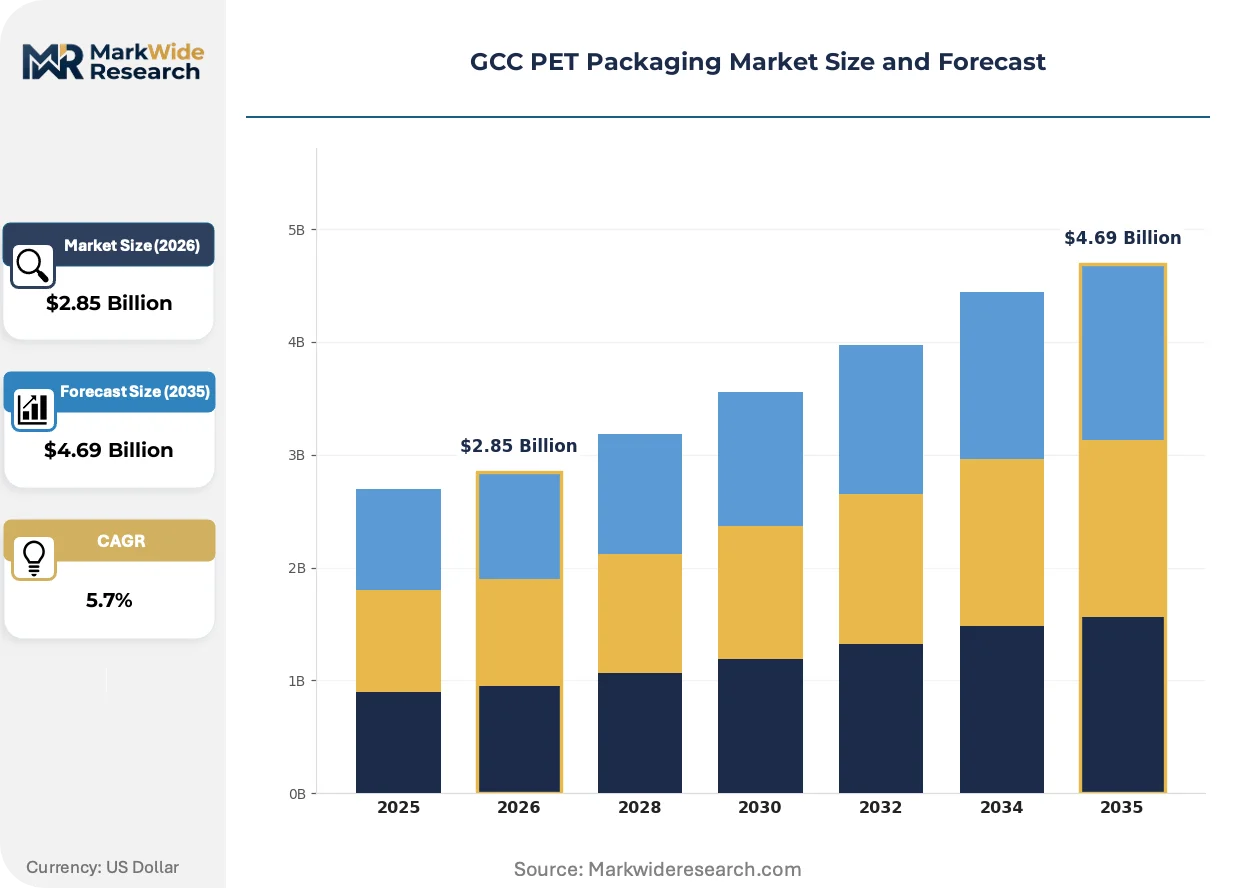
Market Dynamics
Preform-to-bottle conversion economics are restructuring value distribution across the GCC PET packaging chain, as upstream resin integration and downstream lightweighting mandates compress margins at the conversion tier.
Growth Catalysts
- SASO Technical Regulations:Saudi Arabia's food-contact material mandates on resin purity and migration limits are forcing bottlers to upgrade to pharmaceutical-grade PET specifications, expanding addressable premium volumes.
- Carbonated Soft Drink Bottlers:Major beverage producers across the Riyadh-Jeddah corridor are scaling PET procurement for extended shelf-life formulations suited to arid Gulf climates.
- Injection-Stretch Blow Molding:This process technology is displacing conventional extrusion-thermoforming in carbonated beverage applications, enabling lighter-weight bottle designs with equivalent barrier performance.
Market Restraints
- Upstream Resin Concentration:Virgin PET supply concentrates among integrated petrochemical producers with captive ethylene glycol feedstock, limiting converter bargaining power on the Arabian Peninsula.
- rPET Feedstock Scarcity:Post-consumer bottle collection rates remain below circular economy targets set by UAE's Ministry of Climate Change and Environment, constraining food-grade recycled content availability.
- Intrinsic Viscosity Degradation:Mechanical recycling processes reduce PET molecular weight below carbonated beverage grade thresholds, blocking closed-loop bottle-to-bottle applications without solid-state polymerization.
Strategic Opportunities
- Pharmaceutical-Grade PET:Stricter Gulf Health Council compliance requirements for primary packaging are opening technical service contracts for converters with SASO-certified cleanroom blow molding capabilities.
- Extended Producer Responsibility Frameworks:UAE-Emirates Authority for Standardization and Metrology coordination on collection infrastructure obligations is creating partnership openings for integrated resin-to-recycling operators.
- Hot-Fill Bottle Segments:Juice and ready-to-drink tea bottlers in Dubai's industrial zone are retrofitting lines for heat-set PET, a format with higher resin throughput per unit and specialized preform sourcing needs.
Industry Challenges
- Food-Contact Certification Timelines:SASO migration testing protocols for new resin grades impose 12-18 month approval cycles, delaying product launches for converters serving Saudi retail chains.
- Lightweighting Equipment Capex:Downgauge designs below 12 grams per 500ml bottle require high-speed blow molding line upgrades that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC PET Packaging Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.69 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Trays End User: Food & Beverage, Personal Care, Household, Pharmaceutical Technology: Injection Molding, Blowing, Extrusion, Thermoforming Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | SABIC, OCTAL, PAN-ASIA SAUDI CO., LTD, JBF RAK, Alpek, Arabian Packaging LLC, Huhtamaki Oyj, Amcor plc, Resilux NV, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC PET Packaging Market Strategic Shifts & Innovations
Barrier-enhancing material formulations and regulatory pressure on recycled content are compressing conventional PET specifications while opening technical differentiation paths for integrated suppliers.
Mono-material barrier coatings are collapsing the performance gap between standard PET and multilayer constructions for oxygen-sensitive beverages. Saudi bottlers of still water and vitamin-fortified drinks are trialing plasma-deposited silicon oxide layers at commercial scale. This technology is collapsing the premium commanded by imported multilayer bottles in Gulf retail channels.
UAE's extended producer responsibility frameworks are mandating post-consumer recycled content thresholds for beverage packaging sold through Dubai and Abu Dhabi retail chains. Emirates Authority for Standardization and Metrology is drafting harmonized testing protocols for rPET food-contact suitability. Bottled water producers with pan-GCC distribution are most affected, accelerating partnerships with Omani integrated sheet and resin operators for rPET offtake agreements.
Direct-store-delivery bottlers are consolidating preform procurement through regional toll conversion arrangements rather than maintaining captive blow molding operations. Smaller Saudi soft drink brands are outsourcing bottle production to specialized converters in the Riyadh-Jeddah corridor, trading capital intensity for volume flexibility. This pattern concentrates most visibly among private-label water bottlers serving Saudi supermarket chains, where price positioning limits in-house manufacturing justification.
GCC PET Packaging Market Segmentation
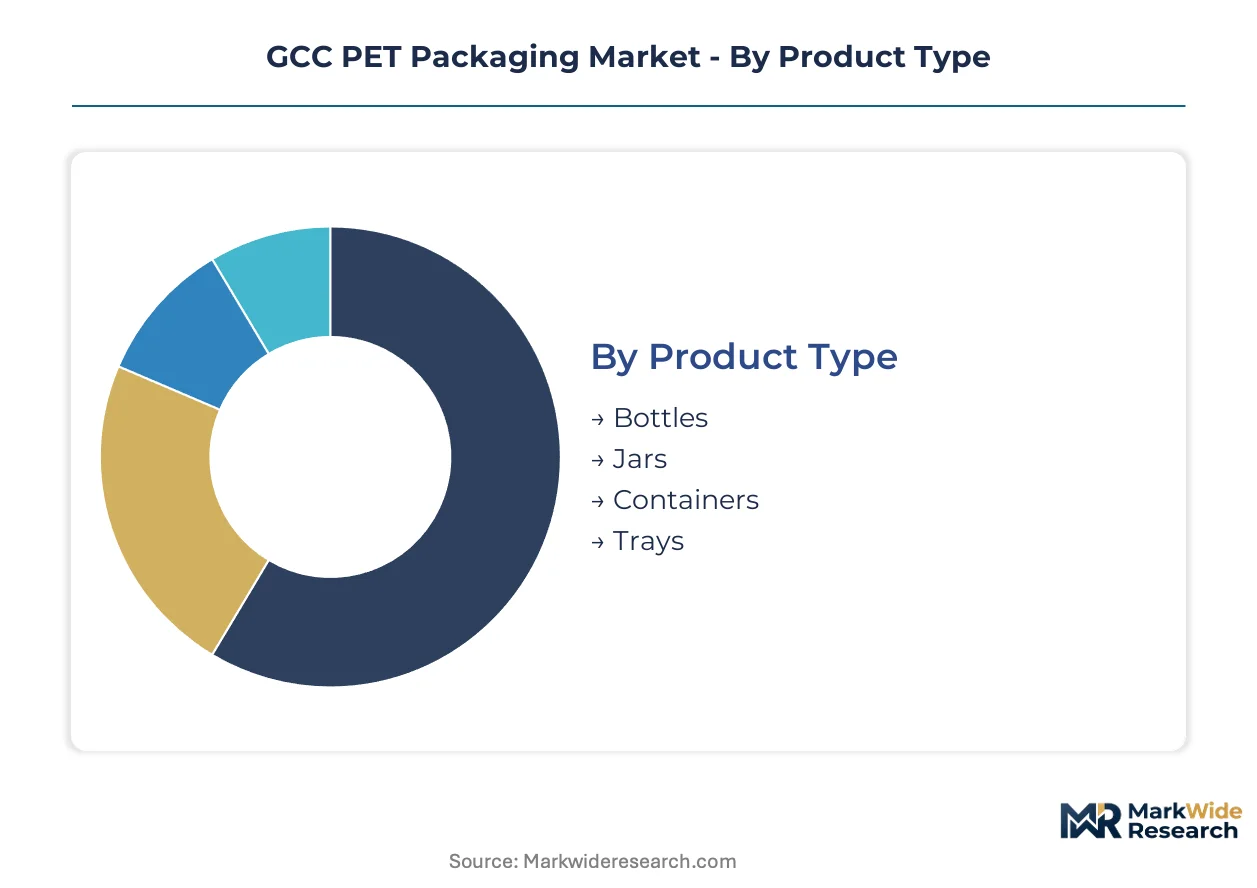
Segmentation in GCC PET packaging reveals how resin specifications, conversion technologies, and channel economics create distinct margin pools. Each dimension carries implications for capital deployment and regulatory compliance across Saudi Arabia and the UAE.
Product Type:
After-sales service intensity varies sharply by product format, with bottles demanding continuous technical support for line integration while trays require minimal converter engagement.
- Bottles:Carbonated beverage and bottled water formats dominate resin offtake, with intrinsic viscosity specifications of 0.72-0.82 dL/g for CO2 retention in Gulf heat. Demand concentrates along Saudi Arabia's Riyadh-Jeddah corridor where major bottlers are retrofitting for sub-12 gram lightweight designs.
- Jars:Wide-mouth containers for spreads and condiments use higher-IV resins for dimensional stability. UAE food processors in Dubai's industrial zone are expanding jar procurement for private-label retail programs.
- Containers:Clamshell and hinged formats serve prepared food and bakery segments with lower barrier requirements than beverage applications.
- Trays:Thermoformed formats for fresh produce and meat packaging absorb significant sheet resin volumes from Omani integrated operations.
Bottles hold the largest share; momentum sits with containers as food service formats expand.
End User:
Cost tier differentiation separates pharmaceutical-grade specifications from commodity beverage applications, with certification timelines and resin purity requirements driving price stratification.
- Food & Beverage:Bottled water and carbonated soft drink producers absorb the majority of regional PET resin throughput. Saudi bottlers are upgrading to SASO-certified pharmaceutical-grade specifications to access extended shelf-life formulations.
- Pharmaceutical:Primary packaging for solid-dose medications requires Gulf Health Council compliance and cleanroom blow molding capabilities. Demand is climbing fastest as regional regulators tighten material migration limits.
- Personal Care:Cosmetic and toiletry bottles use standard IV grades with emphasis on aesthetic clarity and color consistency rather than gas barrier performance.
- Household:Cleaning product containers prioritize chemical resistance and cost minimization over optical properties, typically sourcing from secondary resin grades.
Food & Beverage commands the largest share; Pharmaceutical is climbing the fastest on compliance-driven premium conversion.
Technology:
Volume concentration favors injection-stretch blow molding for beverage applications, while thermoforming retains cost advantages in sheet-based formats.
- Injection Molding:Preform production for stretch blow molding dominates capital deployment, with Saudi converters adding high-speed lines for lightweight bottle programs. The technology enables precise wall thickness control for carbonated beverage grades.
- Blowing:Stretch blow molding lines are expanding fastest as bottlers retrofit for downgauged designs below 12 grams per 500ml bottle.
- Extrusion:Sheet production for thermoforming serves food tray and blister pack segments with lower equipment intensity than injection systems.
- Thermoforming:Vacuum and pressure forming of extruded sheet produces containers and trays with minimal resin throughput per unit for price-sensitive applications.
Injection Molding holds the largest share; Blowing is gaining share fastest on lightweighting mandates.
Distribution Channel:
Customer type segmentation separates direct-store-delivery bottlers from retail-packaged goods, with procurement patterns dictating converter relationship structures.
- Retail:Hypermarket and supermarket chains in Saudi Arabia and the UAE are mandating post-consumer recycled content thresholds under extended producer responsibility frameworks.
- Wholesale:Bulk packaging for food service and institutional buyers prioritizes unit cost over aesthetic specifications, sourcing through regional toll converters.
- Direct Sales:Major beverage bottlers with captive blow molding operations procure resin directly from SABIC and integrated petrochemical suppliers.
- Online:E-commerce channels for specialty and premium formats remain nascent, with logistics constraints limiting bottle-to-pallet economics.
Retail holds the largest share; Direct Sales shows steepest expansion as bottlers consolidate preform procurement through toll arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Gulf Cooperation Council. Saudi bottlers absorb premium resin costs to secure SASO certifications, while smaller UAE converters prioritize toll arrangements that minimize capital exposure.
Saudi Arabia
Bottled water and carbonated soft drink producers along the Riyadh-Jeddah corridor drive PET resin procurement volumes. SASO technical regulations on food-contact material purity and migration limits compel pharmaceutical-grade upgrades. Jeddah's industrial zone hosts major preform conversion facilities retrofitting for sub-12 gram lightweight bottle designs.
United Arab Emirates
Extended producer responsibility frameworks from the Ministry of Climate Change and Environment reshape collection infrastructure obligations for beverage packaging. Emirates Authority for Standardization and Metrology coordinates harmonized rPET testing protocols for food-contact suitability. Dubai's industrial zone concentrates hot-fill bottle retrofitting activity for juice and ready-to-drink tea segments.
Oman
Integrated PET sheet and resin operations anchor regional supply through backward linkages to upstream petrochemical feedstock. The country's central bank monitors capital flows into downstream conversion capacity. Sohar's industrial port cluster facilitates resin export movements to Saudi and UAE bottling operations.
Qatar
Food service and institutional packaging demand absorbs thermoformed tray volumes for fresh produce distribution. The national standardization body aligns with Gulf Cooperation Council customs union harmonization for cross-border resin movements. Doha's logistics corridor channels imported preform supplies to local beverage bottlers.
Kuwait
Private-label water bottlers serving supermarket chains consolidate procurement through regional toll converters rather than captive operations. The Environment Public Authority tracks post-consumer collection rates against circular economy benchmarks. Shuwaikh's industrial area hosts mid-tier blow molding lines serving domestic beverage brands.
GCC PET Packaging Market Key Industry Players
Capability concentration sits with integrated petrochemical producers; scale advantage sits with global packaging specialists with formulation expertise. The market structures around three tiers: upstream resin suppliers with captive ethylene glycol feedstock, regional converters with integrated sheet-to-bottle operations, and international technical service providers. Dominant competitive moves include backward integration into resin production and strategic partnerships for rPET offtake agreements under extended producer responsibility mandates.
Among upstream-integrated suppliers, SABIC and OCTAL occupy positions defined by petrochemical feedstock access and geographic proximity to Arabian Peninsula demand centers. Amcor plc exemplifies the global specialist archetype, extending technical service reach through formulation expertise rather than resin supply control. These three anchors illustrate how competitive positioning splits between feedstock-integrated scale and technical-differentiated service models.
| Leading Market Players |
|---|
| SABIC |
| OCTAL |
| PAN-ASIA SAUDI CO., LTD |
| JBF RAK |
| Alpek |
| Arabian Packaging LLC |
| Huhtamaki Oyj |
| Amcor plc |
| Resilux NV |
| Others |
Cost & Logistics Intelligence
Single-source dependency on integrated petrochemical feedstock from SABIC and OCTAL determines both pricing tier spreads and supply chain shape across the Arabian Peninsula. Resin purity mandates from SASO and the Emirates Authority for Standardization and Metrology compress margins for converters lacking pharmaceutical-grade certification while amplifying premium capture for integrated suppliers with cleanroom capabilities.
Pricing Analysis
Long-term offtake contracts dominate resin procurement between Saudi bottlers and SABIC, insulating volume buyers from ethylene glycol spot volatility while spot purchases prevail among smaller UAE converters. Price differentiation separates pharmaceutical-grade SASO-certified resin from standard beverage grades, with Gulf Health Council compliance commanding measurable premiums. Cost compression in commodity beverage grades is intensifying as lightweighting mandates below 12 grams per 500ml bottle force equipment upgrades. Direct-store-delivery bottlers with captive operations show lowest price sensitivity; toll-dependent private-label water brands in Kuwait exhibit highest.
Supply Chain Analysis
Tariff exposure between Oman and Saudi Arabia remains minimal under Gulf Cooperation Council customs union harmonization, though regulatory divergence on rPET food-contact suitability creates compliance friction. Geographic supply concentration centers on Saudi Arabia for virgin resin, Oman for integrated sheet and bottle operations, and the UAE for hot-fill conversion and distribution. Raw material dependencies rest on purified terephthalic acid, monoethylene glycol, and increasingly post-consumer flake for circular content mandates. Single-source vulnerability concentrates in ethylene glycol feedstock tied to regional cracker operations. Distribution runs through Jeddah's industrial zone for Saudi bottlers and Dubai's logistics corridor for pan-GCC brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC PET packaging market represents high-growth disruption as extended producer responsibility frameworks and pharmaceutical-grade certification requirements simultaneously expand addressable premium volumes and erect compliance barriers. Injection-stretch blow molding displacement of conventional extrusion-thermoforming accelerates margin reconfiguration toward integrated resin-to-bottle operators.
For Market Incumbents: Pre-empt margin erosion from lightweighting mandates by securing backward integration into rPET flake processing or exclusive offtake partnerships with Omani integrated operators. Defend position by accelerating SASO pharmaceutical-grade certification timelines ahead of Gulf Health Council migration limit tightening, converting technical compliance into long-term technical service contracts with Riyadh-Jeddah corridor bottlers. For New Entrants and Emerging Players: Qatar's thermoformed tray segment for fresh produce distribution offers underpenetrated white-space with lower capital intensity than beverage-grade blow molding. Target toll conversion arrangements for Kuwaiti private-label water brands seeking to outsource capital-intensive operations. Enter through barrier-enhancing coating technology partnerships with Saudi still water bottlers trialing plasma-deposited silicon oxide layers. For Investors and Strategic Acquirers: UAE's extended producer responsibility framework reshapes the acquisition landscape by conferring strategic value on integrated resin-to-recycling operators with established collection infrastructure. Long-term viability favors assets with demonstrated rPET food-grade output and Emirates Authority for Standardization and Metrology testing protocol alignment. Watch for SASO approval acceleration for mechanically recycled resin grades as the signal indicating circular economy inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Processing | Secures food-grade recycled content supply under UAE extended producer responsibility thresholds. |
| SASO Pharmaceutical-Grade Certification Investment | Opens technical service contracts with Gulf Health Council-compliant pharmaceutical packaging demand. |
| Hot-Fill Bottle Line Retrofitting | Captures juice and ready-to-drink tea volume in Dubai's industrial zone with higher resin throughput. |
| Regional Toll Conversion Partnerships | Reduces capital exposure for Kuwaiti and Qatari bottlers consolidating preform procurement. |
| Barrier Coating Technology Licensing | Collapses premium on imported multilayer bottles for Saudi vitamin-fortified beverage producers. |
Research Approach
A standing panel of preform conversion plant managers, beverage procurement leads at Saudi bottlers, distribution channel partners in Dubai's logistics corridor, and technical R&D directors at resin suppliers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SASO technical regulation filings, Gulf Cooperation Council customs union documentation, Emirates Authority for Standardization and Metrology protocols, and petrochemical trade flow data. Bottom-up volume modeling from individual converter capacities and top-down resin demand estimates from beverage production statistics were triangulated for convergence.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, end-use industry, conversion technology, and distribution channel. Modeled categories included carbonated beverage versus still water grades, pharmaceutical versus food-contact specifications, injection-stretch blow molding versus thermoforming, and retail versus direct sales channels. CAGRs derived from historical resin throughput trends, capacity expansion announcements, and regulatory compliance timelines. Forecast inputs incorporated SASO certification approval cycles and UAE post-consumer collection rate trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by integrated petrochemical operators or accelerated rPET regulatory approvals would shift outcomes. Forecasts reflect assumptions on ethylene glycol feedstock availability and Gulf Health Council migration limit enforcement consistency. Macroeconomic deviation in oil-linked feedstock costs, regulatory acceleration on circular economy mandates, or breakthrough barrier coating technology adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Reusable Plastic Water Bottles Market