
 India Plastic Bottles Market | 2026-2036
India Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
India Plastic Bottles Market Insights
Multi-source resin procurement is restructuring supply economics for midsize converters across India. Manjushree Technopack Limited leverages captive preform manufacturing to lock in margin control across Karnataka and Tamil Nadu. Alpla Group anchors its India position through technical partnerships with multinational beverage brands requiring lightweighting compliance. Berry Global, Inc. competes on pharmaceutical-grade barrier technology for CDSCO-regulated packaging applications.
India plastic bottles are hollow thermoplastic containers, typically blow-molded from PET or HDPE resin with wall thickness calibrated for internal pressure resistance or chemical compatibility, serving as primary packaging for liquids and semi-solids across consumer and industrial supply chains. PET dominates beverage applications due to clarity, recyclability infrastructure, and stretch-blow processing efficiency at scale. HDPE sustains growth in household chemicals and personal care where chemical resistance and squeezability outweigh optical requirements. The 500ml capacity band leads volume across bottled water and soft drinks, while 200ml formats gain traction in pharmaceutical unit-dose and travel-size personal care segments.
BIS mandates IS 15495 compliance for PET containers in food-contact applications, while the Plastic Waste Management Rules enforce extended producer responsibility obligations that reshape converter cost structures and recycling partnerships. CDSCO packaging regulations for pharmaceuticals impose migration limits and stability testing that differentiate technical suppliers from commodity blow-molders. Stakeholders must monitor evolving EPR enforcement thresholds and state-level plastic ban implementations to calibrate capacity investments and resin diversification strategies.
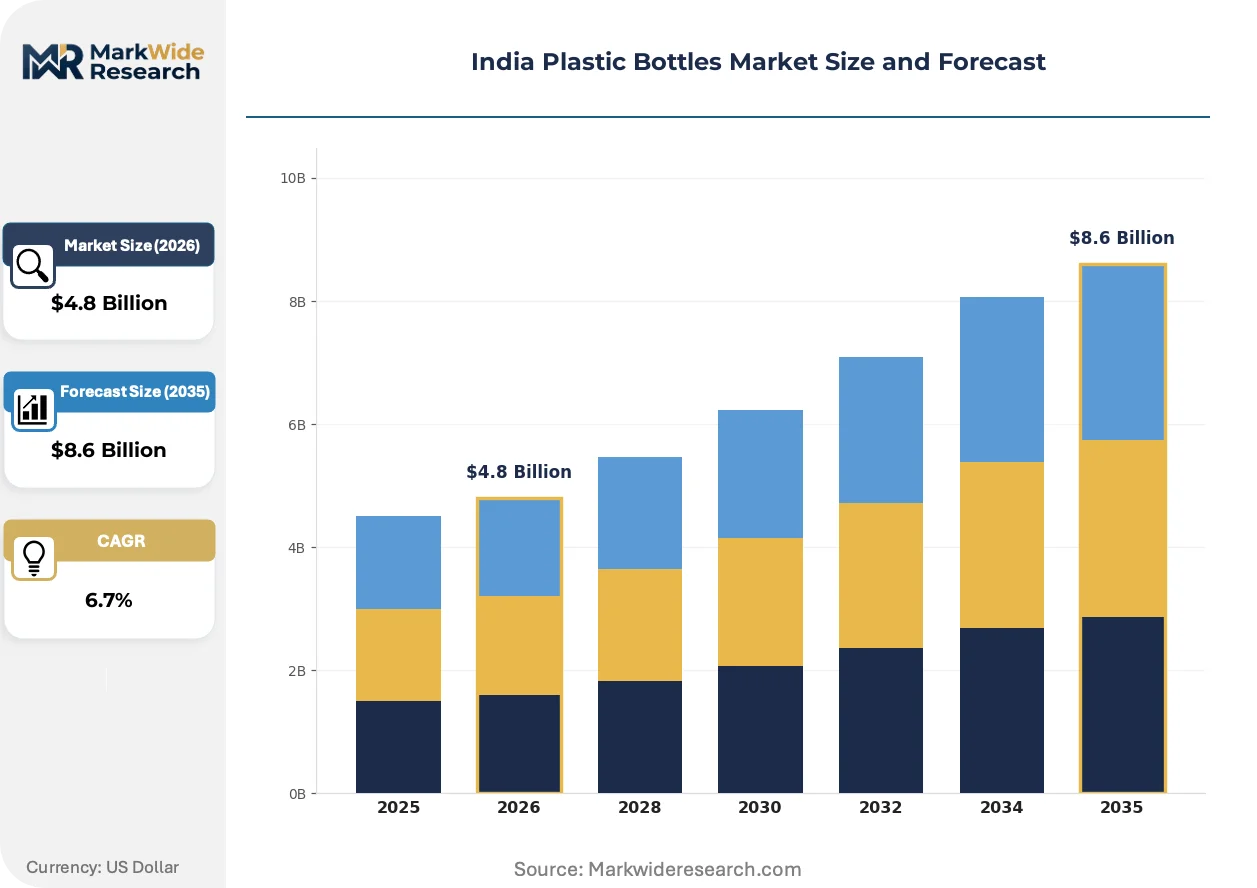
Market Dynamics
The Plastic Waste Management Rules and BIS certification mandates are compressing converter margins while forcing capital redeployment toward recycling infrastructure and food-contact compliance systems across Maharashtra and Gujarat.
Growth Catalysts
- Extended Producer Responsibility mandates:The Plastic Waste Management Rules obligate brand owners to finance collection and recycling, creating contracted demand streams for registered recyclers and integrated converters in western India.
- Beverage sector PET procurement:Carbonated soft drink and packaged water bottlers in Mumbai-Pune corridors are expanding stretch-blow capacity, pulling resin through long-term offtake agreements with domestic preform suppliers.
- Pharmaceutical barrier specifications:CDSCO migration limits and stability testing requirements for unit-dose packaging are differentiating technical blow-molders from commodity converters, rewarding investment in multilayer coextrusion and barrier coatings.
Market Restraints
- PET resin import dependency:Domestic PTA-MEG capacity constraints force converters to absorb rupee-dollar volatility and freight surcharges on purified terephthalic acid shipments from northeast Asian suppliers.
- State-level plastic ban fragmentation:Maharashtra's prohibition on single-use plastics operates alongside Gujarat's narrower restrictions, creating compliance complexity for national distributors and multi-state bottling networks.
- rPET food-contact approval delays:FSSAI has not finalized clearances for recycled PET in direct food applications, blocking circular economy investments that European and North American markets already permit.
Strategic Opportunities
- Tamil Nadu-Karnataka corridor underpenetration:Manjushree Technopack's captive preform network has not saturated southern India, leaving white space for converters with pharmaceutical-grade barrier capabilities near Bengaluru's biotech clusters.
- PLI scheme for specialty chemicals:The production-linked incentive scheme for petrochemicals could localize purified terephthalic acid production, reducing import exposure for midscale blow-molders in western India.
- 200ml pharmaceutical and travel formats:CDSCO-regulated unit-dose packaging and airline amenity segments are shifting from glass and laminate sachets toward barrier-enhanced HDPE bottles with child-resistant closures.
Industry Challenges
- Multilayer coextrusion technician scarcity:Barrier bottle production requires operators trained in EVOH distribution and adhesive tie-layer calibration, skills concentrated among Gujarat-based technicians with European equipment exposure.
- BIS IS 15495 certification timelines:Food-contact PET testing at BIS-approved laboratories creates six-to-nine month approval backlogs, delaying new converter market entry and product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plastic Bottles Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End User: Beverages, Personal Care, Household Chemicals, Pharmaceuticals Capacity: 200ml, 500ml, 1L, 2L Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Manjushree Technopack Limited, Alpla Group, Berry Global, Inc., AG Poly Packs Private Limited, JSK Plastic Industries, TPL Plastech, Hitech Corporation Limited, Bansal Polypacks, Amcor Rigid Plastics India Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plastic Bottles Market Trends and Innovations
Lightweighting compliance mandates and circular economy infrastructure investments are restructuring converter technology choices and resin procurement patterns across India's beverage and pharmaceutical packaging sectors.
Recycled PET flake-to-preform integration is modularizing converter supply chains, allowing midscale blow-molders to source food-grade rPET from domestic mechanical recyclers rather than virgin resin distributors. Beverage brand technical partnerships are accelerating adoption in Maharashtra, where EPR obligations create volume guarantees for registered recycling facilities. This modularization is compressing traditional resin distributor margins and rewarding converters with backward integration into flake washing and solid-state polymerization.
BIS IS 15495 compliance deadlines for food-contact PET are tightening migration testing protocols and documentation requirements for domestic converters. The standard's heavy metal and overall migration limits are forcing equipment upgrades in Gujarat-based facilities serving pan-India beverage distributors. Pharmaceutical packaging suppliers with existing CDSCO stability testing infrastructure are adapting faster than commodity blow-molders, capturing share in regulated segments.
Brand-owner procurement consolidation is compressing converter sales cycles and unbundling technical service from resin supply contracts. Multinational beverage companies in Mumbai-Pune corridors are centralizing preform purchasing through nominated suppliers, displacing fragmented distributor networks. This concentration is most visible in western India, where integrated converters with captive recycling partnerships are securing multi-year offtake agreements at the expense of standalone blow-molders.
India Plastic Bottles Market Segmentation
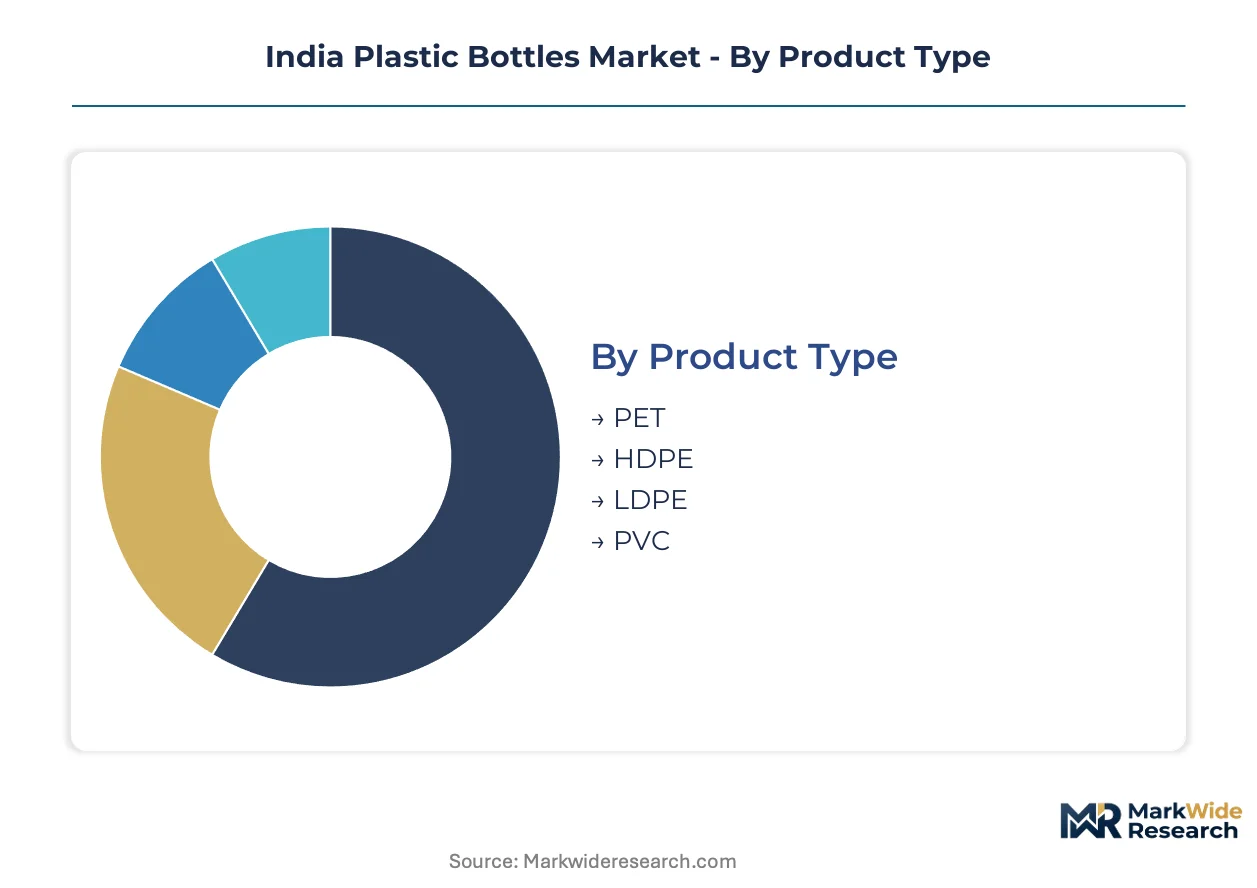
Segmentation in the India plastic bottles market reveals how resin chemistry, end-use specifications, and capacity formats create distinct competitive arenas. Buyers prioritize different performance attributes—barrier properties, chemical resistance, or optical clarity—shaping converter specialization and margin structures across Maharashtra and Gujarat.
Product Type:
Buyers differentiate primarily by clarity requirements, chemical compatibility, and recyclability infrastructure access.
- PET:Amorphous thermoplastic with exceptional optical clarity and biaxial orientation strength from stretch-blow processing. Beverage bottlers in Mumbai-Pune corridors specify PET for carbonated drinks and packaged water, drawn by established rPET collection infrastructure and BIS IS 15495 compliance pathways.
- HDPE:Semi-crystalline polyolefin delivering superior chemical resistance and stress-cracking performance. Household chemical and personal care brands across Gujarat favor HDPE for bleach, detergent, and shampoo applications where squeezability and moisture barriers outweigh transparency needs.
- LDPE:Lower-density polyethylene with enhanced flexibility and impact absorption for squeeze tubes and dispenser pumps. Personal care manufacturers specify LDPE for travel-size formats requiring soft-touch dispensing.
- PVC:Chlorinated polymer with rigid structural properties and chemical inertness for specialized industrial and pharmaceutical applications. Limited food-contact adoption due to plasticizer migration concerns under FSSAI scrutiny.
PET leads volumes today; HDPE is gaining share fastest in chemical-resistant segments.
End User:
Application-driven procurement separates commodity converters from technical specialists certified for regulated sectors.
- Beverages:Carbonated soft drinks, packaged water, and juices demanding clarity, CO₂ retention, and lightweighting compliance. Maharashtra bottlers anchor stretch-blow capacity expansion through long-term preform offtake agreements.
- Personal Care:Shampoo, conditioner, and lotion bottles requiring squeezability, aesthetic surface finish, and fragrance barrier properties. Tamil Nadu-Karnataka corridors show underpenetration for barrier-enhanced formats.
- Household Chemicals:Detergent, bleach, and surface cleaner containers prioritizing chemical resistance and child-resistant closure compatibility. Gujarat converters dominate this segment through HDPE extrusion expertise.
- Pharmaceuticals:Unit-dose and bulk packaging under CDSCO migration limits and stability testing mandates. Technical blow-molders with multilayer coextrusion capabilities capture premium positioning in Bengaluru's biotech clusters.
Beverages command the largest volume share; pharmaceuticals is expanding most quickly as CDSCO enforcement tightens.
Capacity:
Format selection tracks consumption occasion, distribution economics, and regulatory unit-dose requirements.
- 200ml:Compact format for pharmaceutical unit-dose, airline amenities, and travel-size personal care. CDSCO-regulated applications and airline procurement are shifting from glass toward barrier-enhanced HDPE with tamper-evident closures.
- 500ml:Standard single-serve volume for bottled water and soft drinks across retail and institutional channels. Mumbai-Pune bottling networks optimize stretch-blow economics at this capacity band through high-cavitation molds.
- 1L:Multi-serve household format for cooking oils, juices, and personal care refills. E-commerce fulfillment is driving demand for lightweight 1L designs with reinforced top-load strength.
- 2L:Family-size and institutional formats for beverages and household chemicals. Wholesale distribution in western India favors 2L for cost-per-volume efficiency in rural penetration.
500ml dominates current throughput; 200ml is climbing the fastest on pharmaceutical and travel-format demand.
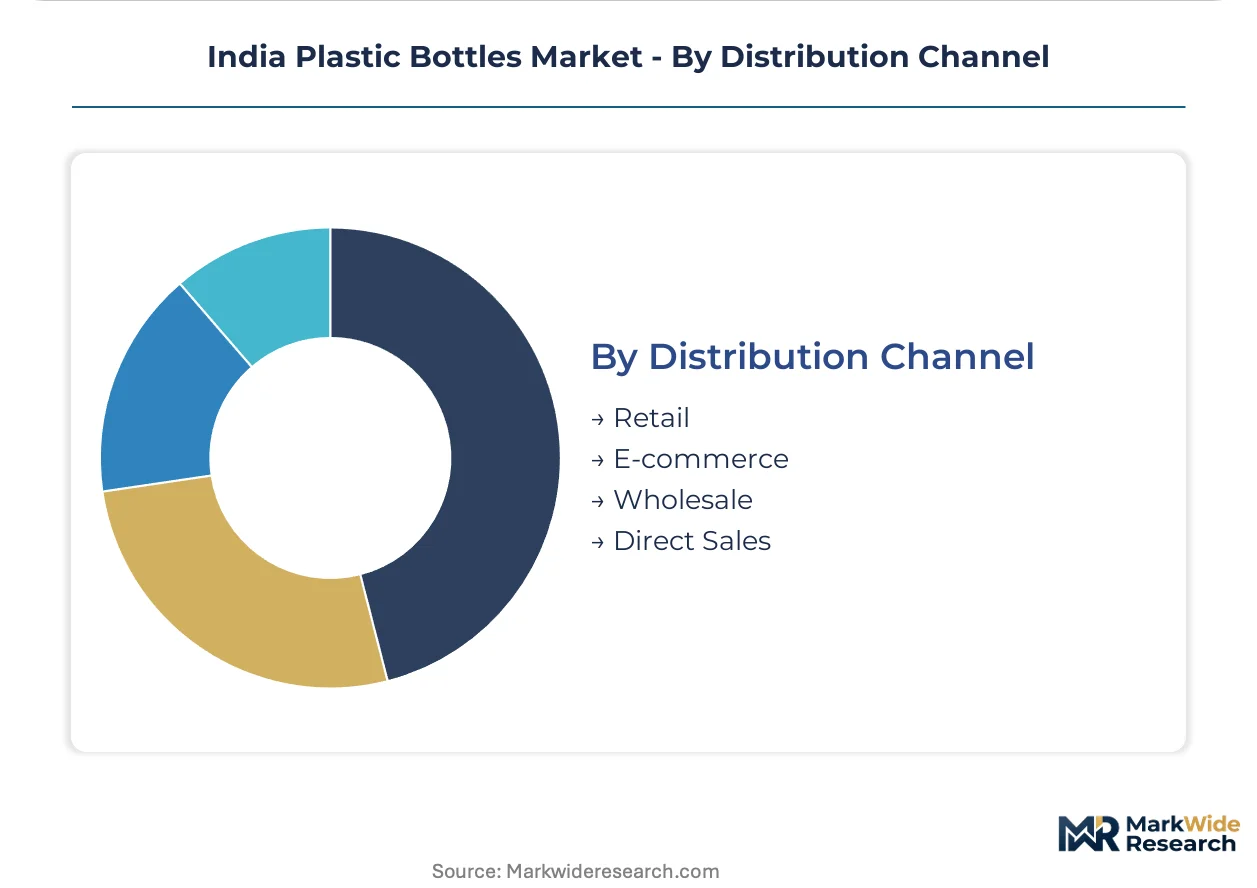
Distribution Channel:
Channel selection determines batch size requirements, labeling specifications, and logistics packaging complexity.
- Retail:Supermarkets, convenience stores, and kirana shops requiring shelf-ready packaging with barcode compliance and regional language labeling. Brand owners consolidate procurement through nominated suppliers in western India.
- E-commerce:Direct-to-consumer fulfillment demanding enhanced top-load strength and reduced dimensional weight. Mumbai-based converters are developing nested bottle designs for reduced freight cube.
- Wholesale:Bulk distribution to institutional buyers and rural distributors. Gujarat-based HDPE suppliers optimize for palletization efficiency and extended supply chain durability.
- Direct Sales:Converter-to-brand-owner relationships for private-label and contract manufacturing. Pharmaceutical and beverage technical partnerships concentrate direct sales among integrated preform producers.
Retail channels anchor volume today; e-commerce is gaining share fastest as fulfillment infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune industrial corridors anchor blow-molding capacity expansion across western India. Beverage bottlers concentrate PET procurement in Maharashtra and Gujarat. Southern states present underpenetrated white space for pharmaceutical-grade converters.
Maharashtra
Carbonated soft drink and packaged water bottlers drive stretch-blow capacity expansion through long-term preform offtake agreements. BIS IS 15495 compliance deadlines tighten migration testing protocols for food-contact PET containers. Mumbai-Pune corridors host integrated converters securing multi-year supply contracts with multinational beverage brands.
Gujarat
Household chemical and personal care brands favor HDPE extrusion for bleach, detergent, and shampoo applications. State-level plastic ban restrictions operate alongside Maharashtra's broader prohibitions, creating compliance complexity. Ahmedabad-Vadodara clusters dominate barrier bottle production with technicians trained in EVOH distribution and adhesive tie-layer calibration.
Karnataka
Manjushree Technopack's captive preform network has not saturated southern India, leaving expansion room for pharmaceutical-grade barrier capabilities. FSSAI has not finalized clearances for recycled PET in direct food applications, blocking circular economy investments. Bengaluru's biotech clusters attract technical blow-molders with multilayer coextrusion capabilities for CDSCO-regulated packaging.
Tamil Nadu
Personal care manufacturers specify LDPE for travel-size formats requiring soft-touch dispensing. PLI scheme for specialty chemicals could localize purified terephthalic acid production, reducing import exposure. Chennai-Coimbatore industrial belts show underpenetration for barrier-enhanced formats serving airline amenity segments.
Delhi-NCR
E-commerce fulfillment drives demand for nested bottle designs with enhanced top-load strength and reduced dimensional weight. Extended Producer Responsibility obligations under Plastic Waste Management Rules reshape converter cost structures. Gurugram-Noida corridors host distributors navigating state-level plastic ban fragmentation across northern markets.
India Plastic Bottles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade barrier specializations and captive recycling integration. The market structures around three tiers: integrated converters with backward resin control, technical specialists certified for CDSCO-regulated applications, and commodity blow-molders serving fragmented distributor networks. Two strategic archetypes dominate: scale-driven preform manufacturers leveraging long-term offtake agreements, and niche barrier-technology providers capturing premium positioning in regulated segments. Competitive moves concentrate on capacity expansion in western India and strategic partnerships with multinational beverage brands requiring lightweighting compliance.
Among India-based converters, Manjushree Technopack Limited, AG Poly Packs Private Limited, and JSK Plastic Industries exemplify distinct archetypes within the competitive structure. Manjushree Technopack occupies a position representing integrated preform manufacturing with geographic concentration in southern states. AG Poly Packs sits within the midscale converter tier serving regional distributor networks. JSK Plastic Industries represents commodity blow-molding operations competing on batch flexibility and shorter lead times. International operators including Alpla Group and Berry Global, Inc. anchor technical partnership positions with multinational brand owners requiring compliance with BIS and CDSCO regulations. Amcor Rigid Plastics India Private Limited exemplifies the multinational subsidiary archetype leveraging global barrier technology portfolios for pharmaceutical applications.
| Leading Market Players |
|---|
| Manjushree Technopack Limited |
| Alpla Group |
| Berry Global, Inc. |
| AG Poly Packs Private Limited |
| JSK Plastic Industries |
| TPL Plastech |
| Hitech Corporation Limited |
| Bansal Polypacks |
| Amcor Rigid Plastics India Private Limited |
| Others |
Pricing and Supply Chain Analysis
PTA-MEG spot indices cascading through Mumbai-Pune converter networks fragment pricing tiers across virgin PET, pharmaceutical-grade barrier, and recycled flake supply streams. Brand-owner procurement consolidation compresses distributor margins while EPR compliance costs embed into long-term offtake negotiations.
Pricing Analysis
Input-cost pass-through from imported purified terephthalic acid shipments anchors transactional pricing for commodity blow-molders, while technical specialists with multilayer coextrusion capabilities command premium positioning. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and standard utility grades separates CDSCO-compliant barrier suppliers from BIS-certified food-contact converters and ungraded commodity producers. Price erosion runs through standard PET tiers as integrated preform manufacturers leverage captive resin control. National beverage distributors show lowest price sensitivity due to lightweighting compliance mandates; regional household chemical brands in Gujarat exhibit highest sensitivity to freight-adjusted resin costs.
Supply Chain Analysis
Reverse-logistics flows from EPR-mandated collection networks feed mechanical recycling facilities in Maharashtra and Gujarat, creating modular flake-to-preform supply options for midscale converters. Domestic supply concentrates in western India, with northeast Asian PTA-MEG shipments and domestic HDPE resin from Reliance Industries anchoring raw material inputs. The chain draws from imported purified terephthalic acid, domestic polyethylene grades, and emerging rPET flake streams. Single-source vulnerability to rupee-dollar volatility on PTA shipments creates margin instability for non-integrated converters. Distribution runs through nominated supplier relationships with multinational beverage brands, displacing fragmented distributor networks in Mumbai-Pune corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India plastic bottles function as a stable compounder, with beverage sector PET procurement and pharmaceutical barrier specifications generating predictable demand visibility across the analysis window.
For Market Incumbents: Anticipate margin compression from BIS IS 15495 certification backlogs and EPR compliance cost escalation by securing captive recycling partnerships and locking in multi-year preform offtake agreements with Maharashtra-based beverage bottlers. Defensive positioning requires backward integration into flake washing and solid-state polymerization to offset virgin resin price volatility. For New Entrants and Emerging Players: Enter via pharmaceutical-grade barrier capabilities targeting Bengaluru's biotech clusters, where CDSCO migration limits and stability testing mandates differentiate technical suppliers from commodity converters. The Tamil Nadu-Karnataka corridor presents underpenetrated white space for 200ml unit-dose formats. A direct technical partnership approach with airline amenity procurement teams bypasses entrenched distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where EPR obligations and BIS compliance thresholds favor integrated converters with backward resin control over fragmented commodity blow-molders. Long-term viability centers on asset-light modular recycling integration rather than greenfield stretch-blow capacity. Acquisition targets should display captive preform manufacturing and pharmaceutical certification infrastructure. Monitor FSSAI rPET food-contact approval timelines as the critical inflection signal for circular economy investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Preform Manufacturing | Manjushree Technopack's Karnataka-Tamil Nadu network locks in margin control against resin volatility. |
| Multilayer Coextrusion Capacity | EVOH barrier technology captures CDSCO-regulated pharmaceutical packaging premiums in Bengaluru clusters. |
| rPET Flake Integration | Mechanical recycling partnerships satisfy EPR obligations for Maharashtra beverage brand contracts. |
| BIS IS 15495 Certification Investment | Food-contact compliance opens nominated supplier relationships with Mumbai-Pune bottling networks. |
| 200ml Format Specialization | Unit-dose pharmaceutical and airline amenity segments shift from glass toward barrier-enhanced HDPE. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Delhi-NCR, with primary inputs from each state cluster combining blow-molding plant managers, beverage procurement leads, pharmaceutical packaging technical directors, and recycling facility operators with secondary validation. BIS notification records, CDSCO packaging guidelines, FSSAI draft regulations, and PLI scheme disclosures for specialty chemicals anchored data triangulation alongside customs PTA-MEG import statistics and state-level plastic ban implementation circulars. Bottom-up capacity assessments across Mumbai-Pune and Ahmedabad-Vadodara corridors were cross-referenced against top-down demand estimates from beverage bottler expansion announcements.
Rate-of-change decomposition tracked resin price index movements, EPR enforcement escalation patterns, and certification timeline compression across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, end-use regulatory classification, capacity format, and geographic production cluster. CAGRs derived from weighted capacity expansion pipelines and brand-owner procurement consolidation trends, with specific inputs from stretch-blow equipment deployment cycles and multilayer coextrusion technician availability constraints in Gujarat.
Inputs from BIS-approved testing laboratories and CDSCO regional offices were available through the study window; gaps in FSSAI final rPET food-contact clearance timelines introduce uncertainty bands around circular economy investment forecasts. Practitioners should monitor state-level plastic ban enforcement consistency and FSSAI notification finalization for early signals of regulatory trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Recycled Plastic Envelope Market