
 Global Plastic Pails Market | 2026-2036
Global Plastic Pails Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Pails Market Foresight
The EU Green Deal is rebalancing procurement criteria across European manufacturing plants and food processing units toward post-consumer recycled content thresholds. Mauser Packaging Solutions leverages its closed-loop reconditioning network to sustain supply relationships with chemical producers seeking circular packaging credentials. Greif Inc. anchors North American volume through integrated blow-molding operations that compete on lead-time reliability for construction materials handling contracts.
Plastic pails are cylindrical containers molded from high-density polyethylene or polypropylene, typically featuring metal or plastic bail handles and capacities ranging from one to seven gallons, engineered for liquid and semi-solid containment across industrial and commercial supply chains. Tight head plastic pails dominate chemical storage applications where UN-certified closure integrity commands premium positioning, while stackable pails represent the fastest-growing configuration as agricultural enterprises and paint suppliers optimize warehouse cube utilization and transportation economics. Polyethylene sustains material leadership due to its stress-crack resistance and compatibility with both food-grade and hazardous material specifications.
REACH in Europe, FDA food-contact regulations in the United States, and BIS certification requirements in India collectively shape resin sourcing, migration testing protocols, and market access conditions for multinational suppliers. The EPA's emerging frameworks for recycled-content verification are forcing reformulation roadmaps among resin converters serving cross-border chemical and food packaging contracts. Stakeholders must monitor evolving Extended Producer Responsibility implementations across multiple jurisdictions to anticipate compliance cost reallocations and qualification timeline extensions.
Market Dynamics
REACH compliance deadlines and EPA recycled-content verification frameworks are forcing resin converters to requalify formulations faster than reconditioning networks can scale capacity, compressing supplier qualification timelines and fragmenting procurement pools.
Growth Catalysts
- Chemical Storage Mandates:UN-certified tight head pails command premium positioning as industrial buyers prioritize sealed containment for hazardous materials handling.
- EU Green Deal Thresholds:Post-consumer recycled content requirements are rebalancing procurement criteria across European manufacturing plants and food processing units.
- India Agricultural Distribution:Stackable pail configurations optimize last-mile logistics for paint suppliers and agricultural enterprises scaling warehouse operations.
Market Restraints
- Resin Price Volatility:High-density polyethylene feedstock costs fluctuate with crude oil indices, squeezing converter margins on fixed-price construction contracts.
- Reconditioning Capacity Bottlenecks:Closed-loop recovery networks concentrate in Western Europe and the US Midwest, leaving Asia-Pacific buyers dependent on virgin resin supply.
- Metal Pail Substitution:Steel drums retain share in solvent-based coatings where thermal stability exceeds polyethylene performance limits.
Strategic Opportunities
- Indian BIS Certification Gap:Domestic suppliers lack certified food-grade blow-molding capacity, creating white space for multinationals meeting FSSAI migration testing protocols.
- Digital Inventory Integration:RFID-enabled pail tracking converges with warehouse management systems, enabling chemical producers to monetize container-level traceability.
- EU Extended Producer Responsibility:Packaging waste directive implementations fund collection infrastructure that lowers post-consumer resin feedstock costs for compliant converters.
Industry Challenges
- Migration Testing Backlogs:FDA and EFSA protocol updates extend qualification timelines for food-contact pail launches, delaying revenue recognition.
- Multi-Jurisdiction Compliance:Simultaneous REACH, BIS, and EPA framework navigation fragments regulatory affairs staffing across mid-cap resin converters.
- Legacy Blow-Molding Retooling:Transitioning to co-extrusion lines for recycled-content layers demands capital deployment that family-owned converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Pails Market |
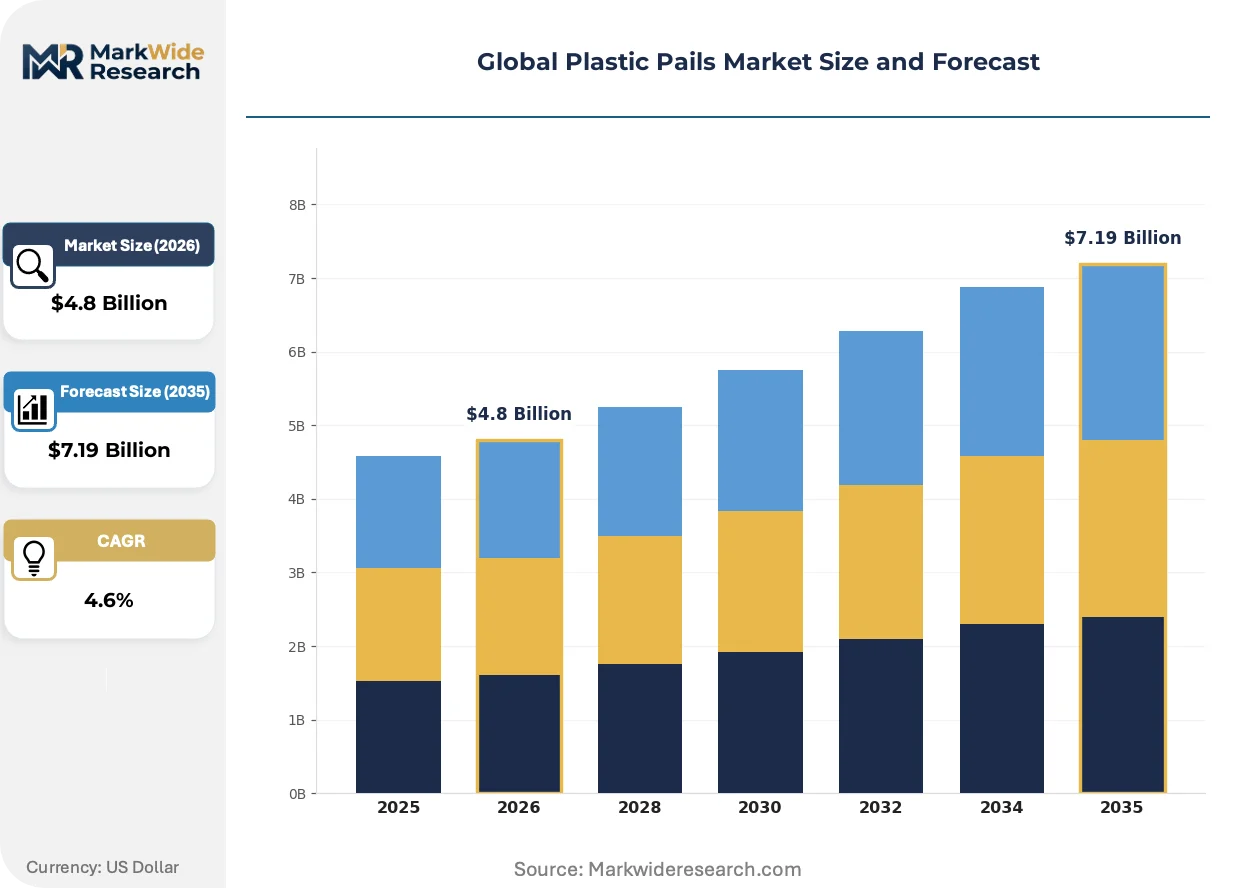
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Pails with Lids, Open Head Plastic Pails, Tight Head Plastic Pails, Stackable Pails, Bucket Containers Material: Polyethylene, Polypropylene, Polycarbonate, Polyvinyl Chloride, Polystyrene Application: Chemical Storage, Food & Beverage Packaging, Agricultural Use, Paint & Coatings, Construction Materials Handling End User: Manufacturing Plants, Food Processing Units, Agricultural Enterprises, Paint Suppliers, Construction Contractors |
| Companies Covered | Mauser Packaging Solutions, Greif Inc., Berry Global Inc., Time Technoplast Ltd., BWAY Corporation, Letica Corporation, M&M Industries Inc., Plastipak Holdings Inc., NCI Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Pails Market Shifts & Advancements
Active barrier coating technologies and digital traceability systems are compressing the traditional specification cycle, enabling real-time compliance verification that redefines supplier-buyer contracting terms.
Co-extruded multilayer polyethylene structures with EVOH oxygen barriers are rewriting performance benchmarks for food-grade pail applications. Dairy processors and sauce manufacturers in Germany and the Netherlands are adopting these configurations within 18-month replacement cycles. The technology is compressing metal can penetration in shelf-stable condiments by matching 24-month shelf life at lower tare weight.
EPA's emerging recycled-content verification frameworks are forcing cross-border reformulation roadmaps among resin converters serving chemical and food packaging contracts. Migration testing protocols now require documentation of post-consumer feedstock chain of custody from collection through pelletization. North American converters serving multinational accounts face the steepest compliance cost reallocations as state-level Extended Producer Responsibility laws diverge from federal guidance.
Consolidated procurement desks at agricultural cooperatives and construction material distributors are compressing supplier rosters to single-source arrangements with integrated reconditioning capabilities. Direct contracting between pail converters and end-users is displacing traditional packaging distributor intermediaries in the US grain belt and Indian Punjab farming clusters. This concentration is most visible where just-in-time delivery requirements punish inventory-holding middlemen.
Global Plastic Pails Market Segmentation
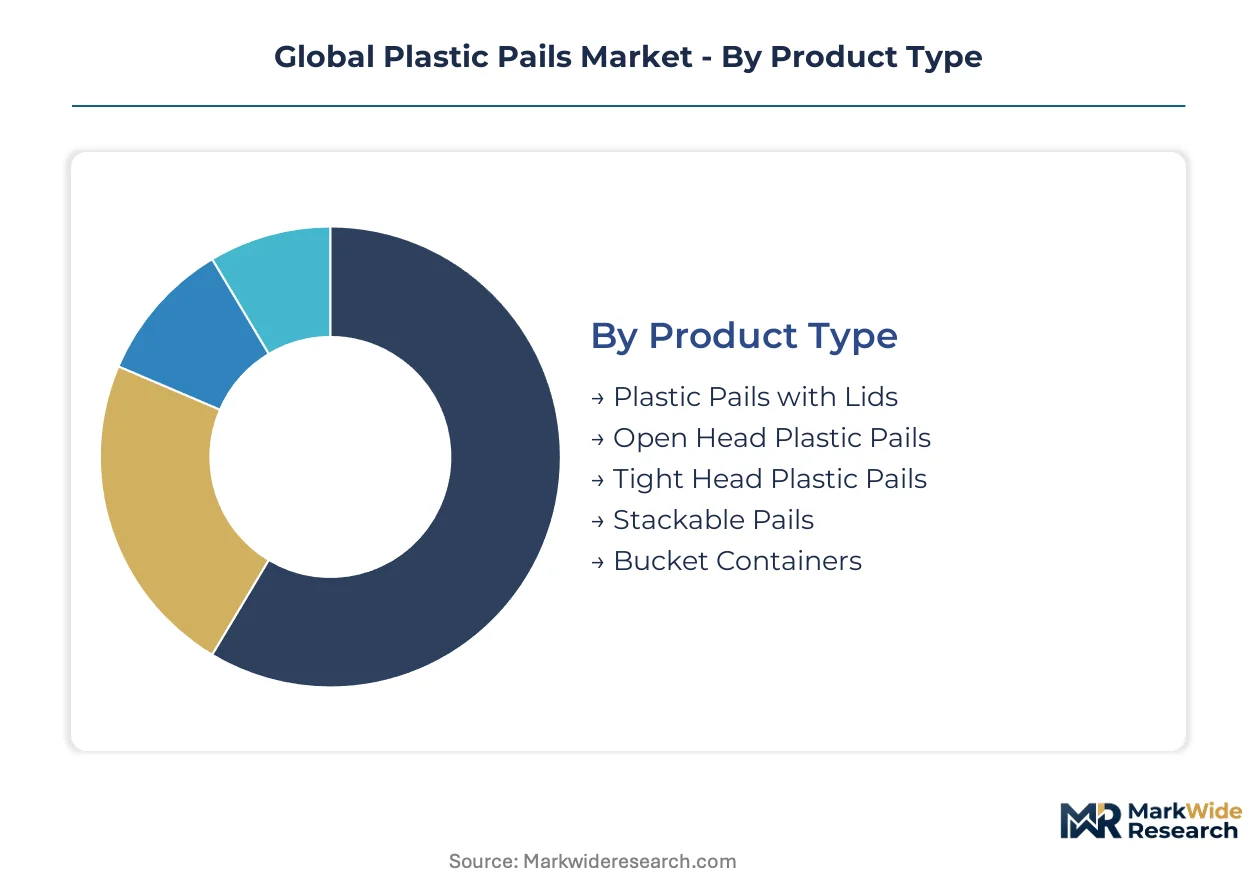
Plastic pail procurement patterns diverge sharply across container configurations and material specifications, with chemical handlers demanding UN-certified closure integrity while agricultural distributors prioritize cube-optimized logistics. Understanding these segment boundaries clarifies where converter investments in co-extrusion capacity or reconditioning networks yield differentiated returns.
Product Type:
Standalone containment systems dominate hazardous material applications where regulatory certification travels with the container itself, while embedded pail configurations integrate into broader packaging ecosystems for food and agricultural distribution.
- Tight Head Plastic Pails:These sealed cylindrical containers feature permanently attached lids with gasketed closure systems certified for UN hazardous material transport. Chemical producers in Germany and the Netherlands specify these configurations for solvent and agrochemical storage where ECHA REACH compliance mandates documented containment integrity.
- Stackable Pails:Engineered with interlocking rim geometries and reinforced sidewalls, these containers maximize warehouse density and truckload cube utilization. Agricultural enterprises in India's Punjab region and paint suppliers in Maharashtra are scaling procurement of these configurations to compress last-mile distribution costs.
- Plastic Pails with Lids:Removable lid designs serve general-purpose industrial applications where frequent access outweighs sealed containment requirements.
- Open Head Plastic Pails:Wide-mouth configurations facilitate manual filling and scooping operations in construction materials handling and food ingredient processing.
- Bucket Containers:Lower-capacity variants address consumer and light commercial applications where portability supersedes bulk logistics efficiency.
Volume placements concentrate in Tight Head Plastic Pails; the faster expansion belongs to Stackable Pails.
Material:
Resin selection stratifies across cost tiers, with commodity polyolefins anchoring high-volume construction and agricultural applications while engineering polymers capture premium food-contact and chemical-barrier specifications.
- Polyethylene:High-density polyethylene dominates industrial pail production through superior stress-crack resistance and broad chemical compatibility. FDA food-contact and EPA hazardous material specifications both accommodate HDPE formulations, enabling converters to serve dual-use contracts without resin line changes.
- Polypropylene:Higher melting points and rigidity suit hot-fill applications and steam sterilization protocols. Food processing units in the US Midwest specify polypropylene pails for sauce and dairy applications where thermal stability exceeds polyethylene performance limits.
- Polycarbonate:Optical clarity and impact resistance serve specialized pharmaceutical and laboratory containment where visual inspection matters.
- Polyvinyl Chloride:Cost-positioned resin captures price-sensitive construction materials handling where regulatory scope excludes food contact.
- Polystyrene:Lightweight, rigid structures address foam-lined protective packaging and disposable applications with limited reuse cycles.
Polyethylene captures the dominant placement share; polypropylene is climbing the fastest as hot-fill food applications expand.
Application:
Application segmentation tracks customer workflow integration depth, with chemical storage representing standalone safety-critical systems versus food packaging embedded within broader supply chain traceability requirements.
- Chemical Storage:UN-certified pail specifications command premium positioning through mandatory closure testing, permeation documentation, and ECHA REACH registration alignment. Industrial buyers prioritize sealed containment systems where failure liability exceeds container cost by orders of magnitude.
- Paint & Coatings:Solvent-based formulations drive tight head requirements while water-based coatings tolerate open head configurations. Paint suppliers in India and Germany are consolidating procurement around stackable formats to optimize warehouse automation compatibility.
- Food & Beverage Packaging:FDA and EFSA migration testing protocols govern resin selection and barrier layer design for dairy, sauce, and ingredient handling.
- Agricultural Use:Fertilizer and seed treatment applications demand UV stabilization and stackable geometries for seasonal distribution surges.
- Construction Materials Handling:Adhesives, sealants, and coatings procurement prioritizes cost efficiency over certification complexity for non-hazardous formulations.
Chemical Storage anchors revenue concentration; Paint & Coatings shows the steepest expansion trajectory as water-based formulation transitions accelerate.
End User:
Customer type segmentation reflects procurement sophistication tiers, with multinational chemical producers imposing qualification protocols that exclude mid-cap converters while agricultural cooperatives prioritize logistics integration over technical specification depth.
- Manufacturing Plants:Integrated chemical and pharmaceutical producers specify pail systems as part of validated containment workflows. These buyers demand batch-level traceability, documented chain of custody, and alignment with EPA emerging recycled-content verification frameworks.
- Agricultural Enterprises:Cooperatives and large farming operations in India and the US grain belt are compressing supplier rosters to single-source arrangements with integrated reconditioning capabilities. Direct contracting with converters displaces traditional packaging distributors where just-in-time delivery requirements punish inventory-holding intermediaries.
- Food Processing Units:Dairy processors and sauce manufacturers in Germany and the Netherlands drive adoption of co-extruded EVOH barrier configurations.
- Paint Suppliers:Formulation companies balance chemical compatibility requirements with branding and label adhesion specifications.
- Construction Contractors:Price-sensitive procurement favors standard open head configurations for non-hazardous material handling.
Manufacturing Plants dominate contract value; Agricultural Enterprises are gaining share fastest as cooperative procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American chemical pail procurement, with integrated petrochemical complexes feeding blow-molding operations that serve Gulf Coast refineries and agricultural distribution networks.
United States
Construction materials distributors in the Midwest grain belt and paint suppliers in the Southeast are consolidating procurement around stackable formats with RFID traceability. EPA recycled-content verification frameworks are forcing reformulation roadmaps among resin converters serving cross-border chemical contracts. Ohio and Michigan host the densest concentration of reconditioning networks serving automotive coatings plants.
Germany
Dairy processors in Bavaria and sauce manufacturers in the Ruhr region are adopting co-extruded EVOH barrier pails within compressed replacement cycles. ECHA REACH compliance deadlines mandate documented containment integrity for solvent and agrochemical storage. The Port of Rotterdam corridor supplies feedstock to blow-molding operations concentrated in North Rhine-Westphalia.
India
Agricultural cooperatives in Punjab and paint suppliers in Maharashtra are scaling procurement of stackable pails to optimize last-mile distribution economics. BIS certification requirements and FSSAI migration testing protocols create qualification barriers for domestic converters lacking certified food-grade capacity. Gujarat hosts emerging blow-molding clusters serving pharmaceutical and chemical export contracts.
Netherlands
Food processing units in the Randstad region specify co-extruded multilayer polyethylene structures for shelf-stable condiment handling. EU Green Deal post-consumer recycled content thresholds are rebalancing procurement criteria across manufacturing plants. The Eindhoven technology corridor incubates digital traceability integration for container-level supply chain verification.
China
Chemical producers in the Yangtze River Delta and construction materials distributors in the Pearl River Delta are driving volume procurement of tight head configurations. GB standards and emerging dual carbon goals are pressuring resin converters toward recycled-content layer integration. Shandong Peninsula hosts the fastest-expanding blow-molding capacity serving domestic agricultural chemical formulation.
Global Plastic Pails Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and reconditioning network integration. The vendor base stratifies into three tiers: integrated multinationals with closed-loop recovery systems, regional specialists with blow-molding scale advantages, and family-owned converters competing on lead-time reliability. Strategic moves concentrate on co-extrusion line retooling for recycled-content layers and direct contracting partnerships with agricultural cooperatives bypassing traditional distributor intermediaries.
Among integrated packaging multinationals, Mauser Packaging Solutions exemplifies the closed-loop reconditioning archetype through its recovery network sustainability positioning. Greif Inc. anchors North American volume leadership through integrated blow-molding operations competing on construction materials handling contracts. Time Technoplast Ltd. occupies the emerging market specialist tier, with its India-based operations representing the geographic pivot toward agricultural and paint distribution growth corridors.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Greif Inc. |
| Berry Global Inc. |
| Time Technoplast Ltd. |
| BWAY Corporation |
| Letica Corporation |
| M&M Industries Inc. |
| Plastipak Holdings Inc. |
| NCI Packaging |
| Others |
Supply & Pricing Matrix
EU Green Deal post-consumer recycled content thresholds gate qualified supply and premium-tier pricing access, compressing converter margins for non-compliant producers while rewarding closed-loop reconditioning networks with pricing power over chemical and food-grade contracts.
Pricing Analysis
UN-certified containment integrity anchors value-based pricing for tight head pails serving hazardous material handlers, where failure liability dwarfs container cost. Price differentiation separates ECHA REACH-compliant configurations from standard industrial grades, with German chemical producers paying premiums for documented migration testing. Cost compression in commodity polyethylene tiers intensifies as resin converters absorb crude oil-linked feedstock volatility on fixed-price construction contracts. Agricultural cooperatives in India exhibit highest price sensitivity, while pharmaceutical and dairy processors in Germany and the Netherlands show lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with virgin resin supply to Asia-Pacific buyers, where closed-loop recovery networks concentrate in Western Europe and the US Midwest. Feedstock sourcing draws from Saudi Arabian and US Gulf Coast petrochemical complexes for high-density polyethylene, with secondary dependence on South Korean and Singaporean resin exports. Tariff exposure on cross-border chemical packaging contracts fragments procurement pools as EPA recycled-content verification frameworks diverge from state-level Extended Producer Responsibility implementations. Distribution runs through direct converter-to-cooperative arrangements in India's Punjab region and the US grain belt, displacing traditional packaging distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing backward integration into reconditioning networks to capture circular packaging credentials and lock in chemical producer contracts.
For Market Incumbents: Anchor market position through captive reconditioning capacity expansion in North Rhine-Westphalia and Gujarat, defending against metal pail substitution in solvent-based coatings by co-developing active barrier coating technologies with agrochemical formulators. Prioritize EVOH co-extrusion line retooling before FDA migration testing protocol updates extend competitor qualification timelines. For New Entrants and Emerging Players: Direct-to-agricultural-cooperative platforms offer the most penetrable route, targeting India's domestic suppliers lacking BIS-certified food-grade blow-molding capacity. White space exists in RFID-enabled pail tracking integration for warehouse management systems, with Maharashtra paint suppliers and Punjab farming clusters as initial beachheads. Pursue FSSAI migration testing qualification to differentiate from uncertified local converters. For Investors and Strategic Acquirers: EPA recycled-content verification framework finalization is the leading indicator that resin converter consolidation will accelerate, as family-owned operators face unsustainable capital demands for co-extrusion line transitions. Long-term viability favors vertically integrated packaging multinationals with existing reconditioning networks and cross-border regulatory affairs staffing. Watch for state-level Extended Producer Responsibility law divergence as the signal for compliance cost reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reconditioning Networks | Closed-loop recovery capacity locks in chemical producer contracts requiring circular packaging credentials under EU Green Deal thresholds. |
| Co-extrusion Line Retooling for Recycled-Content Layers | EVOH barrier integration enables dairy processors in Bavaria to match metal can shelf life at lower tare weight. |
| Direct-to-Cooperative Distribution Bypass | Eliminating distributor intermediaries captures margin compression in India's agricultural last-mile logistics optimization. |
| RFID-Enabled Container Traceability Integration | Real-time compliance verification redefines contracting terms with manufacturing plants requiring batch-level documentation. |
| BIS/FSSAI Certification Investment | Food-grade blow-molding qualification creates defensible positioning in India's domestic supply gap for pharmaceutical and dairy applications. |
Research Methodology
Document review covered trade customs data, SEC filings from packaging multinationals, ECHA REACH registration databases, and BIS certification records, complemented by interviews with blow-molding plant managers, procurement leads at chemical and paint formulators, agricultural cooperative supply chain directors, and regulatory affairs specialists navigating FDA and EPA frameworks. Bottom-up volume modeling from converter capacity and utilization rates was cross-referenced against top-down demand aggregation from end-use industry consumption patterns.
Historical shipment data was cross-referenced against expert panel input from resin suppliers and reconditioning network operators to derive expansion trajectories across the projection horizon. Segmentation modeling incorporated product configuration, material specification, application workflow integration, and end-user procurement sophistication tiers. CAGRs were computed from annual growth rate interpolation between base and terminal values, with sensitivity testing against crude oil price indices and regulatory implementation timelines.
The model holds under stable resin feedstock pricing and phased regulatory implementation; deviation in sudden ECHA enforcement actions or EPA framework acceleration would shift qualification timeline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Polyethylene Terephthalate-Glycol (PETG) Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Cast Films Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market