
 Carton Display Market | 2026-2036
Carton Display Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Display Market Outlook
China is rewriting capacity dynamics for corrugated board converting as domestic brands and exporters alike scale automated die-cutting and gluing lines. Smurfit Kappa Group leverages integrated pulp-to-box operations across European retail networks. WestRock Company anchors North American supply through mill-based containerboard production. Mayr-Melnhof Karton AG specializes in coated recycled board for premium cosmetic and confectionery displays.
Carton displays are point-of-sale structures fabricated from paperboard or corrugated fiberboard, typically ranging from 200 to 1,200 grams per square meter in basis weight, designed to present merchandise at eye level or traffic focal zones within retail environments. Their primary commercial purpose is to convert foot traffic into unplanned purchases while reducing shelf-stocking labor. Floor displays command the largest volume share among product types due to their versatility across seasonal promotions and high-traffic aisle ends. Recycled materials represent the fastest-expanding material category as retailer ESG procurement policies harden. Custom designs capture disproportionate margin pools because brand owners pay premiums for structural differentiation and print fidelity.
The EU Packaging and Packaging Waste Regulation and the US EPA sustainable materials management framework are elevating post-consumer recycled content thresholds, forcing converters to certify chain-of-custody documentation. ISO 14001 environmental management systems increasingly gate supplier qualification for multinational retail chains. Stakeholders must monitor how extended producer responsibility fee structures in California and New York reshape total cost of ownership for disposable display formats.
Market Dynamics
Supermarket chains are consolidating purchasing power around automated replenishment systems, forcing carton display converters to embed RFID-enabled inventory tracking directly into corrugated structures at the factory floor.
Growth Catalysts
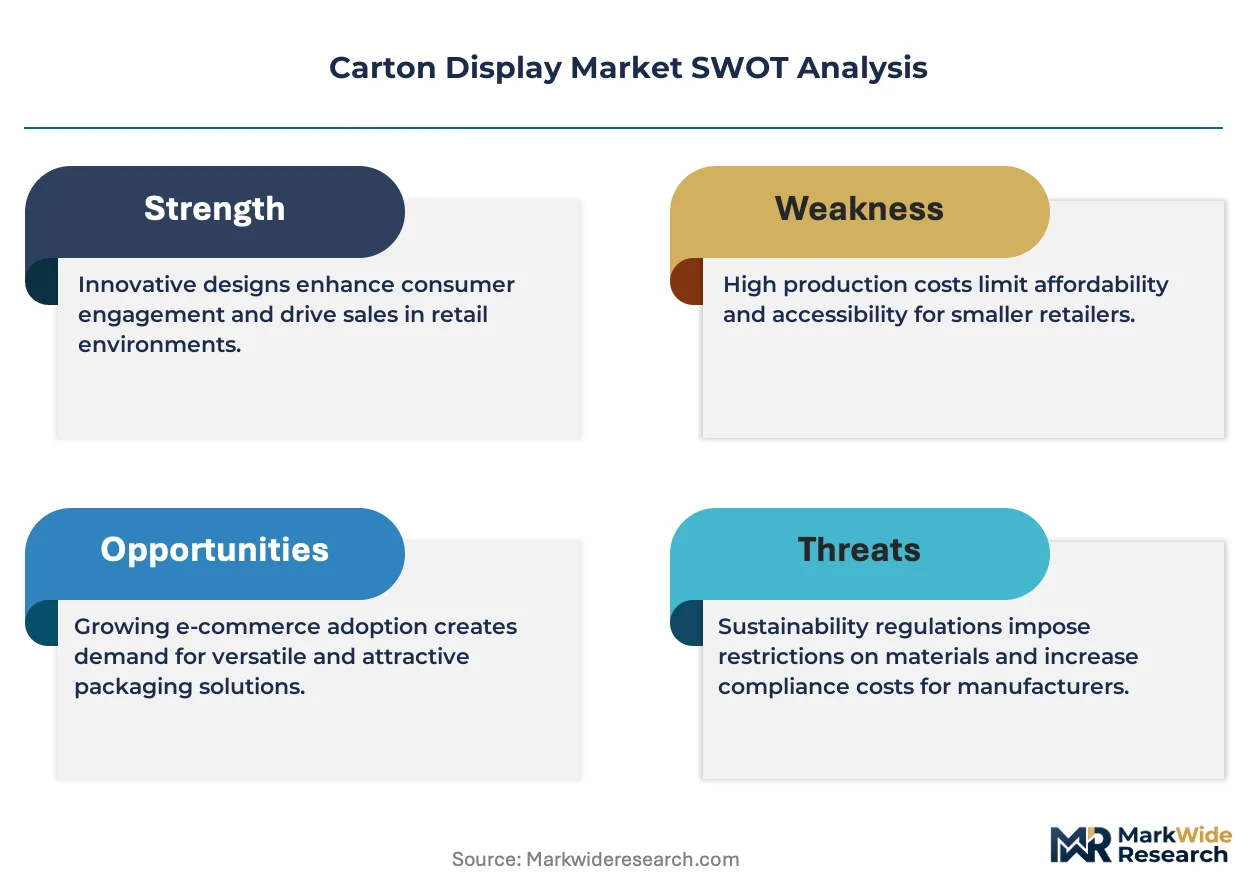
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds are compelling retailers to specify post-consumer fiber displays, creating certified demand pools for compliant converters.
- Seasonal promotion cycles:Mass merchandisers in Germany and France are expanding floor-standing display programs for limited-time product launches, driving volume commitments from board suppliers.
- Water-based flexography:High-speed printing lines are cutting makeready waste by half while enabling photographic-quality graphics on recycled substrates.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import quotas, squeezing margin predictability for recycled board specialists.
- Mill concentration in Scandinavia:Kraftliner supply for premium displays clusters around three Nordic producer groups, creating bottleneck risk during maintenance turnarounds.
- Digital shelf-edge labels:Electronic price displays in electronics retail are displacing printed header cards on some promotional fixtures.
Strategic Opportunities
- Indian modern trade expansion:Reliance Retail and DMart are building automated distribution centers that specify modular carton displays for rapid reconfiguration.
- EPR fee differentials:California's extended producer responsibility structure is penalizing non-recyclable display formats, creating preference pull for fiber-based alternatives.
- Near-field communication integration:NFC chip embedding is converging with QR-enhanced graphics to enable smartphone-triggered augmented reality experiences on shelf.
Industry Challenges
- Structural engineering talent scarcity:Converters lack enough CAD specialists fluent in Esko ArtiosCAD and finite-element analysis for load-bearing pallet displays.
- ISO 14001 certification timelines:Smaller Midwestern US converters face 18-month audit backlogs that lock them out of Walmart and Target supplier pools.
- Legacy ERP integration:Shop-floor data from new die-cutting automation does not feed cleanly into SAP modules, forcing manual reconciliation of job costing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Display Market |
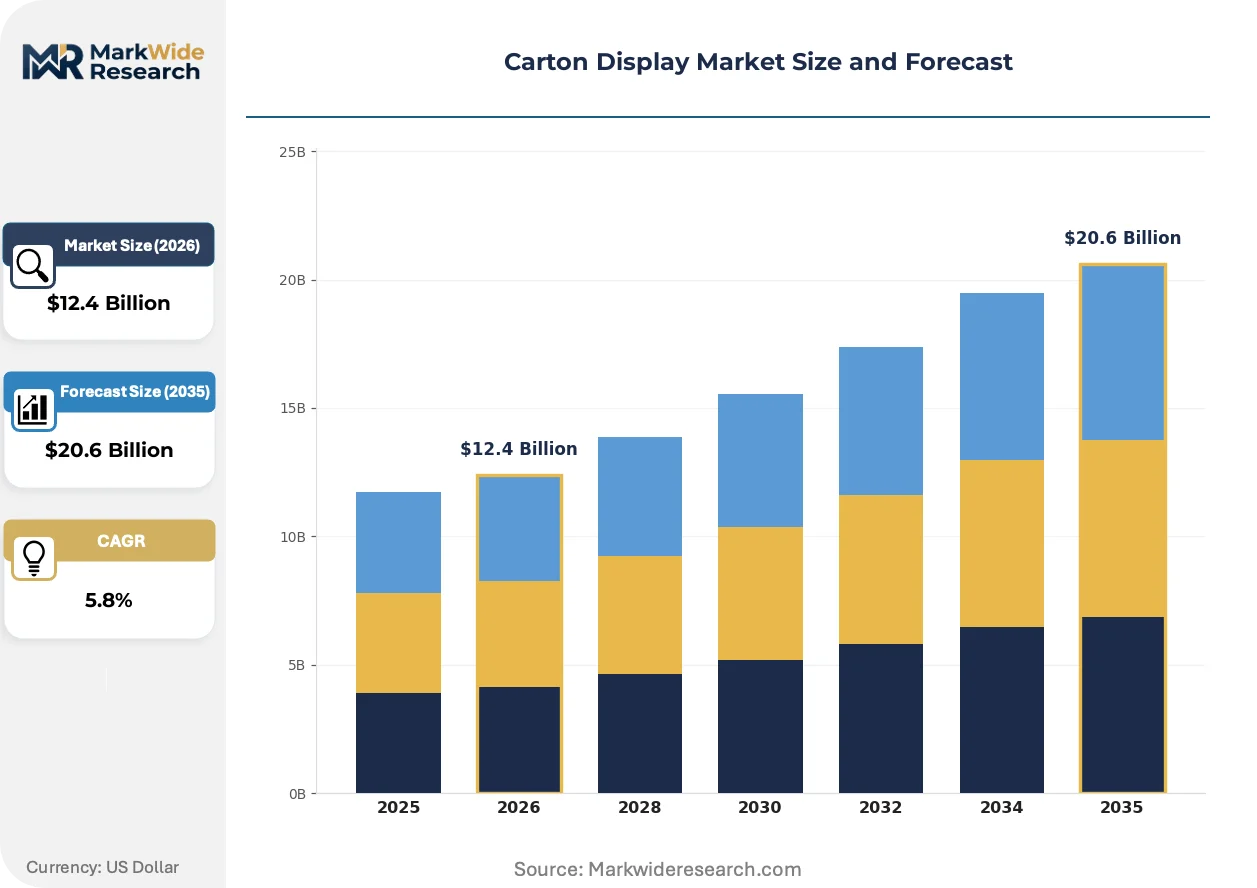
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sidekick Displays, Dump Bins, Pallet Displays, Floor Displays Material: Cardboard, Corrugated Plastic, Foamboard, Recycled Materials End User: Retail Stores, Supermarkets, Trade Shows, E-commerce Design Type: Custom Designs, Standard Designs, Seasonal Displays, Interactive Displays |
| Companies Covered | Smurfit Kappa Group, Sonoco Products Company, WestRock Company, Green Bay Packaging, International Paper Company, Graphic Packaging International, Mayr-Melnhof Karton AG, Pakoro, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Display Market Strategic Shifts
Automation is collapsing the traditional gap between structural design and production execution, enabling same-day prototyping that was previously impossible in corrugated display manufacturing.
Digital die-cutting is digitizing the transition from analog steel-rule tooling to computer-guided knife and crease systems. Mass-market cosmetics brands in Germany are adopting this for micro-batch seasonal launches. The technology is digitizing inventory models by eliminating minimum order quantities tied to physical die investments.
REACH substance restrictions are banning specific flame-retardant coatings previously used in electronics retail displays. Industrial consequence falls heaviest on coated recycled board converters serving big-box CE retailers. Affected suppliers are reformulating with mineral-based alternatives certified under updated EU harmonized standards.
Buying committees at multinational CPG houses are consolidating display procurement under centralized sustainability officers who mandate chain-of-custody documentation. This compresses the supplier base to converters with FSC or SFI certification. The shift is most visible in North American beverage and snack categories where ESG scorecards determine annual vendor rankings.
Carton Display Market Segmentation
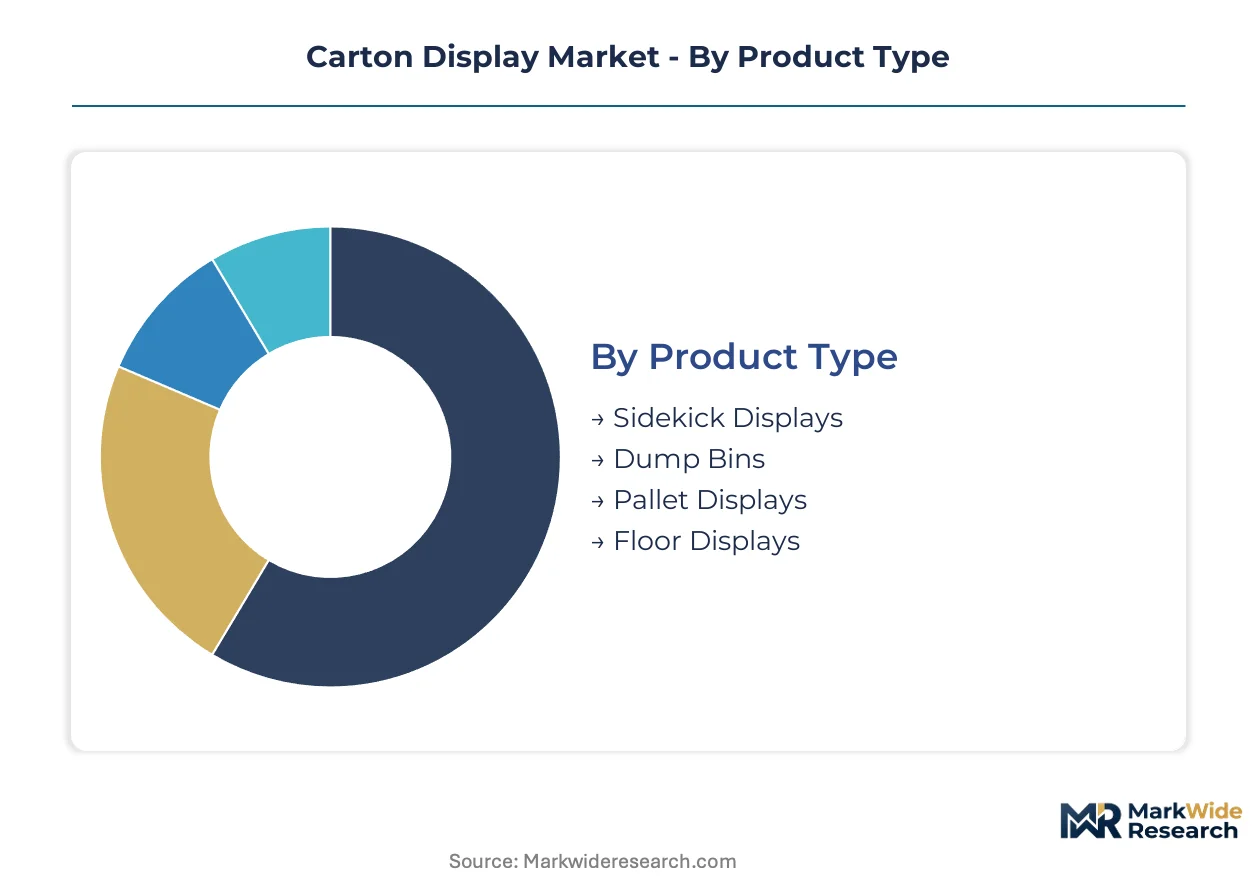
Carton display procurement patterns diverge sharply across structural formats, substrate choices, and retail deployment contexts. Understanding these segment boundaries reveals where converter capabilities align with buyer willingness to pay for speed, sustainability certification, or structural complexity.
Product Type:
After-sales service intensity varies dramatically by display format, with pallet-based units requiring field engineering support for load testing and retail placement guidance while smaller formats ship as disposable consumables.
- Floor Displays:Freestanding units built from double-wall corrugated or rigid paperboard, typically 800-1,200 gsm, engineered for high-traffic aisle ends and seasonal promotional zones. German mass merchandisers and French hypermarkets specify these for limited-time product launches, with demand clustering around Q4 promotional cycles and summer beverage campaigns.
- Pallet Displays:Full-pallet footprint structures integrating base pads, wrap-around graphics, and top-cap signage for warehouse club and big-box formats. Retail density in Germany and sustainability mandates across EU member states push investment here, though structural engineering talent scarcity constrains converter capacity for complex load-bearing designs.
- Sidekick Displays:Narrow vertical fixtures attaching to existing shelving or endcap frames, common in cosmetics and confectionery aisles.
- Dump Bins:Open-top containers for bulk merchandise, prevalent in value retail and clearance events.
By volume, Floor Displays leads. By growth pace, Pallet Displays is ahead.
Material:
Cost tier stratification separates premium virgin fiber displays from economy-grade recycled alternatives, with ESG procurement policies hardening the boundary between compliant and non-compliant supplier pools.
- Recycled Materials:Post-consumer corrugated container (OCC) and mixed paper feedstocks processed into 200-600 gsm board for promotional and seasonal applications. EU Packaging and Packaging Waste Regulation thresholds and California EPR fee structures are pulling demand toward certified chain-of-custody documentation, though OCC price volatility with Chinese import quotas squeezes margin predictability.
- Cardboard:Virgin or semi-bleached kraftliner and testliner grades, 300-800 gsm, specified for premium cosmetic and electronics retail where print fidelity and structural rigidity command price premiums.
- Corrugated Plastic:Polypropylene twin-wall sheet for reusable outdoor and wet-environment displays, common in garden center and hardware retail.
- Foamboard:Polystyrene or PVC-cored rigid panels for lightweight temporary signage and tabletop presentations.
Recycled Materials climbs the fastest as retailer ESG scorecards compress supplier bases to FSC-certified converters.
End User:
Customer type determines order cadence and customization depth, with supermarket buying committees consolidating procurement under centralized sustainability officers while e-commerce fulfillment networks prioritize modularity and damage protection.
- Supermarkets:Automated replenishment systems and RFID-enabled inventory tracking are forcing converters to embed smart tags directly into corrugated structures at factory floors. German retail density and French hypermarket expansion sustain volume commitments for floor-standing and pallet-based seasonal programs.
- Retail Stores:Mass merchandisers and specialty chains balancing promotional impact against labor minimization, with modular designs for rapid reconfiguration gaining preference.
- E-commerce:Ship-ready displays combining protection, presentation, and disposal efficiency for direct-to-consumer unboxing experiences.
- Trade Shows:Lightweight, collapsible formats for temporary exhibition deployment with rapid assembly requirements.
Supermarkets dominate current volume. E-commerce represents the steepest expansion trajectory as fulfillment networks integrate display-ready packaging.
Design Type:
Margin concentration pools in structural differentiation and print fidelity, with brand owners paying premiums for proprietary geometries and photographic-quality graphics that standard templates cannot replicate.
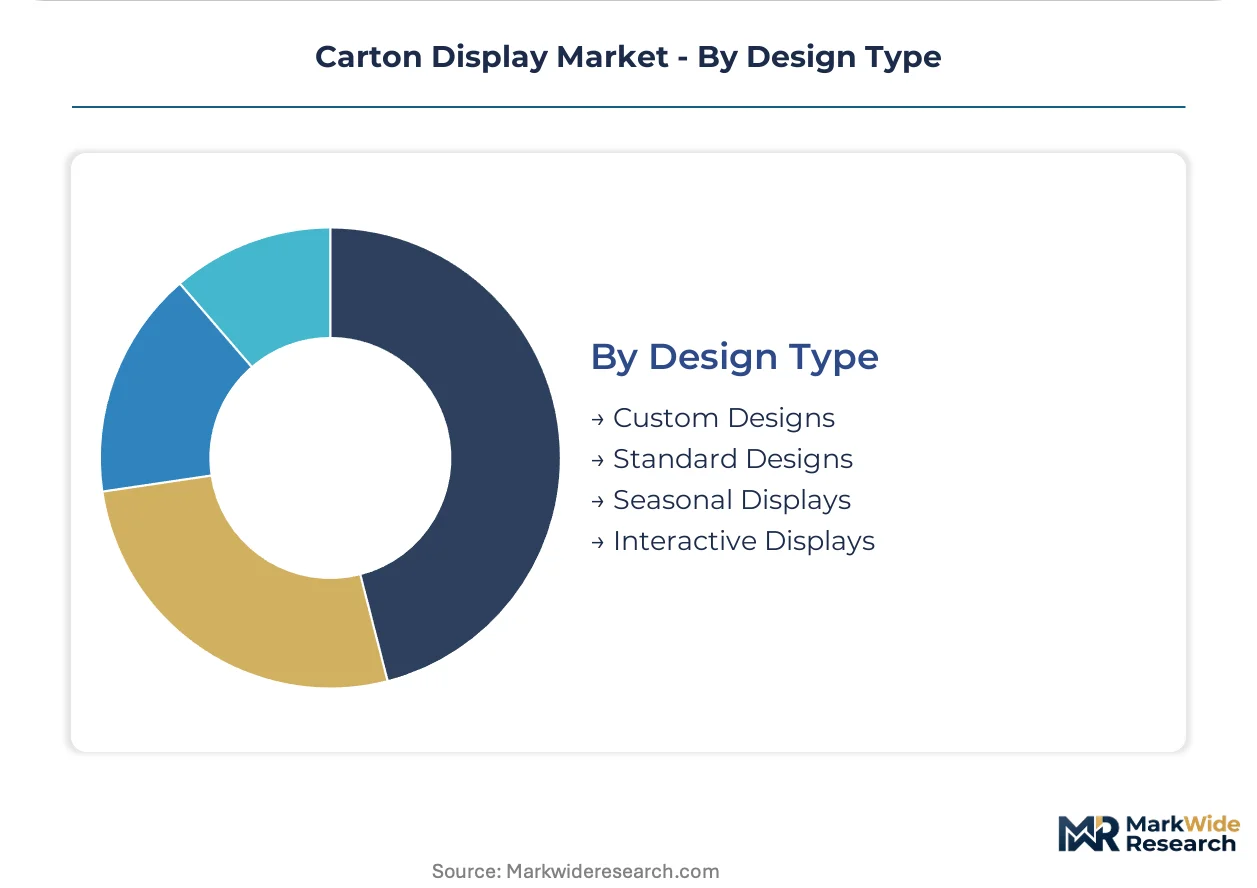
- Custom Designs:Proprietary structural geometries developed in Esko ArtiosCAD or similar platforms, with finite-element analysis for load-bearing applications and high-speed water-based flexography for photographic print quality. Mass-market cosmetics brands in Germany are adopting digital die-cutting for micro-batch seasonal launches, eliminating minimum order quantities tied to physical die investments.
- Interactive Displays:NFC chip embedding converging with QR-enhanced graphics to enable smartphone-triggered augmented reality experiences on shelf.
- Seasonal Displays:Pre-engineered templates for holiday and event-based promotional cycles with faster turnaround times.
- Standard Designs:Catalog formats with minimal customization for cost-sensitive high-volume applications.
Custom Designs captures the largest margin pool. Interactive Displays is gaining share fastest as CPG houses integrate digital engagement into physical retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mill capacity clusters around Nordic producer groups and Great Lakes containerboard corridors, yet demand activation spreads across distinct retail regulatory environments. National packaging waste frameworks and retail density patterns shape where converters invest in certified fiber processing and smart-tag integration.
Germany
Retail density in North Rhine-Westphalia and Bavaria sustains the steepest floor-display procurement rates in Europe. The EU Packaging and Packaging Waste Regulation mandates chain-of-custody documentation that favors FSC-certified converters. Düsseldorf and Munich host buying committees for Rewe and Edeka that consolidate seasonal display programs under centralized sustainability officers.
United States
Walmart and Target supplier pools in Arkansas and Minnesota drive RFID-enabled corrugated structure specifications. California's extended producer responsibility structure penalizes non-recyclable formats, pulling procurement toward fiber-based alternatives. Wisconsin and Michigan mill networks anchor North American kraftliner supply for premium displays.
China
Yangtze River Delta and Pearl River Delta clusters automate die-cutting and gluing lines for domestic brands and export markets alike. The country's dual carbon goals pressure converters toward energy-efficient board production. Shanghai and Shenzhen distribution centers specify modular displays for rapid reconfiguration in expanding modern trade networks.
India
Reliance Retail and DMart automated distribution centers in Maharashtra and Gujarat specify modular carton displays. The Bureau of Indian Standards tightens material traceability for imported board substrates. Mumbai and Ahmedabad converting clusters scale water-based flexography to serve micro-batch seasonal launches.
France
Carrefour and Auchan hypermarket expansion concentrates display demand in Île-de-France and Auvergne-Rhône-Alpes. REACH substance restrictions ban legacy flame-retardant coatings, forcing reformulation with mineral-based alternatives. Lyon and Paris corridors host cosmetics brands adopting digital die-cutting for premium confectionery and beauty displays.
Carton Display Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate and structural engineering niches. The vendor base stratifies between integrated pulp-to-box operators, independent converters with CAD capabilities, and regional specialists in coated recycled board. Three archetypes dominate: mill-integrated giants with captive fiber supply, mid-cap converters with Esko ArtiosCAD design studios, and niche players in premium cosmetic substrates. Competitive moves concentrate on ISO 14001 certification races for retail supplier qualification and digital die-cutting adoption to collapse prototyping cycles.
Among integrated operators, Smurfit Kappa Group and WestRock Company exemplify the mill-captive archetype with fiber supply anchored in European and North American containerboard networks. Mayr-Melnhof Karton AG occupies a specialist position in coated recycled board for premium applications. These three represent distinct competitive vectors: geographic coverage breadth, substrate integration depth, and premium segment focus respectively.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Sonoco Products Company |
| WestRock Company |
| Green Bay Packaging |
| International Paper Company |
| Graphic Packaging International |
| Mayr-Melnhof Karton AG |
| Pakoro |
| Huhtamaki |
| Others |
Value Chain & Pricing Dynamics
OCC price volatility with Chinese import quota fluctuations determines both the spread between certified recycled board and virgin kraftliner tiers and the geographic shape of converter sourcing networks. Buyers facing ESG procurement mandates absorb premium pricing for FSC-certified chain-of-custody documentation while margin compression forces mid-tier converters toward Nordic mill contracts.
Pricing Analysis
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across the carton display market. Three-tier pricing stratifies across premium virgin kraftliner for cosmetic displays, standard semi-bleached grades for mass retail, and economy recycled board for seasonal promotions. Price differentiation centers on certification level—FSC or SFI documentation commands 15-25% premiums over uncertified alternatives. Pricing pressure stems from Old Corrugated Container feedstock cost swings tied to Chinese import policy shifts. Supermarket buying committees show highest price sensitivity in high-volume floor display programs, while premium cosmetic brands demonstrate lowest sensitivity for custom structural designs with photographic print fidelity.
Supply Chain Analysis
Integrated pulp-to-box operators in Sweden, Finland, and Germany hold captive kraftliner capacity for premium display substrates. Raw material dependencies center on Nordic softwood pulp, recycled OCC streams from German retail reverse logistics, and water-based flexographic inks from Netherlands chemical clusters. Supply chain risk concentrates in single-source vulnerability for double-wall corrugated from three Nordic producer groups during maintenance turnarounds. Distribution runs through automated replenishment systems at German and French mass merchandisers, with RFID-enabled inventory tracking embedded at converter factory floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural engineering talent scarcity for load-bearing pallet displays and CAD specialization in Esko ArtiosCAD platforms creates competitive moats for early movers. The gap between design capability and production execution determines which converters capture micro-batch seasonal programs from cosmetics and confectionery brands.
For Market Incumbents: Build certification moats through accelerated ISO 14001 acquisition before Walmart and Target supplier pool deadlines lock out uncertified Midwestern converters. Acquire specialized CAD engineering teams in Germany or France to address structural talent scarcity for complex pallet display load testing. Defend against digital die-cutting disruption by embedding same-day prototyping capabilities that eliminate physical die investment minimums for micro-batch launches. For New Entrants and Emerging Players: Build out modular display capabilities for Indian modern trade expansion, where Reliance Retail and DMart automated distribution centers specify rapid-reconfiguration formats with limited incumbent penetration. Target e-commerce ship-ready display segments combining protection, presentation, and disposal efficiency for direct-to-consumer unboxing experiences. Lead with water-based flexography and digital die-cutting as technical differentiators against legacy analog tooling converters. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap converters with captive design studios and FSC certification already in place. Long-term viability over the next decade hinges on backward integration into recycled fiber processing or downstream control over retail placement services. Watch for inflection signals in California EPR fee structure enforcement that could abruptly penalize non-recyclable display formats and accelerate fiber-based substitution.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14001 Certification Acceleration | Unlocks Walmart and Target supplier pools before audit backlogs extend qualification timelines. |
| Digital Die-Cutting Adoption | Enables same-day prototyping for German cosmetics brands eliminating physical die minimums. |
| NFC Chip Embedding Integration | Converges with QR graphics for smartphone-triggered augmented reality shelf experiences. |
| Modular Display Platform Development | Addresses Reliance Retail and DMart specifications for rapid-reconfiguration Indian distribution. |
| Recycled Fiber Backward Integration | Captures margin from OCC volatility while securing ESG-compliant chain-of-custody documentation. |
Study Parameters
Cross-validation between primary interviews with corrugated converters, retail category buyers, and structural design engineers anchors the qualitative findings against secondary validation from EU regulatory filings, trade association capacity reports, and mill production disclosures. Bottom-up triangulation aggregates converter shipment data by display format and substrate grade, while top-down calibration cross-checks against retail square footage expansion and promotional cycle intensity across German, French, and North American mass merchandisers.
Calibration against historical volume elasticities and promotional spend correlations shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type structural format, material certification tier, end-user channel automation level, and design complexity grade. CAGRs derive from regression against retail modern trade penetration rates and ESG procurement policy adoption curves, with specific inputs from water-based flexography adoption timelines and digital die-cutting capital expenditure cycles.
Sensitivities concentrate around Chinese OCC import quota volatility, Nordic mill maintenance scheduling disruptions, and California EPR fee enforcement timing. Forecasts reflect documented assumptions about regulatory implementation pace and retailer sustainability officer procurement consolidation. Cross-checking against customs trade data for containerboard substrate flows and retail square footage audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Global Cartonboard Market
Cartons
Folding Cartons Market
Cartons
Wax Boxes Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Tetrahedron Carton Market
Cartons
Litho Laminated Cartons Market
Cartons
Soap Boxes Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Global Open Top Cartons Market
Cartons
Mailers Market
Cartons
Brick Carton Packaging Market
Cartons
Digital Folding Cartons Market
Cartons
Carton Bottle Market
Cartons
Global Folding Carton Packaging Market
Cartons
MET-PET Cartons Market