
 Aseptic Carton Packaging Market | 2026-2036
Aseptic Carton Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Carton Packaging Market Analysis
Aftermarket service revenue from filling-line retrofitting and spare-part logistics is rewriting margin allocation across the packaging value chain. Tetra Pak International leverages its installed base of over 5,000 filling machines worldwide to sustain recurring service contracts. SIG Combibloc Group anchors its competitiveness through in-house production of roll-fed carton sleeves, reducing third-party dependency. Greatview Aseptic Packaging specializes in regional dairy supply in Asia, competing on localized technical support and shorter lead times.
Aseptic carton packaging denotes a multi-layer laminated container—typically combining paperboard, polyethylene, and aluminum foil—sterilized separately from the product and sealed in a closed, sterile environment to achieve commercial sterility without refrigeration. The aluminum layer, usually six to seven micrometers thick, provides oxygen and light barriers essential for vitamin retention in sensitive beverages. Beverage Products dominate volume demand due to milk, juice, and plant-based drink proliferation, while Food Products represent the fastest-expanding category as ready-to-eat soup and sauce brands adopt shelf-stable carton formats. Paperboard constitutes the primary material by weight and cost, though aluminum content faces substitution pressure from metallized polymer films designed to meet emerging recyclability protocols.
The EU Green Deal and F-Gas Regulation are tightening requirements on barrier materials and refrigerant use, directly shaping carton laminate specifications and filling-line energy standards. FDA regulations in the United States govern sterility validation and food-contact substance notification, creating compliance thresholds that favor established suppliers with dedicated regulatory affairs teams. China's SAMR and GB standards mandate labeling transparency and material safety testing for imported aseptic packaging, influencing export-oriented manufacturers' product development priorities. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability certification schemes as these will determine market access and premium positioning across major economies.
Market Dynamics
Fiber-based barrier innovation is compressing the aluminum-dependent laminate supply chain as beverage brands accelerate compliance with the EU F-Gas Regulation and emerging extended producer responsibility frameworks.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal and F-Gas Regulation are forcing beverage manufacturers toward fiber-based laminates, expanding retrofit demand for compatible filling equipment across dairy cooperatives.
- Plant-based beverage proliferation:Oat, almond, and soy drink brands are adopting aseptic cartons for ambient distribution, creating sustained volume pull in shelf-stable formats without cold chain dependency.
- Extended-shelf-life dairy:Ultra-high-temperature processing lines in Germany and France are converting to carton compatibility, concentrating capital deployment in Central European dairy processing clusters.
Market Restraints
- Aluminum supply concentration:Six-micrometer foil supply concentrates among a limited supplier base, exposing converters to input volatility and thin-margin pressure during energy price spikes.
- Polyethylene fossil dependency:Sealant layers remain petroleum-derived, creating regulatory friction as France and Germany advance plastic reduction targets under national packaging laws.
- Mechanical recycling incompatibility:Multi-material laminates resist single-stream processing, limiting access to premium recyclability certifications required by major retail chains.
Strategic Opportunities
- Metallized polymer substitution:High-barrier metallized films are penetrating juice and plant-milk segments, enabling aluminum reduction while maintaining oxygen protection for vitamin-fortified products.
- Ready-to-eat food expansion:Soup and sauce brands in Japan and South Korea are piloting shelf-stable carton formats, opening ambient food categories beyond traditional beverage dominance.
- Aftermarket service unbundling:Independent technical service providers are capturing filling-line maintenance contracts from captive supplier networks, fragmenting the post-installation revenue pool.
Industry Challenges
- Sterility validation expertise scarcity:FDA and EFSA compliance pathways require specialized microbiological validation talent that concentrates among legacy equipment suppliers, constraining new market entry.
- Laminate reconfiguration capex:Converting existing lines for fiber-based barrier compatibility demands seven-figure capital commitments, compressing returns for mid-scale dairy processors.
- Recyclability certification fragmentation:Competing national schemes in Germany, France, and Italy create compliance complexity for pan-European brand owners seeking uniform labeling claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Carton Packaging Market |
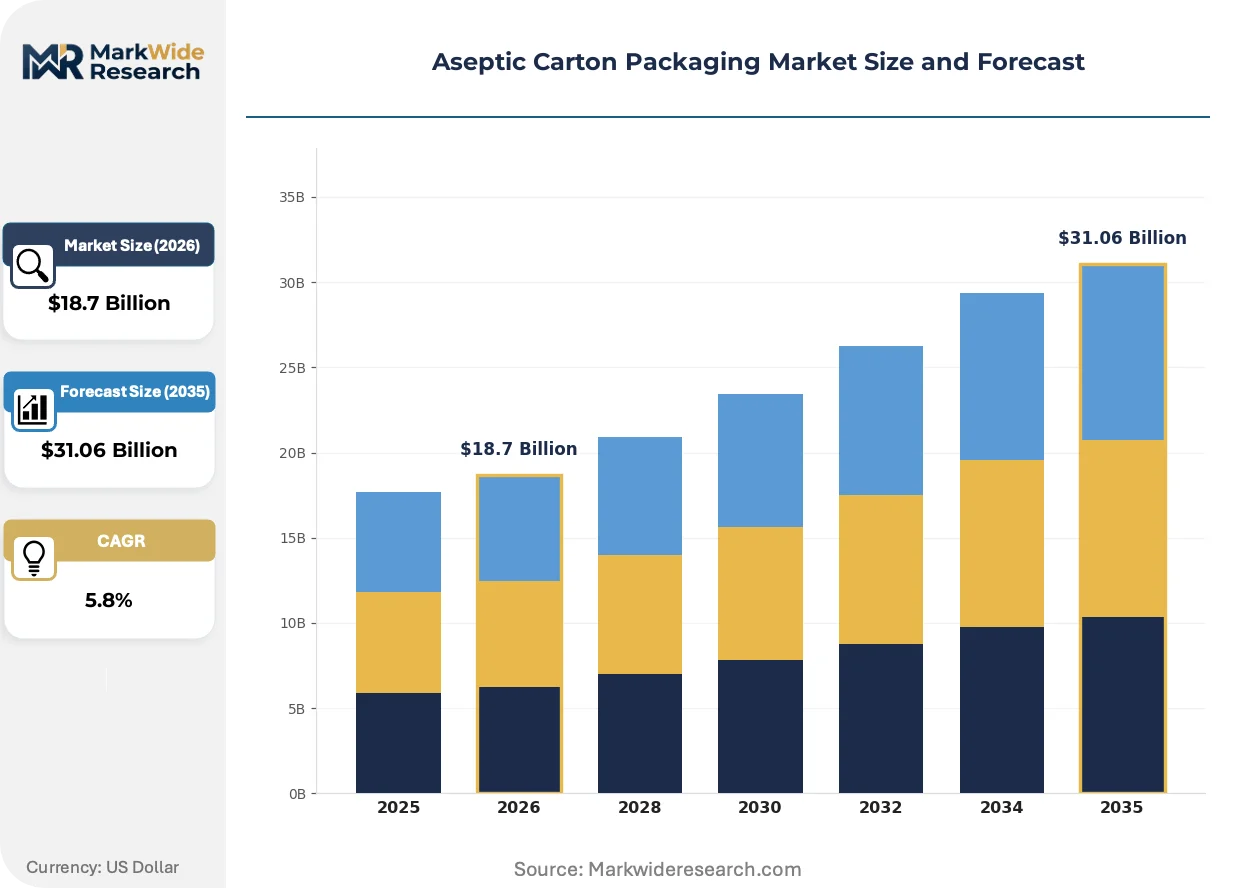
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Products, Dry Products, Food Products, Beverage Products Material: Pulp, Plastic, Aluminum, Paperboard End User: Food Manufacturers, Beverage Companies, Pharmaceutical Firms, Dairy Producers Technology: Forming Machine, Filling Machine, Sealing Machine, Printing Technology |
| Companies Covered | Elopak, Sealed Air Corporation, Tetra Pak International, Huhtamaki Oyj, Berry Global, SIG Combibloc Group, Greatview Aseptic Packaging, International Paper, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Carton Packaging Market Emerging Trajectories
Barrier material science and regulatory chemistry requirements are converging to redefine laminate specifications, while aftermarket service models fragment the traditional equipment-supplier revenue monopoly.
Metallized polyethylene terephthalate films are penetrating oxygen-sensitive beverage applications as a functional replacement for aluminum foil layers. Premium juice and plant-milk brands in Germany and the Netherlands are piloting these barriers at commercial scale. The technology is migrating from niche organic segments toward mainstream private-label adoption, compressing the addressable market for conventional seven-micrometer foil specifications.
REACH chemical authorization and the EU F-Gas Regulation are tightening restrictions on fluorinated compounds and refrigerant gases used in sterilization tunnels. Filling-line energy standards now mandate heat recovery systems and alternative sterilization chemistries. German dairy cooperatives are absorbing compliance costs fastest, retrofitting tunnel designs ahead of French and Italian competitors facing delayed enforcement timelines.
Procurement functions at major beverage groups are unbundling equipment purchase from long-term service contracts, fragmenting supplier lock-in. Technical support and spare-part logistics are migrating toward independent regional providers with shorter response commitments. This pattern concentrates in Central European dairy clusters where cooperative ownership structures favor competitive tendering over single-source relationships.
Aseptic Carton Packaging Market Segmentation
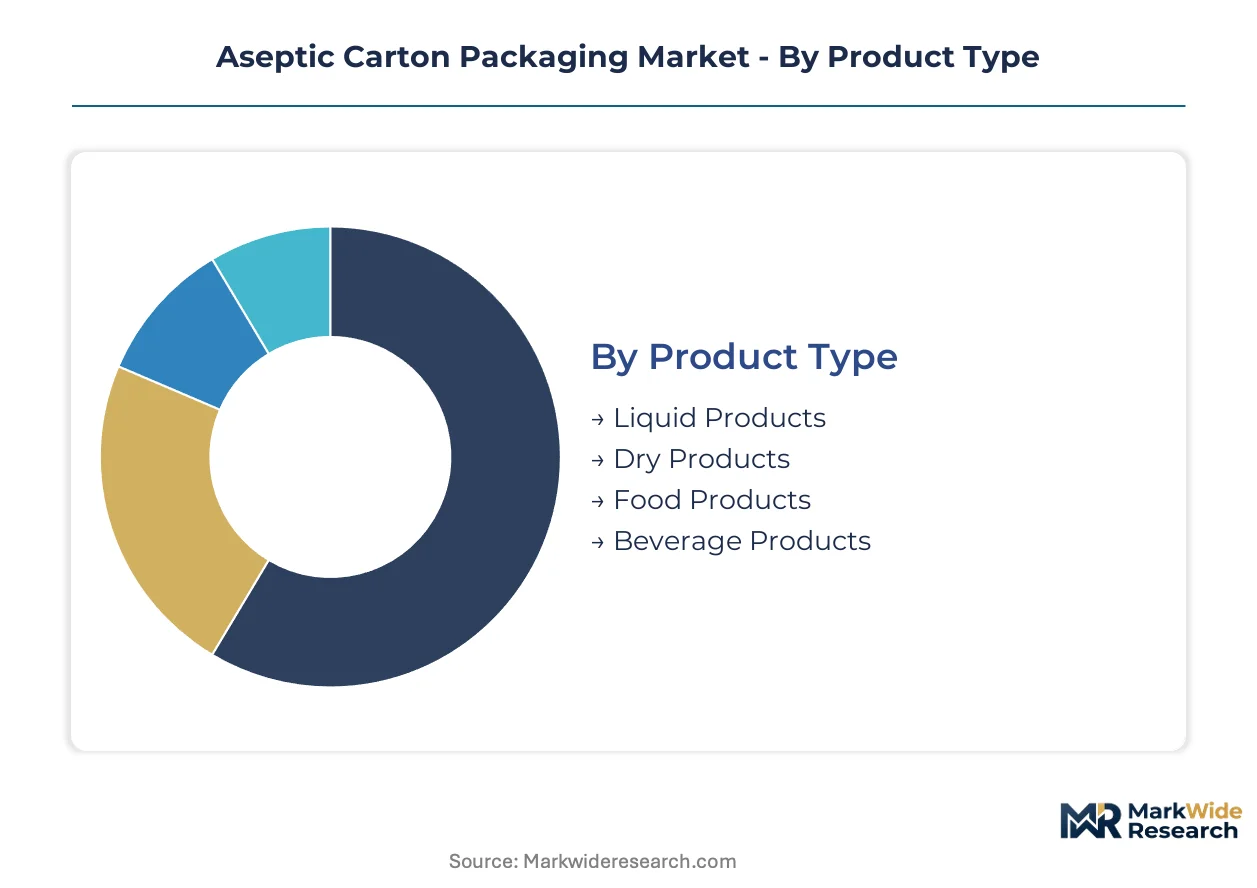
Segmentation in aseptic carton packaging reveals how laminate specifications and filling-line configurations align with distinct sterility requirements, shelf-life targets, and regulatory compliance burdens across end-use categories.
Product Type:
Application context determines barrier complexity and sterilization protocol intensity across liquid, dry, and prepared food formats.
- Beverage Products:Multi-layer laminates with aluminum oxygen barriers dominate milk, juice, and plant-based drinks. German dairy cooperatives and Dutch oat-milk brands drive volume concentration in ambient distribution formats.
- Food Products:Ready-to-eat soups and sauces require higher-temperature sterilization cycles and thicker paperboard walls. Japanese and South Korean brands are piloting shelf-stable carton formats for miso and curry bases, expanding beyond traditional beverage dominance.
- Liquid Products:UHT-processed dairy and non-dairy alternatives constitute the core volume base for standard filling-line configurations.
- Dry Products:Powdered nutrition and infant formula demand modified atmosphere sealing with desiccant integration, commanding premium laminate specifications.
Beverage Products command the established base. The steepest expansion runs through Food Products.
Material:
Cost tier and recyclability pressure are reweighting the traditional paperboard-polyethylene-aluminum stack toward fiber-heavy and aluminum-light alternatives.
- Paperboard:Constitutes 70-75% of laminate weight and cost, sourced from FSC-certified pulp. German and French converters face mounting pressure to increase recycled fiber content under national packaging laws.
- Aluminum:Six-to-seven-micrometer foil layers provide oxygen and light barriers essential for vitamin retention. Supply concentrates among a limited supplier base, exposing converters to energy-price volatility.
- Plastic:Polyethylene sealant layers remain petroleum-derived, creating regulatory friction as France advances plastic reduction targets.
- Pulp:Molded fiber barriers are emerging as aluminum replacements in organic juice segments, though oxygen transmission rates lag metallized alternatives.
Paperboard commands the established base. The steepest expansion runs through Pulp.
End User:
Customer type dictates procurement scale, technical service expectations, and captive versus outsourced filling-line ownership models.
- Beverage Companies:Global brand owners and private-label producers unbundle equipment purchase from long-term service contracts. Central European dairy clusters favor competitive tendering for maintenance over single-source relationships.
- Dairy Producers:Cooperative ownership structures in Germany and France concentrate retrofit investment for extended-shelf-life UHT lines, prioritizing localized technical support.
- Food Manufacturers:Soup and sauce brands in Japan pilot shelf-stable formats, requiring modified filling-line sterilization tunnels.
- Pharmaceutical Firms:Enteral nutrition and liquid medication applications demand FDA-validated sterility protocols with dedicated regulatory affairs documentation.
Beverage Companies command the established base. The steepest expansion runs through Food Manufacturers.
Technology:
Margin concentration and aftermarket revenue potential vary sharply across equipment categories, with service unbundling reshaping traditional supplier lock-in.
- Filling Machine:Over 5,000 installed units worldwide generate recurring service contracts and spare-part logistics revenue. Independent technical providers are capturing maintenance contracts from captive supplier networks.
- Forming Machine:Roll-fed sleeve production determines material efficiency and format flexibility. In-house production capabilities reduce third-party dependency for major converters.
- Sealing Machine:Ultrasonic and induction sealing technologies face reconfiguration demands for fiber-based barrier compatibility.
- Printing Technology:Digital and flexographic systems enable lot-level traceability and variable data printing for EU labeling transparency mandates.
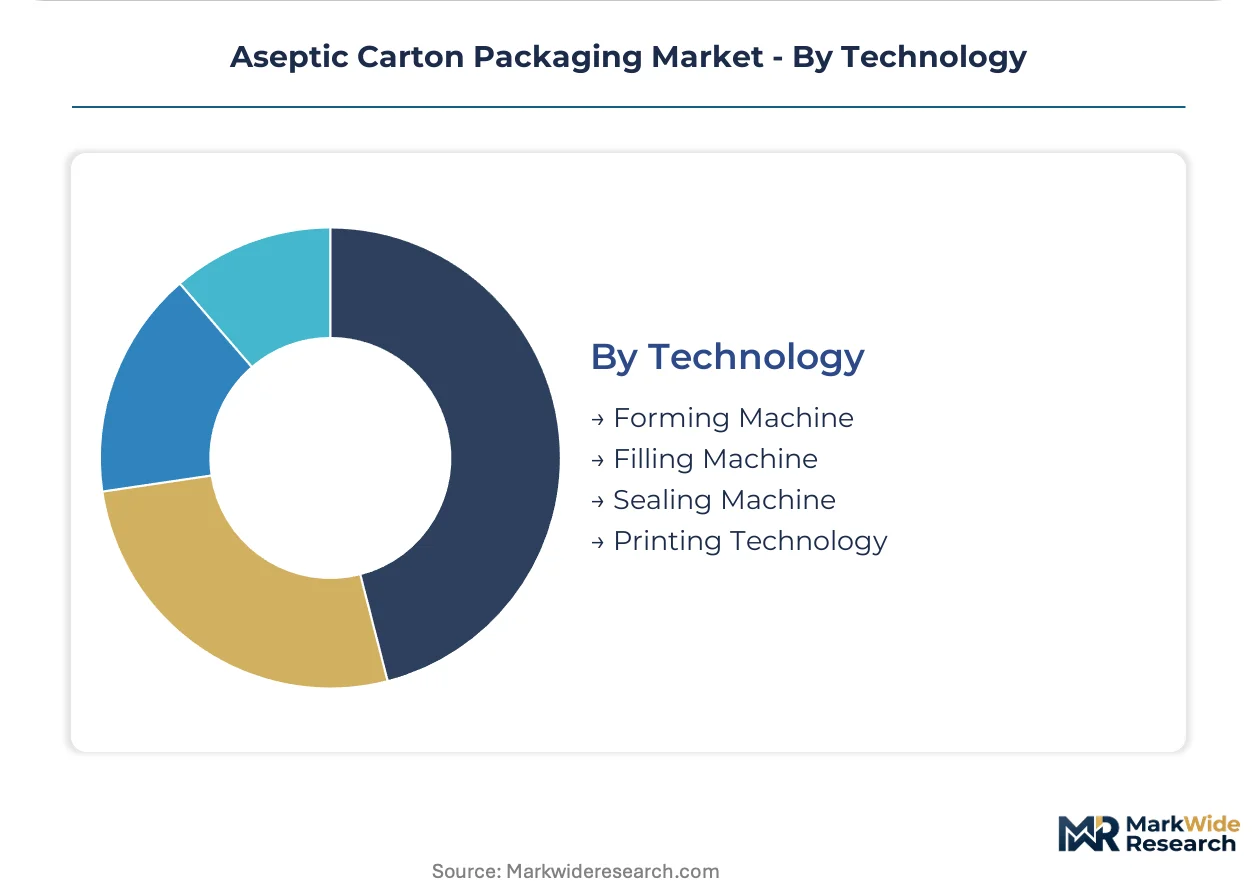
Filling Machine commands the established base. The steepest expansion runs through Forming Machine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity concentrates in Germany, China, and the United States, where dairy cooperatives and beverage multinationals anchor retrofit demand for fiber-compatible filling lines. Regulatory divergence across these markets fragments laminate specifications and compliance timelines.
Germany
Dairy cooperatives in Bavaria and Lower Saxony drive UHT line conversions for extended-shelf-life milk and oat-drink formats. The EU F-Gas Regulation and national packaging laws under the EU Green Deal mandate heat recovery systems and fiber-heavy barrier materials. The Baden-Württemberg processing cluster absorbs seven-figure capital commitments for laminate reconfiguration faster than French or Italian counterparts.
China
Domestic oat-milk brands and imported infant formula producers expand ambient carton adoption for tier-one city distribution. SAMR labeling transparency mandates and GB material safety standards shape export-oriented manufacturers' product development. The Yangtze River Delta converter base shortens lead times for regional dairy supply chains competing with multinational suppliers.
United States
Plant-based beverage startups and private-label juice brands unbundle equipment purchase from long-term service contracts. FDA sterility validation and food-contact substance notification requirements favor established suppliers with dedicated regulatory affairs teams. The Upper Midwest dairy processing corridor concentrates retrofit investment for carton-compatible UHT lines.
Japan
Soup and sauce manufacturers pilot shelf-stable carton formats for miso and curry bases, expanding beyond traditional beverage applications. METI energy standards and JIS packaging specifications influence sterilization tunnel designs. The Kansai industrial belt hosts pilot programs for ready-to-eat food cartons with modified atmosphere sealing.
Netherlands
Oat-milk brands and organic juice labels pilot metallized polymer barriers as aluminum replacements. REACH chemical authorization tightens restrictions on fluorinated compounds in sterilization processes. The Randstad converter cluster supplies laminate materials to German and Belgian dairy processors facing accelerated compliance timelines.
Aseptic Carton Packaging Market Vendor Landscape
Integrated system suppliers and specialized material converters split the market into distinct capability tiers. Consolidation concentrates among legacy equipment manufacturers with installed bases exceeding 5,000 filling machines worldwide, while mid-scale converters compete on regional technical support and shorter lead times. Three archetypes dominate: full-system integrators controlling equipment and materials, roll-fed sleeve specialists with in-house production capabilities, and independent service providers capturing unbundled maintenance contracts. Competitive moves center on laminate reconfiguration partnerships and aftermarket service unbundling.
Within the full-system tier, Tetra Pak International and SIG Combibloc Group anchor competitive positioning through captive equipment networks and recurring service revenue streams. Greatview Aseptic Packaging occupies a position among regional specialists competing on localized technical support in Asian dairy supply chains. These three exemplify how strategic archetypes align with geographic coverage and vertical scope rather than product differentiation alone.
| Leading Market Players |
|---|
| Elopak |
| Sealed Air Corporation |
| Tetra Pak International |
| Huhtamaki Oyj |
| Berry Global |
| SIG Combibloc Group |
| Greatview Aseptic Packaging |
| International Paper |
| Amcor |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta converter cluster anchors global laminate capacity, concentrating supply-side leverage among roll-fed sleeve producers who dictate terms to downstream dairy processors retrofitting for fiber-compatible barriers. This geographic concentration amplifies pricing power for aluminum foil and metallized film suppliers while compressing margins for mid-scale filling-line operators.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European markets, forcing laminate reconfiguration costs into buyer contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical-grade specifications from private-label beverage formats and commodity dairy cartons. Cost compression in the standard tier is intensifying because polyethylene sealant layers remain petroleum-derived under France's advancing plastic reduction targets. Beverage companies exhibit highest price sensitivity due to unbundled procurement, while pharmaceutical firms accept premium positioning for sterility validation documentation.
Supply Chain Analysis
Extended payment terms from German dairy cooperatives are reshaping working capital requirements for converter operations across Central Europe. Raw material sourcing draws from Swedish FSC-certified pulp mills, Chinese metallized film producers, and Saudi petrochemical complexes for polyethylene feedstock. Single-source vulnerability concentrates in six-micrometer aluminum foil supply where energy-price volatility transmits directly to laminate converters. Distribution runs through captive supplier networks for full-system integrators and independent regional logistics providers for aftermarket service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. Switching costs for filling-line reconfiguration and FDA sterility validation create durable barriers against new entrant displacement.
For Market Incumbents: Pre-empt metallized polymer substitution by accelerating laminate reconfiguration partnerships with Dutch and German oat-milk brands before fiber-based barriers achieve cost parity. Backward integration into roll-fed sleeve production reduces third-party dependency while independent technical service providers threaten aftermarket revenue capture. Prioritize certification investment for EU Green Deal compliance ahead of delayed French and Italian enforcement timelines. For New Entrants and Emerging Players: Regional dairy supply chains in Southeast Asia represent the most penetrable entry point, where localized technical support and shorter lead times offset installed-base disadvantages against Tetra Pak and SIG Combibloc. Food manufacturers in Japan piloting shelf-stable soup and sauce formats offer white-space expansion beyond beverage dominance. A service-first go-to-market angle unbundling maintenance contracts from equipment sales aligns with cooperative procurement preferences in Central European dairy clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-system integrators with installed bases exceeding 5,000 filling machines worldwide. Long-term viability over a multi-year horizon favors acquisition targets with captive regulatory affairs teams navigating FDA and EFSA compliance pathways. Watch for inflection signals in metallized polymer barrier adoption rates as aluminum substitution thresholds determine laminate reconfiguration capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Roll-Fed Sleeve Production | SIG Combibloc's in-house manufacturing model reduces material cost volatility for European dairy processors. |
| Laminate Reconfiguration Partnership | Metallized PET film adoption by Dutch oat-milk brands compresses conventional aluminum foil addressable markets. |
| Aftermarket Service Unbundling | Independent technical providers capture maintenance contracts from captive networks in Bavarian cooperative structures. |
| Regulatory Pre-Certification Investment | FDA sterility validation expertise scarcity concentrates among legacy suppliers, constraining new market entry. |
| Geographic Capacity Expansion | Yangtze River Delta converter investments shorten lead times for Chinese domestic oat-milk distribution. |
Methodological Framework
Operator-level perspectives from filling-line engineers, dairy cooperative procurement directors, laminate converter plant managers, and aftermarket service technicians anchored the qualitative base for this study. Primary interviews combined with secondary validation from customs records, FSC certification databases, FDA food-contact substance notifications, and EU F-Gas Regulation compliance filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed the analytical approach, modeling volume and value outputs across product type, material composition, end-user archetype, and technology configuration dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory compliance timeline acceleration in Germany versus delayed enforcement in France and Italy. Forecast inputs incorporated filling-line retrofitting capex cycles and metallized polymer barrier penetration assumptions.
Practitioners should monitor laminate reconfiguration cost curves and extended producer responsibility framework implementation for early signals of competitive repositioning. Forecasts reflect documented assumptions regarding fiber-based barrier oxygen transmission rate improvements and aluminum foil supply concentration stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Plastic Retort Cans Market