
 Global Cartonboard Market | 2026-2036
Global Cartonboard Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cartonboard Market Foresight
Food and beverage packaging is repositioning cartonboard specifications toward grease-resistant and barrier-coated grades. Mayr-Melnhof Karton AG leverages vertical integration across European pulp supply to secure coated board capacity. Graphic Packaging Holding Company anchors North American beverage carton demand through in-house extrusion and printing assets. Smurfit WestRock competes on recycled fiber scale, operating containerboard-to-cartonboard conversion networks across multiple continents.
Cartonboard denotes a paper-based packaging material typically manufactured in grammages between 200 and 500 gsm, composed of bleached or unbleached chemical pulp layers with optional mineral pigment coatings for printability. Its primary commercial purpose is to form rigid or semi-rigid containers that protect consumer goods while providing high-quality printable surfaces for brand communication. Folding Boxboard dominates value generation due to its superior stiffness-to-weight ratio and compatibility with offset lithography, though Recycled Board is gaining structural share as brand owners impose post-consumer content minimums. Solid Bleached Sulphate retains premium positioning in pharmaceutical and cosmetic applications where sterility assurance and visual clarity command margin premiums.
The EPA enforces recycled fiber content thresholds under Comprehensive Procurement Guidelines, while REACH and the EU Green Deal impose substance restrictions and carbon intensity disclosures on imported board. FDA food contact regulations and EFSA migration limits dictate barrier coating chemistries permitted for direct food applications. Stakeholders must monitor evolving extended producer responsibility schemes across multiple jurisdictions to anticipate pass-through cost structures and compliance-driven specification changes.
Market Dynamics
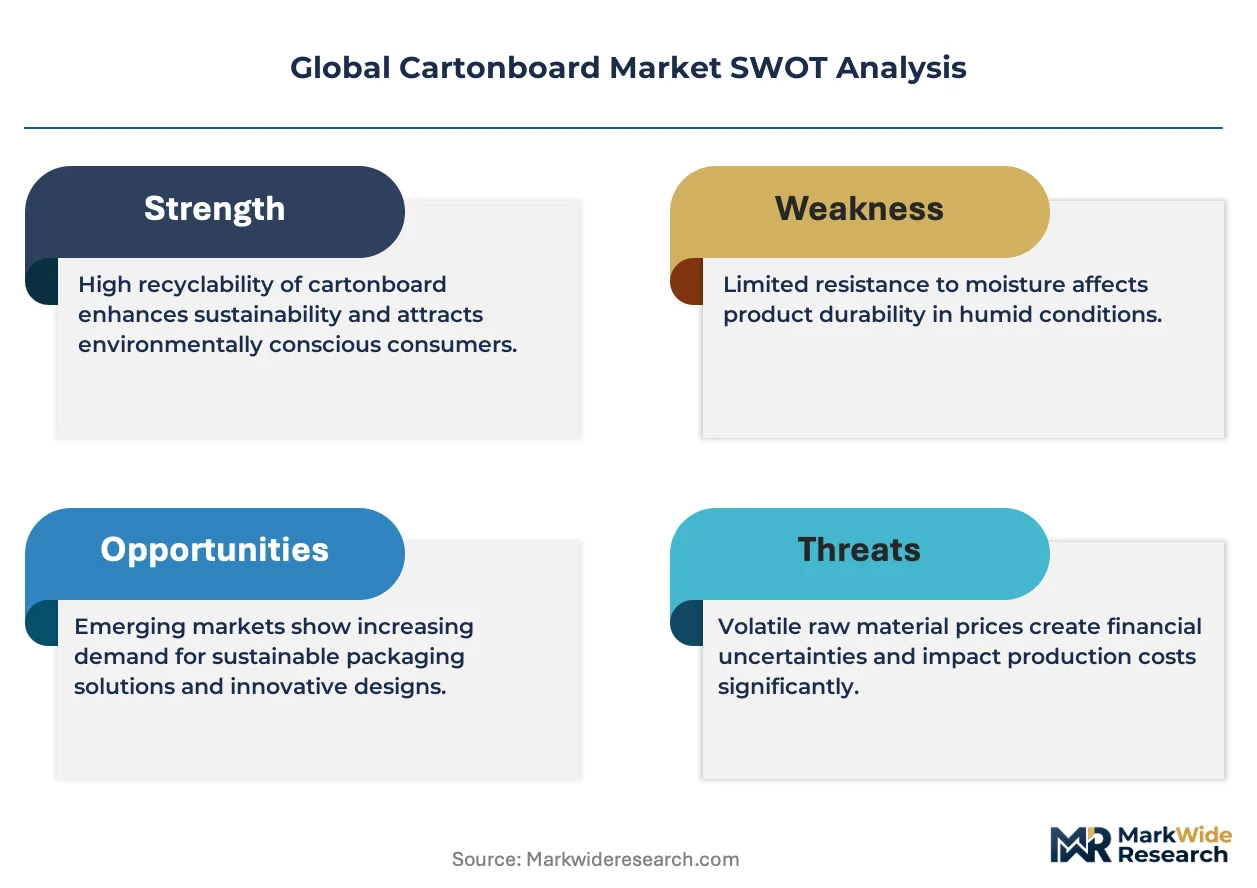
The EU Green Deal and F-Gas Regulation are compressing allowable coating chemistries while brand owners simultaneously impose post-consumer recycled fiber minimums, creating specification tension across European converting operations.
Growth Catalysts
- REACH substance restrictions:European regulators are accelerating substitution of fluorinated barrier coatings with bio-based alternatives, opening capacity for compliant producers.
- Pharmaceutical cold-chain expansion:Folding boxboard demand from vaccine and biologics logistics is tightening sterility-grade Solid Bleached Sulphate supply in Germany and Switzerland.
- Mineral pigment coating advances:Kaolin and calcium carbonate formulations are improving printability at lower grammages, reducing fiber input per unit.
Market Restraints
- Bleached hardwood pulp concentration:Nordic and Brazilian suppliers control over half of global chemical pulp for premium grades, exposing converters to freight and currency volatility.
- Recycled fiber quality degradation:Post-consumer collection streams in North America and Europe contain rising contamination levels, increasing reject rates at recycled board mills.
- Plastic flexible substitution in fresh produce:Polypropylene and PET trays retain cost and moisture-barrier advantages for berries and leafy greens, limiting cartonboard penetration.
Strategic Opportunities
- India FSSAI food contact mandates:The country's national food safety regulator is tightening migration limits, creating first-mover advantage for barrier-coated board with existing EFSA compliance documentation.
- Direct-to-consumer e-commerce packaging:Subscription food boxes and meal kits are specifying printed folding cartons over corrugated for unboxing experience differentiation.
- Carbon border adjustment mechanisms:The EU's emerging CBAM on imported goods is incentivizing regional producers to certify low-carbon intensity board for export-bound customer goods.
Industry Challenges
- Barrier coating reformulation timelines:FDA and EFSA migration studies for novel bio-based chemistries require 18-36 month approval cycles, delaying product launches.
- Multi-site certification complexity:FSC and PEFC chain-of-custody audits across integrated pulp-to-board operations demand specialized audit coordination across three or more facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cartonboard Market |
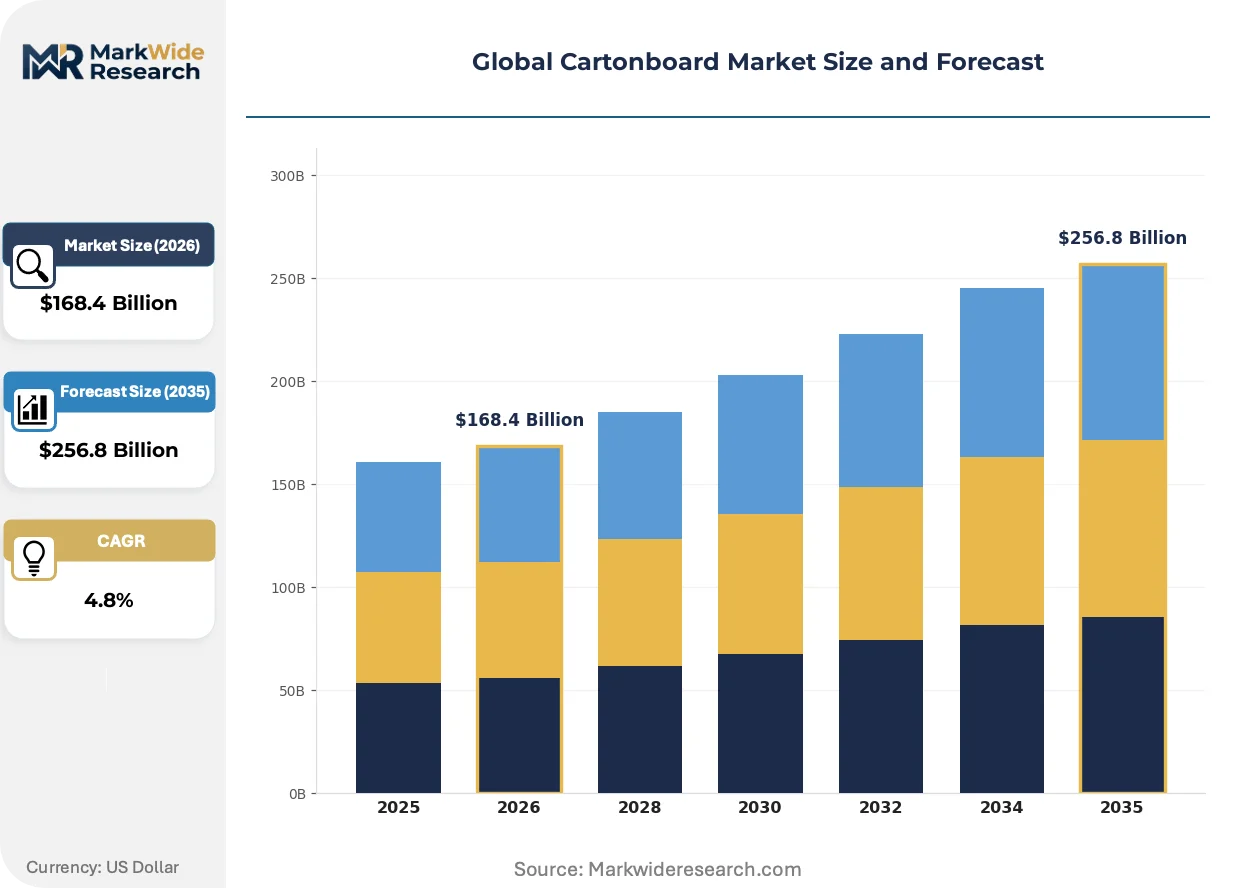
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $256.8 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Boxboard, Solid Bleached Sulphate, Solid Unbleached Sulphate, Recycled Board Application: Pharmaceutical Packaging, Cosmetic Packaging, Food & Beverage Packaging, Consumer Goods Packaging End User: Contract Packaging Providers, Brand Owners, Exclusive Distributors, Retailers Packaging Type: Rigid Boxes, Cartons, Sleeves, Trays, Wraps |
| Companies Covered | Mayr-Melnhof Karton AG (MM Group), Graphic Packaging Holding Company, Nine Dragons Paper (Holdings) Limited, Asia Pulp and Paper Company Ltd., Smurfit WestRock, Stora Enso Oyj, International Paper Company, Metsa Board, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cartonboard Market Shifts & Advancements
Water-based and extruded polymer barrier technologies are displacing conventional polyethylene laminates, while digital printing integration is compressing minimum order quantities and shortening design-to-shelf cycles.
Extruded polyethylene terephthalate glycol (PETG) barrier layers are overtaking conventional extruded polyethylene for high-temperature food contact applications. Ready-meal and bakery brands in France and Italy are specifying PETG-coated folding boxboard for microwaveable trays. The shift is overtaking legacy polyethylene specifications in premium chilled food segments where thermal resistance commands price premiums.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in extrusion processes, forcing converters to adopt carbon dioxide or hydrocarbon-based foam extrusion for insulated packaging. German folding carton producers are retrofitting extrusion lines to comply with 2027 phase-down targets. Pharmaceutical and chocolate confectionery segments are absorbing capital pass-through costs while awaiting scale economies from shared toll-coating infrastructure.
Brand-owner consolidation in personal care and cosmetics is compressing supplier bases and demanding vendor-managed inventory programs. L'Oréal and Unilever procurement teams are mandating quarterly volume commitments with penalty clauses for specification non-compliance. French and German converters are responding with dedicated line capacity and real-time inventory telemetry to defend supplier status.
Global Cartonboard Market Segmentation
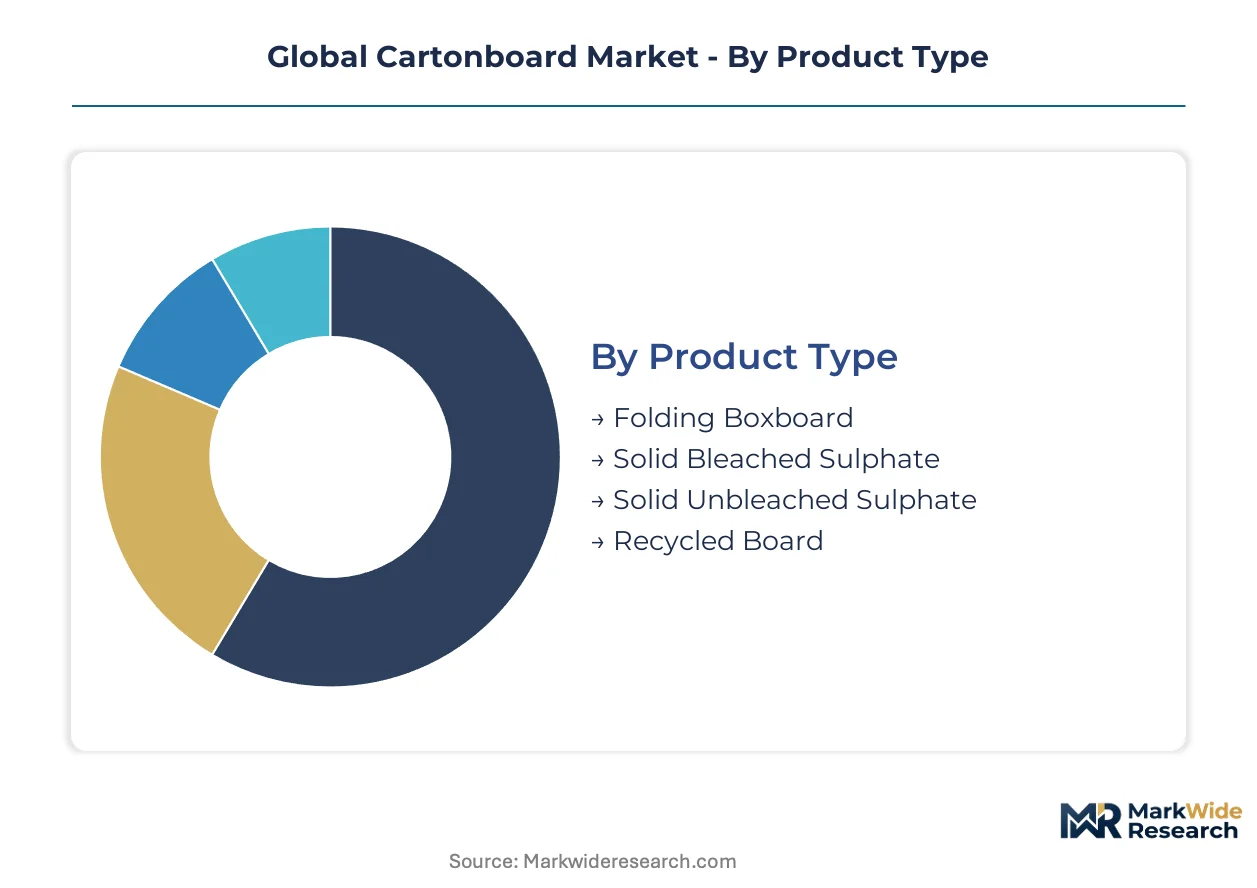
Cartonboard segmentation reflects divergent certification burdens across pharmaceutical sterility standards, food contact migration limits, and cosmetic visual clarity requirements. Specification choices cascade through coating chemistry, fiber sourcing, and grammage selection.
Product Type:
FDA food contact notification and EFSA migration compliance requirements vary sharply across these grades, with pharmaceutical applications demanding the most stringent sterility documentation.
- Folding Boxboard:Multi-ply construction combines mechanical pulp center layers with bleached chemical pulp outer plies, delivering optimal stiffness-to-weight ratios for high-speed converting. Demand concentrates in German pharmaceutical exports and French ready-meal segments where EFSA-compliant barrier coatings command specification priority.
- Solid Bleached Sulphate:Pure bleached chemical pulp construction provides superior visual clarity and sterility assurance for sensitive applications. Swiss and German vaccine logistics networks are tightening supply for cold-chain folding cartons as biologics distribution expands.
- Solid Unbleached Sulphate:Unbleached kraft pulp retains natural fiber coloration, suited for organic food positioning and lower-cost industrial packaging.
- Recycled Board:Post-consumer fiber content meets EPA Comprehensive Procurement Guidelines and emerging EU Green Deal recycled content mandates.
Leading the category by volume: Folding Boxboard. Growing fastest: Recycled Board.
Application:
End-use concentration determines margin tier and regulatory exposure, with pharmaceutical and food segments carrying the heaviest compliance documentation.
- Pharmaceutical Packaging:Sterility-grade Solid Bleached Sulphate dominates vaccine and biologics cartons. German folding carton producers are retrofitting lines to meet Swissmedic and EMA serialization requirements.
- Food & Beverage Packaging:Grease-resistant and barrier-coated grades are displacing legacy specifications. French and Italian microwaveable ready-meal brands specify PETG-coated folding boxboard for thermal resistance.
- Cosmetic Packaging:Premium visual clarity and embossing compatibility support luxury positioning. L'Oréal procurement mandates quarterly volume commitments with penalty clauses.
- Consumer Goods Packaging:Electronics and home care applications prioritize cost efficiency over barrier performance.
Highest margin concentration: Pharmaceutical Packaging. Steepest expansion trajectory: Food & Beverage Packaging.
End User:
Customer type shapes procurement scale, inventory risk allocation, and specification control.
- Brand Owners:Direct specification authority enables post-consumer recycled fiber minimums and vendor-managed inventory programs. Unilever and similar consolidators compress supplier bases while demanding real-time inventory telemetry.
- Contract Packaging Providers:Toll-manufacturing relationships require multi-site FSC and PEFC chain-of-custody certification across integrated operations.
- Exclusive Distributors:Regional stocking positions buffer converters against currency and freight volatility from Nordic and Brazilian pulp suppliers.
- Retailers:Private-label specifications follow corporate sustainability commitments with varying recycled content thresholds.
Greatest pricing leverage: Brand Owners. Fastest channel growth: Contract Packaging Providers.
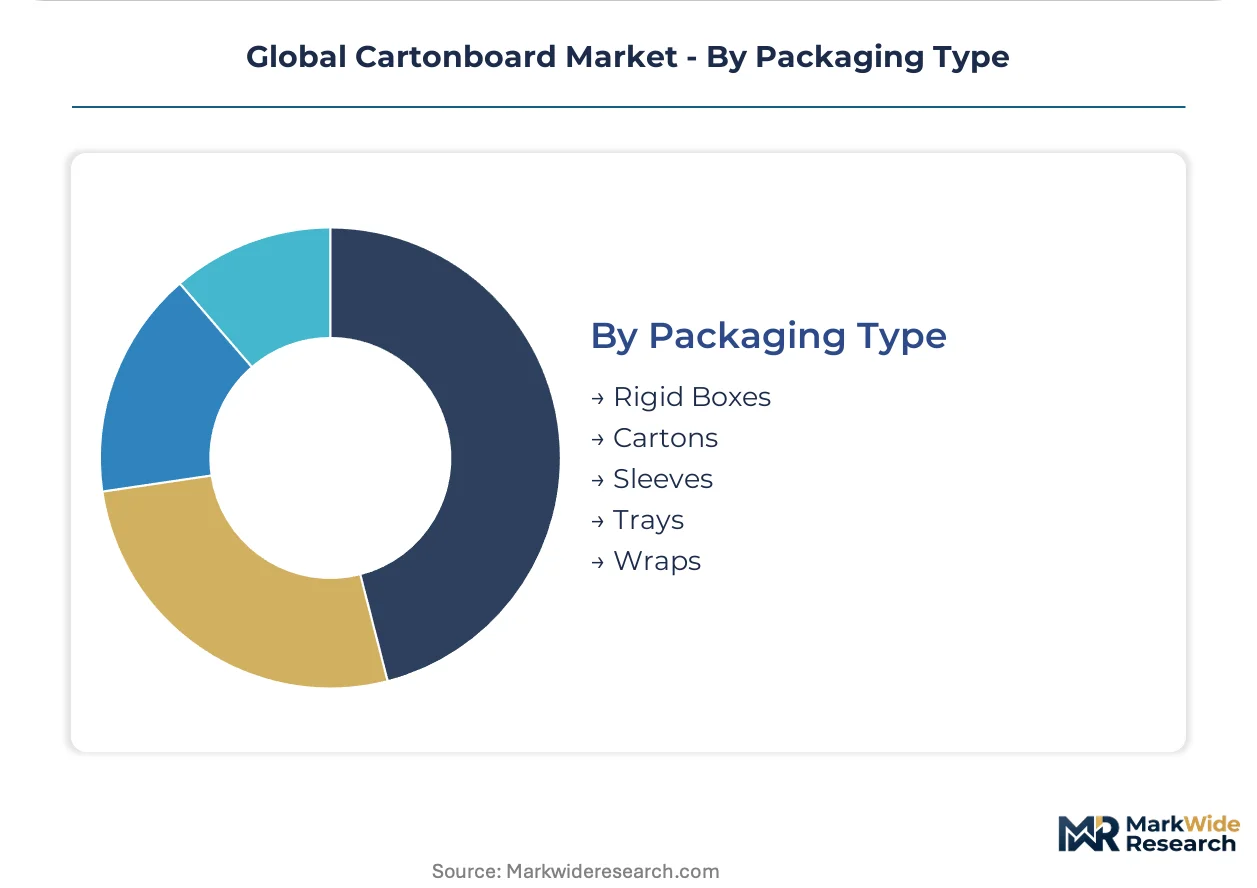
Packaging Type:
Structural format selection drives converting equipment investment and barrier coating application methods.
- Cartons:Standard folding carton formats dominate pharmaceutical and food segments, compatible with offset lithography and digital printing integration.
- Trays:Rigid structural requirements for ready-meal and bakery applications favor higher-grammage folding boxboard with extruded PETG barriers.
- Rigid Boxes:Premium cosmetic and gift applications require manual or semi-automatic assembly, limiting scale economies.
- Sleeves:Banding and multi-pack applications reduce fiber input but require precise die-cutting tolerance.
- Wraps:Lowest-grammage applications for secondary protection and retail-ready display.
Dominant volume format: Cartons. Gaining structural share: Trays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European converting operations consume more cartonboard than regional mills produce, drawing imports from Nordic and Brazilian suppliers. Asian capacity expansion is outpacing domestic demand growth, creating exportable surplus. North American demand concentrates in beverage and pharmaceutical applications with stringent FDA compliance requirements.
Germany
Folding boxboard consumption for pharmaceutical exports drives demand concentration in Baden-Württemberg and Bavaria. The EU Green Deal imposes carbon intensity disclosures on imported board, favoring regional producers with certified low-carbon processes. The Rhine-Main packaging cluster around Frankfurt hosts converting operations serving Swissmedic and EMA serialization requirements for vaccine logistics.
China
Domestic beverage and consumer electronics packaging absorbs massive folding boxboard volumes from Yangtze River Delta mills. The country's dual carbon goals pressure mills to decarbonize coal-dependent drying processes. Guangdong Province converters supply export-bound customer goods facing EU carbon border adjustment mechanism exposure.
United States
Beverage carton demand anchors Graphic Packaging's integrated extrusion and printing assets in the Southeast. EPA Comprehensive Procurement Guidelines enforce recycled fiber content thresholds for federal procurement. The Chicago-Milwaukee corridor concentrates folding carton converting for Midwest food processing and dairy operations.
India
FSSAI food contact mandates are tightening migration limits for barrier-coated board in ready-meal and dairy applications. The country's national food safety regulator creates first-mover advantage for converters with existing EFSA compliance documentation. Maharashtra and Gujarat host expanding converting capacity serving domestic FMCG brand owners and export markets.
Brazil
Bleached eucalyptus pulp integration supports competitive solid bleached sulphate production for cosmetic and pharmaceutical export markets. ANVISA pharmaceutical packaging regulations align with FDA and EMA standards, enabling seamless export qualification. São Paulo state concentrates converting operations serving Mercosur personal care and food brands.
Global Cartonboard Market Competitive Landscape
Top-tier vendors anchor integrated pulp-to-board operations, while mid-scale converters compete on specialized coating capabilities and regional logistics. The vendor base stratifies across three tiers: multinational integrated producers with captive pulp supply, regional specialists with extrusion and printing assets, and toll-coating operators serving brand-owner specifications. Strategic archetypes include backward-integrated European champions, Asian scale players with recycled fiber dominance, and North American beverage-focused converters. Competitive moves concentrate on barrier coating reformulation for regulatory compliance and shared toll-coating infrastructure investments to amortize capital costs.
Within the integrated European tier, Mayr-Melnhof Karton AG exemplifies backward integration into pulp supply to secure coated board capacity. Graphic Packaging Holding Company occupies a position among North American beverage carton specialists with in-house extrusion assets. Smurfit WestRock represents the recycled fiber scale archetype, operating containerboard-to-cartonboard conversion networks across multiple continents.
| Leading Market Players |
|---|
| Mayr-Melnhof Karton AG (MM Group) |
| Graphic Packaging Holding Company |
| Nine Dragons Paper (Holdings) Limited |
| Asia Pulp and Paper Company Ltd. |
| Smurfit WestRock |
| Stora Enso Oyj |
| International Paper Company |
| Metsa Board |
| WestRock Company |
| Others |
Supply & Pricing Matrix
Family-owned Nordic pulp producers anchor supply discipline through captive hardwood fiber reserves, translating upstream scarcity into contract pricing power for premium Solid Bleached Sulphate grades. This ownership structure insulates long-term offtake negotiations from quarterly earnings pressure, reinforcing margin stability across volatile bleached chemical pulp cycles.
Pricing Analysis
Margin tightening in pharmaceutical-grade Solid Bleached Sulphate reflects Swissmedic serialization mandates and EMA sterility documentation requirements. Contract-based long-term offtake dominates, with price differentiation hinging on FDA food contact notification tier and FSC chain-of-custody certification level. Cost-down pressure on recycled board accelerates because post-consumer fiber contamination degrades yield rates at North American mills. Brand owners impose the least price sensitivity, absorbing premium for barrier-coated grades, while contract packaging providers face acute margin compression.
Supply Chain Analysis
Skilled technician shortages in German converting clusters and São Paulo state constrain extrusion line retrofitting capacity for EU F-Gas Regulation compliance. Geographic supply concentrates in Finland, Sweden, and Brazil for bleached chemical pulp, with Germany and China hosting dominant folding carton converting. Raw material dependencies center on Nordic hardwood pulp, Brazilian eucalyptus fiber, and kaolin mineral coatings. Single-source vulnerability runs through Nordic suppliers controlling over half of premium-grade chemical pulp. Distribution feeds from mill-direct contracts to regional converting hubs, then to brand-owner specification control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bleached hardwood pulp concentration props pricing across pharmaceutical and food-contact grades, with Nordic supplier discipline limiting spot market liquidity for premium Solid Bleached Sulphate.
For Market Incumbents: Deepen backward integration into Brazilian eucalyptus pulp supply to offset Nordic freight volatility and currency exposure. Secure dedicated extrusion capacity for PETG barrier coating ahead of 2027 EU F-Gas phase-down deadlines. Reinforce supplier status with L'Oréal and Unilever through vendor-managed inventory telemetry and quarterly volume commitment structures. For New Entrants and Emerging Players: Mid-tier Indian FMCG brand owners present the most penetrable buyer archetype, with FSSAI migration limit tightening creating specification windows for EFSA-compliant converters. Toll-coating partnerships with German pharmaceutical clusters offer asset-light entry into sterility-grade folding carton supply. Target ready-meal and dairy applications in Maharashtra and Gujarat with barrier-coated board positioning. For Investors and Strategic Acquirers: ANVISA alignment with FDA and EMA standards in Brazil is the leading indicator that Mercosur pharmaceutical export capacity will command acquisition premiums. Five-to-ten year viability favors integrated pulp-to-board operators with certified low-carbon intensity processes for EU carbon border adjustment mechanism exposure. Watch for EU Green Deal recycled content mandate acceleration as inflection signal for Recycled Board segment repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Reformulation | Bio-based alternatives to fluorinated chemistries open compliant producer capacity under REACH restrictions. |
| Backward Integration into Pulp | Captive Brazilian eucalyptus supply secures Solid Bleached Sulphate margin against Nordic currency volatility. |
| Shared Toll-Coating Infrastructure | Pharmaceutical and confectionery segments amortize capital costs across German retrofitting investments. |
| Digital Printing Integration | Compression of minimum order quantities enables subscription food box specification capture. |
| Carbon Intensity Certification | EU CBAM exposure incentivizes regional producers to certify low-carbon board for export-bound goods. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across plant managers at integrated mills, procurement leads at folding carton converters, technical R&D directors for barrier coating formulation, and brand-owner packaging specification managers. Bottom-up volume triangulation from mill capacity utilization and top-down demand validation from end-use consumption patterns were reconciled against EPA Comprehensive Procurement Guidelines, EU Green Deal disclosure requirements, and FSSAI migration limit documentation.
Data-stream reconciliation across the projection horizon applied product type, application end-use, and regional regulatory cluster segmentation. CAGRs were derived from elasticity-adjusted demand modeling incorporating pharmaceutical cold-chain expansion rates, beverage carton specification shifts, and recycled fiber content mandate trajectories. Industry-specific forecast inputs included EMA serialization timeline impacts and EU F-Gas Regulation phase-down compliance costs.
Revisions become necessary when REACH substance restriction acceleration, EU carbon border adjustment mechanism implementation scope, or Nordic pulp supply disruption materialize. Forecasts reflect documented assumptions regarding barrier coating approval timelines and post-consumer fiber quality stabilization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
MET-PET Cartons Market
Cartons
Wax Boxes Market
Cartons
Tablet Cartons Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Round Corrugated Box Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Brick Liquid Carton Market
Cartons
Digital Printed Cartons Market
Cartons
Interlocking Boxes Market
Cartons
Folding Cartons Market
Cartons
XXL Packaging Market
Cartons
Global Open Top Cartons Market
Cartons
Fluted Carton Trays Market
Cartons
Europe Corrugated Box Market
Cartons
Carton Display Market
Cartons
Global Hand Carton Sealers Market