
 Beverage Caps and Closures Market | 2026-2036
Beverage Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Caps and Closures Market Outlook
Craft brewers and functional drink startups are reorganizing the buyer landscape for beverage caps and closures, pulling volume away from legacy carbonated soft drink contracts. Crown Holdings, Inc. anchors North American aluminum closure supply through integrated metal forming and coating operations. Silgan Holdings Inc. dominates mass-market plastic screw cap production for bottled water and juice categories. BERICAP Holding GmbH differentiates through specialized sports cap and tethered closure engineering for European dairy and isotonic brands.
Beverage caps and closures are precision-engineered sealing devices, typically injection-molded from high-density polyethylene or polypropylene, or stamped from aluminum or tinplate, designed to maintain carbonation retention, prevent contamination, and enable controlled dispensing across liquid packaging formats. Plastic closures retain volume leadership across the global installed base due to cost scalability and color customization flexibility, while metal variants command premium positioning in alcoholic beverage segments where oxygen ingress control and brand aesthetics carry higher weight. The application dimension shows soft drinks and water categories representing mature, high-volume throughput channels with thinner margins, whereas alcoholic beverages and functional juices concentrate margin pools through custom embossing, tamper-evident features, and specialty dispensing mechanisms.
The FDA governs indirect food contact substances under 21 CFR, while the EU F-Gas Regulation and REACH chemical restrictions constrain certain polymer additives and propellant-based dispensing closures. China's SAMR enforces GB standards for food-contact plastics that affect import qualification timelines for foreign closure suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and tethered closure mandates across multiple jurisdictions to anticipate retooling requirements and material specification shifts.
Market Dynamics
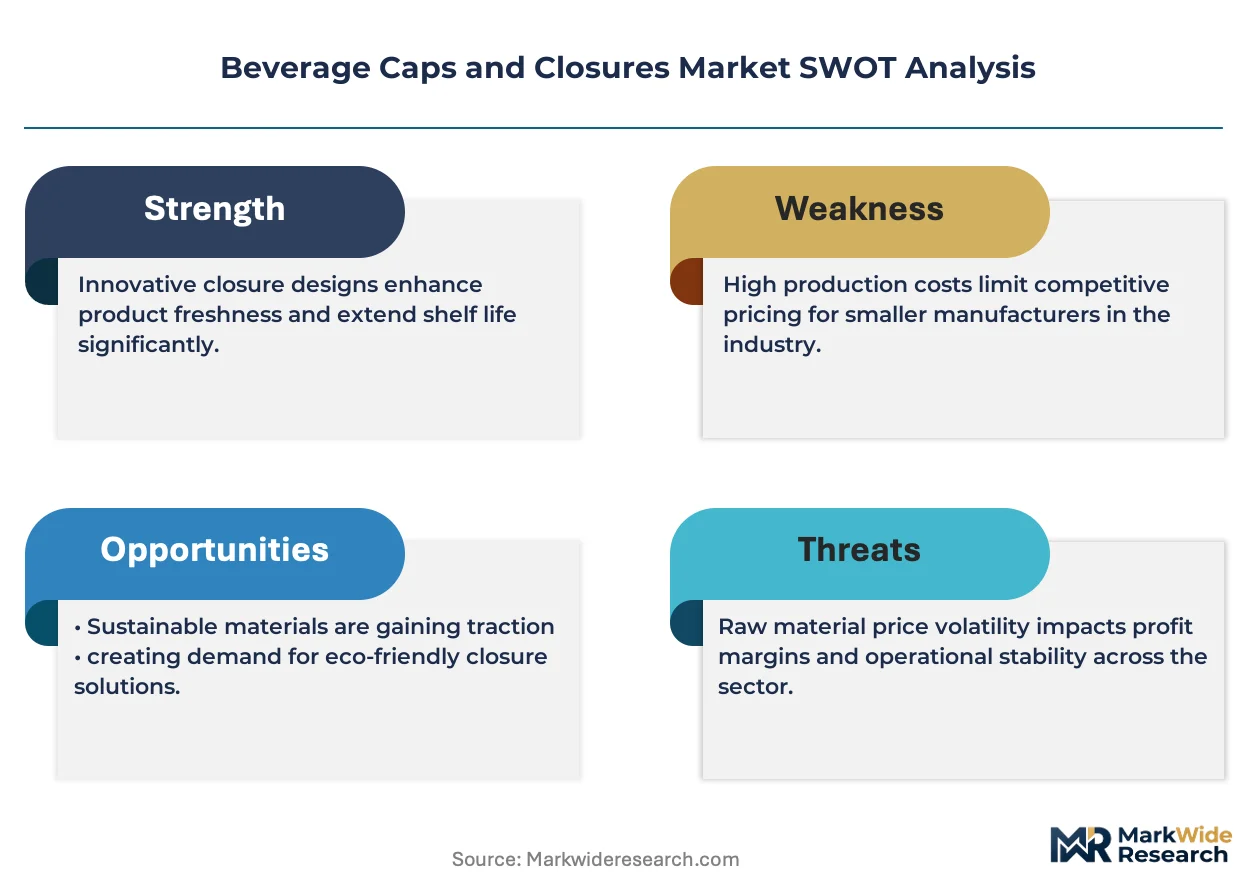
Lightweighting mandates from ready-to-drink tea and functional beverage brands are compressing material specifications across closure procurement contracts, forcing retooling investments at molders serving legacy carbonated soft drink channels.
Growth Catalysts
- EU Single-Use Plastics Directive:Tethered closure mandates are accelerating engineering redesigns at European dairy and isotonic bottlers, creating specification pull-through for compliant closure suppliers.
- India's western bottling corridor:Maharashtra and Gujarat production clusters are scaling domestic beverage manufacturing, concentrating demand for high-throughput screw cap and sports closure formats.
- High-density polyethylene recycling streams:Post-consumer rHDPE availability is improving material circularity credentials for bottled water and juice categories seeking closed-loop packaging claims.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings are compressing margin predictability for injection molders serving mass-market plastic closure contracts.
- Aluminum coil supply concentration:North American metal forming operations face input bottlenecks from concentrated primary aluminum smelter geography.
- REACH chemical restrictions:ECHA additive constraints are limiting certain UV stabilizers and colorants in European food-contact closure applications.
Strategic Opportunities
- China's GB standards compliance:Foreign closure suppliers face extended SAMR qualification timelines, creating first-mover advantage for early-certified entrants.
- Sports cap dispensing convergence:Isotonic and functional beverage brands are consolidating around tethered flip-top geometries that bridge dairy and energy drink applications.
- Extended producer responsibility frameworks:Deposit-return schemes in multiple jurisdictions are mandating design-for-recycling specifications that favor mono-material closure constructions.
Industry Challenges
- Multi-cavity mold engineering talent:Shortage of precision tooling specialists is extending lead times for high-speed closure production lines.
- Legacy carbonated soft drink line integration:Retooling for lighter-weight closures requires synchronized conveyor and capping equipment modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Caps and Closures Market |
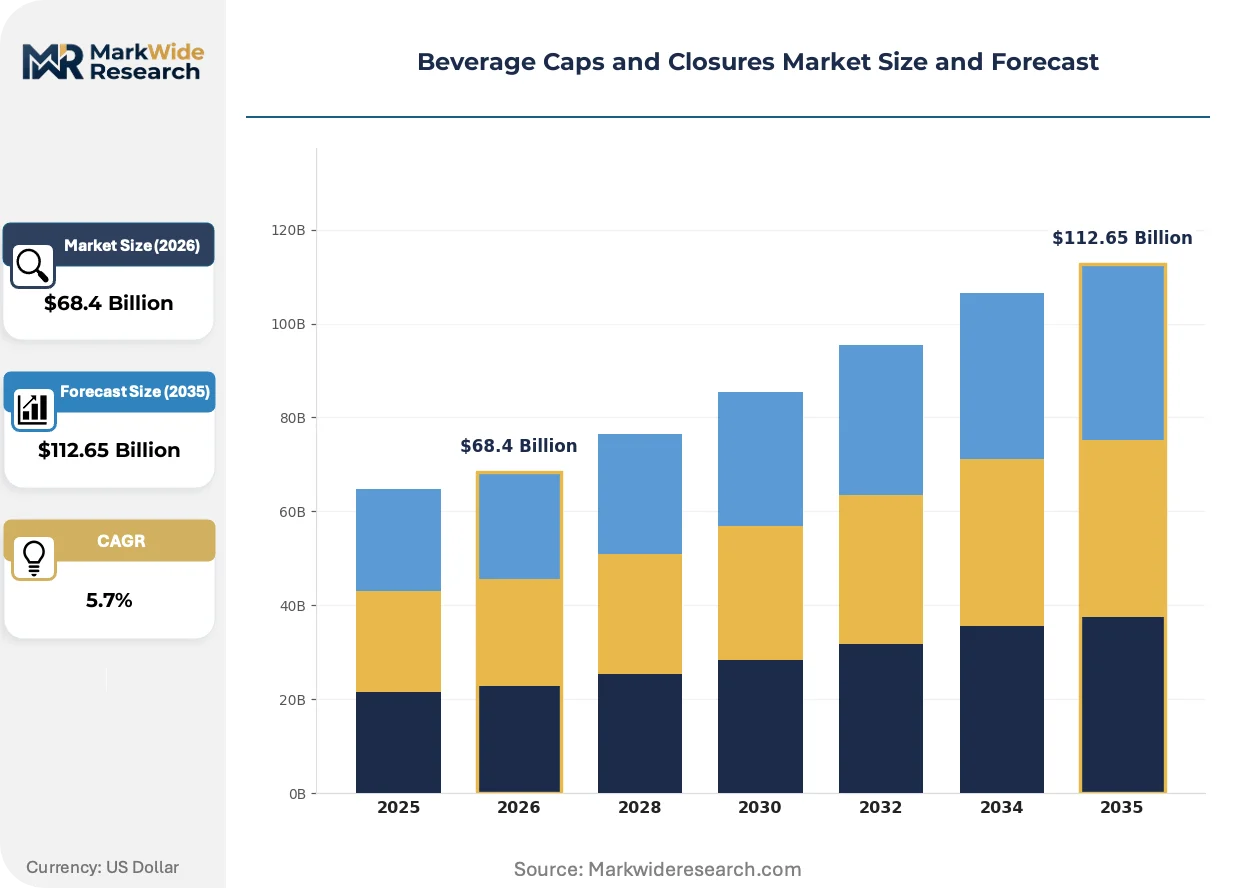
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Lids, Corks, Closures Material: Plastic, Metal, Glass, Composite End User: Beverage Manufacturers, Bottlers, Distributors, Retailers Application: Soft Drinks, Alcoholic Beverages, Water, Juices |
| Companies Covered | Crown Holdings, Inc., Amcor plc, Silgan Holdings Inc., AptarGroup, Inc., BERICAP Holding GmbH, Closure Systems International, Guala Closures S.p.A, Berry Global, Inc., UNITED CAPS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Caps and Closures Market Strategic Shifts
Material science advances and regulatory design mandates are converging to reshape closure engineering priorities, with sustainability credentials and dispensing functionality now co-equal specification drivers.
Mono-material polypropylene closures with integrated tamper-evident bands are fragmenting legacy multi-component designs across premium bottled water and functional juice segments. European and North American craft beverage brands are specifying these constructions to satisfy mechanical recycling stream requirements. The shift is compressing demand for separate liner and cap assemblies that complicate sortation infrastructure.
China's GB standards for food-contact plastics are tightening additive migration thresholds under SAMR enforcement protocols. Imported closure suppliers face extended laboratory testing and documentation requirements before qualifying for domestic beverage production contracts. The friction is redirecting procurement toward certified domestic molders for time-sensitive product launches.
Direct-to-brand procurement models are displacing traditional distributor intermediaries in specialty beverage segments. Functional drink startups and craft brewers are engaging closure engineers directly for custom embossing and specialty dispensing mechanisms. California and Pacific Northwest beverage clusters exhibit the most pronounced channel compression, with brands consolidating specification authority in-house.
Beverage Caps and Closures Market Segmentation
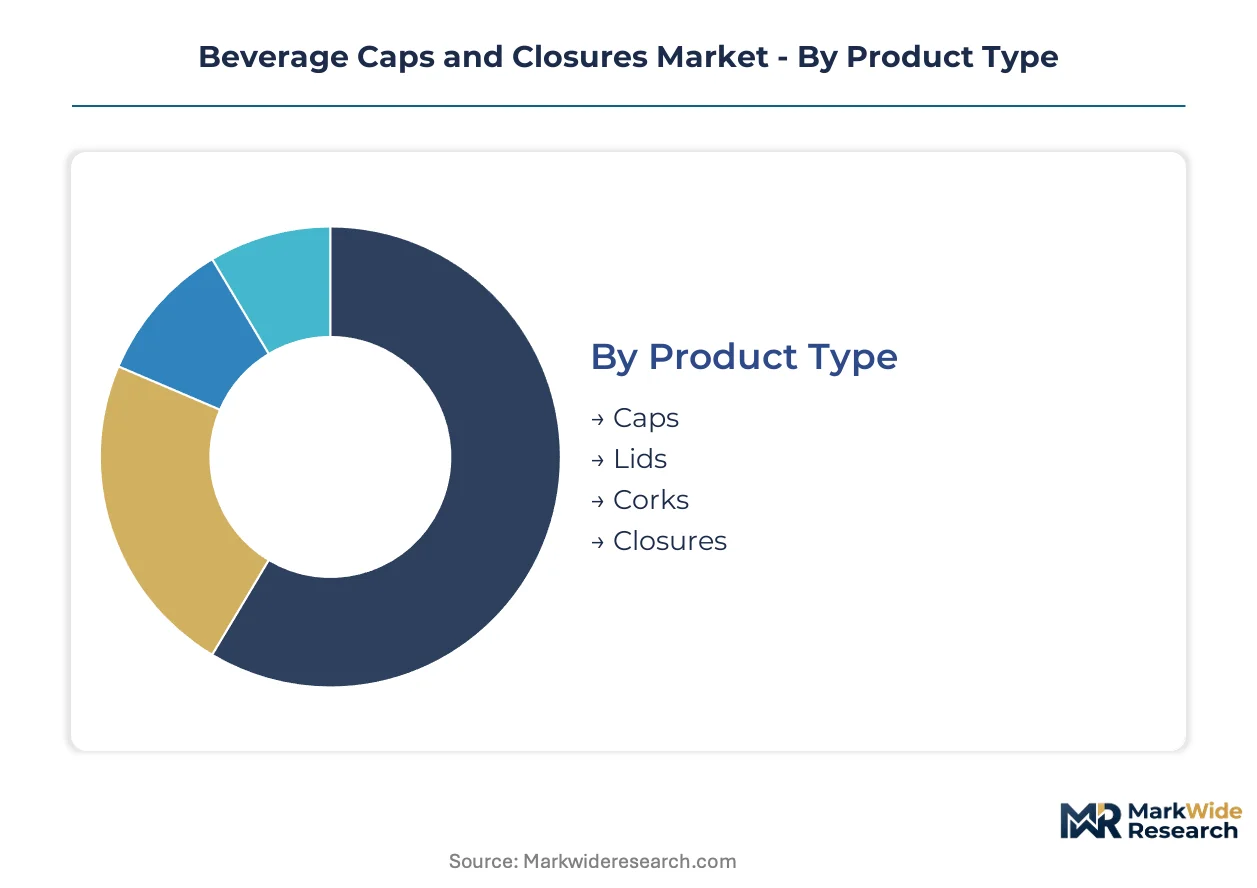
Beverage cap procurement patterns diverge sharply across material types and end-use channels, with carbonated soft drink contracts favoring commodity-scale plastic formats while craft alcoholic brands drive premium metal specifications. Understanding these segment boundaries clarifies where specification authority concentrates and which converter capabilities command pricing power.
Product Type:
Domestic bottling corridors in India and China's eastern provinces anchor demand for high-throughput screw caps, whereas European export channels concentrate specification pull for tethered sports caps and tamper-evident closures.
- Caps:Injection-molded HDPE and polypropylene screw caps dominate bottled water and mass-market juice throughput, with Maharashtra and Gujarat production clusters scaling procurement volumes for domestic Indian brands. Lightweighting mandates from ready-to-drink tea producers are compressing wall thickness specifications and forcing mold reconfiguration.
- Lids:Peelable aluminum and laminated structures serve dairy and functional beverage applications where oxygen barrier properties outweigh cost minimization. European dairy bottlers under EU Single-Use Plastics Directive compliance timelines are specifying tethered lid geometries that integrate with existing filling lines.
- Corks:Natural and synthetic cork formats retain positioning in wine and premium spirits segments where ritual opening experience supports brand premiumization. Portuguese and Spanish cork suppliers face displacement pressure from screw cap adoption in sub-premium wine tiers.
- Closures:Dispensing mechanisms including sports caps, pump closures, and trigger sprayers concentrate in isotonic and functional beverage categories. California beverage startups are engaging closure engineers directly for custom dispensing geometries that differentiate shelf presentation.
Caps hold the largest share; momentum sits with closures as functional beverage brands consolidate procurement around specialized dispensing formats.
Material:
Cost tier stratification separates commodity-scale polymer contracts from premium metal specifications, with recyclability credentials now cutting across both tiers as deposit-return schemes proliferate.
- Plastic:Polypropylene and HDPE closures command volume leadership through cost scalability and color customization flexibility, though propylene monomer price volatility compresses margin predictability for injection molders. Post-consumer rHDPE availability is improving circularity credentials for bottled water brands seeking closed-loop packaging claims.
- Metal:Aluminum and tinplate variants serve alcoholic beverage segments where oxygen ingress control and embossing aesthetics support premium positioning. North American coil supply concentration from primary smelter geography is creating input bottlenecks for metal forming operations.
- Glass:Limited to specialty spirits and ceremonial packaging where inert contact surface and weight signal quality. High freight costs restrict glass closure deployment to super-premium price tiers with localized distribution footprints.
- Composite:Multi-material laminates and co-injected structures bridge barrier performance and cost constraints in extended-shelf-life juice applications. Mechanical recycling incompatibility is forcing redesign toward mono-material alternatives under extended producer responsibility frameworks.
Plastic dominates absolute volume; aluminum is climbing the fastest as craft brewers and premium spirits brands specify metal for oxygen barrier and brand differentiation.
End User:
Customer type determines specification authority concentration, with direct-to-brand procurement displacing distributor intermediaries in specialty segments while mass-market channels retain legacy purchasing structures.
- Beverage Manufacturers:Integrated brand owners including multinational soft drink and water companies exercise centralized procurement with volume-tier pricing and technical specification control. These buyers are mandating lightweighting targets and recyclability certifications across closure supply contracts.
- Bottlers:Contract manufacturing operations serving multiple brands prioritize line compatibility and changeover efficiency over custom engineering, favoring standardized closure formats that minimize retooling downtime.
- Distributors:Wholesale intermediaries retain influence in fragmented regional markets where small brands lack procurement scale, though their specification role diminishes as direct manufacturer engagement expands.
- Retailers:Private label and store-brand beverage programs are consolidating closure specification authority in-house, with European grocery chains imposing tethered closure requirements ahead of regulatory deadlines.
Beverage manufacturers hold the largest share; retailers are gaining specification authority fastest as private label programs expand and compliance mandates concentrate procurement decision-making.
Application:
Application maturity separates high-volume, thin-margin carbonated channels from custom-engineered alcoholic and functional segments where tamper-evident and dispensing features support pricing power.
- Soft Drinks:Carbonated beverage closures emphasize carbonation retention and high-speed capping line compatibility, with procurement concentrated among legacy brand owners facing volume stagnation. Lightweighting mandates are compressing material specifications and forcing synchronized conveyor modifications.
- Alcoholic Beverages:Wine, beer, and spirits applications command premium positioning through custom embossing, oxygen-scavenging liners, and ritual opening mechanisms. Craft brewers and startup distillers are reorganizing buyer landscapes with direct engineering engagement.
- Water:Still and sparkling bottled water represents the highest absolute closure volume with thinnest margins, driving commodity-scale polypropylene procurement and color customization for brand differentiation.
- Juices:Functional and premium juice segments concentrate margin pools through extended shelf-life barriers, tamper-evident bands, and dispensing convenience features that support price premiums over commodity alternatives.
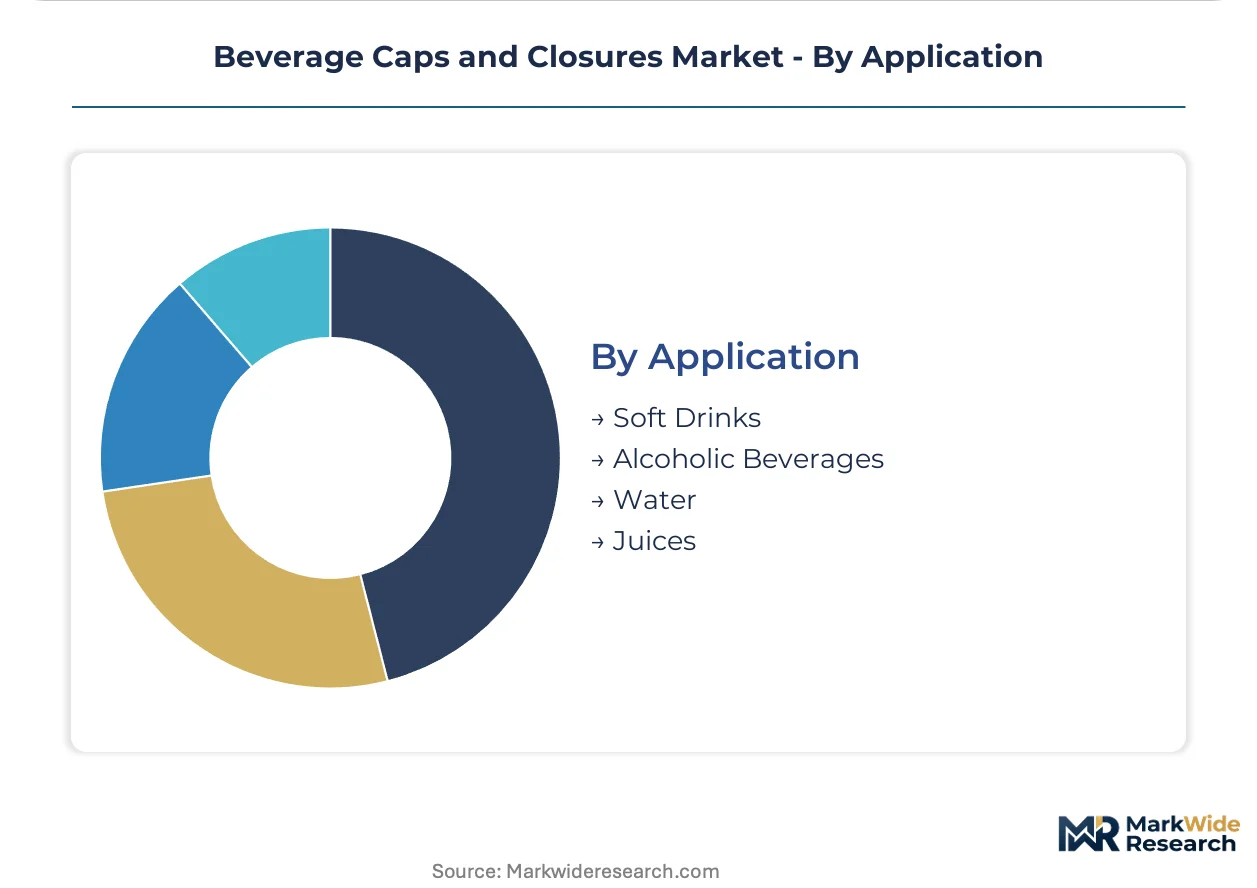
Soft drinks hold the largest share; alcoholic beverages show the steepest expansion trajectory as craft production scales and premiumization extends into emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German closure manufacturers export tethered sports cap designs to European dairy and isotonic bottlers under EU Single-Use Plastics Directive compliance timelines. India's western bottling corridor ships high-throughput screw caps to domestic beverage brands scaling production for regional distribution.
United States
Craft brewers and functional drink startups in California and the Pacific Northwest are consolidating direct procurement relationships with closure engineers for custom dispensing mechanisms. FDA oversight of indirect food contact substances under 21 CFR shapes material qualification protocols for imported polymer formulations. Crown Holdings anchors aluminum closure supply through integrated metal forming operations concentrated in eastern manufacturing zones.
Germany
European dairy and isotonic brands are mandating tethered closure redesigns ahead of regulatory deadlines, pulling engineering specifications toward compliant suppliers. ECHA REACH chemical restrictions constrain UV stabilizers and colorants in food-contact applications, forcing additive reformulation. BERICAP Holding GmbH differentiates through specialized sports cap engineering serving export channels across the continent.
China
SAMR enforcement of GB standards for food-contact plastics is extending qualification timelines for foreign closure suppliers, redirecting procurement toward certified domestic molders. The Yangtze River Delta and Pearl River Delta production clusters concentrate injection molding capacity for bottled water and juice categories. Dual carbon goals are tightening energy efficiency requirements at polymer processing facilities.
India
Maharashtra and Gujarat bottling corridors are scaling domestic beverage manufacturing, concentrating demand for high-throughput screw cap formats. FSSAI food safety protocols govern plastic migration thresholds for closure materials used in packaged drinking water. Silgan Holdings and regional molders are expanding capacity to serve procurement contracts from multinational brand owners establishing local production.
Brazil
São Paulo and Minas Gerais beverage production clusters are driving procurement of color-customizable polypropylene closures for differentiated brand presentation. ANVISA pharmaceutical and food contact regulations shape import qualification requirements for closure materials. Extended producer responsibility frameworks under development are mandating design-for-recycling specifications that favor mono-material constructions.
Beverage Caps and Closures Market Competitive Environment
Listed leaders compete with private specialists across material technology and geographic coverage dimensions. The vendor base organizes around three tiers: multinational packaging conglomerates with integrated metal and polymer operations, mid-cap specialists focused on tethered or dispensing closure engineering, and regional injection molders serving commodity bottled water contracts. Strategic moves center on capacity expansion in India's western corridor and portfolio diversification into mono-material recyclable designs.
Within the integrated conglomerate tier, Crown Holdings, Inc. and Silgan Holdings Inc. occupy positions spanning aluminum forming and plastic injection molding capabilities. BERICAP Holding GmbH exemplifies the specialist archetype, anchoring European engineering expertise in sports cap and tethered closure geometries. These three entities represent distinct competitive vectors: metal-forming scale, mass-market plastic throughput, and differentiated dispensing innovation.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Amcor plc |
| Silgan Holdings Inc. |
| AptarGroup, Inc. |
| BERICAP Holding GmbH |
| Closure Systems International |
| Guala Closures S.p.A |
| Berry Global, Inc. |
| UNITED CAPS |
| Others |
Value Chain & Pricing Dynamics
EU REACH chemical restrictions and FDA 21 CFR compliance tiers simultaneously gate supplier qualification and stratify pricing power across closure procurement contracts. Certification investment separates premium metal forming operations from commodity injection molders, with compliant suppliers commanding specification authority in tethered closure and food-contact segments.
Pricing Analysis
Next-generation mono-material polypropylene closures with integrated tamper-evident bands command 15-25% premiums over legacy multi-component designs, while prior-generation aluminum screw caps face margin compression from coil supply bottlenecks. Contract-based long-term offtake agreements dominate mass-market bottled water procurement, with price differentiation driven by volume scale and GB standards certification tier. Cost compression in commodity polypropylene closures is intensifying because propylene monomer volatility feeds through resin contracts. Beverage manufacturers exhibit lowest price sensitivity in premium alcoholic segments, whereas contract bottlers serving multiple brands drive hardest bargain on standardized formats.
Supply Chain Analysis
Inventory lead times for multi-cavity precision molds now stretch 18-24 weeks, constraining capacity expansion timelines for high-throughput closure lines. Manufacturing concentrates in China, Germany, and India, with the Yangtze River Delta and Maharashtra bottling corridors anchoring injection molding capacity. Raw material flows draw from Saudi Arabian and U.S. Gulf Coast propylene monomer sources, plus Canadian and Australian primary aluminum. Single-source vulnerability concentrates in North American coil supply from smelter geography. Distribution runs through direct-to-brand procurement channels in California and Pacific Northwest beverage clusters, with legacy distributor networks retaining fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where tethered closure standardization across dairy and isotonic categories creates interoperability lock-in for compliant engineering suppliers.
For Market Incumbents: Consolidate specification authority by acquiring certified domestic molders in India's western corridor ahead of FSSAI enforcement tightening. Deepen backward integration into rHDPE recycling streams to secure closed-loop packaging claims that multinational beverage manufacturers now mandate. Crown Holdings and Silgan Holdings must defend aluminum forming scale against polypropylene lightweighting substitution in sub-premium beer tiers.
For New Entrants and Emerging Players: Custom dispensing mechanism engineering for California functional beverage startups represents the most penetrable service-layer gap where incumbents under-serve with standardized catalog offerings. Target direct procurement relationships with craft brewers seeking embossed metal closures and oxygen-scavenging liner integration. Go-to-market angle: rapid prototyping capabilities that compress 12-week custom mold cycles to 6-week iterations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates where closure divisions lack standalone scale but hold tethered closure IP and SAMR GB certification. Mid-cap specialists with European sports cap engineering and Indian production footprint offer strongest 5-10 year viability as regulatory compliance concentrates procurement. Watch ECHA additive restriction expansions as inflection signal for reformulation-driven supplier switching.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Closure Redesign | Mechanical recycling compatibility satisfies EU extended producer responsibility mandates ahead of tethered closure deadlines. |
| India Western Corridor Capacity Expansion | Maharashtra and Gujarat production clusters capture procurement volume from multinational brands localizing beverage manufacturing. |
| GB Standards Certification Investment | SAMR qualification timelines redirect procurement toward early-certified entrants in China's Yangtze River Delta. |
| Sports Cap Dispensing Convergence | Tethered flip-top geometries bridge dairy and energy drink applications, consolidating engineering R&D spend. |
| rHDPE Closed-Loop Integration | Post-consumer recycling streams support bottled water brand sustainability claims and deposit-return scheme compliance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and beverage industry production databases. Primary interviews engaged closure engineering directors at tier-1 molders, procurement leads at multinational beverage manufacturers, plant managers at Indian bottling corridors, and regulatory affairs specialists navigating SAMR and ECHA compliance. Secondary validation drew from FDA 21 CFR guidance documents, EU Single-Use Plastics Directive implementation timelines, and FSSAI food-contact plastic standards. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across material type, application, and regional production cluster dimensions.
Segmentation dimensions modeled include closure product type, material composition, end-user procurement structure, and application category across the analysis window. CAGRs derived from trend extrapolation of lightweighting mandates, regulatory compliance timelines, and regional production scaling patterns. Industry-specific forecast inputs incorporated propylene monomer price volatility assumptions and aluminum coil supply concentration risk factors.
Underlying assumptions cover sustained EU tethered closure enforcement, India's beverage production scaling trajectory, and China's GB standards implementation pace, with deviation risk concentrated in propylene feedstock volatility and REACH chemical restriction expansions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Plunger Stopper Market