
 Europe Mass Spectroscopy Market | 2026-2036
Europe Mass Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mass Spectroscopy Market Insights
The EU Green Deal is rebalancing capital allocation toward high-resolution mass spectrometry platforms capable of sub-part-per-billion contaminant detection. Thermo Fisher Scientific leverages its Orbitrap manufacturing footprint in Bremen to anchor regional supply. Waters Corporation sustains competitive positioning through specialized liquid chromatography-mass spectrometry configurations for biopharma QC. Analytik Jena GmbH & Co. KG differentiates via compact quadrupole systems tailored to mid-sized environmental laboratories.
Mass spectroscopy identifies and quantifies molecules by measuring mass-to-charge ratios of ionized particles, typically achieving resolution below 1 ppm and mass accuracy within 2 ppm using time-of-flight or Orbitrap analyzers. Its primary purpose spans pharmaceutical impurity profiling, environmental pollutant monitoring, and clinical biomarker validation. Quadrupole platforms dominate installed base economics due to lower service attach rates and standardized method transfer, while Orbitrap systems command premium positioning in proteomics and metabolomics where resolution thresholds determine experimental validity. Drug discovery applications absorb the largest share of new instrument spend, though environmental analysis is narrowing the gap as PFAS regulatory limits tighten across member states.
EMA bioanalytical method validation guidelines, REACH substance identification requirements, and EU MDR clinical testing standards collectively elevate compliance burdens for instrument qualification and software integrity. ECHA's expanding candidate list of substances of very high concern directly drives demand for high-resolution accurate mass systems capable of non-targeted screening. Stakeholders must weigh capital deployment between established quadrupole workhorses and emerging desorption electrospray platforms that promise reduced sample preparation overhead.
Market Dynamics
EMA bioanalytical method validation guidelines and REACH substance identification requirements are forcing pharmaceutical and chemical laboratories across Europe to retire legacy quadrupole systems and validate high-resolution accurate mass platforms for compliance-critical workflows.
Growth Catalysts
- EU Green Deal chemical traceability mandates:Member state environmental agencies must detect contaminants at sub-part-per-billion thresholds, accelerating replacement of aging gas chromatography infrastructure with LC-MS/MS and Orbitrap systems in national reference laboratories.
- PFAS regulatory tightening:ECHA's expanding candidate list of substances of very high concern requires non-targeted screening capabilities that only high-resolution mass spectrometry delivers, pulling demand from industrial testing services and contract research organizations.
- German biopharma cluster expansion:Munich and Frankfurt pharmaceutical manufacturing hubs are scaling bioanalytical QC capacity to support biosimilar and cell therapy production, anchoring regional instrument procurement cycles.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry systems depend on constrained helium feedstock from Algerian and Russian sources, creating operational uncertainty for laboratories running electron ionization workflows.
- High-resolution platform cost concentration:Orbitrap and time-of-flight systems carry capital expenditure thresholds that exclude mid-sized environmental laboratories in Southern and Eastern Europe from compliance-ready detection capabilities.
- Service engineer scarcity:Specialized field service capacity for vacuum system maintenance and ion source optimization concentrates with OEM-trained technicians in Germany, France, and the United Kingdom, extending downtime for peripheral markets.
Strategic Opportunities
- Desorption electrospray ionization convergence:Ambient ionization techniques paired with portable mass spectrometers enable point-of-need testing for food safety and customs applications, opening laboratory-adjacent revenue streams.
- Poland and Romania laboratory buildouts:EU structural funds are financing environmental monitoring infrastructure in accession-heavy regions, creating first-mover advantages for compact quadrupole vendors with localized service partnerships.
- CSRD supply chain disclosure requirements:Corporate sustainability reporting obligations are compelling chemical manufacturers to implement continuous emissions monitoring using process mass spectrometry, embedding instruments directly into production lines.
Industry Challenges
- Method transfer standardization gaps:EMA bioanalytical validation guidelines lack harmonized protocols for migrating legacy triple-quadrupole methods to high-resolution platforms, extending qualification timelines for contract research organizations.
- Software integrity verification:EU MDR clinical testing standards and 21 CFR Part 11 compliance requirements impose validation burdens on chromatography data systems, consuming technical resources that might otherwise support method development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mass Spectroscopy Market |
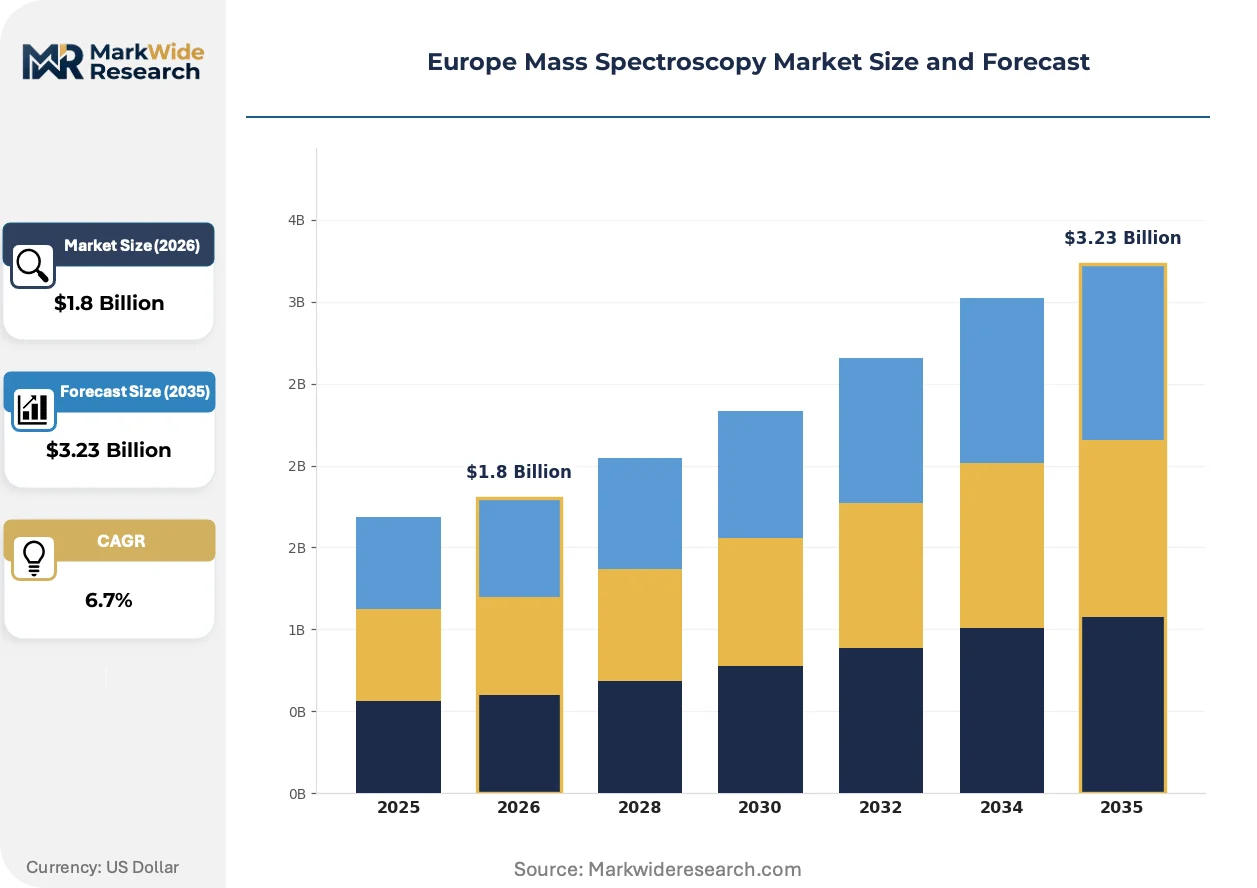
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrupole, Time-of-Flight, Ion Trap, Orbitrap Application: Drug Discovery, Environmental Analysis, Clinical Diagnostics, Proteomics End User: Pharmaceuticals, Academic Research, Food & Beverage, Biotechnology Technology: Gas Chromatography, Liquid Chromatography, Desorption Electrospray, Matrix-Assisted |
| Companies Covered | Thermo Fisher Scientific Inc., Waters Corporation, Agilent Technologies, Inc., Bruker Corporation, Danaher Corporation, Analytik Jena GmbH & Co. KG, Hiden Analytical, Shimadzu Corporation, Dani Instruments SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mass Spectroscopy Market Trends and Innovations
Mass spectrometry instrumentation across Europe is pivoting from centralized laboratory deployment toward distributed analytical networks, with ion source miniaturization and cloud-native data architectures enabling new operational models for regulated testing environments.
Orbitrap-based high-resolution accurate mass systems are absorbing capital allocation previously directed toward triple-quadrupole workhorses in pharmaceutical impurity profiling workflows. Top-ten biopharma manufacturers in Basel, Cambridge, and Södertälje have standardized on Orbitrap platforms for metabolite identification studies. This technology convergence is compressing the acceptable resolution threshold for regulatory submissions, effectively disqualifying lower-resolution alternatives from method validation protocols.
REACH substance identification requirements now mandate analytical techniques capable of distinguishing constitutional isomers and stereoisomers for substances above one tonne annual volume. Chemical manufacturers in the Antwerp-Rotterdam-Rhine-Ruhr corridor are retrofitting existing laboratories with ion mobility-quadrupole-time-of-flight configurations to satisfy ECHA dossier demands. The coatings and polymers segment bears the heaviest compliance burden, with substance notification deadlines cascading through 2025-2027 driving synchronized procurement waves.
Service unbundling is fragmenting traditional instrument sales models across European pharmaceutical quality control departments. Large molecule manufacturers in Ireland and Denmark now separate hardware acquisition from method development and validation services, awarding multi-year service contracts to specialized analytical consulting firms rather than OEM service organizations. This behavioral shift is most pronounced among mid-cap biotechs lacking in-house mass spectrometry expertise, who prefer operational expenditure structures over capital-intensive instrument ownership.
Europe Mass Spectroscopy Market Segmentation
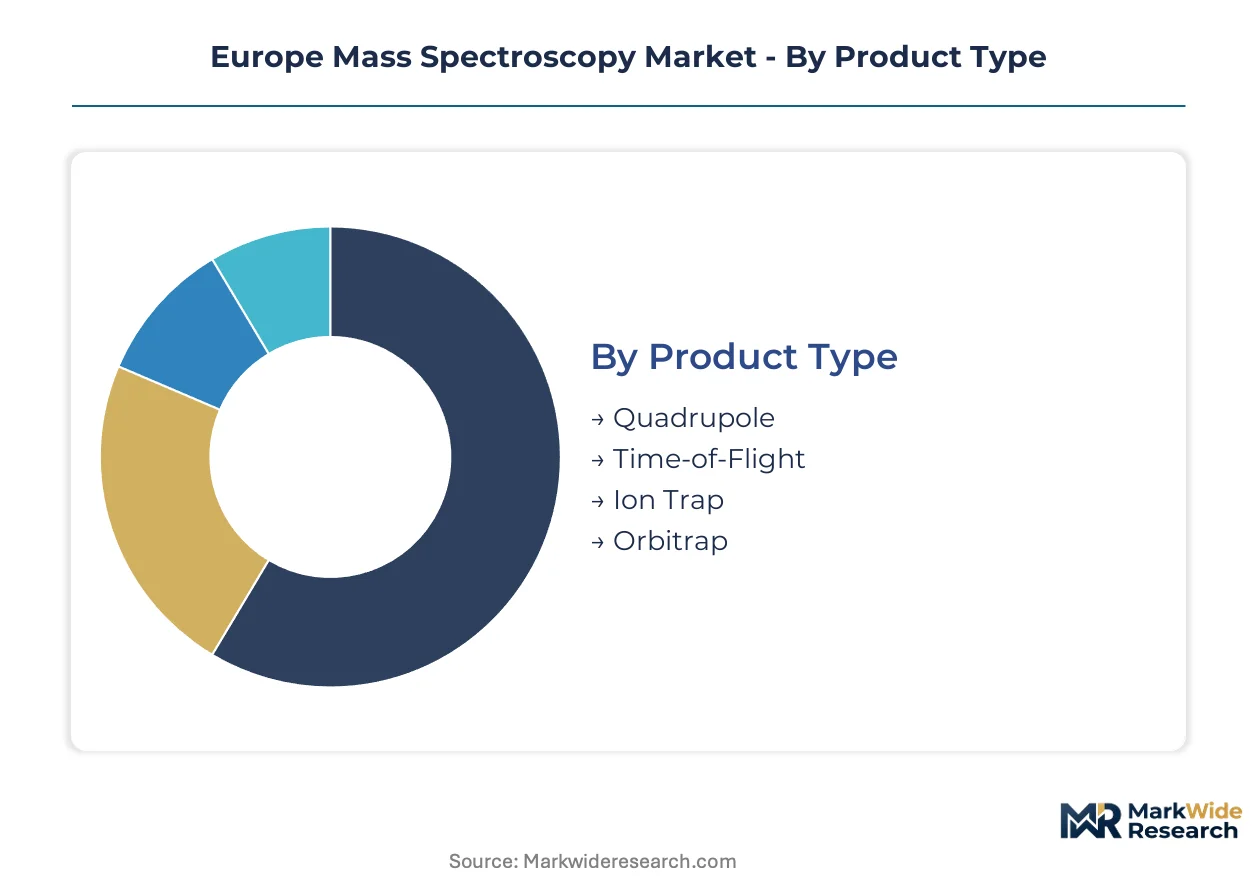
Mass spectrometry purchasing in Europe follows distinct technical and economic logics across product platforms, application workflows, and end-user facilities. Buyers weigh resolution requirements against throughput demands, while regulatory compliance thresholds reshape segment prioritization across national laboratory networks.
Product Type:
Capital allocation decisions hinge on the trade-off between capital intensity and analytical resolution, with compliance mandates increasingly favoring platforms capable of sub-ppm mass accuracy.
- Quadrupole:Triple-quadrupole configurations deliver selective reaction monitoring for quantitative bioanalysis with established method libraries. German pharmaceutical QC departments in Frankfurt and Munich anchor procurement volumes for batch release testing, though EMA bioanalytical guidelines are compressing acceptable resolution thresholds for new method submissions.
- Orbitrap:High-resolution accurate mass systems achieve resolving powers exceeding 100,000 FWHM with mass accuracy below 2 ppm. Basel-based biopharma manufacturers have standardized on these platforms for metabolite identification, pulling demand from legacy quadrupole installations as REACH substance identification requirements tighten.
- Time-of-Flight:TOF analyzers provide rapid full-spectrum acquisition for high-throughput screening applications. Environmental laboratories in the Netherlands deploy these systems for non-targeted contaminant surveillance.
- Ion Trap:Compact benchtop configurations offer multi-stage fragmentation for structural elucidation at moderate cost. Academic research centers in France utilize these platforms for student training and method development.
Quadrupole platforms lead on installed base scale; Orbitrap systems lead on momentum as regulatory resolution thresholds climb.
Application:
Workflow specialization determines instrument configuration, with pharmaceutical and environmental laboratories driving divergent technology requirements across European testing networks.
- Drug Discovery:High-throughput screening and ADMET profiling demand rapid polarity switching and automated sample handling. Irish biopharma manufacturing hubs are expanding LC-MS/MS capacity to support biosimilar development pipelines.
- Environmental Analysis:PFAS monitoring and contaminant traceability require sub-part-per-billion detection limits. ECHA's expanding candidate list of substances of very high concern is accelerating replacement of gas chromatography systems in national reference laboratories across Germany and France.
- Clinical Diagnostics:Therapeutic drug monitoring and newborn screening programs favor robust quadrupole platforms with standardized reagent kits. Hospital laboratories in Denmark are consolidating procurement through multi-year service contracts.
- Proteomics:Bottom-up protein identification and post-translational modification mapping demand Orbitrap resolution. Södertälje-based research institutes anchor regional demand for high-end configurations.
Drug Discovery absorbs the largest share of new instrument expenditure; Environmental Analysis is climbing the fastest as EU Green Deal mandates cascade through member state agencies.
End User:
Facility scale and technical sophistication shape procurement patterns, with large manufacturers separating hardware acquisition from method development services.
- Pharmaceuticals:Quality control and regulatory submission workflows dominate capital deployment. Contract research organizations in the Cambridge cluster are unbundling instrument purchases from validation services, awarding multi-year method development contracts to specialized analytical consultancies.
- Biotechnology:Cell therapy and gene editing applications require specialized sample preparation and ionization techniques. Mid-cap biotechs in Denmark prefer operational expenditure structures over capital-intensive ownership.
- Academic Research:Grant-funded laboratories prioritize flexibility and multi-user accessibility. French national research centers concentrate procurement through centralized funding mechanisms.
- Food & Beverage:Authenticity testing and residue monitoring drive demand for compact quadrupole systems. Customs laboratories in Italy are deploying portable configurations for point-of-need screening.
Pharmaceuticals command the deepest capital pools; Biotechnology is expanding most quickly as advanced therapy manufacturing scales across Northern Europe.
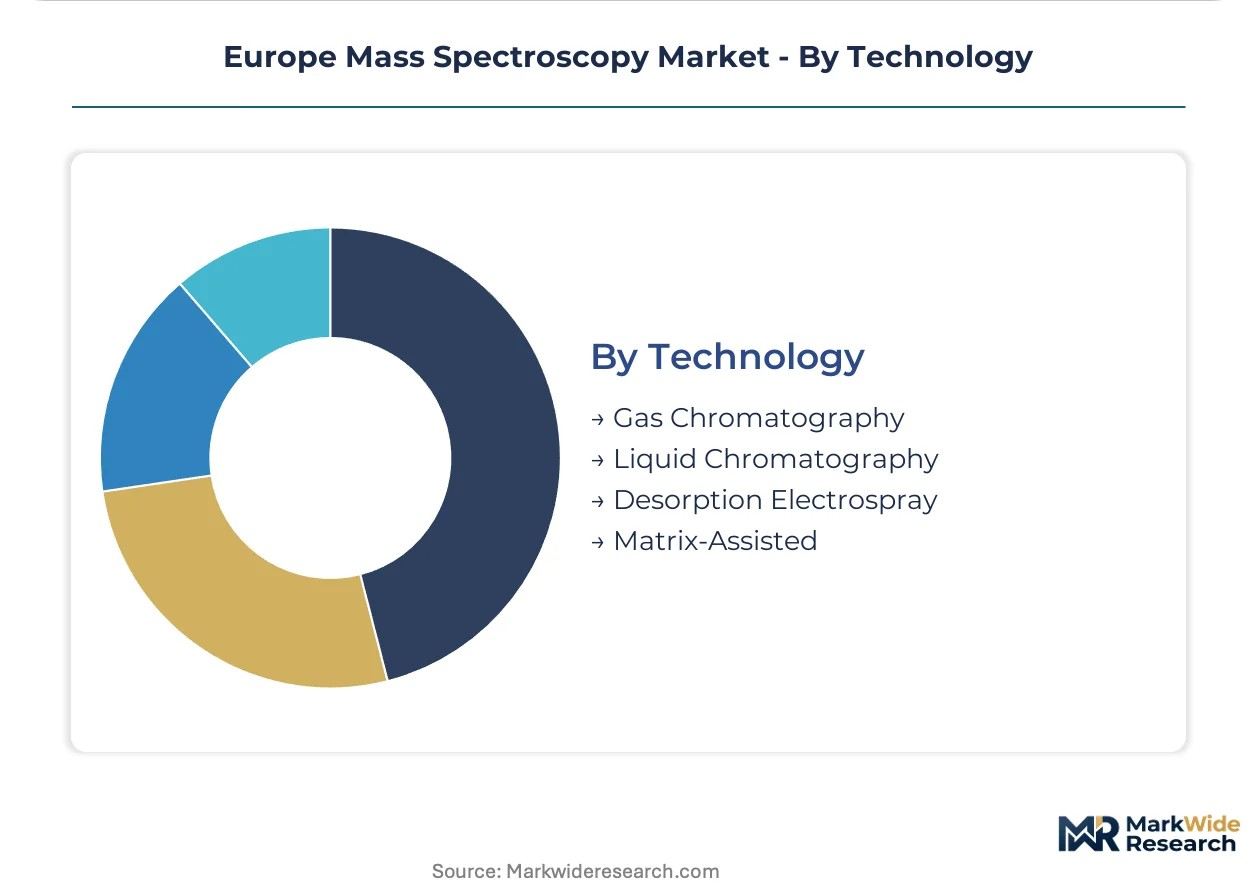
Technology:
Chromatographic coupling and ionization method selection determine analytical scope, with ambient techniques opening laboratory-adjacent deployment models.
- Liquid Chromatography:LC-MS configurations dominate bioanalytical workflows for polar and thermally labile compounds. Waters Corporation sustains competitive positioning through specialized biopharma QC configurations tailored to large molecule analysis.
- Gas Chromatography:GC-MS systems retain installed base in volatile organic compound analysis. Helium supply volatility from Algerian and Russian sources is creating operational uncertainty for electron ionization workflows.
- Desorption Electrospray:Ambient ionization enables direct surface analysis without sample preparation. Food safety applications in Spain are piloting portable DESI-MS systems for customs and border inspection.
- Matrix-Assisted:MALDI-TOF platforms deliver rapid microbial identification and polymer analysis. Clinical microbiology laboratories in Germany are standardizing on these configurations for routine diagnostics.
Liquid Chromatography maintains the broadest application footprint; Desorption Electrospray is gaining share fastest as point-of-need testing models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial laboratories pioneered high-resolution mass spectrometry adoption for pharmaceutical impurity profiling during the 1990s, establishing technical protocols that EMA later codified into bioanalytical validation guidelines.
Germany
Munich and Frankfurt pharmaceutical manufacturing clusters anchor instrument procurement for biosimilar QC workflows. ECHA's REACH substance identification requirements drive retrofitting of industrial testing facilities with accurate mass platforms. Bavarian contract research organizations unbundle hardware purchases from method development services, awarding multi-year validation contracts to specialized analytical consultancies.
France
Parisian national reference laboratories expand LC-MS/MS capacity for environmental contaminant surveillance under EU Green Deal mandates. ANSM clinical testing standards elevate software integrity requirements for hospital-based therapeutic drug monitoring. Île-de-France biopharma manufacturers standardize on Orbitrap configurations for metabolite identification studies.
United Kingdom
Cambridge biotech cluster concentrates demand for high-throughput screening platforms in cell therapy development pipelines. MHRA post-Brexit regulatory divergence creates parallel validation requirements for cross-border pharmaceutical submissions. Greater London contract research organizations consolidate procurement through centralized funding mechanisms.
Netherlands
Rotterdam-Antwerp chemical corridor laboratories deploy ion mobility-quadrupole-TOF systems for REACH dossier compliance in coatings and polymers. ECHA's expanding candidate list of substances of very high concern accelerates replacement schedules for aging gas chromatography infrastructure. Dutch environmental agencies pioneer non-targeted PFAS screening protocols at sub-part-per-billion thresholds.
Switzerland
Basel-based biopharma manufacturers anchor regional demand for proteomics-grade Orbitrap configurations. Swissmedic clinical trial material specifications require mass accuracy below 2 ppm for impurity profiling submissions. Geneva analytical instrument distributors maintain specialized field service capacity for vacuum system maintenance across Alpine peripheral markets.
Europe Mass Spectroscopy Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light service providers for recurring revenue streams in European mass spectrometry markets. The vendor base concentrates around three strategic tiers: diversified life science conglomerates with captive manufacturing footprints, specialized analytical instrument pure-plays with deep application expertise, and regional system integrators with localized service partnerships. Dominant competitive moves include backward integration into ion source component production and geographic expansion through distributor acquisition in Central and Eastern Europe.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify capital deployment strategies that combine hardware manufacturing with consumables lock-in. Waters Corporation occupies a position among application-specialized pure-plays with concentrated biopharma QC positioning. Analytik Jena GmbH & Co. KG represents the regional system integrator archetype, leveraging German manufacturing proximity to anchor service response times for mid-sized environmental laboratories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Waters Corporation |
| Agilent Technologies, Inc. |
| Bruker Corporation |
| Danaher Corporation |
| Analytik Jena GmbH & Co. KG |
| Hiden Analytical |
| Shimadzu Corporation |
| Dani Instruments SpA |
| Others |
Pricing and Supply Chain Analysis
Helium feedstock costs cascade through gas chromatography-mass spectrometry operating economics, compressing margins for laboratories running electron ionization workflows while pushing procurement toward liquid chromatography alternatives that bypass Algerian and Russian supply volatility.
Pricing Analysis
Three-tier pricing structure across premium Orbitrap, standard quadrupole, and economy compact systems anchors capital deployment decisions. Price differentiation rests on resolution specifications and EMA validation support bundling. Cost compression in mid-sized environmental laboratory tiers intensifies because REACH compliance mandates outpace budget allocation. Biotechnology manufacturers show least price sensitivity, prioritizing mass accuracy thresholds for regulatory submissions over capital expenditure minimization.
Supply Chain Analysis
ISO 17025 and EU MDR software integrity certifications gate component sourcing for chromatography data systems and ion source assemblies. Vacuum system manufacturing concentrates in Germany, ion optics fabrication in the United Kingdom, and detector electronics in Switzerland. Raw material dependencies include high-purity helium, specialized ceramic insulators, and precision-machined flight tubes. Single-source vulnerability in superconducting magnet supply for Orbitrap platforms creates procurement risk. Distribution runs through OEM direct sales for pharmaceutical accounts and specialized analytical distributors for environmental laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe mass spectrometry market reads as a late-cycle quality story where EMA bioanalytical guidelines compress acceptable resolution thresholds, forcing replacement of legacy quadrupole systems with premium accurate mass platforms regardless of capital cycle timing.
For Market Incumbents: Acquire specialized field service capacity in Central and Eastern Europe to close response time gaps that disadvantage peripheral market penetration. Backward integration into ion source component production reduces lead time exposure from single-source superconducting magnet suppliers. Defensive positioning requires unbundling hardware sales from method development services before specialized analytical consultancies capture validation contract revenue streams. For New Entrants and Emerging Players: Regional system integrators with Polish and Romanian laboratory partnerships represent the most penetrable channel archetype for compact quadrupole deployment. EU structural fund financing of environmental monitoring infrastructure in accession-heavy regions creates first-mover positioning before incumbent service networks establish presence. Go-to-market execution should emphasize operational expenditure structures over capital-intensive ownership models for mid-cap biotech accounts. For Investors and Strategic Acquirers: Consolidation pressure builds where service engineer scarcity concentrates maintenance revenue with OEM-trained technicians in Germany, France, and the United Kingdom. Long-term viability favors platforms capable of sub-ppm mass accuracy as regulatory resolution thresholds climb irreversibly. Acquisition targets should display deep application expertise in proteomics or metabolomics workflows rather than generic hardware manufacturing capability. Watch for ECHA candidate list expansion velocity as inflection indicator for non-targeted screening demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ion Source Production | Captive supply of electrospray and MALDI components insulates Thermo Fisher's Bremen manufacturing from external lead time volatility. |
| Service Network Expansion in Poland and Romania | Localized vacuum system maintenance partnerships capture EU structural fund flows into environmental laboratory buildouts. |
| Orbitrap Platform Standardization for Biopharma QC | Basel and Södertälje manufacturers validate metabolite identification workflows that compress acceptable resolution thresholds industry-wide. |
| Desorption Electrospray Miniaturization | Ambient ionization convergence enables point-of-need deployment for Spanish food safety customs applications beyond traditional laboratory boundaries. |
| Software Integrity Certification Investment | EU MDR and 21 CFR Part 11 compliance capabilities differentiate chromatography data system vendors for hospital therapeutic drug monitoring contracts. |
Research Methodology
Bottom-up pharmaceutical and environmental laboratory procurement modeling reconciled against top-down instrument manufacturer shipment tracking forms the analytical core of this study. Primary interviews with bioanalytical method validation leads, environmental agency laboratory directors, contract research organization procurement managers, and OEM field service engineers combined with secondary validation from EMA guideline documents, ECHA substance identification technical guidance, SEC 10-K instrument revenue disclosures, and EU structural fund allocation databases. Triangulation across these sources resolves discrepancies between reported installation base and actual utilization rates.
Historical instrument replacement cycle analysis informs projection framework construction across the analysis window. Segmentation dimensions modeled include product platform resolution tier, application workflow regulatory intensity, end-user facility scale, and chromatographic coupling configuration. CAGRs derive from weighted average of bottom-up demand aggregation and top-down manufacturer capacity planning disclosures. Industry-specific forecast inputs incorporate ECHA candidate list expansion schedules and EMA bioanalytical guideline revision timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to helium supply disruption severity and REACH substance identification requirement expansion scope. Projections reflect assumptions regarding regulatory enforcement consistency and laboratory capital budget allocation stability. A model refresh is warranted upon material change in ECHA substance notification deadline schedules or EMA bioanalytical validation protocol harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
ICP-OES Spectrometer Market