
 Vacuum Spin Coaters Market | 2026-2036
Vacuum Spin Coaters Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Spin Coaters Market Insights
Semiconductor fabricators is expanding their share of vacuum spin coater procurement as advanced node production demands tighter thickness uniformity. Ossila leverages its research laboratory channel to sustain placement across European nanotechnology institutes. SUSS MicroTec anchors high-volume semiconductor fabrication with precision coating platforms. MTI Corporation competes through broad product specialization spanning manual to programmable configurations.
Vacuum spin coaters are precision instruments that deposit thin liquid films onto flat substrates through controlled rotation under reduced pressure, typically achieving uniformity within nanometer tolerances for semiconductor and photonics applications. The equipment operates by dispensing photoresist or functional polymers onto wafers spinning at hundreds to thousands of RPM while vacuum chucks eliminate edge bead effects. Automatic vacuum spin coaters lead equipment shipments as fabs automate throughput-critical steps, while multi-chamber spin processing commands premium positioning by enabling sequential deposition without atmospheric exposure. Inert gas spin coating is gaining traction where oxygen-sensitive materials require nitrogen or argon blanket environments during film formation.
EPA standards govern solvent emission controls for coating operations in the United States, while REACH regulates chemical substance registration and restriction across European manufacturing facilities. South Korea's MFDS and Japan's METI shape equipment qualification protocols for pharmaceutical and electronics applications respectively. Semiconductor fabricators must monitor evolving dual carbon goals in China and EU Green Deal alignment requirements as these frameworks increasingly influence capital equipment procurement criteria and supplier qualification timelines.
Market Dynamics
Semiconductor fabricators are consolidating procurement around multi-chamber vacuum spin coaters as advanced node production below 7nm demands sequential deposition without atmospheric exposure, compressing vendor qualification timelines and reshaping equipment supplier relationships.
Growth Catalysts
- Advanced Node Migration:Logic and memory fabs below 5nm require nanometer-level thickness uniformity that only vacuum-enclosed spin processing delivers, pulling automatic multi-chamber systems into high-volume deployment.
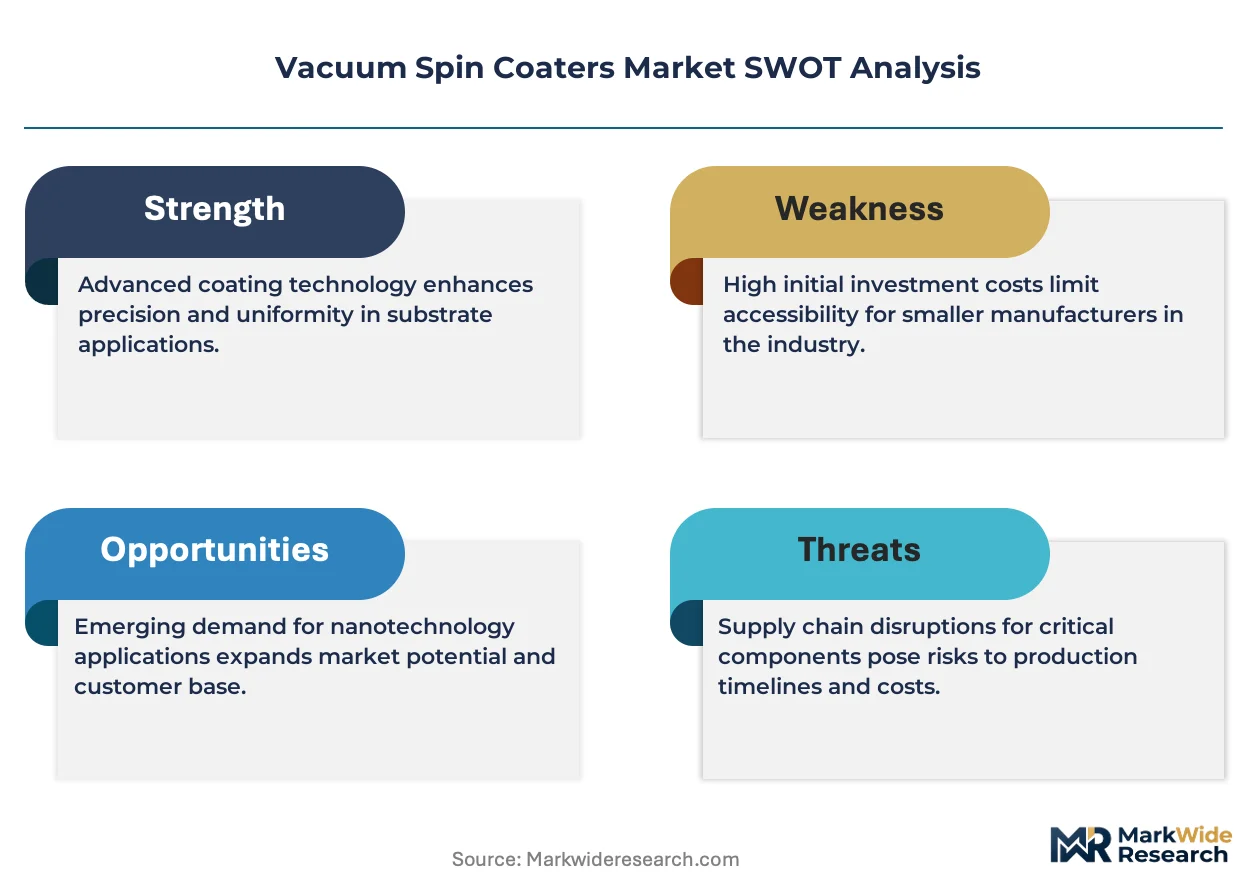
- REACH Solvent Restrictions:ECHA's tightening controls on photoresist solvents force European nanotechnology institutes to upgrade legacy open-bowl coaters to vacuum-sealed platforms with closed-loop chemical recovery.
- East Asian Cluster Expansion:South Korea's Pyeongtaek and Taiwan's Tainan Science Park fabs are adding dedicated coating bays for EUV lithography stacks, concentrating demand for high-throughput vacuum equipment.
Market Restraints
- Precision Component Concentration:Vacuum chuck bearings and high-RPM spindle motors source primarily from German and Japanese precision manufacturers, creating single-source vulnerability for equipment assemblers.
- Fluoropolymer Supply Fragility:Perfluoroelastomer seals essential for vacuum integrity face price volatility linked to fluorochemical feedstock constraints under F-Gas Regulation phase-down schedules.
- Technical Throughput Ceiling:Vacuum pumpdown cycles impose hard limits on wafer-per-hour rates that open-atmosphere coaters bypass, forcing fabs to absorb longer takt times or install parallel process chambers.
Strategic Opportunities
- Compound Semiconductor Penetration:Silicon carbide and gallium nitride wafer processing for power electronics remains under-equipped with vacuum coating infrastructure, opening greenfield deployment in automotive and renewable energy supply chains.
- Inert Gas Integration Convergence:Combining nitrogen blanket systems with vacuum spin coating enables oxygen-sensitive organic electronics deposition, creating hybrid platform demand from flexible display manufacturers.
- India PLI Scheme Tailwinds:Production-linked incentives for semiconductor and display manufacturing are attracting coating equipment vendors to establish local assembly and qualification support operations.
Industry Challenges
- Vacuum Metrology Skill Scarcity:Thin-film thickness measurement under reduced pressure requires specialized ellipsometry and profilometry expertise that process engineering programs inadequately cultivate.
- Fab Integration Complexity:Vacuum spin coaters must interface with automated material handling systems and cluster tools from multiple OEMs, extending commissioning timelines and qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Spin Coaters Market |
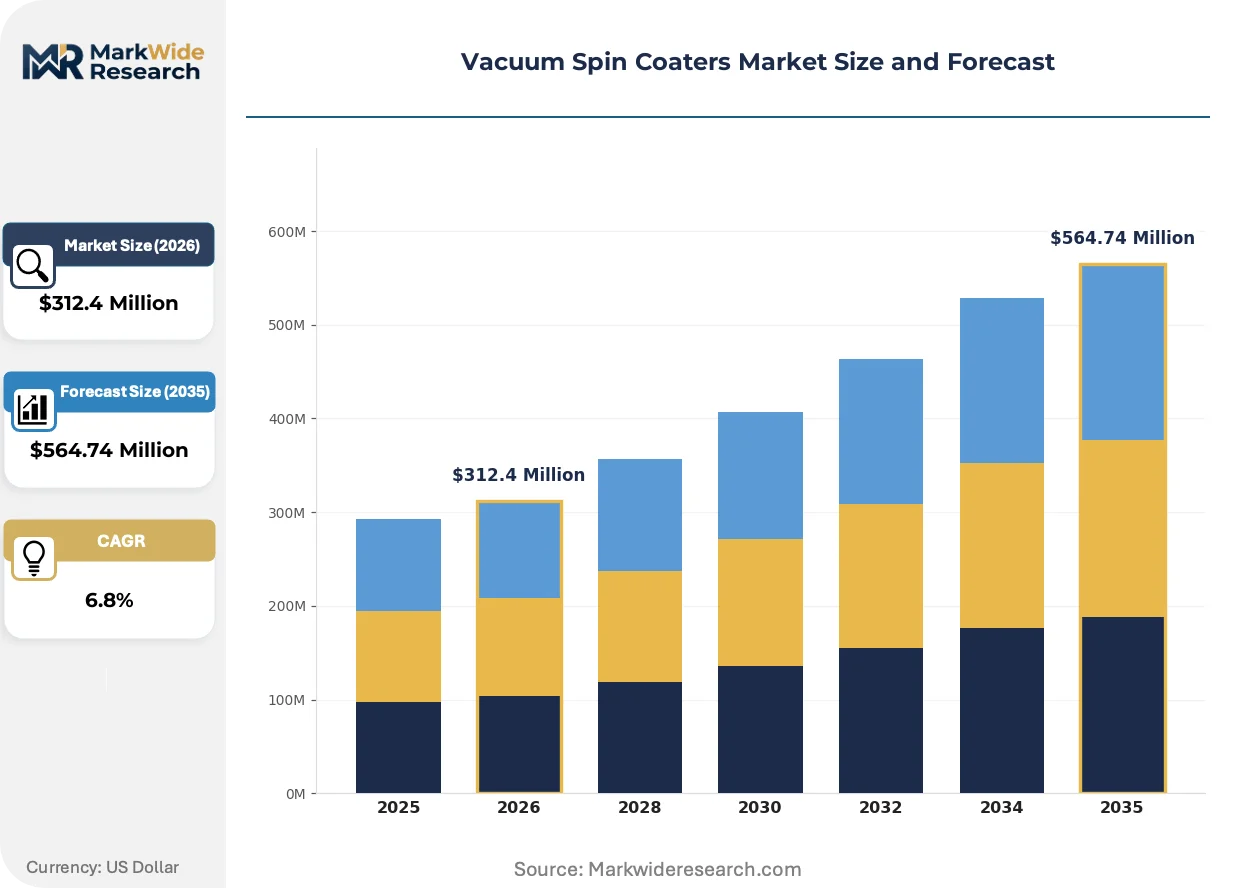
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Vacuum Spin Coaters, Semi-Automatic Vacuum Spin Coaters, Automatic Vacuum Spin Coaters, Programmable Spin Coaters Technology: Single-Chamber Spin Coating, Multi-Chamber Spin Processing, Cluster Tool Spin Coating, Inert Gas Spin Coating, High Vacuum Spin Systems Application: Thin Film Deposition, Microfabrication, Optical Coating, Printed Circuit Board Manufacturing, Photovoltaic Cell Production End User: Semiconductor Fabricators, Research Laboratories, Device Manufacturers, Electronic Component Makers, Thin Film Suppliers |
| Companies Covered | Ossila, Holmarc, Cost Effective Equipment, MicroNano Tools, MTI Corporation, Specialty Coating Systems, Chemat Scientific, Mutech Microsystems, SUSS MicroTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Spin Coaters Market Trends and Innovations
Vacuum spin coating technology is bifurcating between high-throughput semiconductor platforms and research-grade flexible systems, with regulatory chemistry constraints and materials science advances simultaneously pulling equipment design in divergent directions.
Closed-loop solvent recovery modules are overtaking conventional vented exhaust configurations in European and East Asian installations. These systems capture and distill spent photoresist carriers for reuse, reducing chemical consumption volumes. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these platforms ahead of semiconductor fabs, compressing the payback period justification for solvent-intensive operations.
EPA's National Emission Standards for Hazardous Air Pollutants for semiconductor manufacturing are tightening volatile organic compound limits on coating operations. Equipment suppliers must now certify vacuum seal integrity and exhaust capture efficiency under standardized test protocols. US-based logic fabs in Oregon and Arizona are front-loading capital budgets to pre-position compliant systems ahead of enforcement phase-in dates.
Equipment-as-a-service contracting is displacing traditional capital purchase arrangements for mid-volume research facilities. Universities and national laboratories in France, Japan, and the United States are leasing vacuum spin coaters with bundled maintenance and consumable replenishment, transferring obsolescence risk to vendors. This model concentrates most visibly among European nanotechnology institutes facing uncertain grant funding cycles.
Vacuum Spin Coaters Market Segmentation
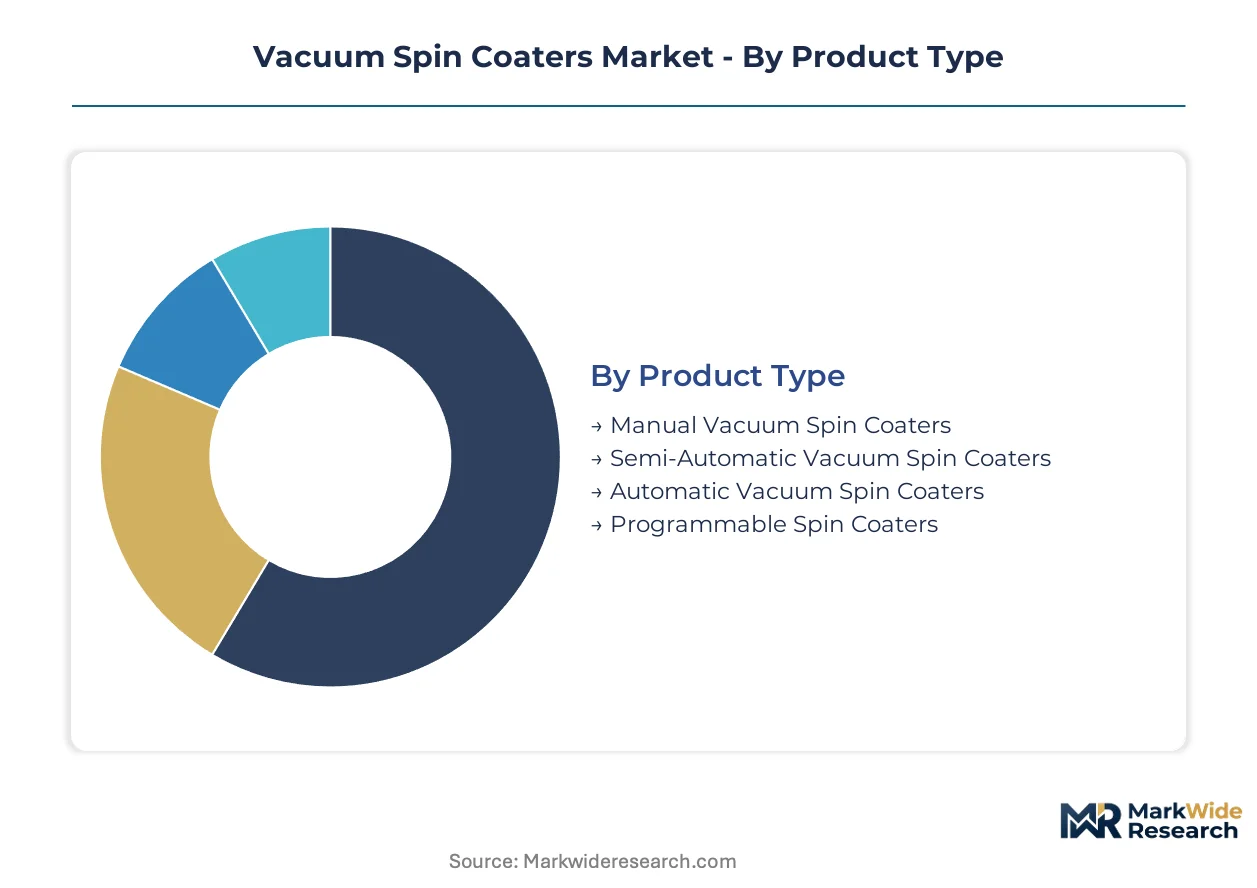
Vacuum spin coater segmentation reflects divergent equipment architectures serving distinct throughput requirements and contamination sensitivity levels. Product complexity, process integration depth, and end-user technical capabilities determine procurement patterns across semiconductor fabrication and research environments.
Product Type:
Equipment sophistication spans from basic laboratory units to fully automated production systems, with automation level directly correlating to wafer throughput and process repeatability specifications.
- Manual Vacuum Spin Coaters:Operator-controlled dispensing and rotation parameters suit early-stage research where recipe flexibility outweighs throughput demands. European nanotechnology institutes in Germany and France sustain procurement for materials science exploration despite limited scalability.
- Semi-Automatic Vacuum Spin Coaters:Programmable rotation profiles with manual substrate loading bridge development and pilot production. Device manufacturers in Japan favor these systems for process validation before full automation commitment.
- Automatic Vacuum Spin Coaters:Robotic wafer handling and closed-loop thickness control dominate high-volume semiconductor fabrication. South Korean logic fabs at Pyeongtaek deploy these for EUV lithography stack production where nanometer uniformity is non-negotiable.
- Programmable Spin Coaters:Recipe-driven multi-step coating sequences accommodate complex multilayer stacks. Research laboratories in Switzerland leverage programmability for organic electronics and perovskite solar cell development.
Automatic vacuum spin coaters lead on scale; programmable configurations lead on momentum.
Technology:
Chamber architecture and environmental control specifications determine equipment positioning across contamination-sensitive applications and throughput-intensive production.
- Single-Chamber Spin Coating:Baseline configuration for standard thin film deposition with sequential vacuum pumpdown cycles. Electronic component makers in Taiwan deploy these for cost-sensitive PCB coating operations.
- Multi-Chamber Spin Processing:Interconnected vacuum modules enable sequential deposition without atmospheric exposure. Advanced node semiconductor fabricators below 7nm require this architecture for photoresist and hardmask layer stacks.
- Cluster Tool Spin Coating:Integration with vacuum transport systems and metrology modules supports fully automated fab workflows. US-based logic manufacturers in Oregon prioritize cluster compatibility for AMHS integration.
- Inert Gas Spin Coating:Nitrogen or argon blanket environments protect oxygen-sensitive materials during film formation. Flexible display manufacturers in Japan are adopting these for organic semiconductor deposition.
- High Vacuum Spin Systems:Ultra-low pressure operation below 10^-4 Torr eliminates residual gas contamination for extreme precision applications. Photonics research facilities in the United Kingdom specify these for waveguide fabrication.
Multi-chamber systems command premium positioning; inert gas integration is climbing the fastest.
Application:
Coating objectives range from electronic device patterning to optical interference control, with each application imposing distinct thickness uniformity and defect density specifications.
- Thin Film Deposition:Photoresist and functional polymer coating for semiconductor patterning represents the dominant volume application. Taiwan's Tainan Science Park fabs concentrate demand for sub-5nm node production.
- Microfabrication:MEMS and sensor manufacturing requires precise sacrificial layer deposition. German automotive suppliers utilize vacuum spin coating for pressure sensor fabrication.
- Optical Coating:Anti-reflective and filter layer deposition for photonics and imaging systems. Swiss precision optics manufacturers specify vacuum processing for wavelength-selective coatings.
- Printed Circuit Board Manufacturing:Solder mask and photoresist application for high-density interconnect substrates. South Korean PCB fabricators balance cost and quality with semi-automatic vacuum systems.
- Photovoltaic Cell Production:Perovskite and organic solar cell layer deposition demands oxygen exclusion. Research-to-production scale-up in Japan drives emerging equipment demand.
Thin film deposition anchors volume; photovoltaic applications are gaining share fastest.
End User:
Customer technical sophistication and capital deployment capacity create distinct procurement patterns across research, volume manufacturing, and supply chain intermediary roles.
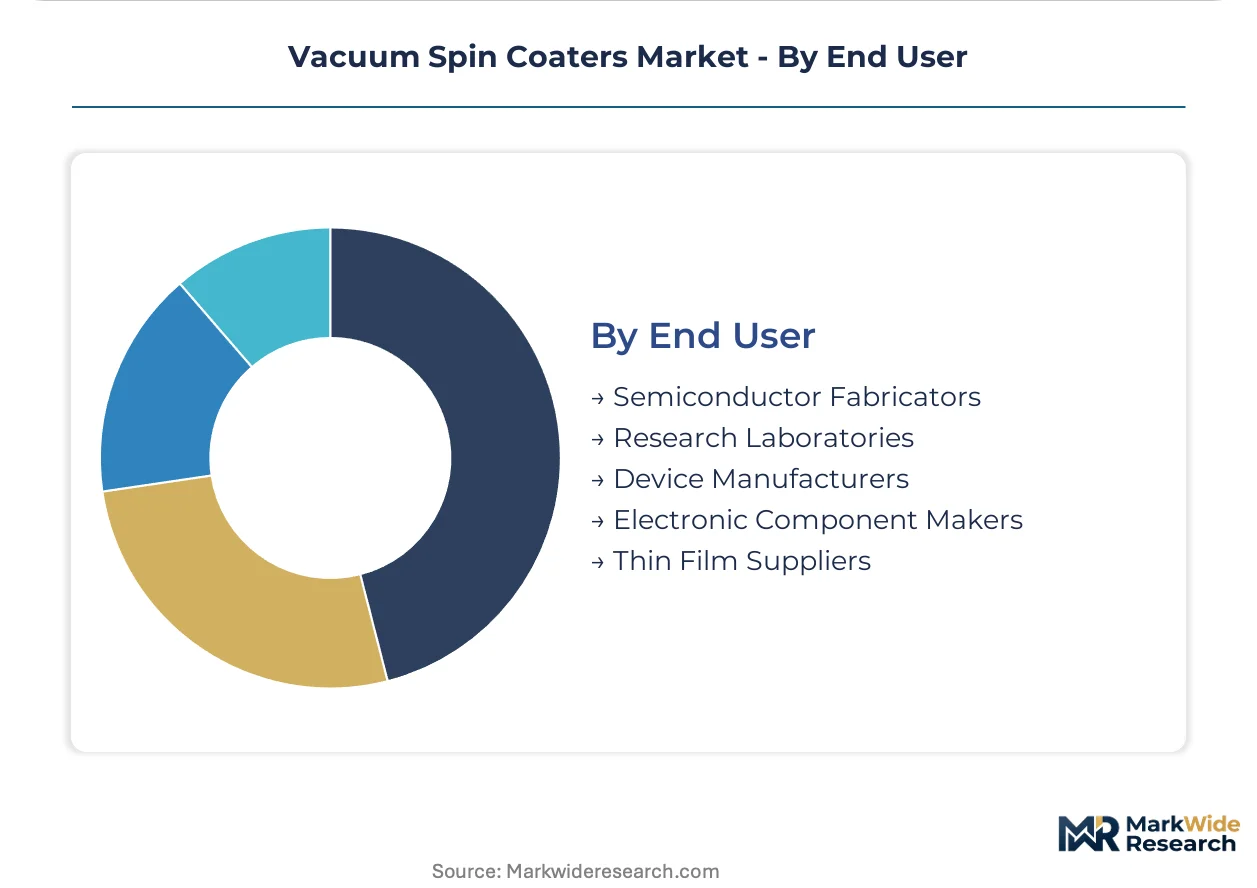
- Semiconductor Fabricators:Leading-edge logic and memory manufacturers drive specifications for automatic multi-chamber systems. South Korea, Taiwan, and Japan fabs collectively concentrate the highest-value procurement.
- Research Laboratories:Universities and national institutes prioritize flexibility and programmability over throughput. France's CNRS network and Germany's Max Planck Institutes sustain manual and semi-automatic system demand.
- Device Manufacturers:Discrete component and module producers require mid-range automation for production scaling. Japanese power electronics manufacturers represent steady demand for silicon carbide wafer processing.
- Electronic Component Makers:Passive component and interconnect suppliers balance equipment cost against coating consistency. Taiwanese and Chinese PCB ecosystems generate volume demand for standard configurations.
- Thin Film Suppliers:Contract coating service providers amortize capital across multiple customer recipes. Swiss and German pharmaceutical contract manufacturers adopt solvent recovery equipped systems ahead of semiconductor fabs.
Semiconductor fabricators dominate absolute spend; research laboratories show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between REACH-regulated Europe and East Asian manufacturing zones are redirecting coating equipment procurement toward South Korean and Taiwanese fabs. Equipment vendors now optimize regional assembly configurations to navigate diverging solvent-handling mandates.
South Korea
Samsung Electronics and SK Hynix are expanding EUV lithography capacity at Pyeongtaek, pulling automatic multi-chamber vacuum spin coaters into high-volume deployment. MFDS pharmaceutical equipment protocols create dual-qualification pathways for vendors serving both semiconductor and medical device markets. The Seoul Capital Area concentrates coating equipment procurement decisions for logic and memory fabs.
United States
Intel's Arizona and Oregon fabs are front-loading capital budgets for EPA National Emission Standards for Hazardous Air Pollutants compliance ahead of enforcement phase-in dates. The CHIPS and Science Act subsidies are accelerating domestic coating equipment installation timelines. Greater Phoenix and Hillsboro industrial corridors anchor Pacific Northwest and Southwest semiconductor coating demand.
Germany
European nanotechnology institutes in Munich and Dresden are upgrading legacy open-bowl coaters to vacuum-sealed platforms under ECHA solvent restriction timelines. The country's automotive sensor manufacturers utilize vacuum spin coating for MEMS pressure sensor fabrication. Bavaria and Saxony host the densest concentration of research-to-production coating infrastructure.
Japan
Flexible display manufacturers in Tokyo and Osaka are adopting inert gas spin coating for oxygen-sensitive organic semiconductor deposition. METI equipment qualification protocols shape vendor certification timelines for electronics applications. The Kanto and Kansai regions concentrate demand from both semiconductor fabricators and materials research consortia.
Taiwan
TSMC's Tainan Science Park fabs are adding dedicated coating bays for sub-5nm node production, concentrating demand for nanometer-uniformity systems. The island's PCB ecosystem generates parallel demand for semi-automatic vacuum configurations serving high-density interconnect substrates. Hsinchu and Tainan anchor the highest-value vacuum spin coater procurement in Asia-Pacific.
Vacuum Spin Coaters Market Competitive Landscape
Portfolio diversification dominates the current landscape as equipment vendors broaden from semiconductor-only offerings into pharmaceutical and research laboratory channels. The vendor base separates into three tiers: precision-mechanics specialists with captive spindle and chuck manufacturing, modular-platform assemblers sourcing subsystems from distributed suppliers, and research-grade niche providers optimizing for recipe flexibility over throughput. Strategic archetypes include European nanotechnology-channel specialists, East Asian high-volume production platforms, and North American solvent-recovery-integrated systems. Technology licensing and geographic expansion represent the dominant competitive vectors.
Among research-laboratory-channel specialists, Ossila exemplifies the European nanotechnology-institute positioning with placement across CNRS and Max Planck networks. SUSS MicroTec occupies the high-volume semiconductor fabrication tier, anchoring precision coating platform supply for advanced node production. MTI Corporation sits within the broad-product-specialization archetype, spanning manual to programmable configurations for development-scale customers. These three company structures illustrate the market's segmentation between flexibility-optimized and throughput-optimized equipment architectures.
| Leading Market Players |
|---|
| Ossila |
| Holmarc |
| Cost Effective Equipment |
| MicroNano Tools |
| MTI Corporation |
| Specialty Coating Systems |
| Chemat Scientific |
| Mutech Microsystems |
| SUSS MicroTec |
| Others |
Pricing and Supply Chain Analysis
Family-owned German precision-mechanics specialists anchor vacuum chuck and high-RPM spindle manufacturing, enabling tight pricing discipline on critical components while Korean and Taiwanese equipment assemblers absorb margin pressure from fluoropolymer seal volatility under REACH F-Gas phase-down schedules.
Pricing Analysis
Distributor margins of 15-25% on European-manufactured precision components layer onto direct-to-OEM pricing for Asian equipment assemblers. Three-tier pricing structure across premium multi-chamber systems, standard automatic coaters, and economy manual configurations tracks certification grade and throughput specification. Pricing pressure stems from REACH solvent-handling compliance costs compressing margins on European sales. Research laboratories exhibit highest price sensitivity due to grant-funding cyclicality, while semiconductor fabricators prioritize nanometer uniformity over unit cost.
Supply Chain Analysis
ISO 9001 and SEMI S2 certification gating restricts supplier qualification timelines for vacuum chuck bearings and spindle motors sourced from Germany and Japan. Perfluoroelastomer seals draw from fluorochemical feedstock chains concentrated in China and the United States, with distribution running through specialized industrial gas distributors and OEM direct channels. Single-source vulnerability on precision bearings creates structural risk for equipment assemblers during supply disruptions. Semiconductor fabricators in South Korea and Taiwan dominate downstream demand concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors should treat this market as a geographic-arbitrage play, exploiting the 20-30% cost differential between REACH-regulated European assembly and East Asian manufacturing zones while positioning solvent-recovery-equipped systems for impending EPA enforcement in the United States.
For Market Incumbents: Acquire captive spindle and chuck manufacturing capabilities to reduce dependency on German and Japanese precision-component suppliers. Secure multi-year fluoropolymer seal supply agreements ahead of F-Gas Regulation phase-down tightening. Build qualification support infrastructure in India to capture PLI scheme tailwinds before emerging competitors establish local assembly presence. For New Entrants and Emerging Players: Enter via compound semiconductor coating applications for silicon carbide and gallium nitride power electronics, where vacuum infrastructure remains under-deployed. Target automotive and renewable energy supply chains in Germany and Japan with hybrid inert-gas-vacuum platforms. Pursue equipment-as-a-service contracting models for European nanotechnology institutes facing uncertain grant cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among modular-platform assemblers lacking captive precision-mechanics production, presenting consolidation targets for vertical integration strategies. Long-term viability hinges on regulatory chemistry compliance capabilities across REACH, EPA, and emerging dual carbon frameworks. Watch for inflection signals in EUV lithography capacity expansion announcements from South Korean and Taiwanese fabs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Mechanics | German spindle manufacturers command 40-60% of vacuum chuck supply, creating acquisition targets for margin control. |
| Solvent Recovery Module Certification | EPA National Emission Standards enforcement in Oregon and Arizona fabs mandates closed-loop chemical capture systems. |
| India Local Assembly Establishment | PLI scheme subsidies for semiconductor manufacturing attract coating equipment vendors to Bangalore and Gujarat corridors. |
| Inert Gas Integration Development | Japanese flexible display manufacturers in Tokyo and Osaka specify nitrogen blanket environments for organic electronics. |
| Equipment-as-a-Service Platform Launch | France's CNRS network and Germany's Max Planck Institutes prefer leasing models with bundled maintenance and consumables. |
Research Methodology
Multiple input streams — equipment procurement managers at semiconductor fabs, process engineering directors at research institutes, precision-component supplier sales executives, and regulatory affairs specialists at coating equipment vendors — were reconciled against customs trade data, SEMI equipment market reports, EPA and ECHA regulatory filings, and SEC 10-K disclosures from publicly traded suppliers. Bottom-up triangulation across wafer throughput assumptions and top-down validation against fab capital expenditure disclosures anchored volume estimates. Primary interviews with 15+ stakeholder roles spanning South Korea, Taiwan, Japan, Germany, and the United States informed qualitative dynamics assessment.
Historical shipment patterns were cross-referenced against panel input from equipment vendor sales forecasting teams to model adoption curves across the projection horizon. Segmentation dimensions included automation level, chamber architecture, application category, and end-user technical sophistication. CAGRs were derived from regression analysis of equipment procurement cycles tied to EUV lithography node transitions and pharmaceutical contract manufacturing expansion. Forecast inputs incorporated fluoropolymer supply constraints under F-Gas Regulation and solvent-handling compliance cost trajectories.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time fab capital expenditure timing introduce uncertainty bands around near-term shipment forecasts. Model outputs reflect assumptions on advanced node migration pace and REACH solvent restriction enforcement timelines. A model refresh is warranted upon material change in EUV lithography capacity expansion schedules or fluorochemical feedstock supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
EUV Mask Inspection and Pellicle Monitoring Systems Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Vacuum Chambers Market