

4-Inch SiC Laser Annealing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
4-Inch SiC Laser Annealing Equipment Market Insights
Electric vehicle powertrain engineering is recalibrating procurement priorities toward SiC substrates that withstand higher thermal loads than silicon alternatives. Applied Materials leverages its installed base of ion implantation tools to cross-sell laser annealing modules into compound semiconductor fabs. Tokyo Electron anchors its position through deep relationships with Japanese SiC wafer producers expanding 4-inch pilot lines. SCREEN Semiconductor Solutions competes on precision thermal control algorithms that reduce crystal defect density during dopant activation.
4-Inch SiC laser annealing equipment employs high-energy laser beams to activate implanted dopants in silicon carbide wafers without thermal damage to the crystal lattice, typically operating at wavelengths from ultraviolet through infrared with peak temperatures exceeding 2,000°C for millisecond durations. Continuous wave lasers dominate current installations due to mature beam stability and throughput economics, while pulsed lasers represent the fastest-growing product type as manufacturers seek finer thermal budget control for next-generation trench MOSFET architectures. UV laser annealing captures premium pricing in power device applications where shallow junction depths demand minimal diffusion, and hybrid annealing configurations are gaining traction among compound semiconductor manufacturers balancing throughput with defect reduction.
The EU Green Deal and REACH chemical safety protocols shape equipment material specifications and cleanroom compliance costs for European-bound tool shipments. Japan's METI subsidizes domestic SiC supply chain buildout through its semiconductor revitalization framework, directly stimulating capital equipment demand from Tokyo Electron and Hitachi High-Tech customers. China's MIIT mandates GB standards compliance for imported laser processing tools, creating certification barriers that favor localized service footprints. Stakeholders must weigh concentrated East Asian demand against geopolitical tooling restrictions when allocating R&D resources and regional support infrastructure.
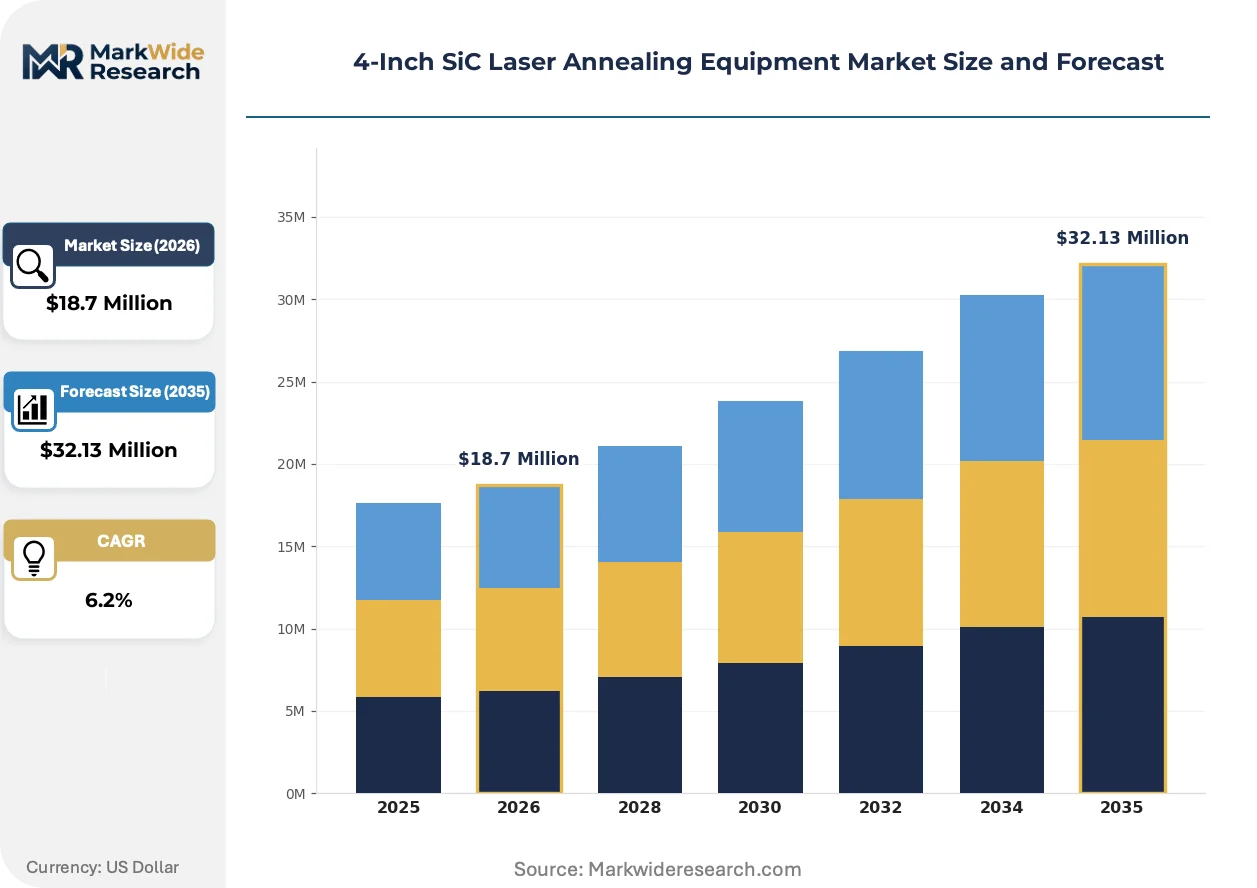
Market Dynamics
EV powertrain voltage architectures are shifting from 400V to 800V systems, forcing SiC device manufacturers to prioritize defect-free dopant activation that only advanced laser annealing can deliver at scale.
Growth Catalysts
- China's dual carbon goals:Beijing's emissions mandates accelerate SiC adoption in grid-tied inverters and traction inverters, directly stimulating capital equipment procurement from domestic fabs.
- 800V battery platforms:Automotive OEMs specify SiC MOSFETs for reduced switching losses, requiring millisecond thermal processing that laser annealing uniquely provides.
- East Asian manufacturing clusters:Concentrated wafer fabrication in Japan, South Korea, and Taiwan creates localized demand density for 4-inch pilot line tools.
Market Restraints
- High-purity SiC substrate shortages:Limited availability of low-defect 4-inch boules from Wolfspeed and Coherent constrains downstream equipment utilization rates.
- Import certification barriers:China's MIIT mandates GB standards compliance for laser processing tools, extending deployment timelines by 6-12 months for non-domestic vendors.
- Technical throughput ceilings:Current pulsed laser systems process 15-20 wafers per hour versus 60+ for silicon annealing, creating cost-per-wafer disadvantages at volume.
Strategic Opportunities
- India's semiconductor PLI scheme:New Delhi's production-linked incentives for compound semiconductor fabs create first-mover advantages for equipment vendors establishing local service infrastructure.
- Hybrid annealing configurations:Combining continuous-wave and pulsed laser modules enables single-tool flexibility across power device and RF device process flows.
- EU Green Deal compliance:REACH chemical safety protocols favor laser annealing over thermal furnace processing, eliminating hazardous gas handling in European-bound production lines.
Industry Challenges
- Process engineer scarcity:Compound semiconductor thermal processing expertise concentrates among veterans of Japanese and Taiwanese fabs, constraining expansion into emerging manufacturing regions.
- Integration complexity with legacy ion implantation tools:Mismatched wafer handling interfaces between 1990s-era implanters and modern laser annealing chambers require costly fab floor reconfiguration.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Inch SiC Laser Annealing Equipment Market Trends and Innovations
Laser wavelength optimization and beam shaping algorithms are redefining thermal budget precision, enabling device architectures previously impossible with conventional furnace processing.
Pulsed excimer laser annealing is overtaking continuous-wave systems in trench MOSFET fabrication. These UV sources activate shallow boron implants with sub-10 nanometer junction depth control. Automotive power module manufacturers in Japan and Germany now specify pulsed tools for next-generation inverter chips. The technology is overtaking incumbent thermal methods by eliminating extended high-temperature exposure that degrades SiC crystal quality.
The EU F-Gas Regulation is phasing out sulfur hexafluoride and fluorinated greenhouse gases used in plasma-based annealing alternatives. Equipment vendors must certify laser systems as fluorine-free process replacements to maintain CE marking eligibility. German and French power semiconductor fabs are accelerating laser annealing evaluations to preempt 2027 compliance deadlines.
Consolidated procurement through semiconductor foundry alliances is displacing individual fab equipment purchasing. Taiwan-based pure-play foundries now negotiate enterprise-wide laser annealing tool contracts covering multiple 4-inch pilot lines. This model concentrates vendor selection authority with procurement teams in Hsinchu and Tainan, compressing sales cycles for approved suppliers while raising barriers for new market entrants.
4-Inch SiC Laser Annealing Equipment Market Segmentation
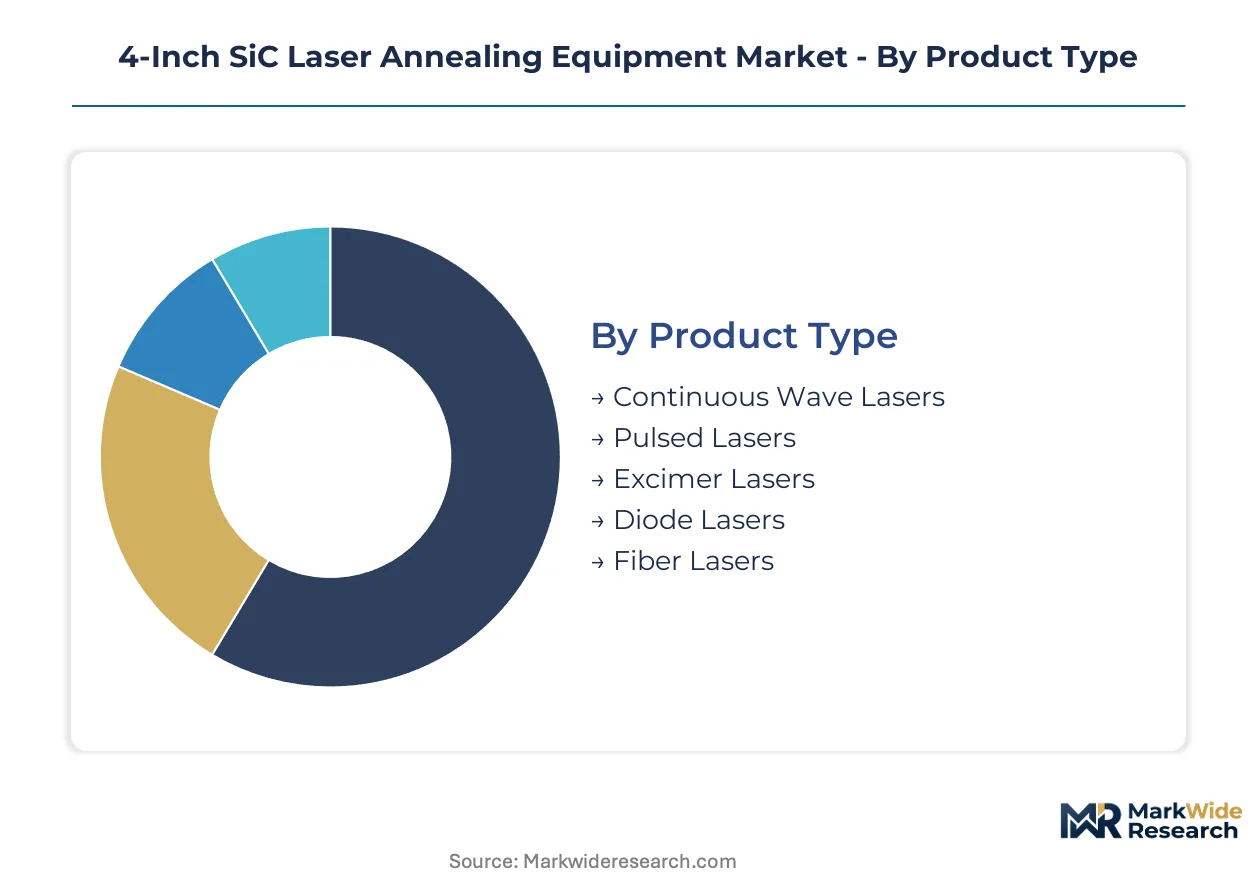
Segmentation reveals how 4-inch SiC laser annealing equipment aligns with distinct thermal processing requirements across device architectures and manufacturing scales. Equipment buyers prioritize wavelength precision, throughput economics, and integration compatibility with existing ion implantation workflows.
Product Type:
Procurement decisions hinge on thermal budget control versus wafer throughput trade-offs.
- Continuous Wave Lasers:Deliver stable beam output for high-volume dopant activation in power MOSFET fabrication. Japanese SiC foundries in Kumamoto and Kagoshima specify these systems for 24/7 production lines where uptime economics dominate capital planning.
- Pulsed Lasers:Generate millisecond-duration energy bursts that limit thermal diffusion in shallow junction architectures. Trench MOSFET manufacturers in Germany's Saxony cluster and Taiwan's Hsinchu Science Park are converting pilot lines to pulsed configurations for next-generation 800V automotive devices.
- Excimer Lasers:UV gas discharge systems enabling sub-10 nanometer junction depth control for RF power amplifiers.
- Diode Lasers:Compact solid-state sources integrating into clustered tool configurations for research-scale fabs.
- Fiber Lasers:Ytterbium-doped architectures offering beam delivery flexibility for multi-chamber processing setups.
Continuous wave systems lead on installed base scale; pulsed configurations lead on technology transition momentum.
Application:
Device performance specifications dictate laser wavelength and annealing duration requirements.
- Power Devices:SiC MOSFETs and Schottky diodes require millisecond-range thermal processing to activate implanted aluminum and nitrogen dopants without degrading crystal quality. EV inverter manufacturers in South Korea's Giheung complex and China's Shenzhen corridor are qualifying laser-annealed chips for 800V traction systems.
- Radio Frequency Components:High-electron-mobility transistors and MMICs demand sub-micron junction control achievable only through UV laser systems. Defense and 5G base station suppliers in the US and Japan specify these processes for gallium nitride-on-SiC integration.
- Sensors:High-temperature pressure and gas sensors for aerospace applications.
- MEMS Fabrication:Piezoelectric actuator annealing for automotive and medical devices.
- Optoelectronics:UV LED and laser diode contact formation on SiC substrates.
Power devices command the largest equipment procurement volumes; RF components are expanding most quickly with 5G and radar system deployments.
Technology:
Equipment architecture selection follows substrate absorption characteristics and junction depth targets.
- UV Laser Annealing:308nm and 351nm excimer wavelengths enable surface-confined heating with minimal bulk crystal disturbance. Premium pricing reflects specialized optics and gas handling systems required for power device shallow junction fabrication.
- Hybrid Annealing:Combines continuous-wave preheating with pulsed laser spike annealing in single-platform configurations. Compound semiconductor manufacturers in Taiwan and Japan adopt these tools to process diverse device portfolios without chamber changeover downtime.
- Green Laser Annealing:532nm frequency-doubled Nd:YAG systems for intermediate absorption depth control.
- Infrared Laser Annealing:1064nm and 1550nm sources for deep junction activation in high-voltage drift layers.
- Laser Thermal Processing:Broad-category systems integrating beam shaping and real-time pyrometry for closed-loop temperature control.
UV laser systems lead on process precision; hybrid configurations are gaining share fastest among diversified compound semiconductor foundries.
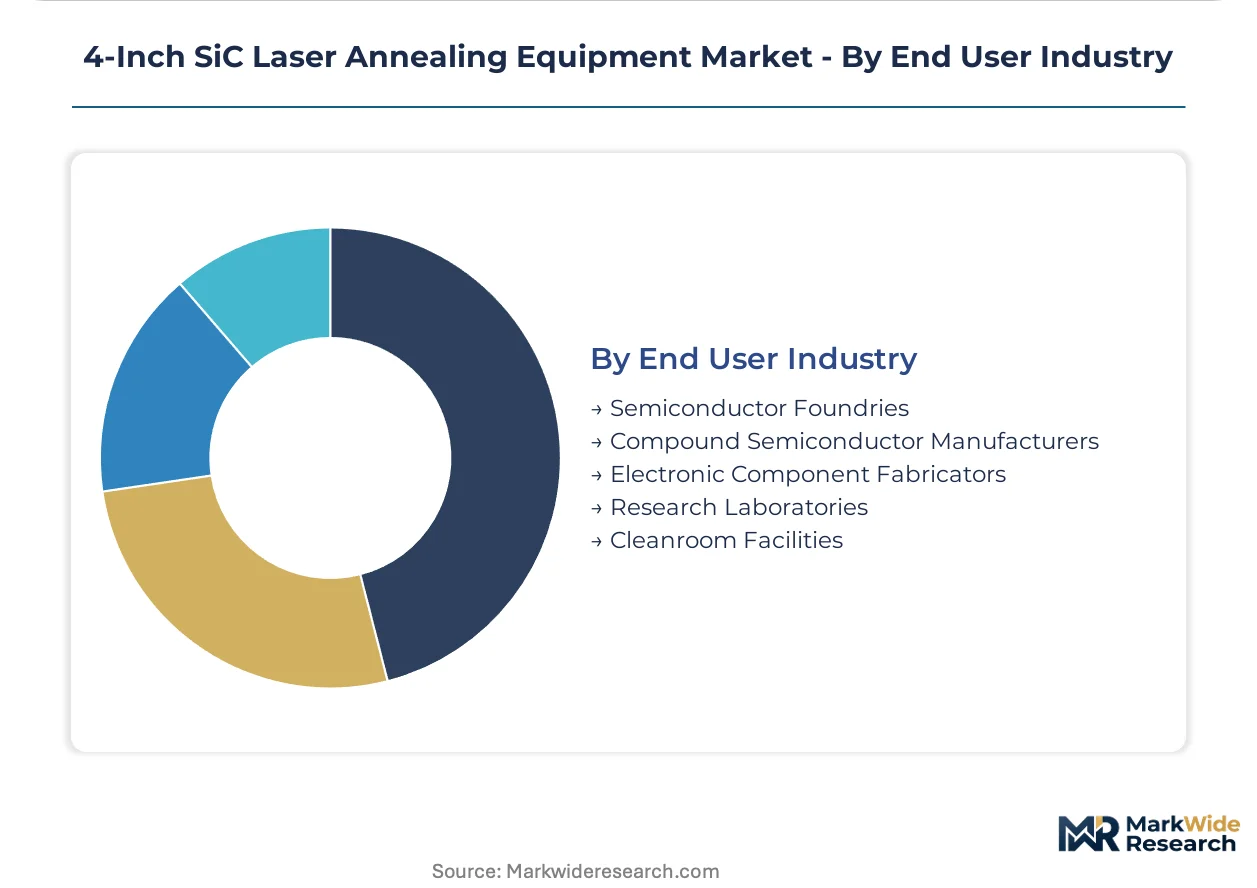
End User Industry:
Facility scale and process maturity determine equipment configuration complexity and service support requirements.
- Semiconductor Foundries:Pure-play SiC fabs in Taiwan, Japan, and South Korea operate multi-tool fleets with standardized process recipes. These buyers negotiate enterprise service agreements covering predictive maintenance and consumables logistics across multiple 4-inch pilot lines.
- Compound Semiconductor Manufacturers:Integrated device manufacturers in Europe and North America combine SiC power device production with III-V optoelectronic fabrication. Their equipment purchases emphasize chamber flexibility and rapid recipe switching between material systems.
- Electronic Component Fabricators:Discrete device specialists serving industrial and automotive tier-two suppliers.
- Research Laboratories:University and national lab facilities developing next-generation device architectures.
- Cleanroom Facilities:Shared research infrastructure serving multiple institutional users with diverse process requirements.
Semiconductor foundries lead on capital deployment scale; compound semiconductor manufacturers are expanding procurement most aggressively with vertical integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kumamoto's SiC wafer fabrication corridor anchors equipment demand as Japanese foundries expand 4-inch pilot capacity. Equipment procurement concentrates in East Asian manufacturing clusters where substrate producers and device fabricators co-locate. Regulatory frameworks in major semiconductor economies are accelerating capital deployment timelines through targeted subsidies and emissions mandates.
Japan
Tokyo Electron and Hitachi High-Tech anchor domestic supply chains serving Kumamoto and Kagoshima SiC clusters. METI's semiconductor revitalization framework subsidizes capital equipment purchases for compound semiconductor fabs. Foundries in Kyushu are converting legacy silicon lines to SiC processing, driving laser annealing tool demand for 800V automotive qualification programs.
China
Shenzhen and Suzhou corridor fabs are scaling SiC MOSFET output for domestic EV inverter supply chains. MIIT mandates GB standards compliance for imported laser processing equipment, extending deployment timelines for non-domestic vendors. Xiamen and Shanghai-based compound semiconductor facilities are qualifying hybrid annealing configurations under state-backed dual carbon implementation roadmaps.
South Korea
Giheung complex manufacturers are specifying laser-annealed SiC chips for Hyundai-Kia 800V traction systems. The Ministry of Trade, Industry and Energy channels semiconductor R&D funding toward SiC power device commercialization. Busan-Ulsan materials suppliers are integrating upstream with device fabricators, creating localized demand density for thermal processing equipment.
Germany
Saxony's power semiconductor cluster is converting pilot lines to pulsed laser configurations for trench MOSFET fabrication. The EU F-Gas Regulation is phasing out fluorinated greenhouse gases, accelerating laser annealing adoption as furnace replacement. Infineon and Bosch suppliers in Dresden are qualifying UV systems to meet 2027 compliance deadlines while serving automotive OEM 800V platform specifications.
United States
North Carolina's Research Triangle SiC substrate producers are expanding 4-inch boule capacity, constraining downstream equipment utilization rates. The Department of Energy's semiconductor manufacturing incentives support compound semiconductor fab buildout. Wolfspeed's Durham operations are driving thermal processing equipment demand as domestic EV supply chain localization accelerates.
4-Inch SiC Laser Annealing Equipment Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors secure anchor customers in expanding SiC wafer fabs. The vendor base concentrates around ion implantation tool incumbents leveraging installed base relationships for laser annealing module cross-sales. Three archetypes define competitive positioning: diversified semiconductor equipment conglomerates, specialized thermal processing specialists, and substrate producers backward-integrating into process equipment. Technology licensing and geographic expansion represent the dominant competitive vectors as vendors establish localized service footprints to circumvent import certification barriers.
Among diversified equipment conglomerates, Applied Materials and Tokyo Electron exemplify scale-driven positioning through ion implantation tool installed bases. SCREEN Semiconductor Solutions occupies a specialist position emphasizing precision thermal control algorithms. Coherent represents substrate-producer backward integration, leveraging crystal growth expertise to inform annealing process development. These three anchors illustrate how competitive positioning follows upstream supply chain relationships rather than standalone equipment capabilities.
| Leading Market Players |
|---|
| SCREEN Semiconductor Solutions |
| Applied Materials |
| Tokyo Electron |
| ULVAC |
| Veeco Instruments |
| ASM International |
| Hitachi High-Tech |
| Sumitomo Heavy Industries |
| Coherent |
| Others |
Pricing and Supply Chain Analysis
Pulsed laser module adoption across 800V automotive qualification programs simultaneously compresses per-wafer processing costs and concentrates procurement leverage with Japanese and Taiwanese foundry alliances. Equipment vendors face margin pressure as these buyers consolidate enterprise-wide contracts covering multiple 4-inch pilot lines, shifting pricing power toward volume-scale purchasers in Kumamoto and Hsinchu.
Pricing Analysis
Input-cost pass-through from specialized UV optics and ytterbium-doped fiber assemblies shapes contract structures for laser annealing equipment. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked EU-compliant configurations from baseline GB-standard tools for China and uncertified research-grade systems. Cost compression in the standard tier is intensifying because foundry procurement teams negotiate multi-tool fleet discounts with predictive maintenance bundling. Research laboratories exhibit the highest price sensitivity due to capital budget constraints, while automotive-qualified semiconductor foundries prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Taiwan-based pure-play foundries, while distributor networks serve smaller compound semiconductor manufacturers in Europe and North America. Manufacturing concentrates in Japan, Germany, and the United States, with final assembly drawing from precision optics suppliers in Japan and laser source producers in Germany. Single-source vulnerability around high-purity SiC substrates from Wolfspeed and Coherent constrains downstream equipment utilization rates. Distribution runs through regional service hubs that circumvent China's MIIT certification barriers for non-domestic vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on hybrid annealing configurations that command premium positioning while reducing customer total cost of ownership through single-tool flexibility. Equipment vendors capturing this shift will outperform competitors locked in pure continuous-wave or pulsed laser commoditization.
For Market Incumbents: Hedge against pulsed laser commoditization by embedding predictive maintenance algorithms and consumables logistics into long-term service contracts. Secure anchor positions in India's semiconductor PLI scheme before local competitors establish GB-compliant service footprints. Capacity addition in Tamil Nadu and Gujarat creates defensive moats against Chinese import substitution policies. For New Entrants and Emerging Players: European compound semiconductor manufacturers integrating SiC power devices with III-V optoelectronics represent the most penetrable buyer archetype due to unmet demand for rapid recipe-switching flexibility. Hybrid annealing configurations offer entry leverage against entrenched continuous-wave incumbents in Germany's Saxony cluster. A channel partnership strategy with regional integrators bypasses direct certification barriers while building installed base credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized thermal processing algorithm developers without captive ion implantation tool relationships. Long-term viability favors vendors with demonstrated trench MOSFET process qualification at automotive OEMs. Watch for hybrid annealing adoption inflection signals at Taiwan-based foundries managing diverse device portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Annealing Platform Development | Enables single-tool processing of power and RF devices at Taiwan foundries. |
| India PLI Scheme Localization | Establishes GB-alternative service infrastructure for compound semiconductor fabs. |
| EU F-Gas Regulation Compliance Certification | Secures CE marking eligibility as fluorine-free furnace replacement in Germany. |
| Predictive Maintenance Service Contracts | Binds foundry customers through enterprise agreements across multi-tool fleets. |
| Trench MOSFET Process Qualification | Unlocks automotive OEM specification for 800V inverter chip supply chains. |
Research Methodology
Bottom-up fab capacity modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with process engineering directors, fab procurement managers, ion implantation tool specialists, and thermal process R&D leads combined with secondary validation from SEMI equipment market databases, METI subsidy disclosure filings, and EU F-Gas Regulation implementation reports. Top-down triangulation against customs records and foundry capital expenditure announcements ensures consistency across estimation approaches.
Input-output matrices map laser annealing tool deployments to SiC wafer fabrication capacity expansion across the analysis window. Segmentation dimensions include product type, application, technology wavelength, and end-user industry scale. CAGRs derive from equipment unit forecasts reconciled against average selling price trajectories by configuration tier. Forecast inputs incorporate EV platform voltage migration timelines and substrate supply constraints from 4-inch boule producers.
Underlying measurement precision varies by segment; semiconductor foundry procurement data carries tighter precision than research laboratory estimates. Forecasts reflect documented assumptions around EV adoption curves, regulatory compliance deadlines, and substrate supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.