
 Solar Module Production Equipment Market | 2026-2036
Solar Module Production Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Module Production Equipment Market Insights
Software-defined process control is restructuring how equipment vendors monetize their platforms, shifting revenue from one-time hardware sales toward recurring digital service contracts. Applied Materials leverages its semiconductor heritage to dominate advanced deposition tools for heterojunction cell architectures. Meyer Burger anchors its European manufacturing base with proprietary SmartWire interconnection technology that reduces silver consumption. CETC Solar competes aggressively on cost-engineered diffusion furnaces tailored to PERC and TOPCon upgrade cycles.
Solar module production equipment encompasses the integrated machinery systems used to fabricate photovoltaic modules from raw silicon wafers or thin-film substrates, including texturing, doping, metallization, lamination, and testing stations operating at throughputs exceeding 10,000 wafers per hour. Its primary commercial purpose is to enable manufacturers to achieve consistent cell efficiencies above 24% while minimizing breakage rates and material waste across gigawatt-scale fabs. Crystalline silicon equipment still occupies the dominant share of capital expenditure, though bifacial technology lines are capturing disproportionate investment as dual-glass architectures become standard for utility-scale procurement. Thin-film deposition systems sustain niche relevance in building-integrated applications where lightweight flexible substrates outweigh efficiency penalties.
China's MIIT enforces GB standards for module efficiency and factory energy consumption that directly determine which equipment configurations qualify for domestic project tenders. The EU Green Deal's carbon border adjustment mechanism and F-Gas Regulation are reshaping import competitiveness, pushing non-European manufacturers toward low-carbon process upgrades to maintain market access. India's PLI scheme and BIS certification requirements are creating parallel compliance pathways that favor locally sourced production tools. Stakeholders must monitor how divergent regional certification regimes fragment equipment standardization and influence vendor selection criteria across major manufacturing hubs.
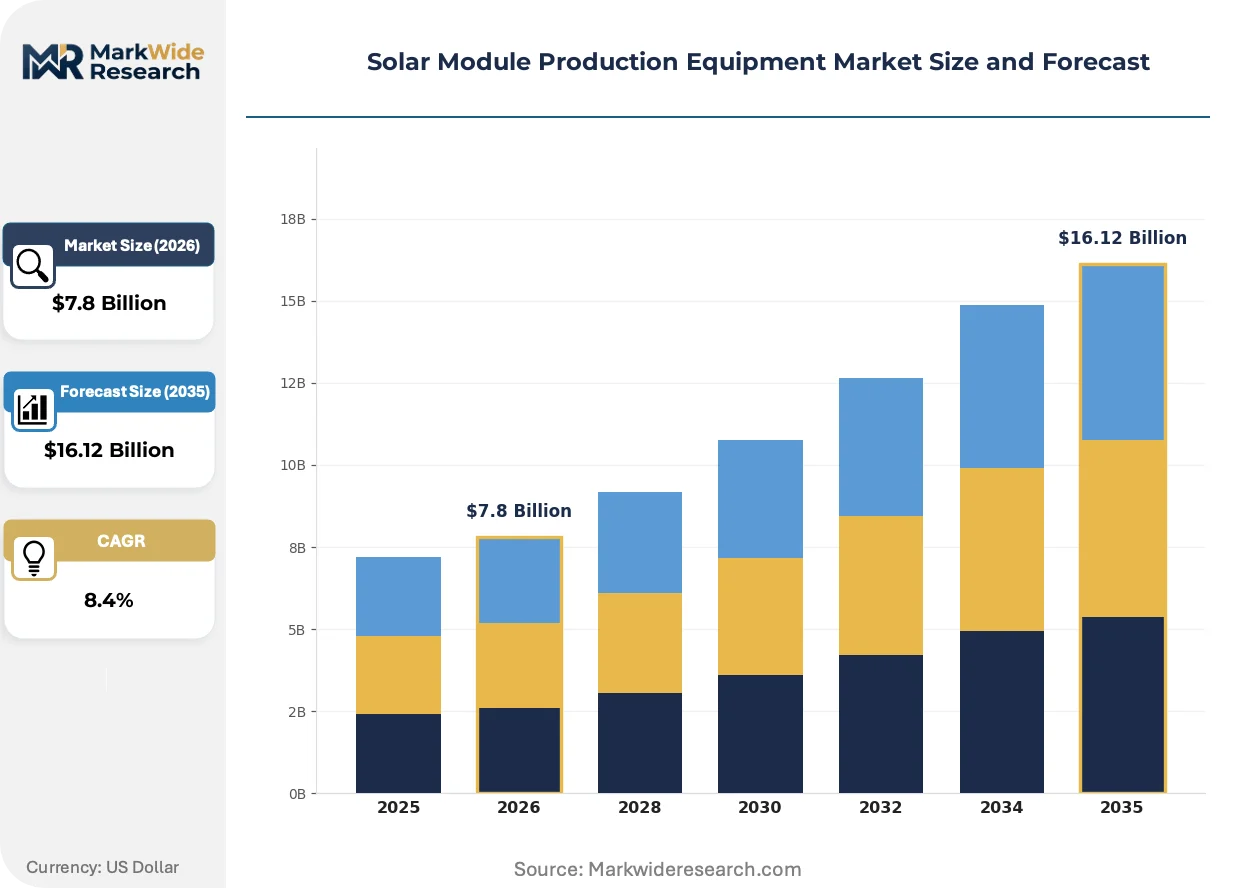
Market Dynamics
Cell metallization equipment faces acute pressure from silver paste cost volatility and heterojunction architecture transitions that demand entirely new deposition tool configurations. Chinese equipment vendors are consolidating diffusion furnace supply while European manufacturers defend lamination and testing station niches through carbon-footprint certification advantages.
Growth Catalysts
- India's PLI scheme:Domestic content requirements under the production-linked incentive program are accelerating local manufacturing capacity buildouts for cell assembly lines and module framing stations.
- Heterojunction cell architectures:Utility-scale solar developers are expanding procurement of automated deposition and passivation tools that enable cell efficiencies above 24%.
- EU Green Deal embodied-carbon standards:The carbon border adjustment mechanism is tightening import requirements, pushing equipment upgrades toward low-carbon process configurations.
Market Restraints
- Silver paste cost volatility:Metallization equipment utilization depends on precious metal input stability that fluctuates with commodity exchange pricing and mining supply disruptions.
- Chinese diffusion furnace concentration:PERC and TOPCon upgrade cycles rely on cost-engineered thermal processing equipment sourced from a concentrated vendor base in Jiangsu and Zhejiang provinces.
- TOPCon-to-heterojunction technical lock-in:Capital-intensive cell architecture transitions create stranded asset risk for manufacturers with recent PERC line investments.
Strategic Opportunities
- Bifacial module lamination:Dual-glass architecture adoption is creating demand for upgraded encapsulant and edge-sealing equipment that accommodates thicker glass substrates.
- Software-defined process control:Equipment vendors are monetizing platforms through recurring digital service contracts that optimize throughput and yield remotely.
- Building-integrated photovoltaics:Lightweight flexible thin-film deposition systems are penetrating architectural glass and roofing membrane applications where rigid crystalline modules fail.
Industry Challenges
- Process engineer talent scarcity:Gigawatt-scale fab commissioning requires specialists in plasma-enhanced chemical vapor deposition who command premium compensation in semiconductor-competing labor markets.
- MIIT GB standards compliance timeline:China's Ministry of Industry and Information Technology efficiency and energy consumption certifications determine equipment qualification for domestic tenders, creating certification backlog bottlenecks.
- Legacy PERC line integration complexity:Partial upgrade paths to TOPCon require retrofitting existing diffusion furnaces with boron doping capabilities that conflict with original phosphorus process configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Module Production Equipment Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Cells, Inverters, Encapsulators, Laminators Technology: Crystalline Silicon, Thin-Film, Bifacial, Multi-junction End User: Manufacturers, Installers, Utilities, Research Institutes Application: Residential, Commercial, Utility-scale, Off-grid |
| Companies Covered | Applied Materials, Meyer Burger, Horiba, Centrotherm, Tempress Systems, Singulus Technologies, CETC Solar, Jinchen Machinery, Centrotherm Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Module Production Equipment Market Trends and Innovations
Equipment vendors are restructuring revenue models around digital service layers while cell architecture transitions force wholesale tool replacement cycles. Three developments are compressing conventional hardware sales timelines.
SmartWire interconnection technology is integrating copper-plated cell connection systems that eliminate busbar welding and reduce silver consumption by over 50%. European module manufacturers are adopting these platforms to satisfy EU Green Deal carbon-footprint disclosure requirements for imported cells. The technology is integrating metallization and interconnection processes into unified deposition-lamination stations that compress factory footprint requirements.
China's MIIT enforcement of updated GB standards for module efficiency and factory energy consumption is disqualifying older diffusion furnace configurations from domestic tender eligibility. Equipment vendors must recertify thermal processing tools against stricter per-watt consumption benchmarks to maintain market access. Indian manufacturers under PLI scheme obligations are importing these compliant configurations to preempt BIS certification delays.
Utility-scale developers are consolidating procurement through integrated engineering-procurement-construction contractors who specify equipment packages rather than individual tool vendors. This channel concentration is squeezing standalone equipment margins while favoring vendors with full-line integration capabilities. The shift is most visible in India's domestic manufacturing buildouts where PLI beneficiaries negotiate turnkey fab contracts with single-source accountability.
Solar Module Production Equipment Market Segmentation
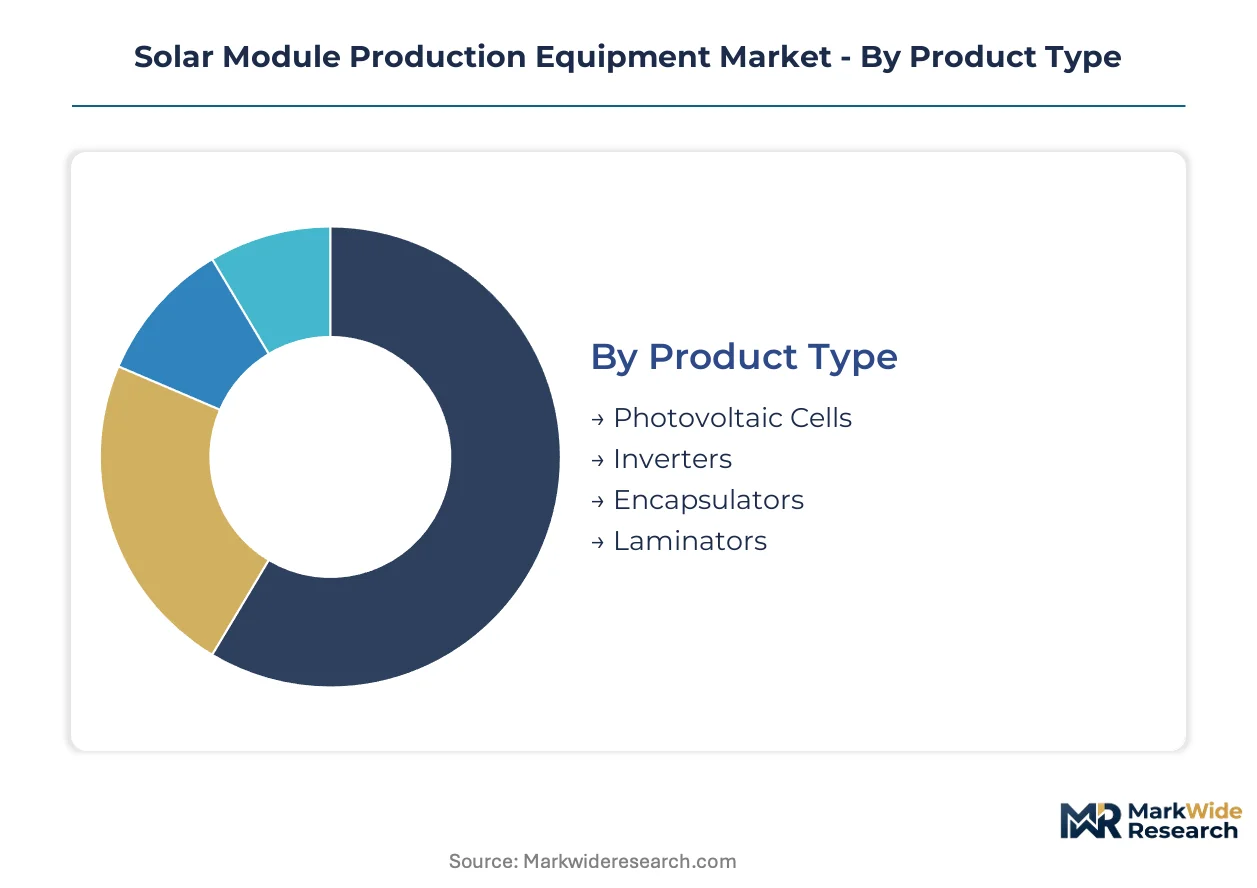
Equipment procurement patterns diverge sharply across cell architectures and installation scales. Understanding these fault lines reveals where capital expenditure concentrates and which technology transitions threaten incumbent tooling investments.
Product Type:
Diffusion furnace and metallization tool vendors cluster in Jiangsu and Zhejiang provinces, while lamination equipment retains European manufacturing footprints.
- Photovoltaic Cells:Texturing, doping, and passivation tools process silicon wafers into functional cells at throughputs exceeding 10,000 units per hour. Heterojunction architecture transitions in India and China are accelerating replacement cycles for legacy PERC diffusion furnaces as manufacturers chase efficiency thresholds above 24%.
- Inverters:Power electronics assembly lines integrate semiconductor packaging, thermal management, and grid-synchronization testing stations. String inverter production for utility-scale developers in India concentrates procurement with EPC contractors specifying integrated equipment packages under PLI scheme obligations.
- Encapsulators:Ethylene-vinyl acetate and polyolefin elastomer sheet extrusion systems supply lamination stations with moisture-barrier materials.
- Laminators:Vacuum-press systems bond cell strings to glass substrates under controlled temperature and pressure cycles.
Today's leader: Photovoltaic Cells. Tomorrow's challenger: Inverters.
Technology:
Cell efficiency benchmarks and silver consumption targets determine which deposition architectures manufacturers adopt.
- Crystalline Silicon:Dominant platform encompassing PERC, TOPCon, and heterojunction cell architectures using Czochralski-grown silicon ingots. China's MIIT GB standards enforce factory energy consumption limits that disqualify older diffusion furnace configurations from domestic tender eligibility.
- Thin-Film:Cadmium telluride and copper indium gallium selenide deposition systems on flexible substrates serve building-integrated applications where weight constraints override efficiency penalties. European architectural glass manufacturers specify these tools to satisfy EU Green Deal embodied-carbon disclosure requirements.
- Bifacial:Dual-glass module architectures demand upgraded encapsulant handling and edge-sealing equipment that accommodates thicker front and rear glass substrates.
- Multi-junction:III-V semiconductor epitaxy systems concentrate in satellite and concentrated solar power applications with extreme efficiency requirements.
Crystalline Silicon commands current capacity expansion. Bifacial tools are climbing the fastest as dual-glass becomes standard for utility procurement.
End User:
Customer scale and technical sophistication fragment equipment specifications across procurement channels.
- Manufacturers:Gigawatt-scale cell and module fabs require fully automated lines with software-defined process control and remote yield optimization. Indian PLI beneficiaries negotiate turnkey contracts with single-source accountability, compressing margins for standalone tool vendors.
- Installers:Regional module assembly operations purchase semi-automated framing and junction-box attachment stations with lower capital intensity.
- Utilities:Integrated generation developers specify equipment packages through EPC contractors rather than individual tool vendors.
- Research Institutes:Pilot-line configurations accommodate rapid process iteration with flexible batch processing and rapid recipe switching.
Manufacturers drive volume concentration. Research Institutes are gaining share fastest as heterojunction process development accelerates.
Application:
Scale economies and regulatory compliance requirements stratify equipment configurations.
- Utility-scale:Automated cell assembly lines with throughput maximization and breakage minimization dominate procurement. EU Green Deal carbon border adjustments push non-European manufacturers toward low-carbon process upgrades to maintain market access.
- Commercial:Rooftop and distributed generation installations favor mid-scale lamination and testing stations with modular capacity expansion.
- Residential:Small-format module production accommodates aesthetic and dimensional constraints with flexible tooling configurations.
- Off-grid:Durable module specifications for remote installations prioritize reliability testing and environmental stress screening equipment.
Utility-scale anchors capital deployment. Commercial applications are expanding most quickly as distributed generation policy support strengthens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production equipment procurement migrates toward jurisdictions where regulatory compliance costs create competitive arbitrage, with manufacturers relocating capacity to exploit gaps between carbon border tariffs and domestic subsidy regimes.
China
Jiangsu and Zhejiang provinces host concentrated diffusion furnace fabrication serving PERC-to-TOPCon upgrade cycles. MIIT enforces updated GB standards for factory energy consumption that disqualify older thermal processing configurations from domestic tender eligibility. Equipment vendors in Suzhou recertify tools against stricter per-watt benchmarks to maintain access to state-backed solar deployment.
India
Gujarat and Tamil Nadu absorb capital inflows for gigawatt-scale cell assembly lines under PLI scheme obligations. BIS certification requirements and domestic content mandates favor locally sourced production tools, compressing timelines for foreign vendor qualification. EPC contractors in Mundra negotiate turnkey fab contracts with single-source accountability, reshaping procurement channel structure.
Germany
EU Green Deal carbon border adjustment mechanisms and F-Gas Regulation reshape import competitiveness for module manufacturers. Lamination and testing equipment retains European manufacturing footprints to satisfy embodied-carbon disclosure requirements. Thuringia-based production lines leverage carbon-footprint certification advantages to defend niche positions against Asian cost competition.
United States
IRA manufacturing tax credits accelerate domestic module fab construction, though equipment sourcing concentrates with established Asian and European vendors. Southeast states attract assembly line investments seeking to bypass Section 201 tariff exposure. Process engineer talent scarcity in plasma-enhanced chemical vapor deposition constrains commissioning timelines for heterojunction pilot lines.
Japan
METI efficiency benchmarks and grid-integration standards shape equipment specifications for residential and commercial module applications. Kansai region manufacturers specialize in high-throughput testing stations with breakage minimization protocols. Thin-film deposition systems sustain relevance in building-integrated segments where architectural glass integration outweighs crystalline silicon efficiency advantages.
Solar Module Production Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line integration capabilities commanding premium positioning against standalone tool vendors. Equipment supply concentrates among three tiers: semiconductor-heritage deposition specialists, solar-dedicated thermal processing vendors, and emerging Chinese cost-engineered furnace fabricators. Strategic moves center on technology licensing partnerships for heterojunction tool configurations and geographic co-location with PLI-subsidized manufacturing hubs in India.
Among semiconductor-heritage deposition specialists, Applied Materials leverages semiconductor process expertise into advanced tool configurations for next-generation cell architectures. Meyer Burger anchors European manufacturing presence with proprietary interconnection platforms that reduce precious metal consumption. CETC Solar exemplifies cost-engineered thermal processing archetypes competing aggressively on diffusion furnace pricing for PERC and TOPCon upgrade cycles.
| Leading Market Players |
|---|
| Applied Materials |
| Meyer Burger |
| Horiba |
| Centrotherm |
| Tempress Systems |
| Singulus Technologies |
| CETC Solar |
| Jinchen Machinery |
| Centrotherm Digital |
| Others |
Pricing and Supply Chain Analysis
Silver paste cost volatility cascades through metallization equipment pricing tiers, with high-purity paste procurement in Jiangsu province feeding into turnkey system quotes that stratify between premium heterojunction deposition platforms and cost-engineered PERC upgrade bundles for Indian PLI beneficiaries.
Pricing Analysis
Distributor margins on diffusion furnace imports into India compress under BIS certification urgency, while direct-to-OEM contracts with Chinese vendors in Zhejiang province command volume discounts. Three-tier pricing structure across premium heterojunction, standard TOPCon, and economy PERC equipment levels differentiates by MIIT GB standard compliance tier and remote service bundling. Pricing pressure stems from EPC contractor consolidation specifying integrated packages rather than standalone tools. Small-scale installers in Tamil Nadu exhibit acute price sensitivity, whereas utility-scale developers prioritize throughput guarantees over capital cost.
Supply Chain Analysis
Regional distribution centers in Mundra and Suzhou consolidate diffusion furnace inventory before hub-and-spoke dispatch to Gujarat and Tamil Nadu fab sites. Manufacturing concentrates in China, Germany, and Japan, with lamination equipment retaining European footprints to satisfy EU Green Deal carbon-footprint disclosure. Raw material dependencies include high-purity silicon ingots, silver paste, and boron dopant gases. Single-source vulnerability in Jiangsu province diffusion furnace fabrication threatens PERC-to-TOPCon upgrade timelines. Distribution runs through EPC contractor-specified turnkey packages rather than discrete tool procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar Module Production Equipment Market compounds steadily as heterojunction architecture transitions force wholesale replacement cycles across gigawatt-scale fabs, creating durable demand for deposition and passivation tooling.
For Market Incumbents: Cement dominance in heterojunction deposition tools by acquiring plasma-enhanced chemical vapor deposition specialist talent pools in semiconductor-competing labor markets. Defend against Chinese cost-engineered furnace vendors by securing MIIT GB standard pre-certification for thermal processing configurations, locking in domestic tender eligibility before competitors complete recertification timelines. For New Entrants and Emerging Players: Capture white-space in building-integrated photovoltaic thin-film deposition systems where architectural glass manufacturers in Europe seek lightweight flexible substrates. Target India's PLI scheme beneficiaries with boron doping retrofit kits for legacy PERC diffusion furnaces, offering partial upgrade paths that avoid stranded asset risk. Lead with software-defined process control layers that monetize recurring service contracts rather than capital equipment sales. For Investors and Strategic Acquirers: Consolidation pressure builds where heterojunction tool configuration licensing creates technology gatekeeper positions. Frame long-term viability around equipment vendors with full-line integration capabilities serving EPC contractor procurement consolidation. Watch for MIIT GB standard enforcement acceleration as the inflection signal that disqualifies older diffusion furnace configurations and triggers replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Heterojunction Tool Licensing | Applied Materials leverages semiconductor heritage into next-generation cell architecture configurations. |
| India PLI Co-location | CETC Solar establishes fabrication presence in Gujarat to preempt BIS certification delays for local content mandates. |
| SmartWire Technology Integration | Meyer Burger reduces silver consumption by over 50% to satisfy EU Green Deal carbon-footprint requirements. |
| Software-Defined Service Layer | Equipment vendors monetize platforms through recurring digital contracts optimizing remote yield management. |
| Backward Integration into Dopant Supply | Diffusion furnace vendors secure captive boron gas sourcing to stabilize input cost volatility. |
Research Methodology
Multiple input streams — primary interviews with equipment vendor sales directors, EPC contractor procurement leads, and fab commissioning engineers, alongside secondary validation through MIIT GB standard filings, EU Green Deal regulatory texts, and PLI scheme administrative records — were reconciled using bottom-up equipment shipment tracking and top-down capital expenditure triangulation.
Data-stream reconciliation across the projection horizon modeled crystalline silicon versus thin-film technology splits, utility-scale versus commercial application scale tiers, and manufacturer versus research institute end-user segments. CAGRs were derived from installed capacity buildout trajectories and equipment replacement cycle assumptions, incorporating heterojunction adoption curves and silver paste price elasticity as industry-specific forecast inputs.
Policy subsidy withdrawal, silver commodity price spikes, and MIIT certification timeline delays are the dominant revision risks that could compress or extend equipment procurement schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market