
 Global Laser Dicing Systems Market | 2026-2036
Global Laser Dicing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laser Dicing Systems Market Outlook
End-use demand is shifting toward advanced IC packaging as chiplet architectures proliferate across high-performance computing. DISCO Corp. dominates precision dicing equipment for silicon wafers, while Synova S.A. leverages water-jet guided laser technology for brittle materials. Han's Laser Technology Co. Ltd. anchors cost-competitive production lines across China's electronics manufacturing base.
Laser dicing systems employ focused beam energy to separate semiconductor wafers, solar cells, and MEMS substrates with kerf widths below 20 micrometers and minimal mechanical stress on die edges. Ultra-fast laser platforms command premium positioning due to cold ablation capabilities for thin-wafer processing, while fiber laser configurations compete on operational efficiency in high-volume LED manufacturing. The application dimension reveals IC packaging as the mature revenue base, with MEMS device dicing representing the fastest structural expansion as automotive and biomedical sensor demand intensifies.
US EPA and OSHA frameworks govern industrial laser safety classifications and workplace exposure limits, while EU REACH and RoHS directives restrict hazardous substances in dicing consumables and cooling systems. Japan's METI enforces JIS standards on precision equipment calibration that shape export eligibility for Tokyo Seimitsu Co. Ltd. and 3D Micromac AG. Stakeholders must monitor evolving dual-use export controls on sub-10-micron positioning systems before committing capacity expansion plans.
Market Dynamics
The transition from mechanical blade dicing to laser-based separation is compressing kerf widths and enabling thinner wafer processing, with EU F-Gas Regulation and US EPA emissions standards accelerating fiber laser adoption over gas-based platforms.
Growth Catalysts
- Advanced packaging architectures:Chiplet-based designs in high-performance computing require precision dicing for interposer fabrication. Semiconductor foundries in Taiwan and South Korea are expanding laser dicing capacity to serve this demand.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases push manufacturers toward solid-state and fiber laser platforms that eliminate gas-based cooling systems.
- Automotive sensor proliferation:MEMS device demand for LiDAR and pressure sensing applications drives adoption of ultra-fast laser systems for brittle material processing.
Market Restraints
- Ultra-fast laser source concentration:German and Swiss suppliers dominate femtosecond oscillator production, creating supply vulnerability for system integrators dependent on cold ablation technology.
- Technical limitation in thick wafer processing:Laser dicing exhibits reduced throughput above 300-micron silicon thickness, constraining penetration in power semiconductor segments where mechanical saws retain cost advantage.
- Substitution threat from plasma dicing:Dry etch-based stealth dicing alternatives achieve narrower streets for certain memory applications, pressuring laser system pricing in NAND flash manufacturing.
Strategic Opportunities
- India's semiconductor manufacturing incentives:PLI scheme subsidies for domestic fab construction create greenfield demand for laser dicing equipment in a market currently dependent on imported dice.
- Biomedical MEMS expansion:Implantable glucose monitors and microfluidic diagnostic cartridges require polymer and glass substrate dicing, opening applications beyond traditional silicon processing.
- Convergence of AI-driven process control:Machine vision integration with real-time beam modulation enables adaptive dicing paths for warped wafers, differentiating premium system offerings.
Industry Challenges
- Laser safety engineering talent scarcity:Industrial laser system manufacturers compete for specialists capable of designing Class 1 enclosure systems compliant with OSHA and IEC 60825 standards.
- Sub-10-micron positioning system certification delays:Dual-use export control classifications for precision motion stages extend order fulfillment timelines for equipment bound for Chinese fabs.
- Legacy mechanical dicing infrastructure lock-in:Established packaging houses face capital efficiency constraints when retrofitting cleanrooms for laser-based processes requiring different particle management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laser Dicing Systems Market |
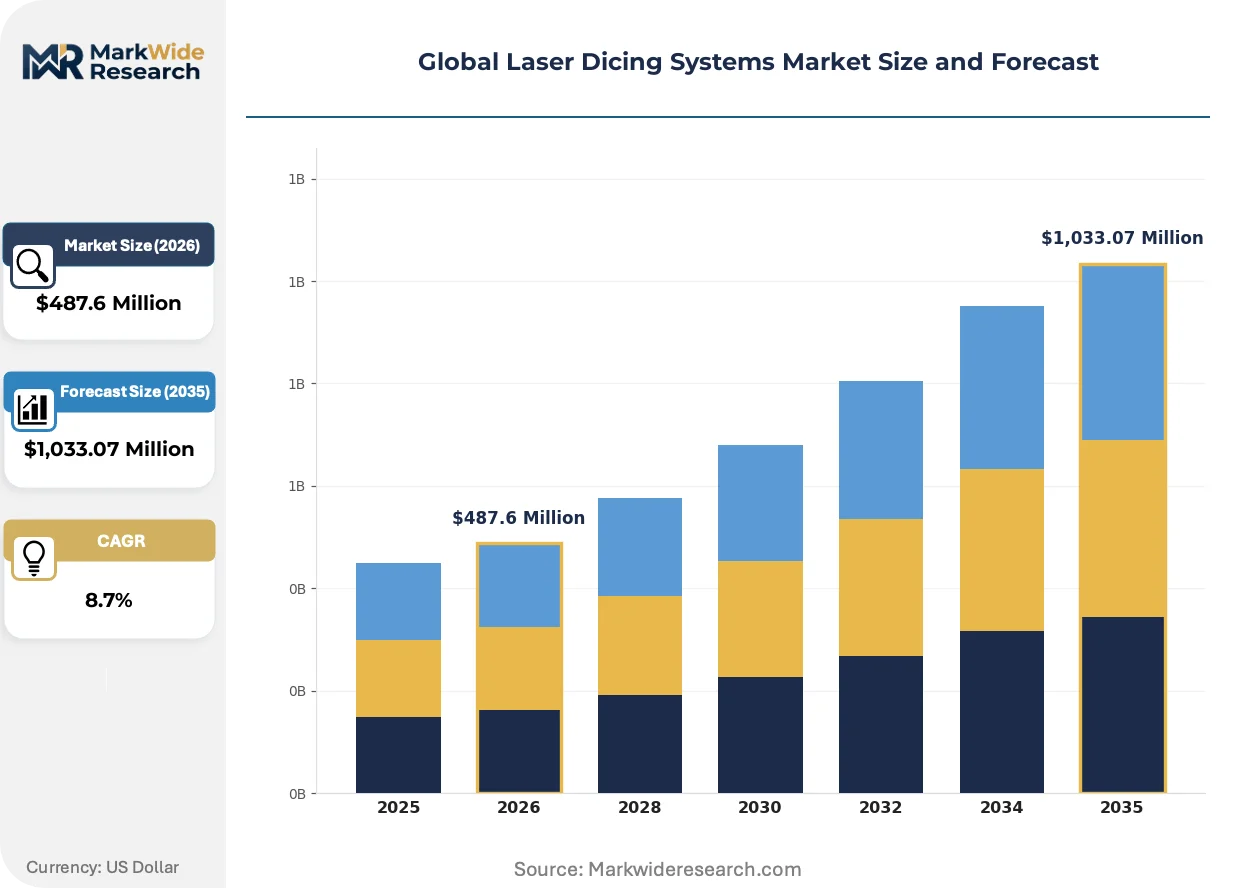
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Excimer Laser, Fiber Laser, Solid-State Laser, Ultra-Fast Laser Product Type: Laser Dicing System, Laser Processing Tool, Laser Cutter, Laser Marking Machine End User: Semiconductor Industry, Electronics Manufacturers, Medical Device Companies, Automotive Suppliers Application: IC Packaging, Solar Cells, MEMS Devices, LED Manufacturing |
| Companies Covered | Tokyo Seimitsu Co. Ltd., Han's Laser Technology Co. Ltd., DISCO Corp., Neon Tech Co. Ltd., GL Tech Co. Ltd., Synova S.A., 3D Micromac AG, EO Technics, ASMPT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laser Dicing Systems Market Strategic Shifts
Beam delivery architectures and process control systems are converging to enable single-platform flexibility across wafer materials, while regulatory pressure on consumables reshapes coolant and assist gas supply chains.
Picosecond laser platforms are integrating burst-mode pulse tailoring to optimize material removal rates in silicon carbide substrates. Power semiconductor manufacturers in Japan and Germany are adopting these systems for electric vehicle inverter chip production. This capability is integrating thermal management directly into beam modulation electronics, compressing system footprint requirements.
EU REACH restrictions on chromium compounds in cooling system additives are forcing reformulation of closed-loop chiller fluids used in high-power fiber laser dicing equipment. Industrial coolant suppliers must substitute corrosion inhibitors while maintaining thermal conductivity specifications. European system integrators face the tightest compliance timelines, with German manufacturers leading fluid chemistry validation efforts.
Contract packaging houses are unbundling equipment procurement from process development services, treating dicing parameter optimization as a separately billed engineering engagement. This purchasing behavior disrupts traditional turnkey system sales models in Taiwan and South Korea. Semiconductor foundries with captive packaging operations retain bundled purchasing, creating a two-tier vendor relationship structure.
Global Laser Dicing Systems Market Segmentation
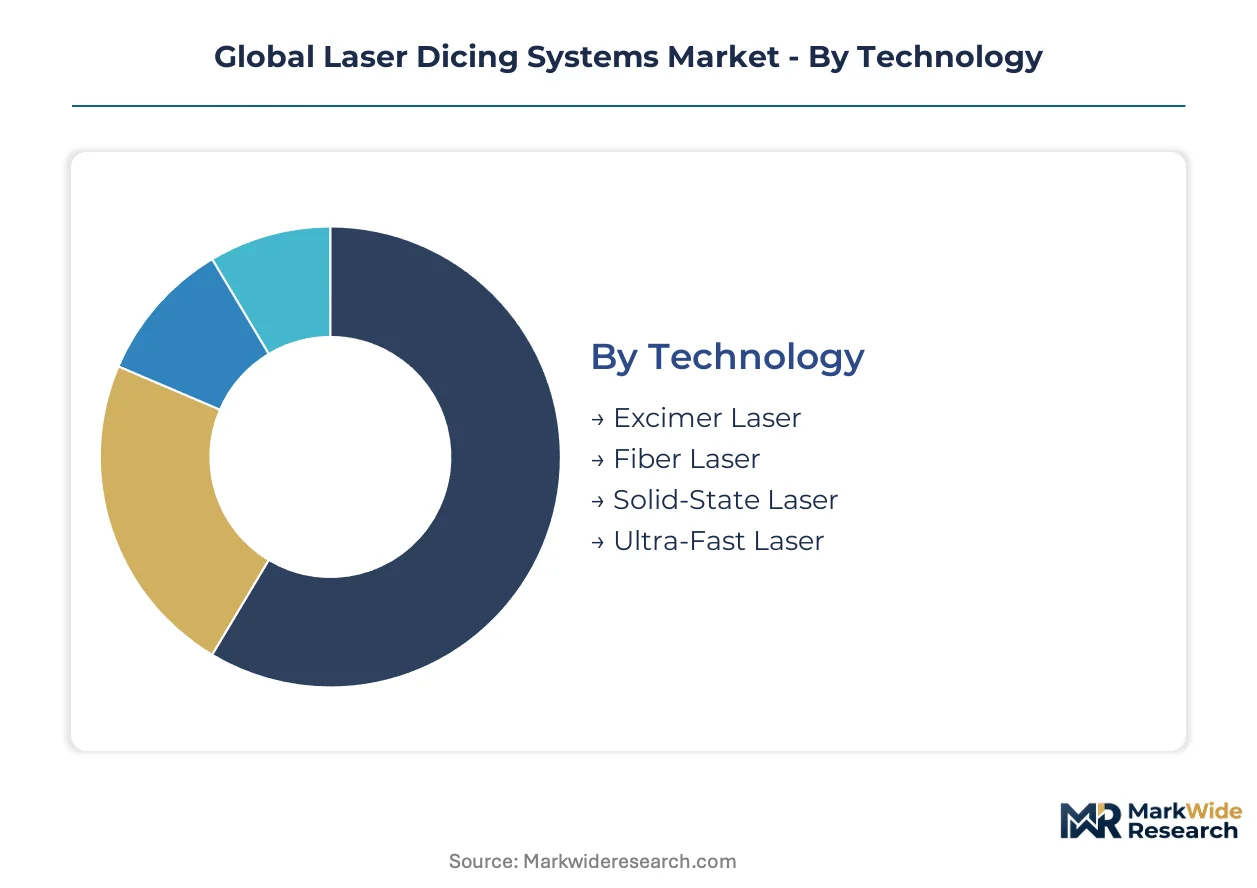
Laser dicing equipment purchasing patterns diverge sharply across technology platforms and end-use requirements. Semiconductor fabs prioritize precision thresholds and throughput metrics that differ fundamentally from solar cell producers or MEMS fabricators.
Technology:
Capital allocation priorities separate buyers seeking operational efficiency from those demanding cold ablation capabilities for thermally sensitive substrates.
- Ultra-Fast Laser:Femtosecond and picosecond pulse durations enable cold ablation with minimal heat-affected zones below 10 micrometers. Demand concentrates in MEMS device fabrication for automotive LiDAR sensors where silicon carbide and glass substrates require fracture-free edge quality.
- Fiber Laser:Diode-pumped solid-state architectures deliver wall-plug efficiencies above 25% with minimal maintenance intervals. Electronics manufacturers in Taiwan and South Korea deploy these systems for high-volume LED wafer singulation where kerf width tolerance bands are less stringent than advanced IC applications.
- Solid-State Laser:Nd:YAG and Nd:YVO4 platforms serve mid-range precision requirements in legacy packaging lines.
- Excimer Laser:UV wavelengths at 193nm and 248nm address specialized polymer and thin-film ablation in biomedical device manufacturing.
Volume sits with fiber laser configurations; growth tilts toward ultra-fast platforms as chiplet packaging proliferates.
Product Type:
Equipment purchasing behavior reflects the divergence between captive semiconductor fabrication and outsourced packaging services.
- Laser Dicing System:Integrated platforms combining beam delivery, motion stages, and machine vision for fully automated wafer singulation. Semiconductor foundries in Hsinchu and Seoul specify these systems for interposer dicing in 2.5D/3D packaging architectures.
- Laser Processing Tool:Modular configurations permitting rapid retooling between dicing, drilling, and marking operations. Electronics contract manufacturers in Shenzhen favor this flexibility for multi-product fabrication lines serving consumer device OEMs.
- Laser Cutter:Stand-alone cutting stations for post-dicing substrate trimming in solar cell manufacturing.
- Laser Marking Machine:Post-singulation die identification systems integrated into packaging workflows.
Revenue concentrates in full dicing systems; flexibility premiums drive processing tool adoption among contract manufacturers.
End User:
Customer technical requirements stratify across precision thresholds, cleanroom classifications, and regulatory compliance burdens.
- Semiconductor Industry:Integrated device manufacturers and foundries operate Class 10 cleanroom environments demanding sub-5-micron positioning accuracy. Taiwan Semiconductor Manufacturing Company and Samsung Electronics anchor procurement volumes for 300mm wafer processing systems.
- Automotive Suppliers:Tier-1 sensor manufacturers in Germany and Japan require dicing systems qualified to AEC-Q100 stress test protocols for powertrain and autonomous driving MEMS components.
- Electronics Manufacturers:PCB and discrete component producers prioritize throughput metrics over absolute precision.
- Medical Device Companies:Implantable device fabricators face FDA 21 CFR Part 820 quality system requirements affecting equipment validation protocols.
Procurement scale favors semiconductor fabs; regulatory complexity steepens fastest for medical device applications.
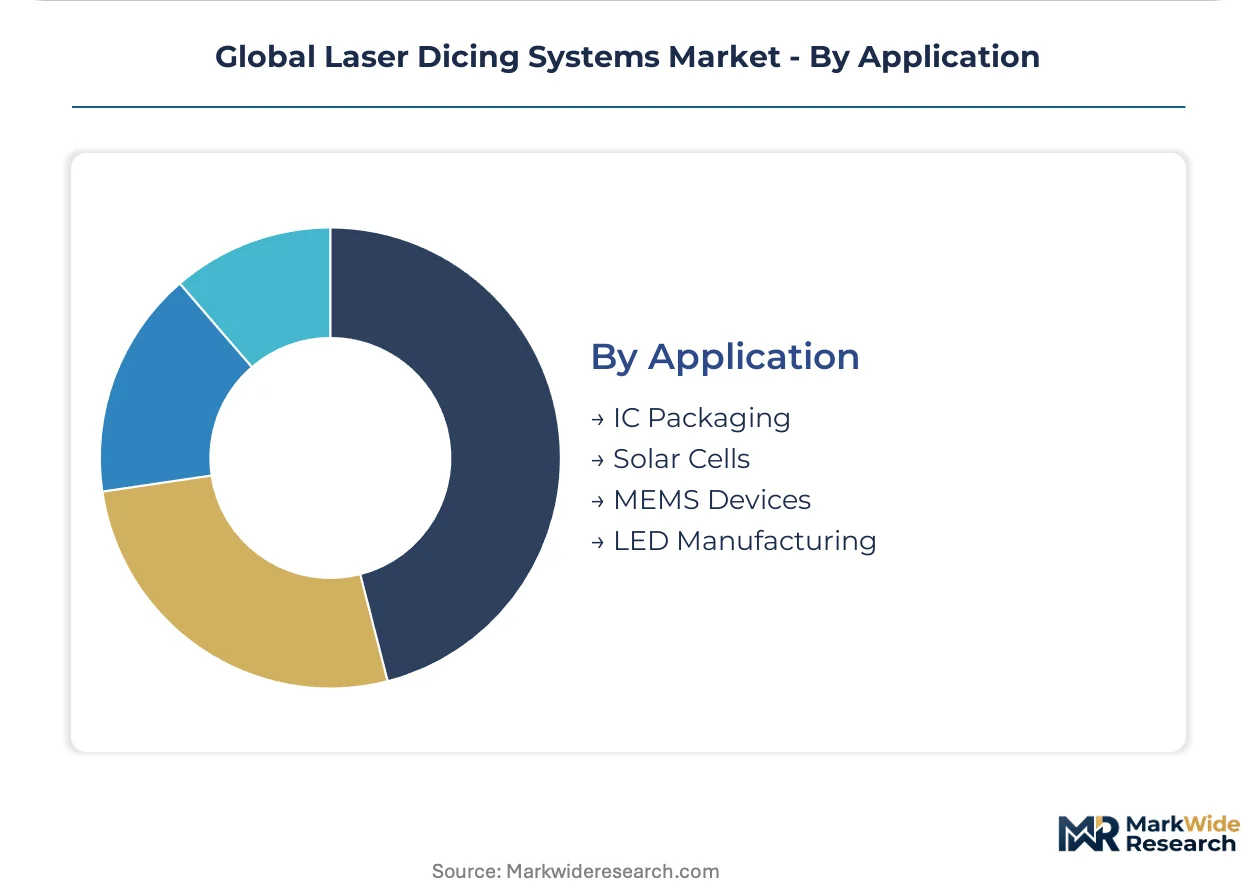
Application:
Material properties and die fragility determine laser wavelength selection and pulse parameter optimization.
- IC Packaging:Silicon wafer dicing for logic and memory devices represents the established revenue base. Advanced packaging transitions toward chiplet architectures require stealth dicing and plasma-assisted laser hybrid approaches for ultra-thin wafer handling.
- MEMS Devices:Micro-electromechanical systems for pressure, inertial, and optical sensing applications demand brittle material processing capabilities. Automotive sensor proliferation in electric vehicle platforms accelerates equipment orders for silicon carbide and glass substrate dicing.
- Solar Cells:Crystalline silicon and thin-film photovoltaic manufacturers balance kerf loss minimization against throughput requirements.
- LED Manufacturing:Sapphire and silicon carbide wafer singulation for solid-state lighting applications.
IC packaging commands current installed base; MEMS device fabrication exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park tax incentives concentrate semiconductor foundry investment in Taiwan, while South Korea's K-Semiconductor Belt drives matching capacity expansion. These special economic zones anchor East Asian laser dicing equipment procurement.
Taiwan
TSMC and United Microelectronics Corporation expand advanced packaging lines for chiplet architectures. Taiwan's National Development Council offers tax holidays for semiconductor equipment investment under the A+ Industrial Innovation Program. Hsinchu anchors precision dicing system demand for 300mm wafer interposer fabrication.
South Korea
Samsung Electronics and SK Hynix deploy laser dicing for high-bandwidth memory stacking applications. South Korea's Ministry of Trade, Industry and Energy (METI) administers K-Chips Act subsidies for domestic fab equipment procurement. Seoul Capital Area foundries concentrate ultra-fast laser platform orders for silicon carbide processing.
China
Yangtze Memory Technologies and Hua Hong Semiconductor scale domestic packaging capacity. China's Ministry of Industry and Information Technology (MIIT) enforces GB standards on laser equipment safety classifications. Shenzhen and Shanghai manufacturing clusters absorb cost-competitive fiber laser dicing systems for LED and discrete component production.
Japan
Sony and Kioxia integrate stealth dicing for 3D NAND memory device fabrication. Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS B 6802 standards on precision motion stage calibration. Kyushu and Tohoku industrial corridors host equipment validation centers for automotive MEMS sensor applications.
United States
Intel and GlobalFoundries reshore advanced packaging operations under CHIPS Act funding. The US Environmental Protection Agency (EPA) enforces emissions standards pushing fiber laser adoption over gas-based cooling systems. Arizona and Texas fab construction sites generate greenfield demand for Class 1 laser enclosure systems compliant with OSHA 29 CFR 1926 regulations.
Global Laser Dicing Systems Market Competitive Environment
Top-tier vendors anchor precision dicing equipment, while mid-tier system integrators compete on regional service density. Japanese and German manufacturers concentrate femtosecond oscillator supply, creating tiered dependency structures for cold ablation technology. Three archetypes dominate: precision equipment specialists, cost-optimized volume producers, and beam delivery technology licensors. Strategic moves center on geographic expansion through local assembly partnerships and technology licensing agreements to bypass dual-use export controls.
Among Japanese precision equipment manufacturers, Tokyo Seimitsu Co. Ltd. and DISCO Corp. occupy positions within the high-accuracy tier for silicon wafer processing. Synova S.A. represents the water-jet guided laser archetype, while Han's Laser Technology Co. Ltd. anchors cost-competitive production lines. These three exemplify the geographic and technological stratification shaping vendor selection criteria across East Asian electronics manufacturing clusters.
| Leading Market Players |
|---|
| Tokyo Seimitsu Co. Ltd. |
| Han's Laser Technology Co. Ltd. |
| DISCO Corp. |
| Neon Tech Co. Ltd. |
| GL Tech Co. Ltd. |
| Synova S.A. |
| 3D Micromac AG |
| EO Technics |
| ASMPT |
| Others |
Value Chain & Pricing Dynamics
Captive femtosecond oscillator production in Germany and Switzerland anchors premium pricing power for ultra-fast laser system integrators, while outsourced fiber laser component sourcing from Chinese suppliers compresses margins in high-volume LED dicing segments. This integration split between cold ablation technology and cost-optimized platforms creates divergent pricing architectures across the equipment spectrum.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to ultra-fast laser systems dependent on German femtosecond oscillator supply, while spot inventory discounts emerge for fiber laser configurations with standardized diode pump modules. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 qualified automotive MEMS systems from industrial LED dicing equipment and refurbished legacy platforms. Cost compression in fiber laser tiers intensifies because Chinese electronics manufacturers negotiate volume aggregation contracts. Contract packaging houses in Taiwan exhibit highest price sensitivity; captive foundry operations at TSMC and Samsung Electronics prioritize precision thresholds over unit economics.
Supply Chain Analysis
Refurbishment flows for precision motion stages and beam delivery optics create secondary supply channels serving mid-tier system integrators in South Korea and Taiwan. German and Swiss suppliers dominate femtosecond oscillator production; Chinese manufacturers anchor fiber laser diode and cooling system component supply. Tariff exposure on sub-10-micron positioning systems extends order fulfillment timelines for equipment bound for Chinese fabs. Distribution runs through direct OEM relationships for semiconductor foundries; contract manufacturers access equipment through regional distributors in Shenzhen and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into femtosecond oscillator production represents the decisive competitive lever as cold ablation demand accelerates for chiplet packaging and silicon carbide processing applications.
For Market Incumbents: Extend precision calibration service contracts to lock in semiconductor foundry relationships against emerging Chinese system integrators. Backward integration into beam delivery optics manufacturing reduces dependency on Japanese optical component suppliers facing JIS certification bottlenecks. Capacity expansion in South Korea's K-Semiconductor Belt captures Samsung Electronics and SK Hynix procurement growth for high-bandwidth memory stacking applications. For New Entrants and Emerging Players: Biomedical device contract manufacturers in Germany and Switzerland represent an underserved buyer archetype requiring polymer and glass substrate dicing capabilities outside traditional silicon processing expertise. India's PLI scheme subsidies for domestic fab construction create greenfield demand in a market currently dependent on imported dice. Partnership with established coolant suppliers reformulating REACH-compliant chiller fluids accelerates European market entry without proprietary fluid chemistry investment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to precision equipment conglomerates seeking MEMS dicing capabilities. Long-term viability hinges on differentiation in ultra-fast laser platforms as fiber laser commoditization accelerates. Acquisition targets should demonstrate qualified AEC-Q100 system deployments or FDA-validated biomedical processing installations. Watch for dual-use export control relaxation on Chinese fab equipment orders as an inflection indicator for demand recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Femtosecond Oscillator Supply Agreement | Secures cold ablation technology access for automotive MEMS sensor manufacturers qualifying to AEC-Q100 protocols. |
| REACH-Compliant Coolant Formulation Partnership | Enables EU market participation as ECHA restrictions phase out chromium-based corrosion inhibitors in laser cooling systems. |
| Machine Vision Integration Development | Differentiates premium offerings through AI-driven adaptive dicing paths for warped wafer processing in advanced packaging. |
| Indian PLI Scheme Equipment Localization | Captures greenfield fab construction demand under India's semiconductor manufacturing incentive program. |
| Sub-10-Micron Positioning System Certification | Resolves dual-use export control delays extending order fulfillment for Chinese-bound precision motion stages. |
Study Parameters
Document review covered SEC filings from precision equipment manufacturers, ECHA regulatory submissions on coolant formulations, and JIS calibration standards, complemented by interviews with semiconductor fab equipment procurement managers, laser system integration engineers, automotive MEMS qualification specialists, and industrial coolant supplier technical directors. Secondary validation drew from Taiwan's National Development Council A+ Industrial Innovation Program disclosures, South Korea's K-Chips Act subsidy documentation, and US EPA emissions standard enforcement records. Bottom-up equipment shipment data triangulated against top-down fab capacity expansion announcements.
Installed base projections across technology platforms, end-use segments, and regional manufacturing clusters informed market sizing throughout the forecast period. Segmentation dimensions modeled include laser source type, system configuration, application material, cleanroom classification requirement, and regional regulatory compliance burden. CAGRs were derived from equipment replacement cycles, technology transition timelines, and capacity expansion announcements. Forecast inputs incorporated femtosecond oscillator supply constraints, EU F-Gas Regulation phase-down schedules, and CHIPS Act funding disbursement progress.
Revisions become necessary when dual-use export control classifications shift, femtosecond oscillator supply disruptions materialize, or plasma dicing technology achieves cost parity for memory applications. Forecasts reflect assumptions on semiconductor capital expenditure cycles, packaging technology migration rates, and regulatory compliance timeline adherence. Practitioners should monitor US Bureau of Industry and Security export control updates, German laser source manufacturer capacity announcements, and AEC-Q100 qualification protocol revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market