
 United States Polymer Emulsion Market | 2026-2036
United States Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
United States Polymer Emulsion Market Analytics
Low-VOC specification tiers is bifurcating the competitive landscape into reformulation-ready suppliers and legacy solvent-based holdouts. BASF SE leverages its integrated acrylic monomer position to supply compliant emulsions at scale. Celanese Corporation anchors its presence through captive vinyl acetate ethylene technology. Trinseo competes on specialty styrene-acrylic blends for premium architectural segments.
Polymer emulsion denotes a colloidal dispersion of polymer particles in an aqueous continuous phase, typically ranging from 0.05 to 5.0 microns in particle diameter, manufactured via free-radical emulsion polymerization using surfactant-stabilized systems. These waterborne systems serve as binders, adhesives, and film-forming agents across industrial and consumer applications where solvent reduction is mandated. Acrylic formulations command the deepest margin pools due to exterior durability and UV resistance premiums in architectural coatings. Paints and coatings applications absorb the majority of volume, though adhesives segments are gaining share on packaging sustainability trends. Emulsion polymerization technology dominates production economics, as aqueous-phase heat removal enables higher throughput with lower capital intensity than bulk or solution alternatives.
EPA VOC regulations, OSHA workplace exposure limits, and state-level CARB standards collectively mandate waterborne system conversion across architectural and industrial coatings categories. The Federal Insecticide, Fungicide, and Rodenticide Act and Toxic Substances Control Act add compliance layers for antimicrobial and specialty functional additives. Stakeholders must monitor state-level adoption of California's SCM-2015 standards, as interstate regulatory diffusion would accelerate reformulation timelines and compress supplier qualification windows.
Market Dynamics
EPA's National Volatile Organic Compound Emission Standards for Consumer and Commercial Products is compressing reformulation timelines across architectural coatings, forcing solvent-based suppliers to convert waterborne systems or exit specification-driven procurement channels entirely.
Growth Catalysts
- Low-VOC architectural mandates:EPA emission standards under 40 CFR Part 59 are eliminating solvent-based alternatives from federal and state procurement specifications. Waterborne acrylic systems capture specification-compliant volume.
- Gulf Coast petrochemical integration:Captive monomer production along the Texas-Louisiana corridor secures acrylic and vinyl acetate feedstock supply for regional emulsion manufacturers.
- Packaging sustainability pivot:Paperboard and corrugated converters are switching from solvent adhesives to emulsion-based systems to meet retailer sustainability scorecards and extended producer responsibility frameworks.
Market Restraints
- Acrylic monomer cost volatility:Propylene oxide and acrylic acid feedstock exposure ties margin stability to Gulf Coast refinery operating rates and hurricane season disruption patterns.
- Specialty surfactant supply concentration:Alkyl phenol ethoxylate and reactive surfactant production concentrates among a limited supplier base, creating qualification bottlenecks for food-contact and medical-grade emulsions.
- Freeze-thaw performance ceiling:Waterborne systems face intrinsic viscosity stability limits in sub-zero logistics and exterior winter application windows, constraining northern climate market penetration.
Strategic Opportunities
- Texas and Louisiana capacity expansion:Underpenetrated specialty emulsion production in the Gulf Coast corridor offers backward integration synergies for paint manufacturers with captive resin needs.
- Bio-based acrylic feedstocks:USDA BioPreferred program certification and IRA clean manufacturing tax credits create margin advantages for emulsions incorporating bio-attributed monomers.
- Pressure-sensitive adhesive migration:Hot-melt and solvent PSA segments in medical and electronics bonding are converting to waterborne acrylic emulsions for clean room and skin-contact applications.
Industry Challenges
- Formulation chemist scarcity:Free-radical emulsion polymerization expertise concentrates among aging technical workforces, constraining R&D throughput for custom specification development.
- Multi-jurisdictional compliance stacking:CARB SCM-2015, OTC model rules, and emerging state-level VOC standards create overlapping testing and documentation burdens for national product lines.
- Legacy coating system integration:Waterborne emulsions require substrate preparation protocol changes and spray equipment modifications that slow adoption among contractor networks with established solvent-based workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Polymer Emulsion Market |
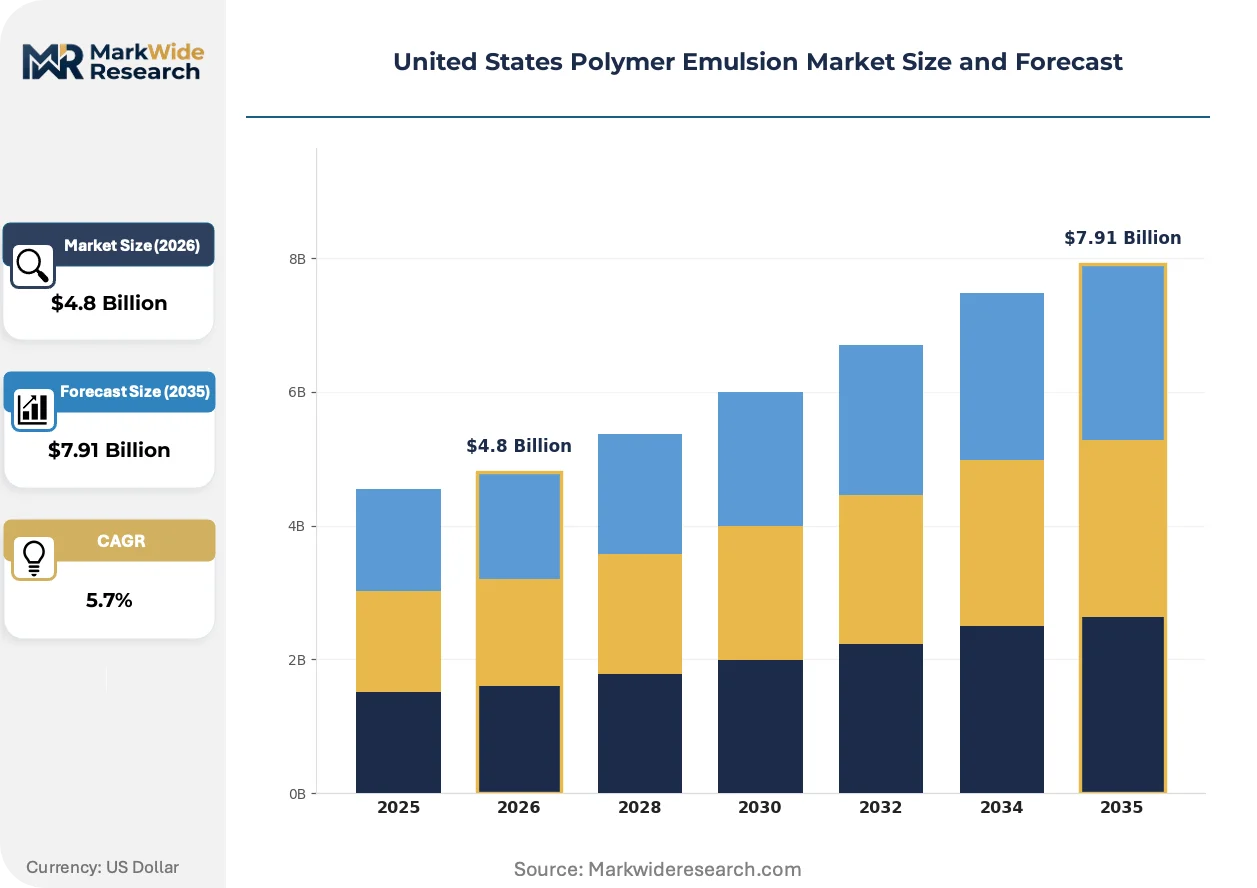
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Styrene-Butadiene, Vinyl Acetate, Polyurethane Application: Paints & Coatings, Adhesives, Textile, Paper End User: Construction, Automotive, Packaging, Consumer Goods Technology: Emulsion Polymerization, Solution Polymerization, Bulk Polymerization, Suspension Polymerization |
| Companies Covered | OMNOVA Solutions, Trinseo, Mallard Creek Polymers Inc., Specialty Polymers Inc., STI Polymer, Engineered Polymer Solutions, Celanese Corporation, The Dow Chemical Company, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Polymer Emulsion Market Evolving Landscape
Reformulation chemistry is fragmenting across performance tiers as regulatory thresholds tighten and end-users demand application-specific durability profiles rather than commodity binder solutions.
Hybrid acrylic-polyurethane emulsion technology is fragmenting the premium architectural coatings segment. Exterior durability specifications for commercial facades and infrastructure are driving adoption among specification architects and national account paint contractors. This convergence of acrylic UV resistance with polyurethane abrasion resistance is compressing pure acrylic share in high-traffic and severe-exposure applications.
OSHA's updated Permissible Exposure Limits for styrene and residual monomers are accelerating styrene-acrylic emulsion substitution with pure acrylic and VAE alternatives. Industrial maintenance and traffic marking segments face reformulation deadlines that compress supplier qualification windows to 18-24 months. Manufacturers with pre-qualified low-styrene portfolios are capturing specification-driven volume in federal and state DOT coatings procurement.
Direct-to-contractor digital distribution is disintermediating traditional coatings distribution in the maintenance and small-project segments. Regional paint contractors and facility maintenance buyers are sourcing specification-compliant emulsions through manufacturer-direct portals and integrated supply platforms. This channel compression is most visible in Texas, Florida, and California metropolitan markets where contractor consolidation has created national account purchasing leverage.
United States Polymer Emulsion Market Segmentation
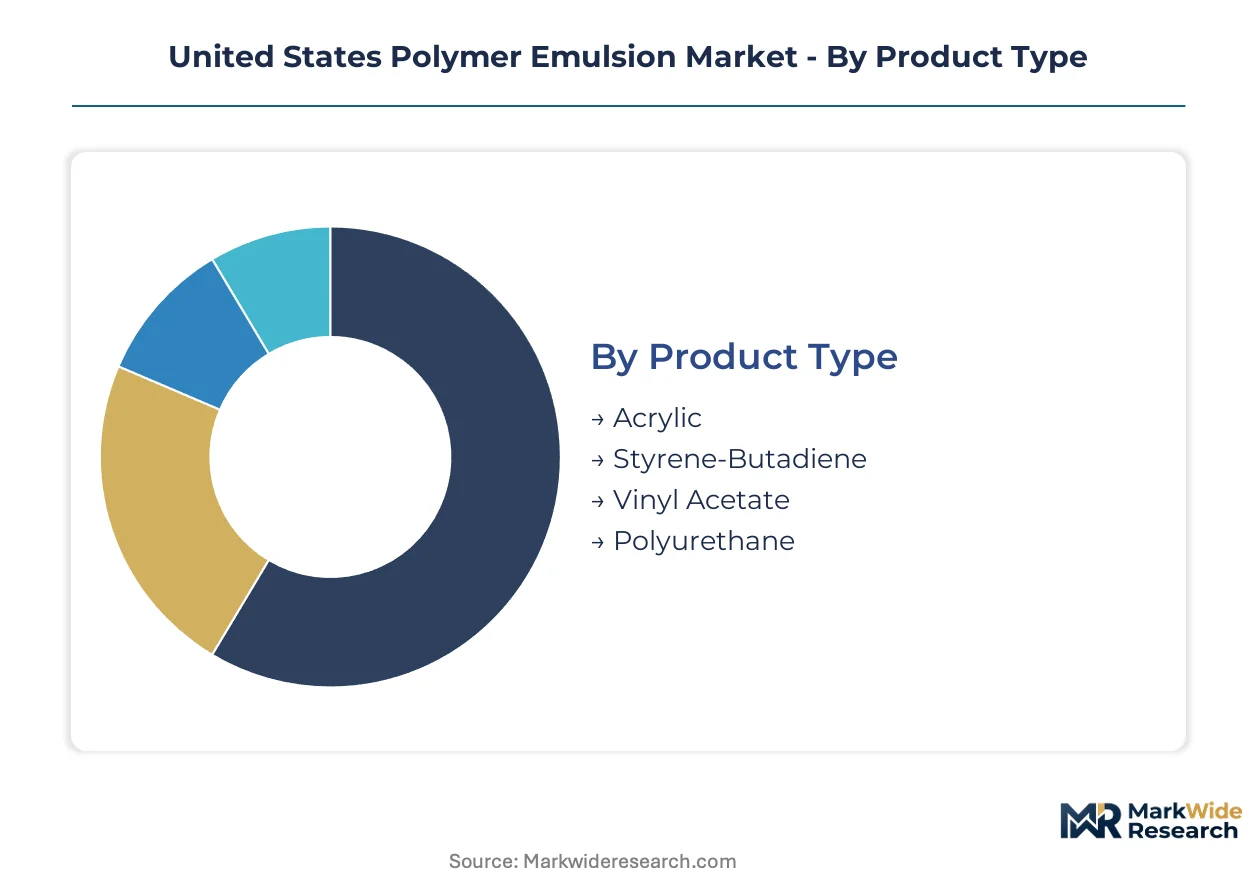
Polymer emulsion segmentation in the United States reflects divergent compliance burdens and performance specifications across federal and state procurement channels. Each dimension carries distinct margin structures and qualification barriers that reshape supplier positioning.
Product Type:
EPA VOC thresholds under 40 CFR Part 59 and California CARB SCM-2015 standards create tiered compliance burdens that fragment competitive positioning across chemistries.
- Acrylic:Dominates exterior architectural coatings through UV resistance and hydrolytic stability. Demand concentrates in California and Florida metropolitan markets where CARB-compliant specifications eliminate solvent alternatives.
- Styrene-Butadiene:Delivers cost-competitive binding for carpet backing and paper coatings. OSHA's tightened styrene exposure limits are compressing adoption timelines in industrial maintenance segments.
- Vinyl Acetate:Celanese Corporation's captive VAE technology anchors interior architectural and packaging adhesive applications with low residual monomer profiles.
- Polyurethane:Hybrid acrylic-polyurethane emulsions command premium positioning in severe-exposure infrastructure and high-traffic commercial flooring.
Established volume favors acrylic; emerging adoption favors polyurethane.
Application:
Application-driven procurement channels exhibit divergent price elasticity and specification intensity.
- Paints & Coatings:Absorbs the majority of emulsion volume across architectural, industrial, and traffic marking segments. Federal and state DOT procurement specifications mandate waterborne systems for bridge and highway infrastructure in coastal states.
- Adhesives:Paperboard converters in the Midwest and Southeast are switching from solvent systems to meet retailer sustainability scorecards and extended producer responsibility frameworks.
- Textile:Nonwoven binders and fabric finishing applications in North Carolina's textile corridor demand soft-hand and wash-durability specifications.
- Paper:Saturating and coating grades for packaging and publication papers concentrate demand in Wisconsin and Maine pulp-and-paper clusters.
Coatings applications retain volume leadership; adhesives segments are climbing the fastest on packaging sustainability mandates.
End User:
End-user concentration patterns align with regional construction cycles and manufacturing density.
- Construction:Residential and commercial building activity in Texas, Florida, and California metropolitan markets drives specification-compliant architectural coatings demand.
- Automotive:OEM and refinish applications in Michigan and Ohio manufacturing corridors require chip-resistant and corrosion-protective emulsion systems.
- Packaging:Corrugated and folding carton converters across the Midwest and Southeast are converting adhesive formulations to meet retailer environmental compliance requirements.
- Consumer Goods:Pressure-sensitive labels, tapes, and DIY adhesives distribute through big-box retail and contractor supply channels.
Construction anchors current volume; packaging end-use is gaining share fastest on sustainability-driven adhesive conversion.
Technology:
Production economics and capital intensity fragment technology selection across scale tiers.
- Emulsion Polymerization:Aqueous-phase heat removal enables higher throughput with lower capital intensity than bulk or solution alternatives. Gulf Coast integrated producers leverage captive monomer supply for margin advantage.
- Solution Polymerization:Retains niche positioning in specialty coatings requiring precise molecular weight control and narrow polydispersity.
- Bulk Polymerization:Limited adoption due to high viscosity handling challenges and solvent removal requirements that conflict with VOC regulations.
- Suspension Polymerization:Produces larger particle diameter dispersions for specific adhesive and modifier applications with distinct rheological profiles.
Emulsion technology dominates installed capacity; solution polymerization retains specialty margins in specification-driven niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialty surfactants and acrylic monomers shapes regional supply security across domestic emulsion manufacturing corridors. Export competitiveness hinges on Gulf Coast petrochemical integration and compliance with divergent state-level VOC standards.
Gulf Coast Corridor
Texas and Louisiana host integrated acrylic and vinyl acetate monomer production that feeds regional emulsion manufacturing. EPA Region 6 enforcement of 40 CFR Part 59 standards drives reformulation activity among Houston-area coatings formulators. The Texas-Louisiana petrochemical corridor concentrates backward-integrated producers with captive feedstock supply.
California
CARB SCM-2015 standards create the nation's most stringent VOC compliance environment for architectural coatings. Los Angeles and San Francisco metropolitan markets demand specification-compliant waterborne systems for commercial and residential construction. California's regulatory diffusion pattern influences Oregon and Washington state adoption timelines.
Southeast Manufacturing Belt
North Carolina's textile corridor consumes emulsion binders for nonwoven and fabric finishing applications. Georgia and Florida construction cycles drive architectural coatings demand through Atlanta and Miami metropolitan markets. State-level adoption of OTC model rules compresses supplier qualification windows across the region.
Midwest Industrial Cluster
Wisconsin and Michigan pulp-and-paper operations concentrate saturating and coating grade emulsion demand. Ohio and Illinois automotive manufacturing corridors require chip-resistant emulsion systems for OEM and refinish applications. Cold-climate logistics constraints limit waterborne system penetration in northern tier winter application windows.
Northeast Corridor
New York and Boston metropolitan construction markets specify low-VOC architectural coatings for commercial facade and infrastructure projects. Pennsylvania and New Jersey industrial maintenance segments face OSHA styrene exposure limit compliance deadlines. Regional distribution networks consolidate procurement leverage for national account paint contractors.
United States Polymer Emulsion Market Competitive Landscape
Concentration sits with integrated petrochemical majors and specialty emulsion formulators operating across tiered specification tiers. The competitive structure fragments between Gulf Coast backward-integrated producers and regional custom formulators serving niche application segments. Strategic archetypes include captive monomer suppliers, specialty blend developers, and toll manufacturing operators. Capacity expansion along the Texas-Louisiana corridor and qualification-driven portfolio diversification dominate competitive moves.
Among integrated chemical producers, BASF SE and Celanese Corporation exemplify archetypes with captive monomer positions. Trinseo occupies a position within specialty styrene-acrylic blend development. These entities anchor competitive positioning through feedstock security and specification compliance capabilities rather than commodity volume scale.
| Leading Market Players |
|---|
| OMNOVA Solutions |
| Trinseo |
| Mallard Creek Polymers Inc. |
| Specialty Polymers Inc. |
| STI Polymer |
| Engineered Polymer Solutions |
| Celanese Corporation |
| The Dow Chemical Company |
| BASF SE |
| Others |
Value Network & Pricing Analysis
EPA's National Volatile Organic Compound Emission Standards for Consumer and Commercial Products gates both supplier qualification and price differentiation simultaneously, compressing specification-compliant emulsions into premium tiers while legacy solvent-based alternatives face procurement exclusion.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure. Price differentiation stems from CARB SCM-2015 certification tier and volume scale commitments. Pricing pressure intensifies from acrylic monomer cost volatility tied to Gulf Coast refinery operating rates. National account paint contractors exhibit lowest price sensitivity due to specification lock-in, while small regional formulators face acute margin compression.
Supply Chain Analysis
Strategic stockpiling of acrylic monomer and specialty surfactants dominates inventory strategy over just-in-time approaches. Supply concentrates in the United States, Germany, and Japan for alkyl phenol ethoxylate surfactants. Production draws from propylene oxide, acrylic acid, and vinyl acetate monomer feedstocks. Single-source vulnerability in reactive surfactant production creates qualification bottlenecks. Distribution runs through manufacturer-direct portals and integrated supply platforms serving national account contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States polymer emulsion market is experiencing high-growth disruption as EPA VOC mandates and hybrid acrylic-polyurethane technology convergence compress reformulation timelines and fragment competitive tiers.
For Market Incumbents: Fortify captive monomer positions through Gulf Coast capacity expansion and pre-qualify low-styrene portfolios ahead of OSHA exposure limit deadlines. BASF SE and Celanese Corporation demonstrate archetype positioning through backward integration into acrylic and VAE monomer production. Channel control through direct-to-contractor digital platforms defends against distribution disintermediation.
For New Entrants and Emerging Players: Lead with bio-based acrylic feedstock certification under USDA BioPreferred program to capture IRA clean manufacturing tax credit advantages. Underpenetrated specialty emulsion production in Texas and Louisiana offers white-space entry. Pressure-sensitive adhesive migration from solvent systems in medical and electronics bonding presents the most penetrable application segment.
For Investors and Strategic Acquirers: Interstate diffusion of California's SCM-2015 standards reshapes the acquisition landscape toward reformulation-ready suppliers with pre-qualified low-VOC portfolios. Five-to-ten year viability favors backward-integrated producers over toll manufacturing operators. Target acquisition archetypes include Gulf Coast emulsion manufacturers with captive monomer supply and specialty blend developers serving DOT procurement channels. The signal to monitor is state-level adoption of OTC model rules accelerating qualification window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Gulf Coast captive acrylic supply secures margin stability against propylene oxide volatility. |
| Low-VOC Certification Investment | CARB SCM-2015 pre-qualification opens federal and state DOT procurement channels. |
| Direct-to-Contractor Digital Platform | Texas and Florida metropolitan markets show channel compression toward manufacturer-direct sourcing. |
| Bio-Based Feedstock Transition | USDA BioPreferred certification unlocks IRA tax credits and retailer sustainability scorecard compliance. |
| Specialty Surfactant Supplier Qualification | Reactive surfactant dual-sourcing mitigates food-contact and medical-grade emulsion bottlenecks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, ACC industry reports, SEC 10-K disclosures, and customs trade data. Primary interviews engaged coatings formulators, procurement leads at national account paint contractors, plant managers at Gulf Coast petrochemical facilities, and technical R&D directors at emulsion manufacturers. Bottom-up volume triangulation against top-down value estimation validates segment-level outputs.
Segmentation dimensions modeled include chemistry type, application category, end-use industry, and technology platform across the projection horizon. CAGRs derive from regression analysis of historical volume trends against regulatory compliance timelines and construction cycle indicators. Feedstock cost curves and monomer capacity expansion schedules inform margin trajectory assumptions.
Forecasts assume regulatory continuity in EPA 40 CFR Part 59 and CARB SCM-2015 regimes; material policy shifts would require re-modeling. Acrylic monomer supply disruption from Gulf Coast hurricane patterns or OSHA styrene exposure limit acceleration represent primary revision triggers. Revision becomes warranted when state-level OTC model rule adoption crosses thresholds affecting national product line qualification burdens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Polysorbate Market